
 Aircraft Curtains Market | 2026-2036
Aircraft Curtains Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Curtains Market Outlook
Certified textile engineering talent is rotating away from general industrial fabrics toward aerospace-grade cabin materials, tightening the labor pool for flame-retardant curtain development. Safran leverages its integrated cabin systems portfolio to bundle curtain solutions with broader interior retrofit packages. Collins Aerospace sustains technology leadership through advanced materials R&D for lightweight, compliant divider systems. Lantal Textiles anchors European supply with deep specialization in woven fabrics meeting stringent aviation burn-test requirements.
Aircraft curtains are textile divider assemblies engineered to FAA and EASA flammability standards, typically constructed from inherently fire-resistant polyester or nylon blends with specified char lengths and smoke-density ratings, serving to partition cabin zones, control light ingress, and manage thermal loads. Blinds and thermal insulation products command the largest volume share as airlines prioritize energy-efficient cabin management and passenger comfort controls. Sheer fabrics represent the fastest-growing material category as carriers adopt layered transparency designs for premium cabin aesthetics. Deployment across commercial aircraft dominates absolute demand, while private jets and business aviation segments concentrate higher-margin custom fabrication.
FAA Part 25.853 flammability requirements and EASA CS-25 certification standards govern material selection and testing protocols, directly shaping supplier qualification timelines and product development costs. The EU Green Deal sustainability frameworks and emerging FAA circulars on cabin interior environmental impact are pressuring manufacturers toward recycled-content fibers and reduced-VOC finishing processes. Stakeholders must monitor regulatory harmonization between FAA and EASA on next-generation fire-testing methodologies to anticipate compliance-driven specification shifts.
Market Dynamics
Retrofit mandates from aviation regulators are compressing supplier lead times while certified textile engineering capacity concentrates in fewer hands, forcing airlines to lock multi-year curtain supply agreements ahead of cabin refurbishment cycles.
Growth Catalysts
- FAA Part 25.853 flammability mandates:Airlines accelerate curtain replacement schedules to meet evolving burn-test requirements, generating recurring demand for compliant textile assemblies.
- Narrowbody fleet densification:Low-cost carriers expand galley and lavatory partition installations to maximize seat counts on reconfigured single-aisle aircraft.
- Sheer fabric layering:Premium cabin designers adopt transparent woven materials for aesthetic differentiation, opening specification slots beyond traditional opaque dividers.
Market Restraints
- Aramid fiber cost volatility:Inherently fire-resistant yarn inputs fluctuate with aerospace composite demand, squeezing margin predictability for weavers.
- European supplier concentration:Specialized aviation textile mills cluster in Switzerland and Germany, creating geographic vulnerability to regional logistics disruptions.
- Legacy polyester substitution limits:Surface-treated fabrics face displacement by inherently flame-retardant polymers, stranding existing dye-house investments.
Strategic Opportunities
- India MRO expansion:IndiGo and Air India maintenance bases create captive demand for localized curtain fabrication and rapid-turn refurbishment services.
- EU Green Deal recycled-content mandates:First-mover suppliers developing post-consumer nylon recovery processes capture preferential airline procurement scoring.
- Digital textile printing convergence:On-demand pattern customization for corporate jet liveries and airline branding programs commands triple standard pricing multiples.
Industry Challenges
- Certified weaving technician scarcity:FAA-approved fabric testing and documentation skills migrate toward composite aerostructures, extending hiring timelines for curtain specialists.
- Dual-certification timeline compression:Simultaneous FAA and EASA qualification paths for new material formulations demand parallel laboratory investments, stretching R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Curtains Market |
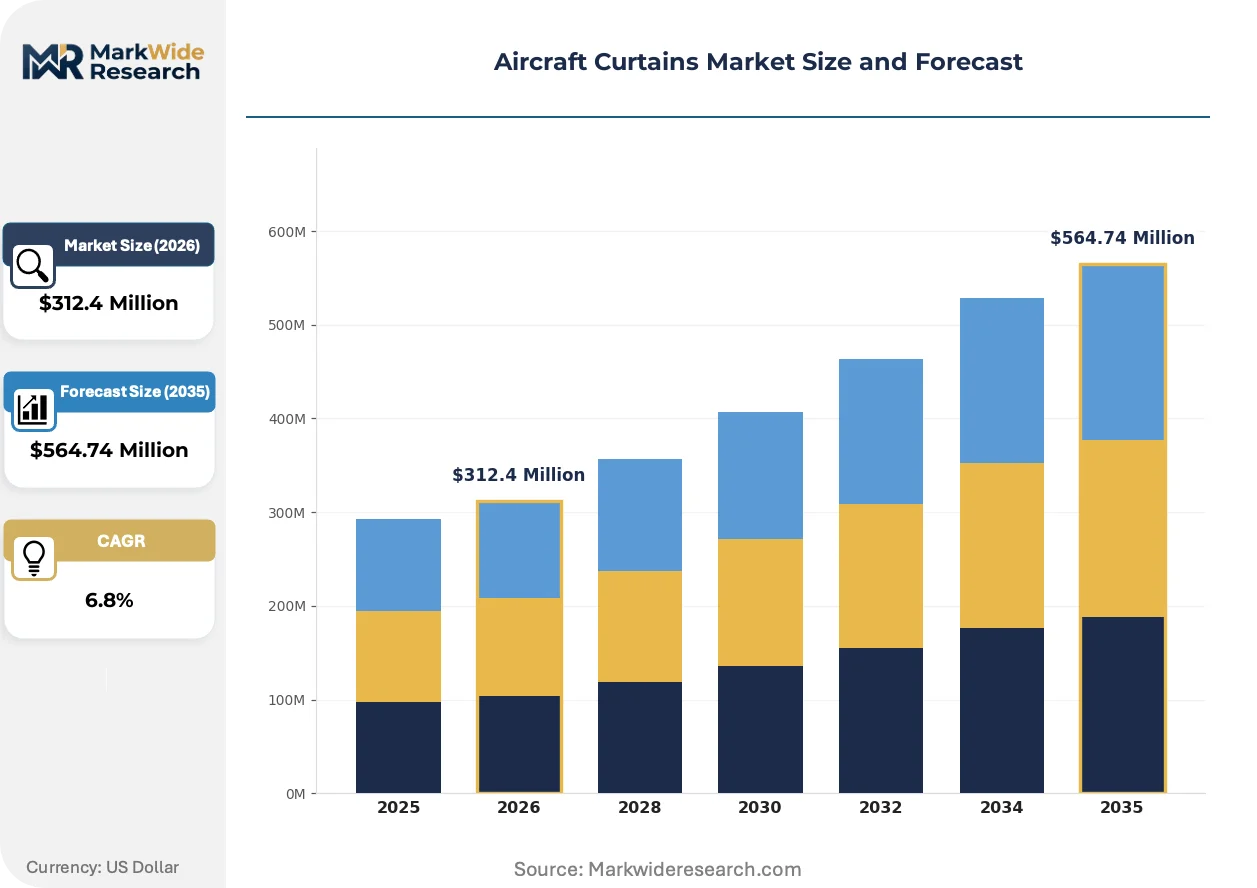
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blinds, Drapes, Sheer Fabrics, Thermal Insulation Material: Polyester, Vinyl, Nylon, Cotton Deployment: Commercial Aircraft, Private Jets, Business Aviation, Military Aircraft End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Retrofit Suppliers |
| Companies Covered | Safran, Collins Aerospace, Zodiac Aerospace, Lantal Textiles, Spectra Interior Products, Diehl Aviation, Aircraft Cabin Modification GmbH, Botany Weaving, NIEMLA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Curtains Market Strategic Shifts
Woven architecture is fragmenting as airlines demand lighter, smarter cabin dividers that integrate sensing and environmental control functions previously handled by separate hardware.
Inherently flame-retardant polymer yarns are decomposing the traditional surface-treatment supply chain. Weavers at Lantal Textiles and specialized European mills now extrude fire-resistant filaments directly, eliminating post-weave chemical finishing. Major carriers in the United States and Gulf states specify these materials for new deliveries, compressing the addressable market for dye-house operators dependent on topical flame-retardant application.
EU Green Deal sustainability frameworks are forcing virgin-fiber displacement across cabin interiors. EASA certification staff now evaluate recycled-content curtain submissions under expedited environmental-impact protocols, rewarding suppliers with documented circular supply chains. French and German flag carriers lead specification shifts, embedding recycled-nylon content minimums into retrofit tender documents.
Airline technical procurement teams now unbundle curtain supply from full-cabin interior packages, issuing standalone textile tenders to specialized weavers rather than accepting bundled solutions from systems integrators. This fragmentation favors direct mill relationships and compresses distributor margins. Low-cost carriers in Southeast Asia and Latin America pioneer this model, using digital sourcing platforms to compare certified suppliers across multiple continents.
Aircraft Curtains Market Segmentation
Aircraft curtain procurement channels fragment sharply between OEM line-fit programs, airline direct retrofit tenders, and MRO aftermarket flows. Understanding which segments concentrate through each channel exposes margin architecture and supplier qualification barriers.
Product Type:
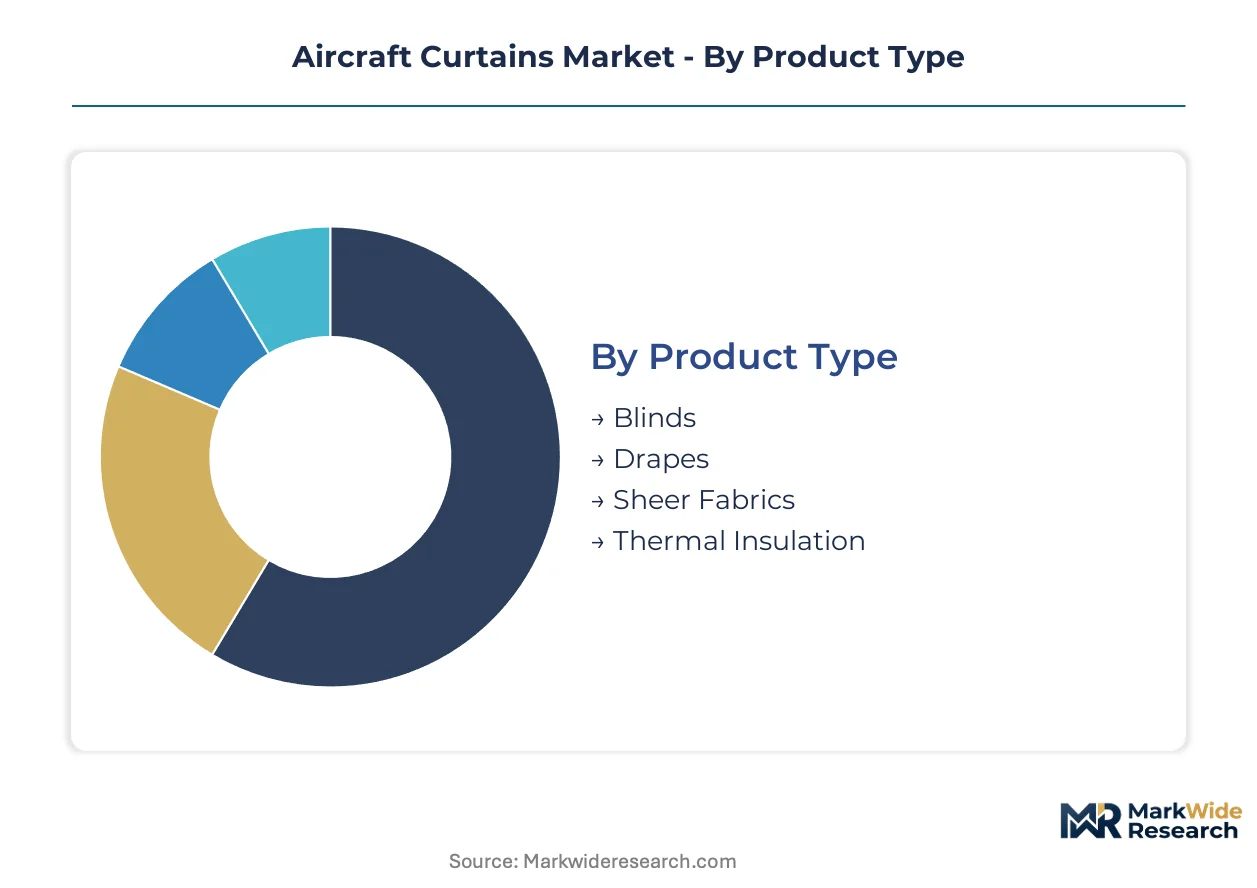
Blinds and thermal insulation products flow predominantly through OEM cabin systems integrators, while sheer fabrics and drapes increasingly bypass bundled packages via airline direct sourcing platforms.
- Blinds:Roller and pleated assemblies constructed from fire-rated polyester laminates with integrated light-blocking layers. Demand clusters in United States narrowbody retrofit programs where FAA Part 25.853 compliance deadlines compress replacement cycles.
- Thermal Insulation:Multi-layer textile barriers engineered to manage cabin thermal loads and acoustic dampening. Gulf carrier widebody fleets specify these for premium cabin zones, driving specification upgrades as burn-test standards tighten.
- Drapes:Heavier woven partitions for galley and lavatory enclosures.
- Sheer Fabrics:Transparent woven materials enabling layered aesthetic designs in premium cabins.
Blinds dominate installed base. Sheer fabrics are where expansion concentrates.
Material:
Cost tier stratification separates commodity synthetics from aerospace-certified specialty polymers, with recycled-content grades commanding procurement scoring premiums under EU Green Deal frameworks.
- Polyester:Inherently flame-retardant filament grades now displace surface-treated variants, eliminating post-weave chemical finishing. Swiss and German mills extrude these directly, capturing specification shifts from major United States carriers.
- Nylon:High-tenacity aramid-blend yarns meeting stringent char-length requirements. Post-consumer recovery processes under development position recycled nylon for preferential airline procurement scoring.
- Vinyl:Coated substrates for heavy-duty wipe-clean applications in high-traffic zones.
- Cotton:Natural fiber limited to non-structural decorative applications with topical flame-retardant treatment.
Polyester anchors volume shipments. Nylon is climbing the fastest on sustainability-linked tenders.
Deployment:
Application context determines certification burden and margin structure, with commercial aviation demanding dual FAA-EASA qualification while private aviation tolerates single-jurisdiction approval.
- Commercial Aircraft:Narrowbody and widebody fleets requiring full burn-test documentation and traceable lot certification. United States low-cost carriers densify galley partitions to maximize seat counts, generating recurring retrofit demand.
- Private Jets:Custom fabrication for corporate and VIP configurations with shorter lead times and triple-standard pricing multiples for bespoke patterns.
- Business Aviation:Mid-size cabin platforms balancing certification rigor with customization flexibility.
- Military Aircraft:Specialized tactical requirements with distinct procurement channels and classified specification protocols.
Commercial aircraft dominates absolute demand. Private jets concentrate the steepest expansion trajectory on digital textile printing convergence.
End User:
Customer type fragmentation accelerates as airlines unbundle curtain supply from full-cabin interior packages, compressing distributor margins and favoring direct mill relationships.
- Airlines:Technical procurement teams issuing standalone textile tenders via digital sourcing platforms, particularly low-cost carriers in Southeast Asia and Latin America pioneering disintermediation.
- Aircraft Manufacturers:Boeing and Airbus line-fit programs with multi-year supply agreements locked ahead of delivery ramps.
- Maintenance Providers:India MRO expansion at IndiGo and Air India bases creates captive demand for localized fabrication and rapid-turn refurbishment.
- Retrofit Suppliers:Specialized cabin refurbishment contractors managing compressed lead times from regulatory mandate deadlines.
Airlines dominate procurement volume. Maintenance providers are gaining share fastest on geographic supply chain reconfiguration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25.853 mandates in the United States compress replacement cycles and concentrate specification authority with domestic carriers and their designated suppliers. Regulatory divergence between Washington and Brussels forces dual-track qualification investments, while emerging aviation economies in South Asia and the Gulf states reconfigure procurement geography.
United States
Low-cost carriers densify narrowbody galley partitions to maximize seat counts, generating recurring retrofit demand from legacy fleets. FAA burn-test deadlines accelerate curtain replacement schedules ahead of compliance windows. Wichita and Seattle aerospace clusters anchor OEM line-fit programs with multi-year supply agreements locked to delivery ramps.
Germany
Specialized aviation textile mills in Baden-Württemberg and Bavaria extrude inherently flame-retardant polymer yarns, eliminating post-weave chemical finishing. EASA CS-25 certification protocols govern material selection and supplier qualification timelines. Hamburg and Munich maintenance bases drive aftermarket flows for Lufthansa Group and third-party operators.
France
Flag carriers embed recycled-nylon content minimums into retrofit tender documents under EU Green Deal sustainability frameworks. ANSM and DGAC coordinate with EASA on expedited environmental-impact evaluation protocols. Toulouse aerospace cluster integrates curtain supply into broader cabin systems packages for Airbus line-fit programs.
India
IndiGo and Air India maintenance bases at Delhi and Mumbai create captive demand for localized fabrication and rapid-turn refurbishment services. BIS standards align with FAA and EASA flammability requirements for imported textile assemblies. Karnataka and Maharashtra industrial corridors attract Tier-2 weavers serving MRO aftermarket channels.
United Arab Emirates
Gulf carrier widebody fleets specify thermal insulation upgrades for premium cabin zones as burn-test standards tighten. MOHAP and GCAA coordinate cabin interior safety protocols with EASA reference standards. Dubai and Abu Dhabi aviation clusters concentrate specification authority for retrofit programs across Middle Eastern and African operator networks.
Aircraft Curtains Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with aerospace-grade textile engineering capacity concentrating in Swiss and German mills. The upper tier bundles curtain solutions with full cabin interior retrofits, while mid-scale weavers compete on direct airline procurement platforms. Three archetypes dominate: systems integrators with bundled portfolios, specialized textile mills with deep certification expertise, and regional fabricators serving MRO aftermarket channels. Competitive moves center on backward integration into polymer extrusion and geographic expansion toward India MRO hubs.
Among European specialists, Lantal Textiles exemplifies the certified weaving mill archetype with deep specialization in aviation burn-test compliance. Safran and Collins Aerospace occupy positions within the integrated systems tier, leveraging broader cabin interior portfolios to anchor specification influence with major carriers. These three names represent the structural concentration of engineering talent and regulatory qualification capacity that defines competitive positioning.
| Leading Market Players |
|---|
| Safran |
| Collins Aerospace |
| Zodiac Aerospace |
| Lantal Textiles |
| Spectra Interior Products |
| Diehl Aviation |
| Aircraft Cabin Modification GmbH |
| Botany Weaving |
| NIEMLA |
| Others |
Value Chain & Pricing Dynamics
Multi-year capacity reservation agreements with Swiss and German weaving mills lock in both FAA-certified aramid fiber supply and forward price visibility for United States carriers facing compressed retrofit deadlines. These contracts insulate airlines from aramid cost volatility while tethering margin predictability to European textile engineering capacity.
Pricing Analysis
Price spreads between European-certified mills and Asian fabricators narrow as FAA Part 25.853 documentation requirements intensify. Pricing stratifies across OEM line-fit, airline direct procurement, and MRO aftermarket channels, with certification grade and burn-test traceability as primary differentiation drivers. Cost compression in surface-treated polyester tiers is intensifying because inherently flame-retardant polymers displace legacy finishing processes. Low-cost carriers in Southeast Asia exhibit highest price sensitivity; Gulf state flag carriers and private jet operators show lowest.
Supply Chain Analysis
Swiss and German textile engineering clusters control certified weaving capacity for aerospace-grade flame-retardant yarns, creating single-source vulnerability for airlines requiring EASA CS-25 documentation. Raw material flows draw from aramid fiber producers, virgin and recycled nylon compounders, and specialized dye-chemical formulators. Tariff exposure on European textile imports into India and the United States threatens margin architecture for regional MRO fabricators. Distribution runs through OEM cabin systems integrators, direct airline technical procurement platforms, and India-based maintenance provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern this market as digital sourcing platforms disintermediate traditional distributor layers, enabling direct mill-to-airline contracting that rewards interoperability with airline ERP and compliance documentation systems.
For Market Incumbents: Fortify backward integration into inherently flame-retardant polymer extrusion to defend against European mill concentration risk and capture margin from surface-treatment displacement. Lock multi-year capacity reservation agreements with IndiGo and Air India MRO bases before localized competitors achieve BIS-FAA dual certification. Prioritize EASA expedited environmental-impact protocol pre-qualification to capture EU Green Deal recycled-content tenders from French and German flag carriers. For New Entrants and Emerging Players: Lead with recycled-nylon recovery process development to exploit sustainability-linked procurement scoring gaps among first-mover suppliers. Target India MRO aftermarket channels where rapid-turn refurbishment demand outpaces certified weaving technician supply. Pursue digital textile printing capabilities for private jet bespoke pattern contracts commanding premium pricing multiples. For Investors and Strategic Acquirers: Certified weaving mills with established FAA-EASA dual qualification and documented circular supply chains represent the highest-conviction acquisition archetype in this market. Long-term viability hinges on regulatory harmonization durability and virgin-fiber displacement velocity across cabin interiors. Monitor EASA recycled-content certification submission volumes as inflection indicator for circular supply chain maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Extrusion | Eliminates post-weave chemical finishing costs and captures margin from surface-treatment displacement by inherently flame-retardant yarns. |
| Recycled-Nylon Recovery Process Development | Positions suppliers for preferential procurement scoring under EU Green Deal frameworks and EASA expedited environmental protocols. |
| Digital Textile Printing Capability Investment | Enables on-demand pattern customization for private jet and corporate aviation segments commanding triple-standard pricing multiples. |
| India MRO Geographic Expansion | Captures localized fabrication demand from IndiGo and Air India maintenance bases while reducing logistics vulnerability to European supplier concentration. |
| Dual FAA-EASA Certification Pre-Investment | Accelerates qualification timelines for new material formulations and defends specification access as regulatory harmonization pressures intensify. |
Study Parameters
Cross-validation between primary interviews with airline technical procurement officers, MRO maintenance directors, and certified textile engineering specialists and secondary validation through FAA Part 25.853 certification databases, EASA CS-25 submission records, and EU Green Deal framework documentation anchors the qualitative findings. Customs and trade flow data from United States, German, and Indian export-import authorities complement SEC filings from listed cabin interior systems integrators. Bottom-up segment sizing triangulates against top-down fleet projection models across narrowbody, widebody, and business aviation platforms.
Sensitivity analysis around aramid fiber cost volatility, recycled-content adoption velocity, and India MRO capacity buildout rates tests forecast robustness across the projection horizon. The analytical framework segments by product type, material grade, deployment platform, and end-user procurement channel, with CAGRs derived from regression against fleet delivery schedules and regulatory mandate compliance windows. Burn-test standard evolution timelines and EASA-FAA harmonization progress serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of flammability mandates, continued airline retrofit program prioritization, and stable aerospace-grade textile engineering labor availability would require recalibration. Forecasts reflect documented assumptions about certification timeline compression and virgin-fiber displacement economics. Practitioners should keep alternative scenarios live as EASA recycled-content protocol adoption rates and India MRO localization policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market