
 Commercial Aircraft Cabin Interior Market | 2026-2036
Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Cabin Interior Market Analysis
Aerospace composites engineering talent is reorganizing supply chain geography as tier-one suppliers race to secure laminate certification expertise for next-generation cabin modules. Collins Aerospace leverages in-house thermoplastic processing to sustain vertical integration across seating structures and lighting systems. Safran anchors European manufacturing scale through its dedicated aircraft interiors division, while Recaro Aircraft Seating competes on ergonomic specialization in premium economy configurations.
Commercial aircraft cabin interior encompasses the integrated assemblies, surface finishes, and functional systems installed within the pressurized fuselage to provide passenger accommodation, safety compliance, and in-flight service enablement, typically specified to meet 16g crashworthiness and 90-second evacuation criteria through fire-resistant material selection and structural load-path engineering. The primary purpose is to maximize revenue-generating floor space while minimizing operational weight penalty per passenger seat-mile. Seating commands the largest value share as airlines prioritize densification-compatible slimline designs with integrated power and connectivity. Composite materials are displacing aluminum in structural monuments and sidewall panels where specific strength targets drive gram-per-seat reductions. Retrofit installation channels are expanding faster than linefit as post-pandemic fleet reconfiguration cycles accelerate cabin refresh timelines.
FAA Part 25 flammability standards and EASA CS-25 certification requirements govern material qualification timelines, forcing suppliers to front-load testing expenditure before production commitments. EU REACH chemical restrictions and impending CSRD sustainability disclosure obligations are reshaping material selection criteria toward recycled content and end-of-life recyclability. Stakeholders must monitor how emerging airworthiness directives for electrical systems integration affect in-seat power and connectivity retrofit economics across aging narrow-body fleets.
Market Dynamics
Fleet renewal cycles among low-cost carriers are compressing supplier lead times as airlines demand faster cabin reconfiguration turnaround. Thermoplastic qualification timelines now determine competitive positioning more than manufacturing scale.
Growth Catalysts
- Flammability-resistant thermoplastics:EASA certification acceleration for these materials enables faster supplier onboarding and reduces qualification cycle burden for narrow-body retrofits.
- China:COMAC C919 production ramp and domestic airline fleet expansion create concentrated demand for modular overhead bin systems and lightweight seating platforms.
- Retrofit channel expansion:Post-pandemic cabin refresh programs accelerate as airlines prioritize densification-compatible slimline designs with integrated connectivity.
Market Restraints
- Pre-production testing expenditure:FAA Part 25 and EASA CS-25 flammability standards force suppliers to front-load capital before securing production commitments.
- Specialized laminate certification expertise:Concentration of qualified aerospace composites engineers in specific manufacturing clusters limits supplier geographic flexibility.
- Aluminum substitution ceiling:Structural monuments in wide-body configurations retain metal load-bearing elements where thermoplastic specific strength targets remain unproven.
Strategic Opportunities
- End-of-life recyclability mandates:EU REACH chemical restrictions and impending CSRD sustainability disclosure obligations reward suppliers with closed-loop material recovery systems.
- Electrical systems integration:Emerging airworthiness directives for in-seat power and connectivity retrofit economics create aftermarket service bundling potential across aging narrow-body fleets.
- Ergonomic specialization:Premium economy configuration growth rewards seating suppliers with differentiated anthropometric databases and adjustable lumbar support platforms.
Industry Challenges
- 16g crashworthiness certification:Structural load-path engineering for 90-second evacuation compliance requires specialized dynamic testing facilities with limited global capacity.
- Supply chain reconfiguration:Tier-one supplier consolidation of thermoplastic processing capabilities disrupts established subcontractor relationships for sidewall panel fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Cabin Interior Market |
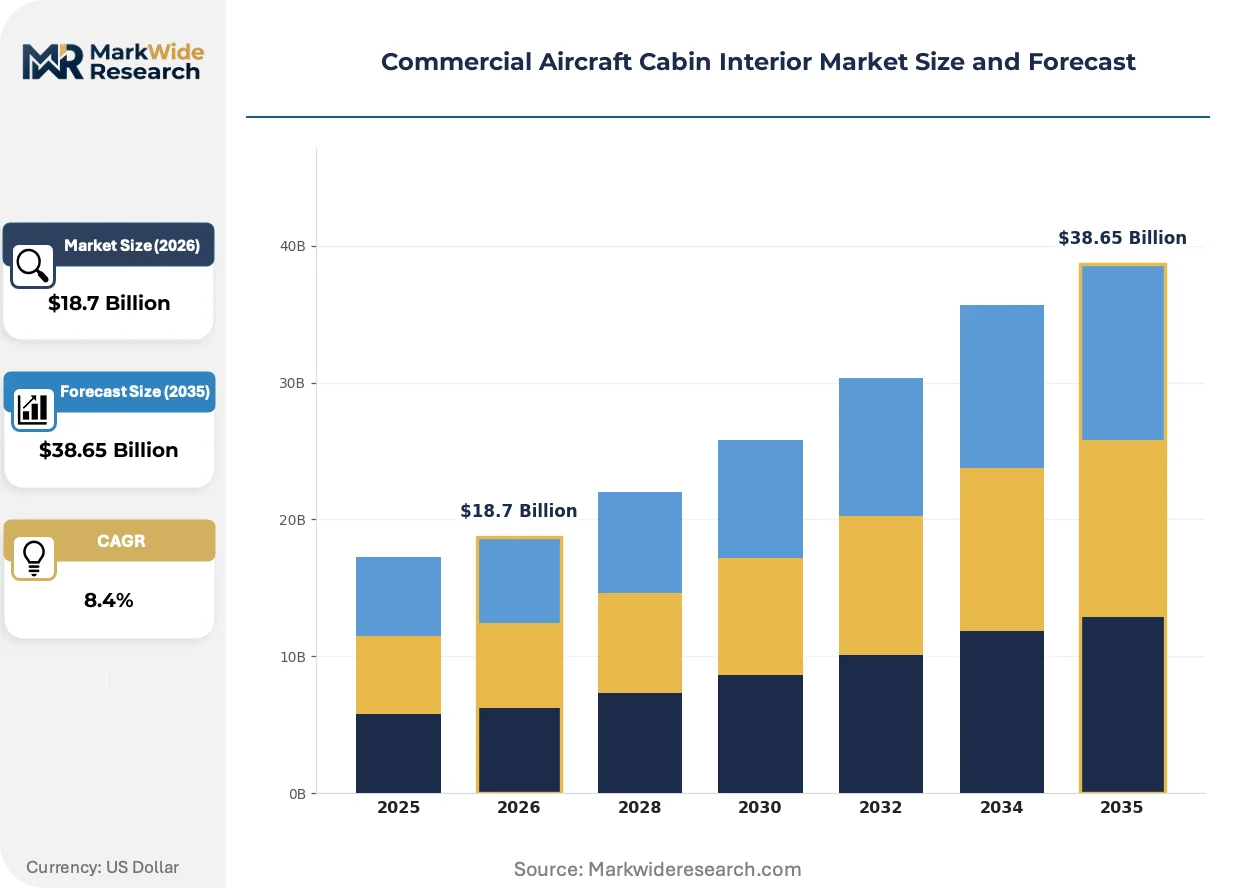
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Overhead Storage, Cabin Lighting, Window Shades Material: Aluminum, Composite, Fabric, Thermoplastic End User: Airlines, OEMs, MRO Providers, Lessors Installation Type: Retrofit, Linefit, Modular, Custom |
| Companies Covered | JAMCO Corporation, Diehl Aviation, Collins Aerospace, Astronics Corporation, Honeywell International Inc., Safran, Recaro Aircraft Seating, Acro Aircraft Seating Ltd., Panasonic Avionics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Cabin Interior Market Emerging Trajectories
Material science breakthroughs and regulatory compression timelines are restructuring how cabin systems achieve airworthiness certification. Supplier competitive advantage increasingly derives from in-house testing velocity rather than component manufacturing scale.
Thermoplastic composites are decomposing traditional aluminum-intensive supply chains for structural monuments and sidewall panels. Low-cost carriers adopting narrow-body fleet renewal programs specify these materials for gram-per-seat reduction targets. The technology is decomposing established tier-two supplier roles as tier-one integrators bring laminate processing captive.
EU CSRD sustainability disclosure obligations are mandating recycled content traceability for cabin interior materials. Suppliers must now document end-of-life recyclability pathways before EASA certification approval. European narrow-body operators face compressed material selection timelines as REACH chemical restrictions converge with carbon accounting requirements.
Airline procurement teams are consolidating vendor relationships around full-cabin integrators capable of simultaneous seating, lighting, and monument delivery. Fragmented component suppliers lose access to linefit channels without modular system packaging capabilities. This concentration is most visible in China where domestic carriers prioritize single-source accountability for COMAC C919 cabin outfitting.
Commercial Aircraft Cabin Interior Market Segmentation
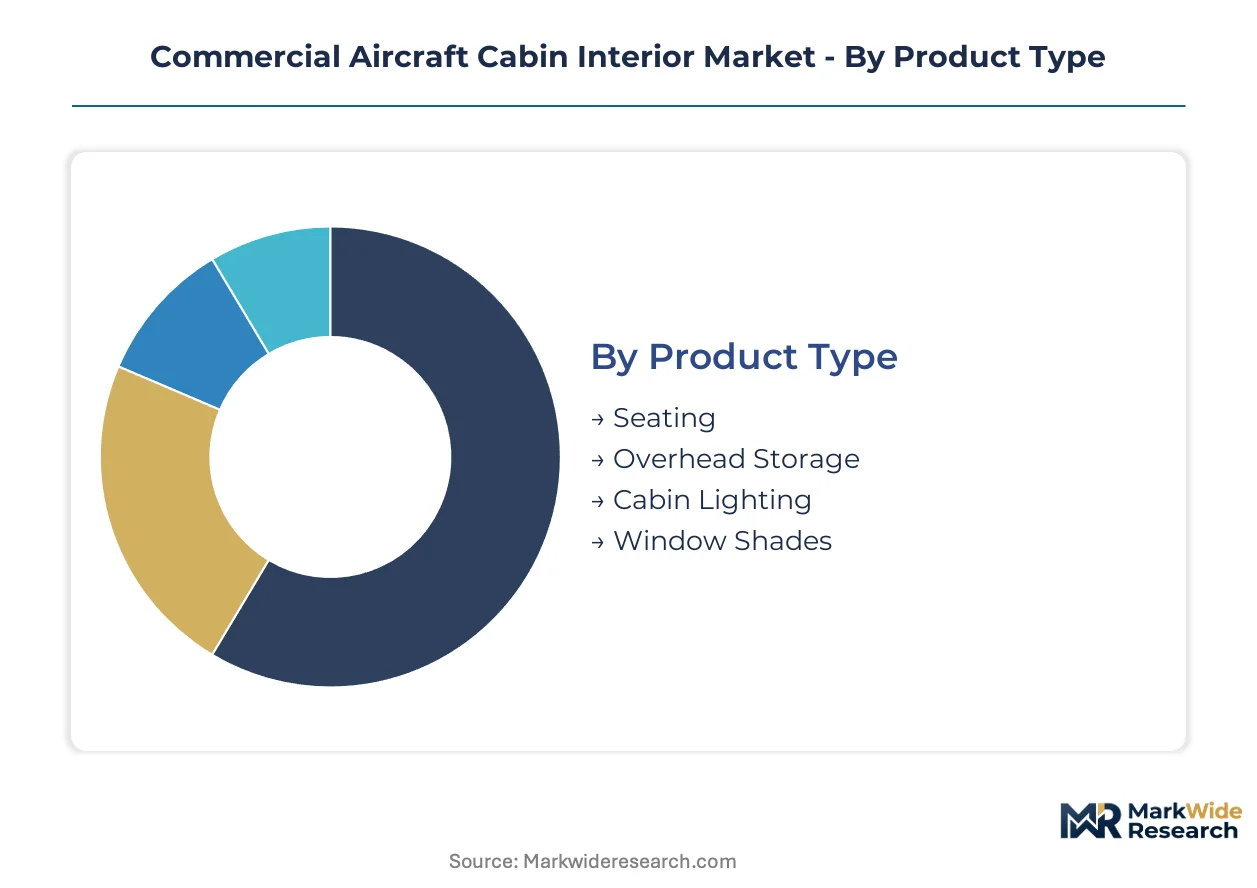
Cabin interior procurement channels diverge sharply between linefit OEM contracts and aftermarket retrofit programs. Each segment category carries distinct qualification burdens, pricing mechanisms, and supplier relationship structures that determine competitive positioning.
Product Type:
Linefit channels concentrate on integrated system packages while retrofit demand fragments across component-level procurement. Airlines bundle seating and lighting through tier-one integrators for new deliveries, whereas MRO providers source monuments and window treatments separately for cabin refresh cycles.
- Seating:Slimline configurations with integrated power and connectivity dominate narrow-body densification programs. Demand concentrates among low-cost carriers in China and Southeast Asia pursuing maximum seat counts within FAA Part 25 evacuation envelopes. Thermoplastic shell structures displace aluminum where gram-per-seat reductions justify qualification investment.
- Overhead Storage:Modular bin systems with pivot-down access mechanisms enable faster turnaround times. COMAC C919 linefit programs and Airbus A320neo family retrofits in China drive specification volume for pivot-bin configurations with integrated PSU routing.
- Cabin Lighting:LED mood systems with circadian rhythm programming reduce power draw versus fluorescent legacy installations.
- Window Shades:Electrochromic dimmable layers replace mechanical blinds in premium configurations where passenger experience differentiation commands price premiums.
Seating dominates installed base. Overhead storage is where expansion concentrates.
Material:
Cost tiers separate qualification-intensive thermoplastics from commodity aluminum in structural applications. Premium channel economics reward composite investments where lifecycle weight savings exceed upfront certification expenditure.
- Thermoplastic:Flammability-resistant formulations with 35% glass fiber content achieve specific strength targets for structural monuments. EASA certification acceleration in Europe compresses supplier onboarding timelines for narrow-body retrofits. Recyclability documentation under EU CSRD mandates now precedes production approval.
- Composite:Carbon fiber reinforced polymers dominate sidewall panels and galley structures where 16g crashworthiness compliance requires tailored laminate layup sequences. Demand clusters at tier-one integrators with in-house autoclave capacity in Germany and France.
- Aluminum:Legacy alloys retain wide-body floor beam applications where thermoplastic creep resistance remains unproven at elevated temperatures.
- Fabric:Wool-nylon blends with inherent flame resistance cover seating upholstery where passenger contact frequency demands abrasion resistance.
Aluminum retains widest installed base. Thermoplastic is climbing the fastest.
End User:
Customer type determines contract structure, with OEMs demanding multi-year system integration commitments and MRO providers seeking spot availability for aging fleet support.
- Airlines:Full-service carriers specify differentiated cabin zones across premium, standard, and economy tiers. Procurement teams consolidate vendor relationships around integrators capable of simultaneous seating, lighting, and monument delivery for linefit programs.
- OEMs:Boeing and Airbus cabin engineering groups prescribe qualified supplier lists with locked pricing for multi-year production blocks. COMAC's C919 ramp concentrates demand among domestic Chinese integrators with SAMR certification.
- MRO Providers:Third-party maintenance shops source retrofit components through distribution channels with compressed lead time requirements.
- Lessors:Aircraft leasing companies specify generic cabin configurations maximizing residual value across multiple operator transitions.
Airlines command specification authority. MRO providers represent the steepest expansion trajectory.
Installation Type:
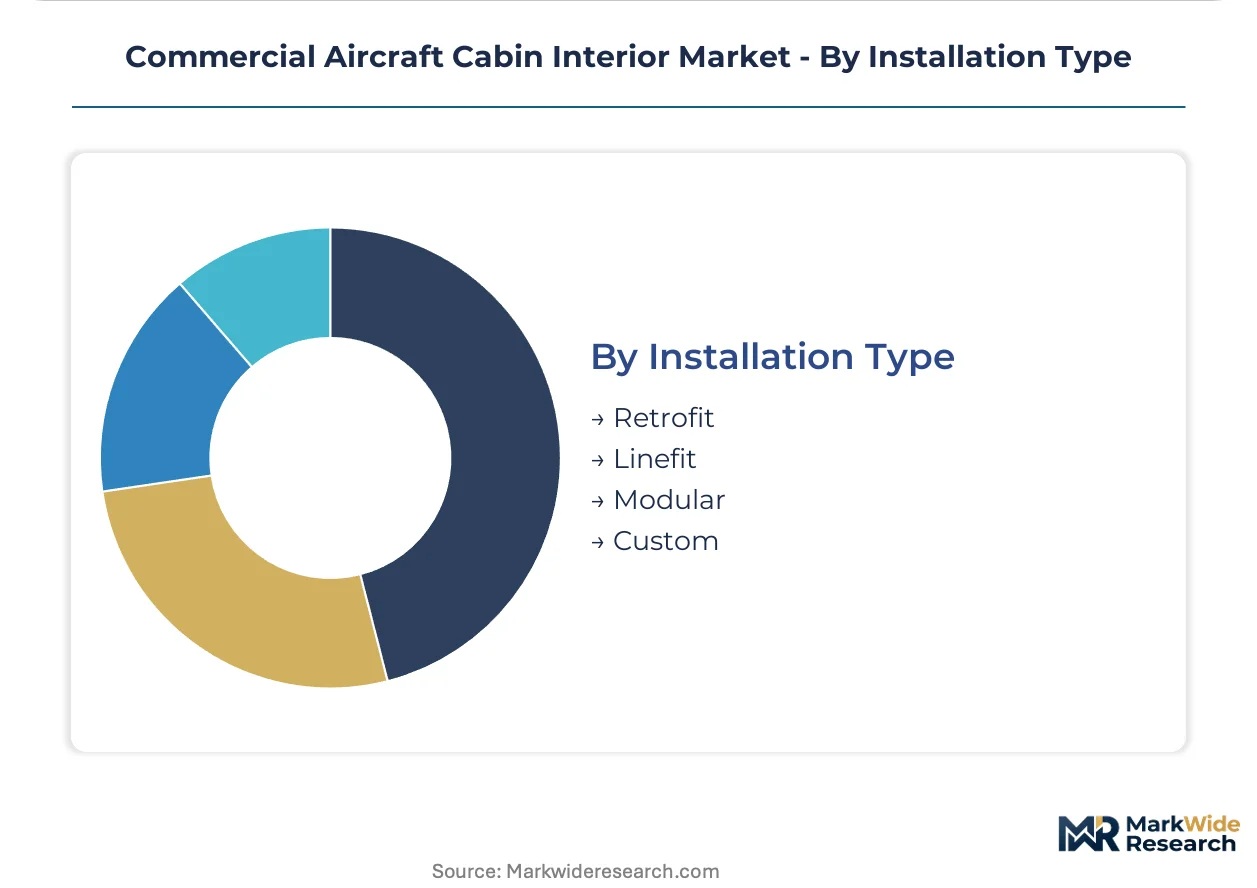
Volume distribution tilts toward retrofit as post-pandemic fleet reconfiguration cycles accelerate cabin refresh timelines beyond new delivery rates.
- Retrofit:Compressed turnaround schedules demand pre-certified modular assemblies installable during overnight maintenance windows. Aging narrow-body fleets in the US and Europe drive specification volume for connectivity-integrated seat replacements.
- Linefit:OEM production integration enables full cabin system testing before delivery. Suppliers with FAA-approved quality systems capture multi-year contracts tied to airframe production rates.
- Modular:Standardized monument dimensions enable rapid reconfiguration between high-density and premium layouts.
- Custom:VIP and head-of-state configurations demand bespoke craftsmanship with extended engineering cycles.
Linefit retains revenue concentration. Retrofit is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA Part 25 certification requirements in the United States anchor the dominant regulatory geography for cabin interior qualification, with EASA CS-25 standards in Europe and SAMR oversight in China forming complementary certification pillars across the three primary demand centers.
United States
Legacy narrow-body fleet reconfiguration drives retrofit demand for connectivity-integrated seating and LED lighting upgrades. FAA airworthiness directives for electrical systems integration compress supplier qualification timelines for in-seat power retrofits. Wichita, Kansas and the Pacific Northwest host concentrated MRO provider clusters where third-party maintenance shops source modular components for overnight installation windows.
China
COMAC C919 production ramp concentrates linefit demand for modular overhead bin systems and lightweight seating platforms. SAMR certification requirements for domestic suppliers create qualification bottlenecks for foreign integrators seeking C919 cabin contracts. Shanghai and the Yangtze River Delta anchor manufacturing clusters where domestic integrators build qualification expertise for narrow-body programs.
Germany
Tier-one integrators with in-house autoclave capacity dominate carbon fiber reinforced polymer supply for sidewall panels and galley structures. EU CSRD sustainability disclosure obligations mandate recycled content traceability before EASA production approval. Hamburg and Bavaria host specialized laminate processing facilities where aerospace composites engineers concentrate for 16g crashworthiness certification.
France
Safran's dedicated aircraft interiors division anchors European manufacturing scale for seating structures and lighting systems. REACH chemical restrictions converge with carbon accounting requirements to compress material selection timelines for narrow-body operators. Toulouse and the Occitanie region concentrate cabin engineering groups with locked pricing for multi-year production blocks.
United Kingdom
Acro Aircraft Seating Ltd. exemplifies mid-cap specialists competing on ergonomic configuration for premium economy densification programs. CAA alignment with EASA flammability standards enables faster supplier onboarding for narrow-body retrofits. Southwest England hosts seating fabrication clusters where slimline design expertise concentrates for low-cost carrier procurement teams.
Commercial Aircraft Cabin Interior Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with tier-one suppliers consolidating thermoplastic processing capabilities to displace established subcontractor relationships. The structure rewards in-house testing velocity over component manufacturing scale, as EASA certification acceleration compresses competitive positioning timelines. Three archetypes dominate: full-cabin integrators with simultaneous seating-lighting-monument delivery, ergonomic specialists with differentiated anthropometric databases, and connectivity-embedded seating fabricators. Consolidation through strategic partnerships and geographic expansion into Chinese linefit channels represent the dominant competitive vectors.
Among the integrated tier, Collins Aerospace and Safran exemplify full-cabin system packaging capabilities, while Recaro Aircraft Seating occupies a position within the ergonomic specialization archetype for premium economy configurations. These three anchors represent distinct competitive vectors: North American integrators leveraging in-house thermoplastic processing, European manufacturers scaling through dedicated interiors divisions, and German seating specialists competing on anthropometric database differentiation rather than manufacturing scale.
| Leading Market Players |
|---|
| JAMCO Corporation |
| Diehl Aviation |
| Collins Aerospace |
| Astronics Corporation |
| Honeywell International Inc. |
| Safran |
| Recaro Aircraft Seating |
| Acro Aircraft Seating Ltd. |
| Panasonic Avionics Corporation |
| Others |
Supply Flow & Price Mechanics
Fourteen-month qualification cycles for EASA flammability-resistant thermoplastics concentrate pricing power among tier-one integrators with captive testing facilities, while compressing margins for component subcontractors lacking in-house certification velocity.
Pricing Analysis
China-US price spreads for narrow-body seating assemblies exceed 20 percent, reflecting divergent labor cost structures and SAMR certification overhead. Three-tier pricing structure across premium, standard, and economy levels segments by crashworthiness certification grade and integrated connectivity features. Cost compression in slimline configurations intensifies because low-cost carriers prioritize gram-per-seat reductions over upholstery durability. MRO providers exhibit highest price sensitivity due to overnight installation windows limiting supplier negotiation leverage.
Supply Chain Analysis
Germany, France, and China anchor thermoplastic laminate processing for structural monuments and sidewall panels. Raw material flows draw from Saudi Arabia for carbon fiber precursor, Belgium for epoxy resin systems, and Japan for glass fiber rovings. Single-source vulnerability concentrates in qualified aerospace composites engineers clustered around Hamburg and Toulouse. Distribution runs through tier-one integrators delivering full-cabin system packages to OEM linefit channels and modular assemblies to third-party MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of engineers holding dual FAA-EASA laminate certification credentials concentrates competitive advantage among incumbents with established testing infrastructure, while raising barriers for new entrants seeking narrow-body retrofit contracts.
For Market Incumbents: Fortify in-house thermoplastic processing capabilities to displace tier-two subcontractors for COMAC C919 linefit programs. Expand autoclave capacity in Yangtze River Delta manufacturing clusters to capture SAMR certification timelines. Defensive consolidation around 16g crashworthiness testing facilities counters emerging entrant challenges from Chinese domestic integrators. For New Entrants and Emerging Players: Lead with ergonomic specialization in premium economy configurations where anthropometric database differentiation commands price premiums over manufacturing scale. Target US and European retrofit channels for aging A320ceo and 737NG fleets requiring connectivity-integrated seat replacements. Go-to-market through MRO distribution partnerships with compressed lead-time guarantees. For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core interiors divisions lacking full-cabin integration capabilities. Long-term viability centers on suppliers controlling both laminate certification expertise and modular system packaging for linefit channels. Monitor COMAC C919 production rate announcements as inflection indicator for Chinese domestic supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Processing Captive | Collins Aerospace and Safran internalize laminate qualification to compress EASA certification cycles for narrow-body retrofits. |
| Chinese Linefit Channel Expansion | Domestic integrators with SAMR certification capture COMAC C919 seating and overhead bin specifications from foreign competitors. |
| Retrofit Service Bundling | Tier-one suppliers package connectivity-integrated seating with LED lighting upgrades for post-pandemic fleet reconfiguration programs. |
| Sustainability Certification Investment | EU CSRD compliance for recycled content traceability precedes EASA production approval for thermoplastic structural monuments. |
| Ergonomic Database Acquisition | Recaro Aircraft Seating leverages anthropometric specialization to differentiate premium economy configurations from commodity slimline competitors. |
Methodological Framework
Cross-validation between primary interviews with aircraft interiors procurement managers, MRO operations directors, and aerospace composites engineers and secondary validation through FAA airworthiness directive filings, EASA certification databases, and OEM production rate disclosures anchors the qualitative findings. Bottom-up triangulation aggregates seat-level pricing and installation volume data across linefit and retrofit channels, while top-down verification benchmarks against airframe delivery forecasts and fleet age distributions.
Sensitivity analysis tests forecast robustness across alternative scenarios for COMAC C919 production ramp rates, EASA thermoplastic certification acceleration timelines, and low-cost carrier fleet renewal cycles. Segmentation dimensions span product type, material qualification tier, end-user contract structure, and installation channel. CAGRs derive from compound growth modeling of narrow-body delivery forecasts and retrofit penetration assumptions, with specific inputs including 16g crashworthiness certification capacity constraints and REACH chemical restriction implementation schedules.
Forecasts assume regulatory continuity in FAA Part 25, EASA CS-25, and SAMR oversight regimes; material policy shifts would require re-modeling. Specific risks include airworthiness directive delays for electrical systems integration, aluminum substitution ceilings in wide-body structural applications, and concentration of qualified laminate engineers in German and French manufacturing clusters. Recalibration cycles align with material shifts in COMAC production rates, EASA certification timeline compressions, and EU CSRD disclosure obligation implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market