
 Aircraft Seating Market | 2026-2036
Aircraft Seating Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Seating Market Analysis
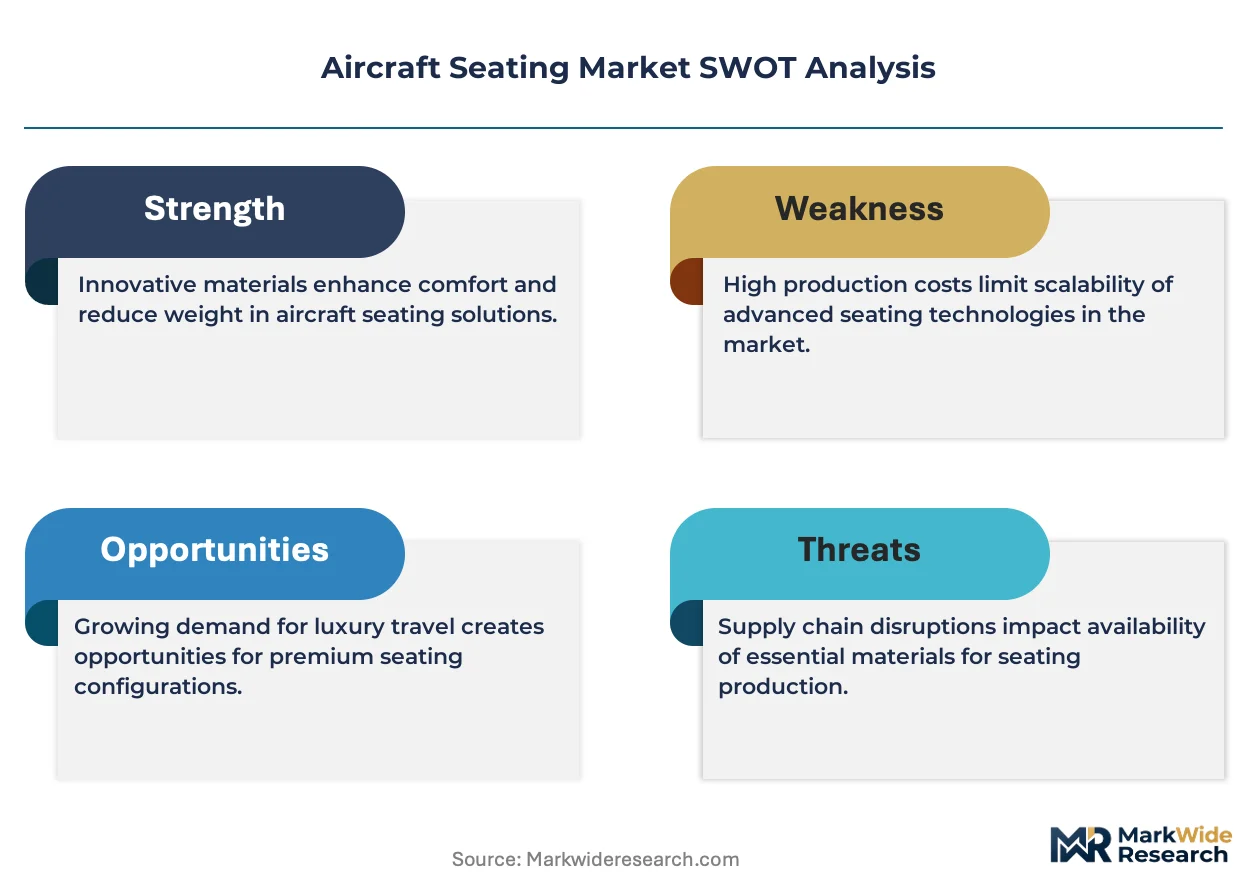
Capital-intensity divergence between full-service seat integrators and component-focused suppliers is bifurcating competitive dynamics across the sector. Safran Seats leverages vertical integration from raw materials to final assembly, sustaining margin control through captive supply of critical mechanisms. Collins Aerospace competes through its broad avionics-to-interiors portfolio, anchoring multi-billion-dollar airline relationships that extend beyond seating into full cabin ecosystems. RECARO Aircraft Seating specializes in lightweight composite engineering, dominating the premium economy and business class segments where gram-reduction translates directly into fuel savings.
Aircraft seating comprises engineered passenger accommodation systems installed in fixed-wing and rotary-wing platforms, typically integrating aluminum or composite frames, fire-resistant cushioning, and restraint harnesses meeting strict flammability and crashworthiness criteria. These assemblies must withstand dynamic load testing while minimizing mass to preserve payload-range performance. Economy class configurations occupy the highest unit volumes, though margin pools concentrate in business class and first class where customization complexity and aftermarket service attach rates elevate profitability. Premium economy is recording the fastest trajectory as hybrid cabin strategies allow network carriers to capture yield between traditional tiers without full flat-bed investment.
FAA Technical Standard Orders and EASA Certification Specifications govern flammability, structural integrity, and occupant injury criteria, creating multi-year validation timelines that favor incumbents with established test histories and regulatory relationships. The EU Green Deal and emerging ICAO carbon efficiency benchmarks are pressuring airlines to prioritize weight-optimized seating platforms that contribute to fleet-level fuel reduction mandates. Stakeholders must monitor how evolving crashworthiness standards and sustainability-linked procurement criteria reshape supplier qualification and long-term contract structures.
Market Dynamics
Fleet densification mandates from US network carriers are compressing seat pitch while demanding lighter platforms, forcing suppliers to reconcile crashworthiness with mass reduction targets.
Growth Catalysts
- FAA Technical Standard Order C127a:Updated flammability testing protocols are accelerating replacement cycles for legacy cushion assemblies in narrow-body retrofits.
- Carbon fiber thermoplastic composites:Material substitution in seat frames is trimming kilograms per passenger position, translating directly into fuel burn reductions for high-cycle operators.
- India:Indigo and Air India's combined narrow-body order books are generating concentrated demand for economy-class platforms with 28-inch pitch configurations.
Market Restraints
- Titanium and aluminum alloy volatility:Frame material costs swing with aerospace-grade metal spot markets, squeezing fixed-price contract margins.
- Supply concentration in Germany and France:Mechanism and actuator fabrication clusters create single-source vulnerability for tier-two integrators.
- EASA Certification Specification 25.853:Multi-year burn-through and smoke toxicity validation timelines extend program development by 18-24 months.
Strategic Opportunities
- Saudi Arabia:Riyadh Air's greenfield fleet buildout offers first-mover positioning for suppliers willing to co-locate finishing capacity near King Abdulaziz International Airport.
- 16G seat track and leg interface standards:Regulatory harmonization between FAA and EASA is creating cross-certification efficiencies for platforms validated to both regimes.
- Digital twin integration:Convergence of finite element modeling with real-time load monitoring is enabling predictive maintenance contracts for business-class mechanisms.
Industry Challenges
- Composite layup technician scarcity:Manual fiber placement skills for complex seat shell geometries outstrip vocational pipeline output in Western Europe and North America.
- Dynamic 14G testing backlog:FAA-approved crash-test facilities face 12-month queue times, delaying platform introductions.
- Retrofit certification complexity:STC (Supplemental Type Certificate) amendments for mixed-fleet operators multiply engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Seating Market |
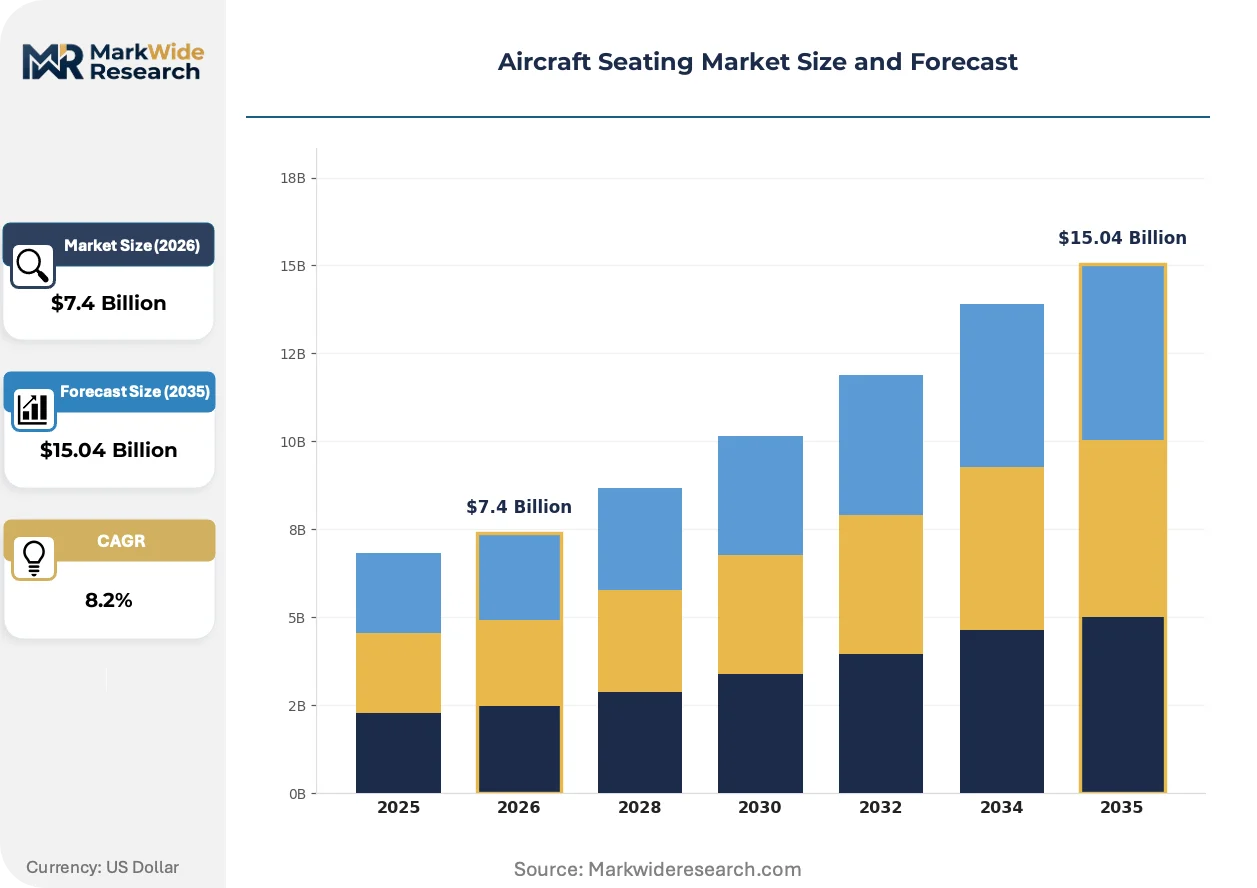
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $15.04 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Economy Class, Business Class, First Class, Premium Economy Material: Leather, Fabric, Plastic, Metal End User: Commercial Airlines, Private Jets, Military Aircraft, Charter Services Installation Type: Fixed, Recliner, Foldable, Convertible |
| Companies Covered | Jamco Corporation, Zodiac Aerospace, Safran Seats, STELIA Aerospace, Geven S.p.A., Collins Aerospace, Thompson Aero Seating, Aviointeriors, RECARO Aircraft Seating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Seating Market Emerging Trajectories
Material science advances and regulatory harmonization efforts are compressing development cycles while opening new service revenue streams for integrated suppliers.
Carbon fiber reinforced thermoplastic (CFRTP) seat shells are supplanting traditional aluminum monocoque construction in premium cabin segments. Singapore Airlines and Qatar Airways are specifying these platforms for next-generation business-class suites. The technology is supplanting incumbent metal-forming suppliers who lack autoclave or press-forming capabilities for complex organic geometries.
EU Green Deal carbon-efficiency benchmarks are pressuring airlines to document lifecycle emissions from seat production through disposal. Original equipment manufacturers must now submit environmental product declarations covering raw material extraction, manufacturing energy intensity, and end-of-life recyclability. Narrow-body operators in the European Union are responding by weight-optimizing every kilogram of cabin furnishings to meet fleet-average CO2 reduction targets.
Airline engineering departments are consolidating supplier relationships around full-cabin integrators capable of delivering seat, monument, and lighting packages under single-source accountability. This consolidation is displacing fragmented procurement of discrete seat platforms from specialists without adjacent interior capabilities. The shift is most visible among US ultra-low-cost carriers retrofitting entire cabin interiors during compressed overnight maintenance windows.
Aircraft Seating Market Segmentation
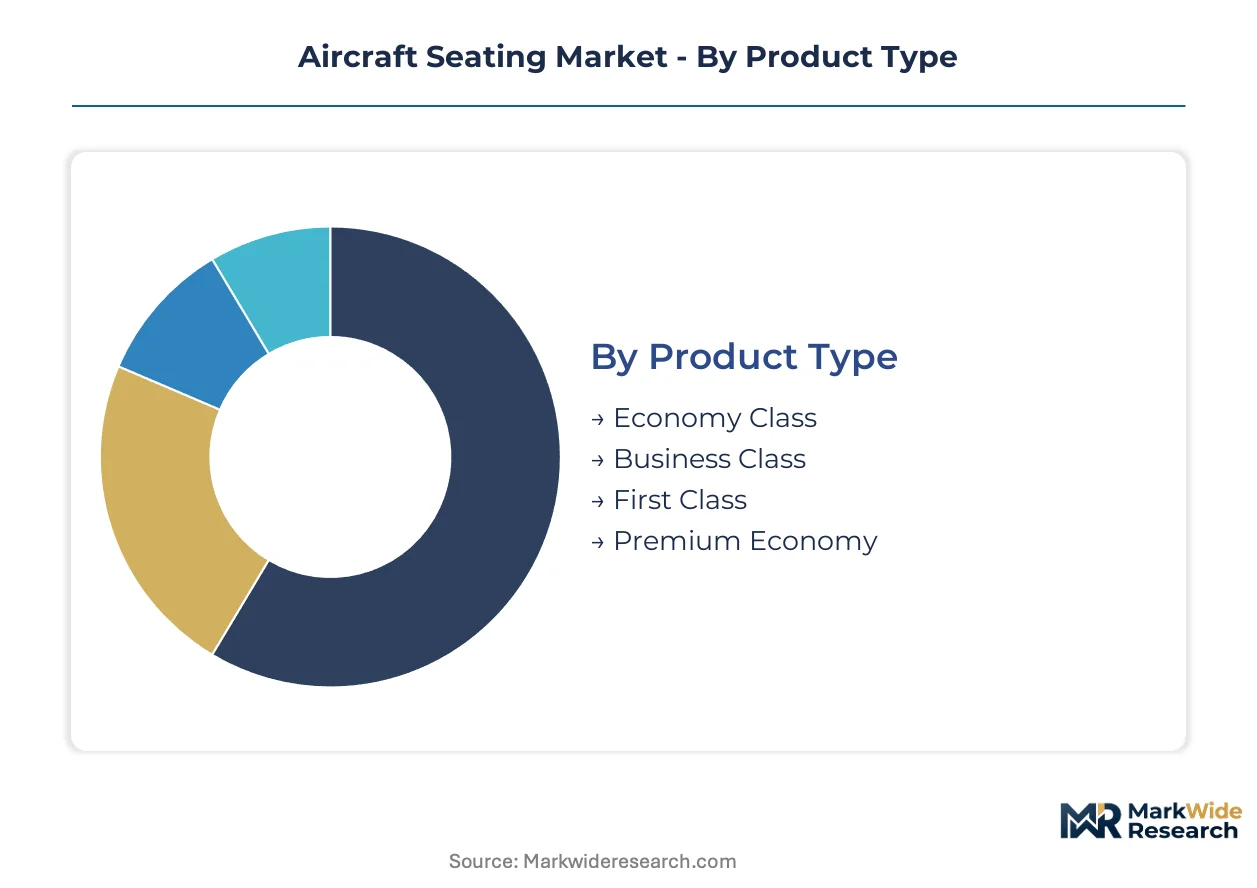
Aircraft seating segmentation reveals divergent margin architectures across cabin tiers and material technologies. Platform selection determines certification burden, weight trade-offs, and aftermarket service attach rates for suppliers competing on fuel efficiency and passenger density metrics.
Product Type:
Substitution pressure from premium economy platforms is compressing demand for traditional business class configurations as hybrid cabin strategies spread.
- Economy Class:High-density aluminum or composite frames with 28- to 32-inch pitch configurations dominate narrow-body retrofits. US network carriers and Indian low-cost operators are driving concentrated demand for sub-10kg platforms that preserve payload-range performance on high-cycle routes.
- Business Class:Lie-flat mechanisms and privacy shells command the highest per-unit margins. Qatar Airways and Singapore Airlines are specifying carbon fiber reinforced thermoplastic shells that displace legacy metal-forming suppliers lacking autoclave capabilities.
- First Class:Ultra-customized suites with personal storage and entertainment integration occupy limited fleet positions. Emirates and Etihad retain demand for enclosed compartments on A380 and 777-300ER platforms.
- Premium Economy:Recliner mechanisms with 38-inch pitch bridge yield gaps between economy and business tiers. British Airways and Lufthansa are expanding dedicated cabins on long-haul fleets.
Economy class retains volume leadership; premium economy holds the steepest expansion curve.
Material:
Cost tier differentiation separates aerospace-grade synthetics from commodity upholstery in procurement specifications.
- Leather:Full-grain hides treated with fire-blocking layers meet FAA Technical Standard Order C127a flammability protocols. Gulf carriers specify premium hides for first and business class applications where durability and aesthetic standards justify material cost premiums.
- Fabric:Woven aramid and wool blends dominate economy and premium economy segments. Indigo and Ryanair procurement teams prioritize stain resistance and cleaning cycle efficiency over tactile luxury.
- Plastic:Injection-molded polycarbonate seat backs and tray tables reduce unit costs for ultra-low-cost carriers. Component suppliers in Germany and France concentrate molding capacity for high-volume programs.
- Metal:Aluminum alloy and titanium frames persist in legacy platforms and high-load structural elements. Spot price volatility in aerospace-grade metals squeezes fixed-price contract margins for tier-two integrators.
Metal frames retain volume leadership; carbon fiber composites hold the steepest expansion curve.
End User:
Customer type determines specification rigor, with military and private aviation demanding crashworthiness beyond commercial minimums.
- Commercial Airlines:Scheduled carriers account for the dominant share of seat procurement. Delta and United retrofit programs are compressing installation timelines to overnight maintenance windows.
- Private Jets:Business aviation operators prioritize customization and rapid reconfiguration. Gulfstream and Bombardier completion centers source bespoke interiors with accelerated certification paths.
- Military Aircraft:Crew and troop transport platforms require 16G dynamic load compliance and ballistic protection integration. Lockheed Martin C-130J and Boeing P-8 programs specify mission-specific restraint systems.
- Charter Services:Mixed-use operators demand quick-change cabins switching between passenger and cargo configurations. ACMI providers in Europe and the Middle East are expanding convertible fleet segments.
Commercial airlines retain volume leadership; charter services hold the steepest expansion curve.
Installation Type:
Volume concentration in fixed configurations reflects fleet densification priorities, while recliner and convertible mechanisms capture premium positioning.
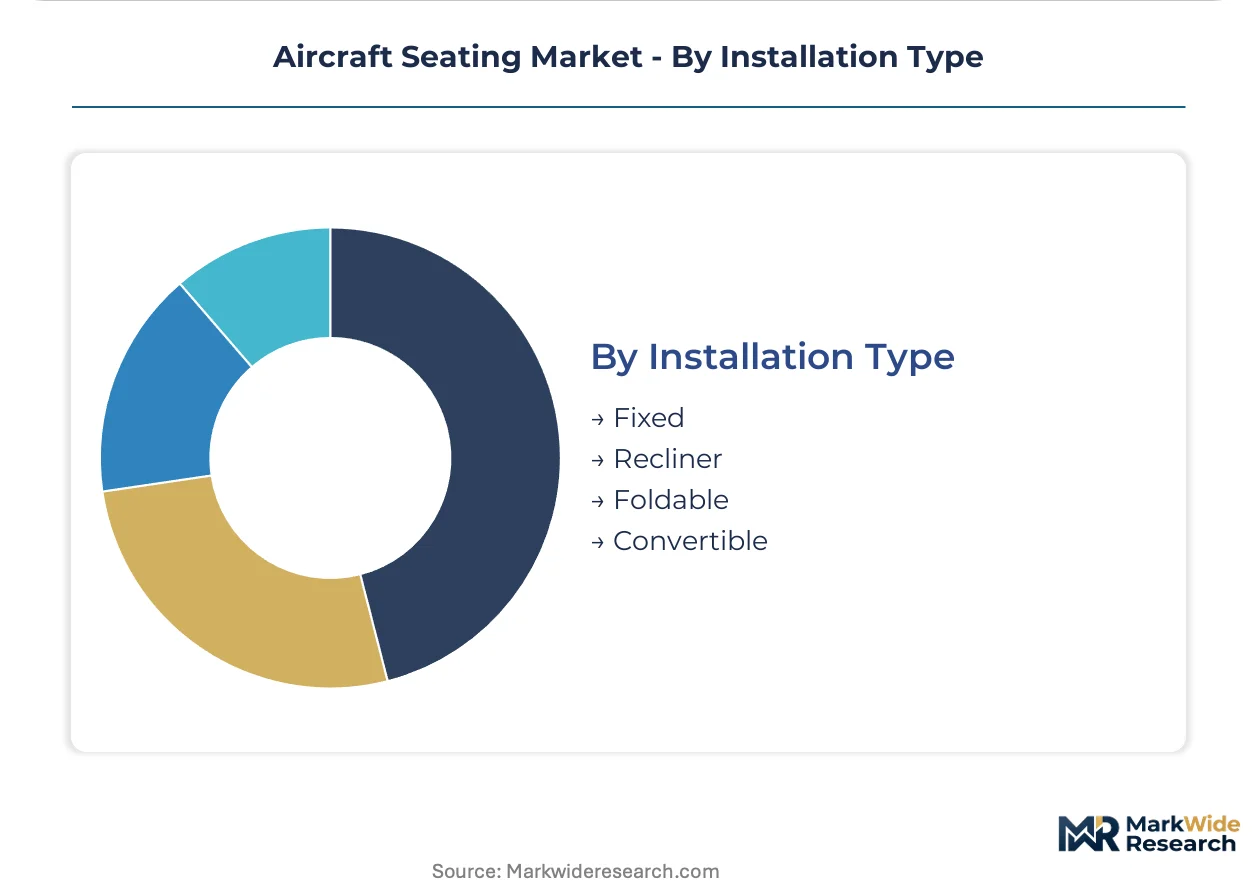
- Fixed:Rigid seat pans with minimal adjustment range minimize weight and maintenance. Spirit Airlines and Frontier Airlines specify fixed-back designs at 28-inch pitch for maximum density.
- Recliner:Articulating mechanisms with 6- to 8-inch travel range dominate premium economy and regional business class. RECARO and Safran compete on mechanism reliability and noise reduction.
- Foldable:Stowable crew and jump seats serve regulatory compliance and space flexibility requirements. Cargo conversion programs for Amazon Air and DHL specify quick-detach foldable positions.
- Convertible:Mechanisms switching between passenger and freight configurations address hybrid fleet utilization. Israel Aerospace Industries and EFW offer supplemental type certificate packages for narrow-body conversions.
Fixed installations retain volume leadership; convertible platforms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. US network carriers prioritize densified configurations at aggressive contract terms, while Gulf carriers accept material cost premiums for premium cabin differentiation. European operators balance EU Green Deal compliance with fleet modernization budgets.
United States
Delta and United are compressing retrofit timelines to overnight maintenance windows, driving demand for quick-install seat platforms. FAA Technical Standard Order C127a governs flammability compliance for cushion replacements. Wichita, Kansas hosts concentrated finishing capacity serving domestic narrow-body programs.
Germany
Lufthansa Group is expanding premium economy cabins across long-haul fleets, requiring 38-inch pitch recliner mechanisms. EASA Certification Specification 25.853 mandates multi-year burn-through validation for new platforms. Hamburg and Munich anchor composite layup clusters for seat shell fabrication.
China
COMAC C919 production ramp-up is generating localized seat procurement for domestic airline customers. GB standards and CAAC harmonization with FAA crashworthiness protocols shape certification pathways. Shanghai and Tianjin concentrate tier-one integrator joint ventures with Western suppliers.
India
Indigo and Air India narrow-body order books are driving concentrated demand for 28-inch pitch economy platforms. BIS flammability standards and DGFT import regulations influence local content requirements. Bangalore and Hyderabad host emerging MRO clusters supporting retrofit programs.
Saudi Arabia
Riyadh Air's greenfield fleet buildout offers first-mover positioning for suppliers co-locating finishing capacity. SFDA and GACA alignment with EASA certification timelines streamline platform validation. King Abdulaziz International Airport vicinity is attracting supplier investment for direct airline integration.
Aircraft Seating Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive architecture. Tier-one integrators control captive supply chains for critical mechanisms and fire-blocking materials, while component-focused suppliers compete on narrow technical specializations. Three archetypes dominate: full-cabin integrators, lightweight composite specialists, and mechanism-focused fabricators. Consolidation is accelerating through vertical integration into raw material supply, and strategic partnerships are displacing arm's-length procurement for complex platform programs.
Among European-integrated leaders, Safran Seats and RECARO Aircraft Seating exemplify divergent strategic positions. Safran represents the full-cabin integrator archetype with backward control over critical supply chains. RECARO occupies a specialist position anchored in premium cabin lightweight engineering. Collins Aerospace, with its US-based portfolio breadth, sits within the multi-system integrator tier extending beyond seating into full cabin ecosystems.
| Leading Market Players |
|---|
| Jamco Corporation |
| Zodiac Aerospace |
| Safran Seats |
| STELIA Aerospace |
| Geven S.p.A. |
| Collins Aerospace |
| Thompson Aero Seating |
| Aviointeriors |
| RECARO Aircraft Seating |
| Others |
Supply Flow & Price Mechanics
Long-term fixed-price contracts with escalation clauses lock in titanium and aluminum alloy supply for tier-one integrators while capping margin exposure to aerospace-grade metal spot volatility. These agreements bind Safran Seats and Collins Aerospace to multi-year delivery schedules that stabilize input costs for narrow-body retrofit programs across US network carriers.
Pricing Analysis
Aftermarket service and spare parts revenue streams drive lifetime value for seat integrators, often exceeding original equipment margins across the platform lifecycle. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden and customization complexity, with business-class mechanisms commanding substantial premiums over fixed-back economy configurations. Pricing pressure stems from ultra-low-cost carrier procurement teams demanding sub-10kg platforms at aggressive contract terms. Indian low-cost operators exhibit highest price sensitivity, while Gulf carriers accept material cost premiums for premium cabin differentiation.
Supply Chain Analysis
Just-in-time inventory strategies dominate final assembly operations, though strategic stockpiling of fire-blocking textiles and carbon fiber prepreg mitigates lead-time volatility for critical certification-path items. Germany, France, and the United States anchor mechanism fabrication and composite layup capacity for seat shell production. The industry draws from aerospace-grade aluminum, titanium alloys, and carbon fiber thermoplastic resins as primary inputs. Single-source vulnerability in actuator and track mechanism clusters concentrated in Hamburg and Toulouse poses structural risk. Distribution runs through direct airline procurement channels and tier-one integrator relationships, with MRO facilities serving retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft seating operates as a defensive-moat market where multi-year FAA and EASA certification timelines create regulatory entrenchment that protects incumbents from rapid competitive displacement.
For Market Incumbents: Fortify captive supply chains for fire-blocking materials and precision mechanisms through backward integration into textile treatment and actuator fabrication. Expand finishing capacity in Saudi Arabia near King Abdulaziz International Airport to capture Riyadh Air's greenfield fleet buildout. EASA Certification Specification 25.853 validation timelines represent the primary barrier shielding established players from fast-follower competition. For New Entrants and Emerging Players: Anchor in convertible platform segments for cargo-conversion programs serving Amazon Air and DHL narrow-body retrofits, where supplemental type certificate complexity has deterred full-cabin integrators. Target charter service operators in Europe and the Middle East with quick-change cabin mechanisms, the most penetrable segment outside scheduled carrier procurement lock-ins. Pursue partnerships with Israel Aerospace Industries or EFW for STC co-development to bypass direct airline sales cycle barriers. For Investors and Strategic Acquirers: Composite engineering specialists with autoclave capabilities for carbon fiber reinforced thermoplastic shells present compelling acquisition targets as Qatar Airways and Singapore Airlines displace legacy metal-forming suppliers. Long-term viability rests on fuel-efficiency mandates tightening across the analysis window, with seat weight optimization becoming non-negotiable for fleet-level CO2 compliance. Watch for FAA-EASA regulatory harmonization on 16G seat track standards as inflection indicator for cross-certification efficiency gains that would accelerate platform introductions.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Thermoplastic Shell Investment | Enables Qatar Airways and Singapore Airlines to specify gram-reduced premium cabin platforms. |
| Co-Located Finishing Capacity Expansion | Positions suppliers for Riyadh Air's direct integration requirements near King Abdulaziz International Airport. |
| Predictive Maintenance Contract Development | Captures recurring revenue from business-class mechanism monitoring through digital twin integration. |
| Fire-Blocking Textile Backward Integration | Secures margin control for FAA Technical Standard Order C127a compliant cushion assemblies. |
| Supplemental Type Certificate Portfolio Buildout | Opens cargo-conversion revenue streams with Amazon Air and DHL narrow-body programs. |
Methodological Framework
Operator-level perspectives from fleet engineering directors, procurement executives at network carriers, MRO facility managers, and certification specialists anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from FAA Technical Standard Order filings, EASA Certification Specification databases, airline fleet planning disclosures, and customs import records for aerospace-grade materials. Bottom-up platform demand modeling triangulated against top-down fleet projection frameworks to ensure dimensional consistency.
Sensitivity analysis across fuel price scenarios, fleet renewal cycles, and regulatory harmonization timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include cabin class tier, material technology, installation mechanism type, end-user category, and geographic regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution across these segments. Industry-specific forecast inputs incorporated narrow-body order book concentrations from Indigo and Air India, plus EU Green Deal carbon-efficiency benchmark compliance requirements.
Decision-makers should treat outputs as directional under base assumptions of sustained fleet densification and stable certification timelines; material deviation would warrant model refresh. Forecasts reflect assumptions of continued FAA-EASA regulatory alignment and titanium alloy price band stability. Revision becomes warranted when aerospace-grade metal spot volatility crosses thresholds that compress tier-two integrator margins beyond contract renegotiation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Aviation Carpet Market