
 Aerospace Interior Market | 2026-2036
Aerospace Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Interior Market Intelligence
TSO-C127 and ETSO-C127 certification cycles for aircraft seating is bifurcating the competitive landscape into qualified incumbents and excluded aspirants. Collins Aerospace leverages vertical integration across seating and galley systems to sustain program awards on next-generation platforms. Safran anchors European supply chains through Diehl Aviation's specialized cabin architecture capabilities. RECARO Aircraft Seating dominates premium and economy seating segments through dedicated ergonomics R&D.
Aerospace interior encompasses the complete habitable environment within an aircraft fuselage, including structural panels, seating systems, galleys, lavatories, and integrated lighting—typically engineered to meet 16g dynamic load requirements and 60-second evacuation protocols while minimizing weight below traditional metallic alternatives. The primary purpose centers on passenger safety, crew operational efficiency, and carrier revenue optimization through configurable density and amenity differentiation. Cabin seating captures the largest value pool as airlines prioritize passenger experience metrics and frequent-flier retention, while composite materials displace aluminum in sidewalls and overhead bins to achieve double-digit weight reductions per shipset. LED lighting and noise reduction technologies represent the fastest-expanding technology segments as carriers retrofit older fleets without full cabin reconfigurations.
FAA Part 25 flammability standards, EASA CS-25 certification requirements, and ISO 2685 fire containment protocols collectively dictate material selection, testing cadence, and supplier qualification timelines across all product categories. These frameworks create multi-year barriers to entry that protect incumbent positions while raising compliance costs for new entrants. Stakeholders must monitor evolving sustainability mandates from regulators in the United States and Europe, as recycled content thresholds and carbon disclosure requirements reshape procurement criteria and supplier scorecards.
Market Dynamics
Certification bottlenecks at FAA and EASA are compressing supplier qualification timelines while narrow-body fleet refresh cycles concentrate procurement authority among three major airframe integrators. This structural tension between regulatory rigor and production velocity defines current competitive positioning.
Growth Catalysts
- FAA Part 25 Amendment 25-116:Updated flammability testing protocols are accelerating composite panel adoption in sidewall applications as carriers retrofit aging narrow-body fleets.
- LED ambient lighting systems:Retrofit demand from low-cost carriers seeking cabin differentiation without full reconfiguration drives aftermarket revenue expansion.
- United States manufacturing concentration:Boeing's supply chain anchorage in Washington and South Carolina creates localized demand pull for tier-two seating and galley subsystem suppliers.
Market Restraints
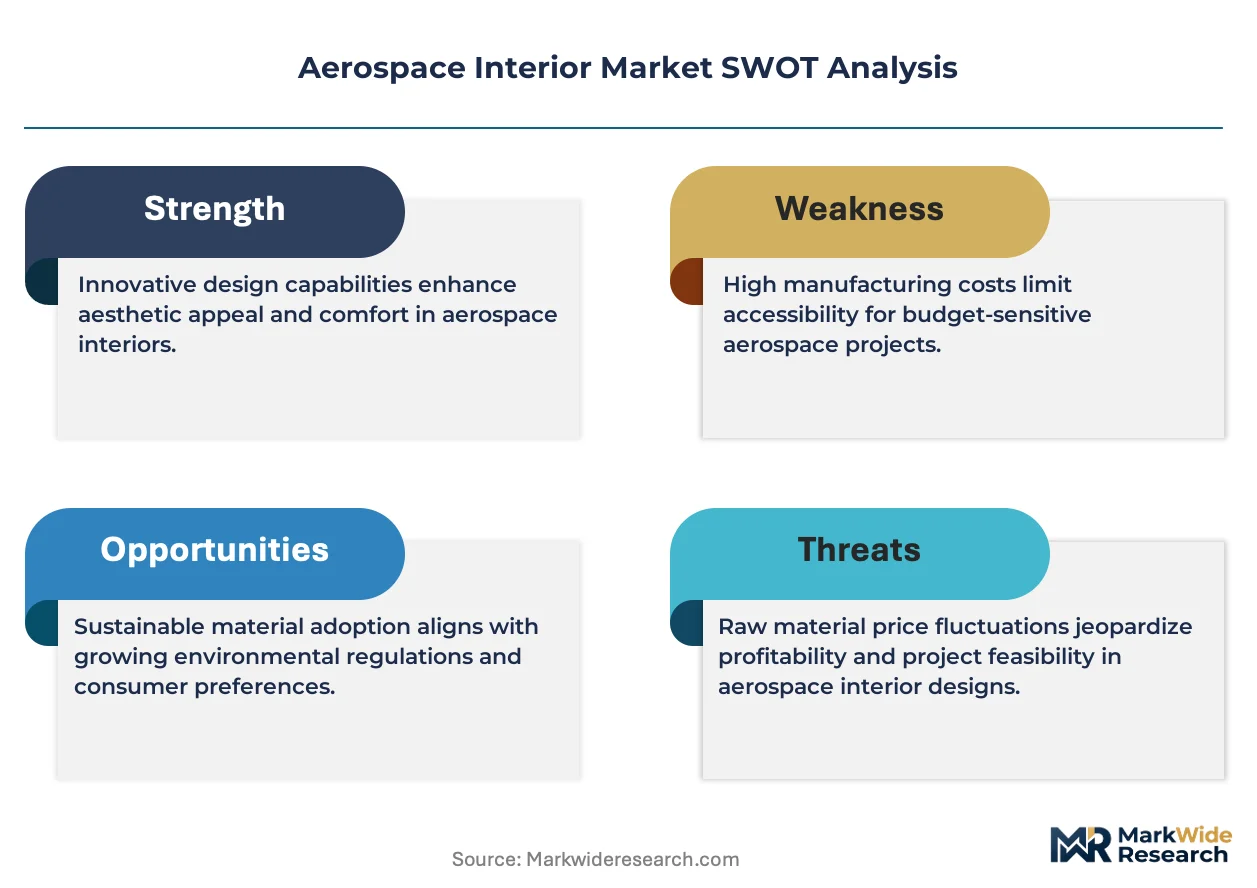
- Titanium and aramid fiber cost volatility:Aerospace-grade material input prices swing with defense sector demand cycles, squeezing margin predictability for seat frame manufacturers.
- European supplier concentration:Diehl Aviation and Safran cabin systems dominate EASA-certified galley architecture, limiting new entrant access to A320/A350 program awards.
- 16g dynamic load certification:Crashworthiness testing requirements for seating systems impose capital-intensive test facilities that exclude mid-tier engineering firms from commercial programs.
Strategic Opportunities
- India narrow-body expansion:IndiGo and Air India fleet orders create demand for economy seating and lavatory modules as indigenous MRO capabilities mature.
- EU Green Deal sustainable aviation mandates:Recycled content thresholds for cabin materials are reshaping supplier scorecards and creating first-mover advantage for bio-composite developers.
- Digital twin convergence with predictive maintenance:Integrated cabin sensor networks and IoT-enabled seat monitoring enable aftermarket service contracts beyond hardware shipment.
Industry Challenges
- TSO-C127 certification timeline compression:FAA backlog in dynamic testing approvals delays program entry for redesigned seat models, forcing suppliers to maintain dual certification tracks.
- Legacy IFE integration complexity:New lightweight seating platforms must interface with existing in-flight entertainment architectures, constraining form factor innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Interior Market |
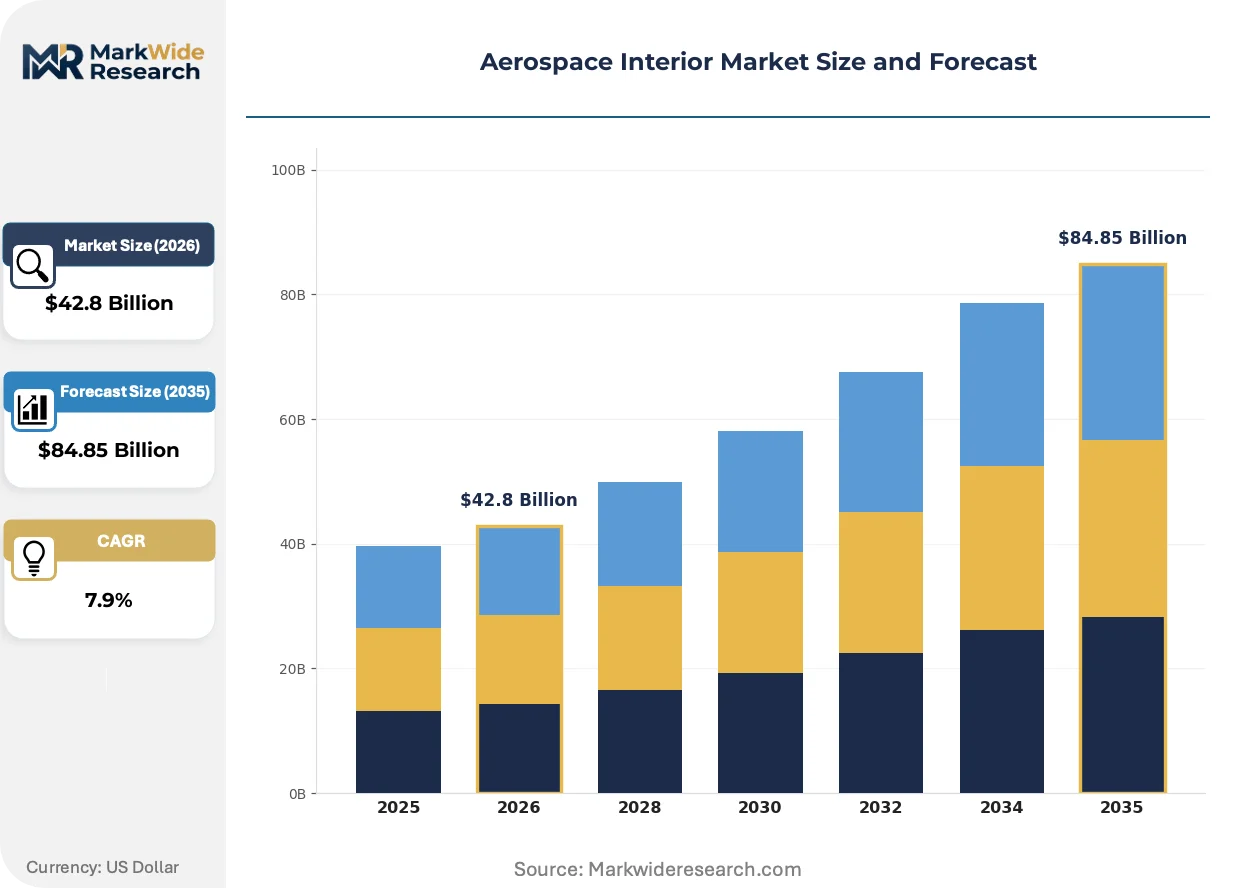
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $84.85 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cockpit, Cabin Seating, Galley, Restroom Material: Aluminum, Composite, Fabric, Foam End User: Commercial Airlines, Private Jets, Cargo Operators, MRO Technology: LED Lighting, In-flight Entertainment, Cabin Pressure Systems, Noise Reduction |
| Companies Covered | Collins Aerospace, Safran, Panasonic Avionics Corporation, Diehl Aviation, Honeywell International, Jamco Corporation, RECARO Aircraft Seating, Astronics Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Interior Market Strategic Shifts & Innovations
Material substitution and modular cabin architectures are compressing development cycles while regulatory pressure on fire safety and weight reduction intensifies specification evolution across seating and paneling categories.
Advanced thermoplastic composites are bifurcating the sidewall and overhead bin supply base. Boeing and Airbus are qualifying carbon fiber-reinforced PEEK panels for next-generation single-aisle programs. This material transition is bifurcating incumbent aluminum suppliers from composite specialists capturing double-digit weight reduction contracts.
REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of seat upholstery and insulation foams. European suppliers face accelerated substitution timelines for legacy materials. The seating segment bears primary compliance burden as EASA tightens smoke toxicity thresholds beyond FAA baseline requirements.
Carrier procurement teams now unbundle cabin reconfiguration projects into phased retrofit schedules. Low-cost operators in Southeast Asia prioritize lavatory and galley module replacement over full seating replacement. This pattern concentrates in Indonesia and Vietnam where lease-return aircraft enter secondary service with minimal downtime tolerance.
Aerospace Interior Market Segmentation
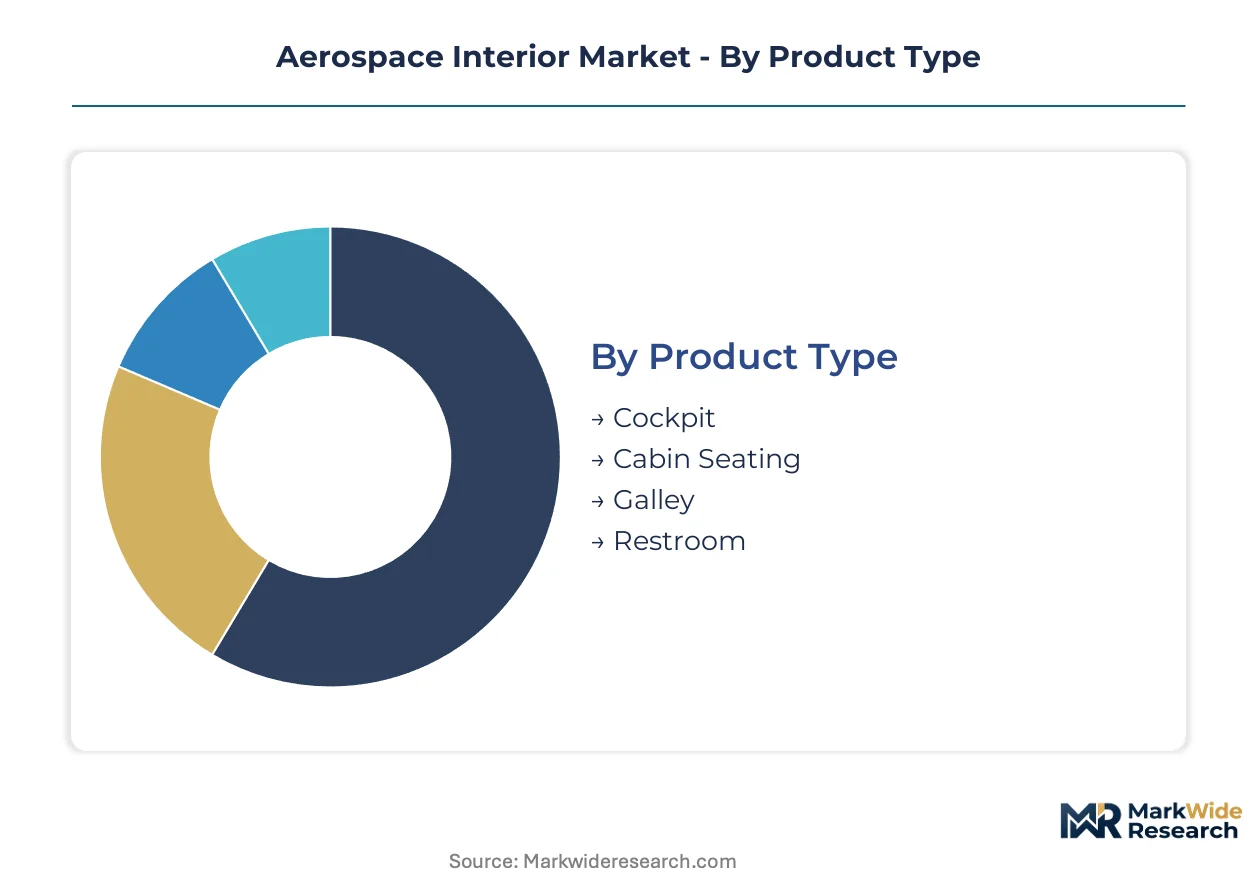
Aerospace interior procurement splits across four distinct category axes, each governing supplier qualification pathways and margin structures differently. Product type and material composition determine FAA and EASA certification burden, while end-user channel and technology tier dictate retrofit versus OEM attach rates.
Product Type:
Domestic United States demand concentrates in cabin seating and galley systems serving Boeing's Washington and South Carolina assembly lines, while European export flows center on restroom modules and cockpit inserts qualified for Airbus A320 family programs.
- Cockpit:Flight deck enclosures integrate structural panels meeting 16g dynamic load specifications alongside avionics mounting interfaces. Boeing 737 MAX and Airbus A350 programs in the United States and France anchor OEM demand, though aftermarket refurbishment cycles lag cabin refresh timelines by three to five years.
- Cabin Seating:TSO-C127 and ETSO-C127 certification requirements bifurcate supply into qualified incumbents and excluded aspirants. Economy and premium configurations for narrow-body fleets in the United States drive volume, while lie-flat business class seats for long-haul carriers concentrate specification authority with Lufthansa and Emirates engineering teams.
- Galley:Modular food service and storage systems integrate with lavatory architecture in space-optimized single-aisle layouts.
- Restroom:Vacuum waste and water systems prioritize weight reduction and 60-second evacuation compliance over passenger amenity differentiation.
Cabin seating commands the established base. The steepest expansion runs through galley systems as carriers unbundle reconfiguration projects.
Material:
Cost tier stratification separates legacy aluminum suppliers defending installed base from composite specialists capturing next-generation platform awards through double-digit weight reduction claims.
- Aluminum:Conventional sidewall and overhead bin construction retains cost advantage for lease-return aircraft entering secondary service in Southeast Asia. Indonesian and Vietnamese low-cost operators specify aluminum panels to minimize acquisition outlay on fifteen-year-old A320 airframes.
- Composite:Carbon fiber-reinforced PEEK panels qualify for Boeing and Airbus next-generation single-aisle programs, displacing metallic alternatives through 12-18% shipset weight reduction. REACH Annex XVII halogen restrictions accelerate European substitution timelines beyond FAA baseline requirements.
- Fabric:Upholstery and decorative surfacing materials face reformulation pressure from EASA smoke toxicity thresholds tightening beyond United States standards.
- Foam:Seat cushion and insulation substrates confront recycled content mandates under EU Green Deal procurement scorecards.
Aluminum retains the volume base. Composite materials are climbing the fastest as airframe integrators prioritize fuel efficiency certification.
End User:
Customer type determines specification authority concentration, with commercial airlines consolidating procurement decisions among three major airframe integrators while private jet and cargo channels fragment across completion centers.
- Commercial Airlines:Narrow-body fleet refresh cycles in the United States concentrate demand for economy seating and LED retrofit lighting. United, Delta, and American Airlines specification teams coordinate directly with Boeing on 737 MAX cabin configurations, bypassing traditional tier-two distributors.
- Private Jets:Completion centers in Wichita and Savannah customize interiors for ultra-high-net-worth owners, prioritizing bespoke craftsmanship over certification velocity.
- Cargo Operators:Main-deck fire containment and 9g restraint systems dominate specification for converted freighter programs.
- MRO:Third-party maintenance providers in Miami and Singapore manage lease-return refurbishment without airframe OEM direct involvement.
Commercial airlines command the established base. The steepest expansion runs through MRO channels as lease-return volume accelerates in Asia-Pacific.
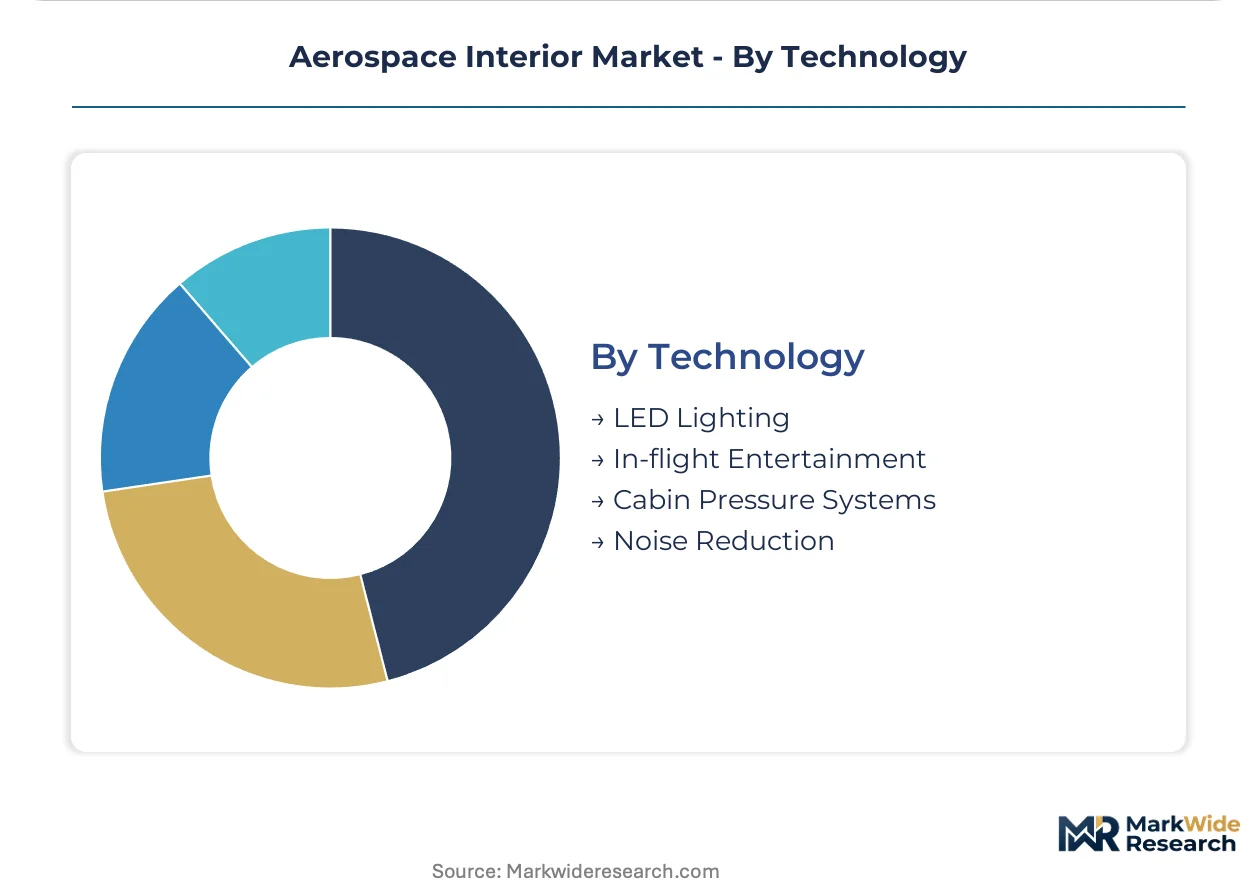
Technology:
Application maturity separates LED lighting and noise reduction as retrofit-friendly upgrades from integrated IFE and pressure systems requiring airframe-level engineering coordination.
- LED Lighting:Ambient and task illumination systems retrofit into aging narrow-body fleets without structural modification. Low-cost carriers in the United States specify LED upgrades to differentiate cabin experience without full reconfiguration downtime.
- In-flight Entertainment:Seatback screen and connectivity hardware integration constrains lightweight seating platform form factor innovation. Legacy IFE architectures from Panasonic and Thales impose interface requirements on new seat designs.
- Cabin Pressure Systems:Environmental control integration requires airframe OEM engineering sign-off, limiting aftermarket participation.
- Noise Reduction:Acoustic panel and active cancellation technologies gain specification as carriers prioritize passenger comfort metrics for frequent-flier retention.
In-flight entertainment commands the established base. The steepest expansion runs through LED lighting as retrofit demand outpaces OEM attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline specification authority concentrates with Boeing in the United States and Airbus in France, creating dual demand poles that structure procurement geography. Certification requirements from FAA and EASA reinforce this concentration. Supply chains cluster around final assembly locations in Washington, South Carolina, Toulouse, and Hamburg.
United States
Boeing's 737 MAX and 777X programs in Washington and South Carolina drive demand for economy seating and LED retrofit systems. FAA Part 25 Amendment 25-116 accelerates composite panel adoption as carriers refresh narrow-body fleets. The Pacific Northwest cluster anchors tier-two seating and galley subsystem suppliers to Everett and Renton assembly lines.
France
Airbus A320 and A350 final assembly in Toulouse concentrates specification authority for cabin architecture and lavatory modules. EASA CS-25 certification timelines exceed FAA baselines, favoring incumbent European suppliers with established qualification tracks. The Occitanie region hosts specialized composite panel fabricators serving Airbus single-aisle programs.
Germany
Hamburg's A320 family completion center and premium cabin outfitting facilities drive demand for lie-flat business class seats and bespoke interior configurations. REACH Annex XVII restrictions on halogenated flame retardants accelerate upholstery reformulation timelines beyond United States requirements. Bavaria-based engineering firms specialize in 16g dynamic load testing for seating certification.
China
COMAC C919 production ramp in Shanghai creates incremental demand for domestic-qualified seating and galley systems as indigenous narrow-body capacity scales. China's national aviation regulator imposes flammability testing protocols aligned with FAA baselines but with extended documentation requirements. The Yangtze River Delta cluster concentrates MRO refurbishment activity for lease-return aircraft entering Chinese carrier fleets.
India
IndiGo and Air India fleet expansion drives specification for high-density economy seating and modular lavatory systems as narrow-body capacity doubles through 2030. The country's Directorate General of Civil Aviation maintains certification reciprocity with FAA and EASA but requires local witness testing for initial approvals. Bangalore and Hyderabad emerging as MRO hubs for cabin refurbishment of returning leased aircraft.
Aerospace Interior Market Key Industry Players
Player mix skews toward vertically integrated airframe-tier suppliers with captive certification capabilities. Three structural tiers separate qualified incumbents holding TSO-C127 approvals from mid-tier engineering aspirants and regional fabrication specialists. Dominant competitive moves include backward integration into composite material supply and strategic partnerships with airframe OEMs on next-generation platform development.
Within the integrated-systems tier, Collins Aerospace and Safran exemplify archetypes combining seating, galley, and cabin management capabilities under unified program execution. RECARO Aircraft Seating occupies a specialized position representing dedicated ergonomics-focused seating houses that compete through R&D velocity rather than portfolio breadth. These three anchors illustrate how certification assets and airframe relationships structure competitive access more than manufacturing scale alone.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| Panasonic Avionics Corporation |
| Diehl Aviation |
| Honeywell International |
| Jamco Corporation |
| RECARO Aircraft Seating |
| Astronics Corporation |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Boeing's 737 MAX production cadence at 42 monthly units and Airbus A320 family output exceeding 50 monthly frames create capacity-utilization premiums that compress supplier margins while elevating qualification barriers. This scale concentration allows airframe OEMs to enforce long-term cost-plus contracts with raw material indexation, locking tier-two seating and galley manufacturers into pass-through pricing with limited margin expansion leverage.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum and titanium sponge indexation dominate narrow-body seating programs, though composite panel suppliers negotiate fixed-price arrangements for carbon fiber-reinforced PEEK shipsets. Price differentiation separates FAA-certified incumbents from EASA dual-track aspirants, with certification grade commanding 15-20% premiums on equivalent seat configurations. Pricing pressure stems from low-cost carrier procurement consolidation around IndiGo, Ryanair, and Southwest specification teams. MRO channels exhibit highest price sensitivity due to lease-return refurbishment budget constraints, while private jet completion centers demonstrate lowest sensitivity to unit economics.
Supply Chain Analysis
Inventory cycles extending 18-24 months for aramid fiber and titanium castings force seating manufacturers to absorb working capital burdens before program revenue recognition. Supply concentrates in the United States for Boeing-tier seating and galley systems, in France and Germany for Airbus-qualified cabin architecture, and in Japan for specialized composite preform fabrication. Raw material dependencies include aerospace-grade carbon fiber from Toray and Hexcel, titanium sponge from VSMPO-AVISMA and TIMET, and PEEK resin from Victrex and Solvay. Single-source vulnerability concentrates in Russian titanium sponge supply subject to trade restriction risk. Distribution runs through airframe OEM direct procurement for OEM attach rates, with tier-two distributors serving aftermarket retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace interior procurement fragmentation creates niche opportunities as carrier unbundling of cabin reconfiguration projects breaks monolithic program awards into modular component sourcing. This demand-side shift enables specialized seating ergonomics houses and bio-composite developers to capture specification authority previously consolidated within integrated-systems tier suppliers.
For Market Incumbents: Consolidate backward integration into carbon fiber preform manufacturing to defend margin position against raw material cost volatility, while expanding captive 16g dynamic load testing capacity to compress TSO-C127 certification timelines for redesigned seat models. Threats from bio-composite specialists qualifying under EU Green Deal recycled content mandates require preemptive sustainability scorecard positioning.
For New Entrants and Emerging Players: Aftermarket IoT-enabled seat monitoring and predictive maintenance service layers represent incumbents' under-served white space, where hardware-software bundling creates recurring revenue attachment. India's narrow-body fleet expansion offers the most penetrable geography given indigenous MRO capability maturation and DGCA certification reciprocity with FAA baselines. Go-to-market execution should anchor on partnerships with Bangalore and Hyderabad emerging MRO hubs for lease-return refurbishment contracts.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cabin management system integrators with embedded software maintenance contracts and sensor network service agreements. Long-term viability favors suppliers with dual FAA-EASA certification tracks and composite material qualifications on next-generation single-aisle platforms. Acquisition target archetypes include specialized 16g testing facilities and bio-composite formulation specialists. The signal to watch is EASA smoke toxicity threshold tightening beyond FAA baselines, which would accelerate incumbent material substitution costs and create competitive openings for pre-qualified alternative suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Qualification | Carbon fiber-reinforced PEEK panel approval on Boeing 737 MAX and Airbus A320neo programs displaces aluminum shipsets. |
| Certification Investment | Dual-track FAA-EASA TSO-C127 approval compresses program entry timelines for redesigned seat models. |
| Aftermarket Service Expansion | IoT-enabled seat monitoring and predictive maintenance contracts extend revenue capture beyond hardware shipment. |
| Sustainability Repositioning | EU Green Deal recycled content compliance reshapes supplier scorecards and procurement criteria for European carrier awards. |
| Geographic Manufacturing Footprint | India MRO hub proximity to IndiGo and Air India fleet expansion captures lease-return refurbishment volume. |
Research Approach
A spread of perspectives from Boeing and Airbus procurement executives, tier-two seating manufacturer program managers, FAA certification engineers, and low-cost carrier specification teams converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA TSO-C127 certification databases, EASA CS-25 type certificate records, and airframe OEM supplier qualification lists. Bottom-up triangulation across product category shipment volumes and top-down reconciliation against airframe production forecasts anchored market size estimation.
Segmentation dimensions modeled include product type, material composition, end-user channel, and technology tier across the projection horizon. CAGRs derived from airframe delivery forecasts, fleet refresh cycle analysis, and retrofit penetration assumptions by carrier archetype. Industry-specific forecast inputs incorporated Boeing 737 MAX and Airbus A320neo production ramp schedules, composite material substitution curves, and LED lighting retrofit adoption rates by fleet age cohort.
Forecasts assume regulatory continuity in FAA Part 25 and EASA CS-25 certification regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Interior Market