
 Latin America Commercial Aircraft Cabin Interior Market | 2026-2036
Latin America Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Commercial Aircraft Cabin Interior Market Foresight
OEM-direct procurement channels in Latin America is reconfiguring as Brazilian and Mexican carriers consolidate supplier relationships around integrated cabin programs. Safran SA leverages its seating and cabin systems integration to anchor retrofit contracts with LATAM and Azul. Panasonic Avionics Corporation competes on in-flight entertainment and connectivity hardware, while Diehl Aerospace GmbH specializes in lighting and overhead bin assemblies for Airbus A320 family operators across the region.
Latin America commercial aircraft cabin interior encompasses the complete fit-out of passenger and crew spaces within fixed-wing commercial aircraft, including seats, stowage, lighting, linings, and lavatories engineered to meet flammability, smoke, and toxicity specifications under FAR 25.853 and equivalent standards. Seating commands the largest product type share as airlines densify cabins to maximize revenue per available seat mile, while retrofit installation type grows fastest as aging A320ceo and 737NG fleets require interior refresh cycles. Composites displace aluminum in sidewall panels and overhead bins to reduce weight, though fabrics retain dominance in upholstery due to cost and replaceability.
Brazil's ANAC applies FAA-harmonized certification rules for cabin materials, while Mexico's DGAC enforces equivalent airworthiness directives that shape supplier qualification timelines. EASA REACH substance restrictions on flame retardants increasingly influence material selection for European-leased aircraft operating in Latin America. Stakeholders must monitor how upcoming ICAO carbon offset requirements interact with cabin weight reduction targets to determine composite versus conventional material strategies.
Market Dynamics
Retrofit installation cycles are compressing as Brazilian and Mexican low-cost carriers accelerate narrowbody cabin refresh programs to capture ancillary revenue from densified seating configurations. This structural force is reshaping supplier relationships around integrated program delivery rather than component transactions.
Growth Catalysts
- Fleet densification mandates:Azul, Gol, and Volaris are reconfiguring A320 and 737 cabins to add 6-12 seats per aircraft, driving replacement demand for slimline seats and re-engineered overhead bins.
- ANAC-DGAC harmonization:Brazil's ANAC and Mexico's DGAC have aligned fire safety certification timelines with FAA Part 25 standards, reducing duplicate testing costs for interior suppliers serving both markets.
- Composites substitution:Carbon fiber-reinforced thermoplastics are displacing aluminum in sidewall panels and bin assemblies, cutting 15-20% weight per lavatory and galley module.
Market Restraints
- Epoxy resin price volatility:Composite panel manufacturers face margin compression from petrochemical feedstock fluctuations that constitute 35-40% of raw material costs.
- Supplier concentration in São Paulo state:Three-quarters of certified seat assembly capacity sits within 200 kilometers of Guarulhos, creating geographic vulnerability to logistics disruptions.
- EASA REACH substance restrictions:European-leased aircraft operating Latin American routes must meet flame retardant chemical standards that conflict with legacy interior material specifications.
Strategic Opportunities
- Colombia hub expansion:Avianca's Bogotá maintenance complex is emerging as a third retrofit cluster alongside São Paulo and Mexico City, attracting tier-two seating suppliers seeking proximity.
- Line-fit pre-delivery programs:Airbus's Mobile and São José dos Campos delivery centers offer direct installation contracts that bypass airline procurement departments entirely.
- Connected cabin convergence:Integration of Panasonic Avionics IFE hardware with Diehl lighting systems creates bundled upgrade paths for A320neo operators seeking single-source retrofit accountability.
Industry Challenges
- Certification engineer scarcity:ANAC-qualified flammability testing specialists number fewer than 200 across Brazil, creating 8-14 month backlog for new material approvals.
- Legacy 737NG integration complexity:Aging wire harness architectures cannot support modern LED lighting and USB power loads without complete electrical system overhaul.
- Spare parts forecasting opacity:Airlines withhold fleet utilization data from seat OEMs, forcing suppliers to maintain excess inventory of wear-prone upholstery and armrest mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Commercial Aircraft Cabin Interior Market |
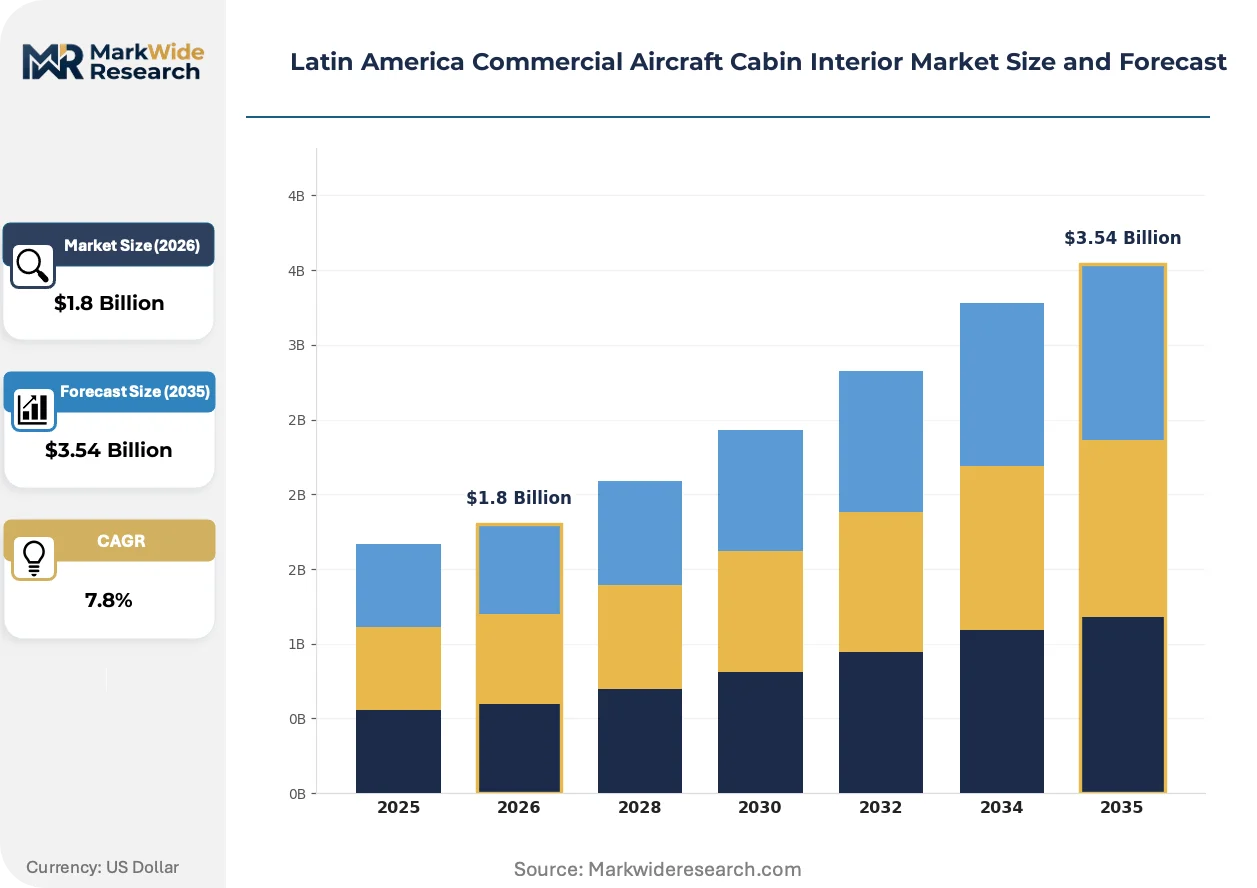
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Overhead Bins, Lighting, Cargo Compartments End User: Commercial Airlines, Charter Operators, Freight Services, Private Jets Material: Aluminum, Composites, Fabrics, Plastics Installation Type: Line Fit, Retrofit, Modification, Maintenance |
| Companies Covered | Honeywell International Inc, Triumph Group Inc, Thompson Aero Seating Ltd, Thales Group, RECARO Holding GmbH, Panasonic Avionics Corporation, Raytheon Technologies Corporation, Diehl Aerospace GmbH, Safran SA, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Commercial Aircraft Cabin Interior Market Shifts & Advancements
Digital design-to-manufacture workflows are collapsing development timelines for custom cabin configurations while regulatory pressure on material toxicity is forcing chemistry substitutions across upholstery and composite formulations.
Polyetherimide thermoplastics are migrating from thermoset composites in thermoformed seat shells and tray table surfaces, cutting tooling costs by 60% for production runs below 500 units. Regional carriers like Aeroméxico Connect and Azul Conecta are adopting these materials for rapid fleet harmonization. The technology is migrating from aerospace-exclusive supply chains into automotive-crossover manufacturing partnerships that leverage shared thermoplastic stamping infrastructure.
EASA REACH substance restrictions on halogenated flame retardants are compelling textile suppliers to reformulate seat cover coatings before 2026 phase-out deadlines. Brazilian manufacturers serving LATAM's European-leased A350 fleet must now dual-certify materials under ANAC and EASA protocols simultaneously. Upholstery mills in Minas Gerais are responding by partnering with German chemical firms to fast-track phosphorus-based alternatives through accelerated aging tests.
Airlines are unbundling interior procurement from airframe purchase agreements, creating direct supplier relationships that bypass traditional OEM intermediaries. Volaris and Gol now negotiate seat and lighting contracts separately from Airbus or Boeing line-fit packages, compressing decision cycles from 18 months to 7 months. This pattern is most visible in Mexico's narrowbody retrofit market, where maintenance divisions have gained procurement autonomy previously held by fleet planning departments.
Latin America Commercial Aircraft Cabin Interior Market Segmentation
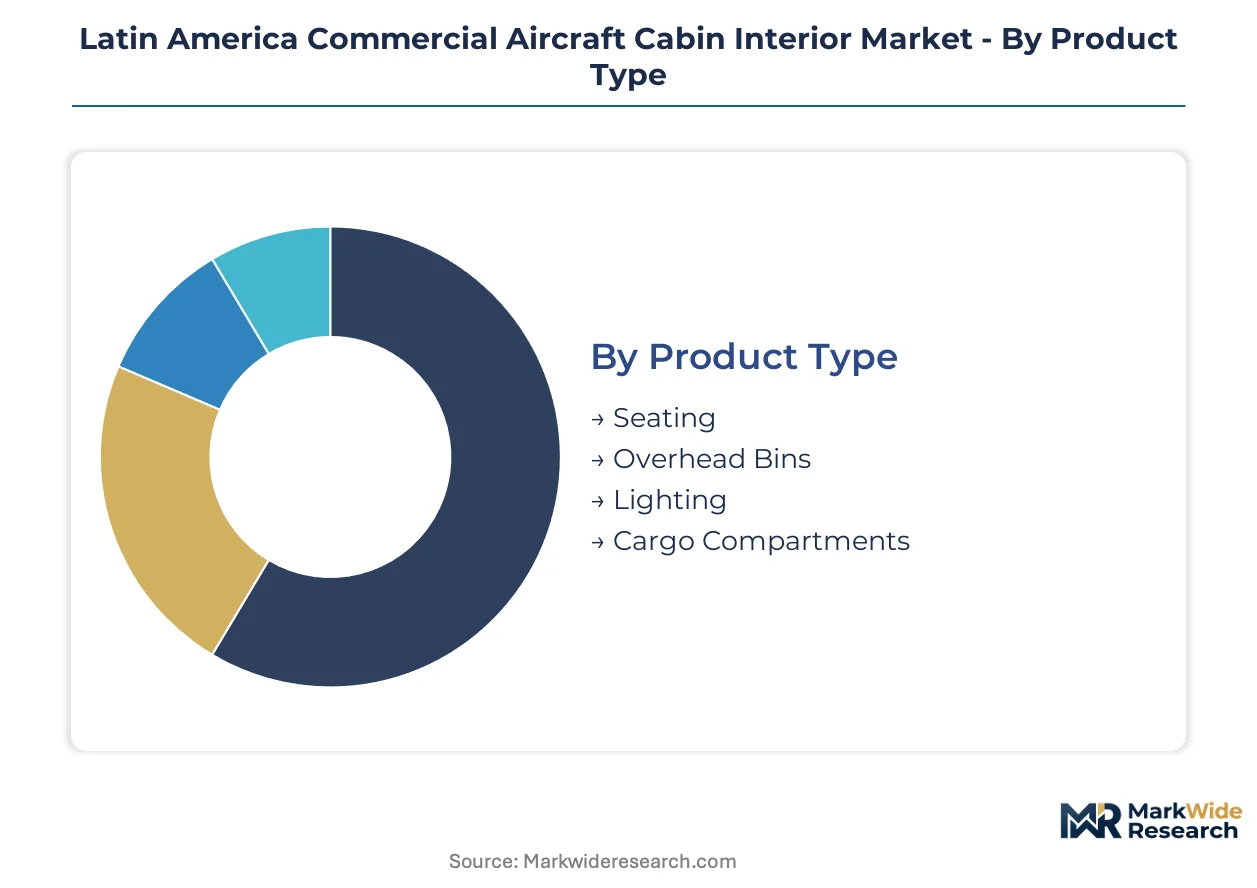
Cabin interior procurement in Latin America splits across product function, operator economics, material certification pathways, and installation timing. Each dimension shapes supplier qualification requirements and contract structures differently across Brazilian and Mexican aviation markets.
Product Type:
Cost tier determines supplier consolidation and margin structure, with high-investment categories commanding integrated program delivery while commoditized segments fragment across regional fabricators.
- Seating:Slimline and recliner assemblies incorporating fire-blocking layers, dynamic test certification, and track-mounted quick-change rails. Demand concentrates at Azul's Belo Horizonte maintenance base and Volaris's Guadalajara facility where densification programs add 6-12 seats per narrowbody. ANAC flammability testing backlogs extend supplier lead times for new cushion formulations.
- Overhead Bins:Stowage compartments engineered from carbon fiber-reinforced thermoplastics to achieve 15-20% weight reduction versus legacy aluminum. Retrofit demand clusters at São Paulo-Guarulhos where LATAM and Gol simultaneously refresh A320ceo and 737NG fleets. Bin expansion programs require structural floor reinforcement that drives concurrent seat track modification.
- Lighting:LED mood and task illumination systems with programmable color temperature for circadian rhythm management.
- Cargo Compartments:Fire-resistant liner panels and restraint netting assemblies certified to FAA Part 25.855 standards.
Seating commands the established base. The steepest expansion runs through overhead bins as weight-driven retrofit accelerates.
End User:
Application context shapes procurement autonomy, with scheduled carriers centralizing fleet decisions while charter and cargo operators delegate to maintenance divisions.
- Commercial Airlines:LATAM, Azul, Gol, Aeroméxico, and Volaris operating narrowbody and widebody fleets under Part 121-equivalent rules. São Paulo and Mexico City corridors dominate interior refresh spending as these carriers densify cabins to capture ancillary revenue from seat selection and extra legroom.
- Charter Operators:Supplemental carriers including corporate shuttle and tour package specialists with mixed-generation fleets. Demand concentrates in Cancún and Rio de Janeiro-Santos Dumont where rapid turnaround requirements prioritize quick-change seat configurations.
- Freight Services:Cargo converters and express package operators modifying passenger aircraft for dedicated freight.
- Private Jets:Business aviation fleet owners specifying custom cabin completions through São Paulo's Embraer Executive Jets and aftermarket modifiers.
Commercial airlines anchor volume commitments. Charter operators are gaining share fastest as post-pandemic corporate travel restructuring expands fractional ownership models.
Material:
Volume scale separates aerospace-grade specifications from commercial alternatives, with certification burden determining viable supplier pools.
- Aluminum:Legacy 2024-T3 and 7075-T6 alloys in seat frames, bin support structures, and galley framing. Demand persists at older 737NG operators in Brazil where electrical system limitations prevent full LED and USB retrofits requiring composite-integrated power distribution.
- Composites:Carbon fiber and glass-reinforced thermoplastics displacing metal in sidewall panels, bin shells, and lavatory modules. Mexican A320neo deliveries from Airbus Mobile drive line-fit composite penetration as EASA REACH substance restrictions harmonize with DGAC certification timelines.
- Fabrics:Wool-nylon blends and synthetic leathers with halogenated flame retardant coatings facing phase-out deadlines.
- Plastics:Injection-molded ABS and polycarbonate components for non-structural trim and decorative finishes.
Aluminum retains the installed base. Composites are climbing the fastest as weight reduction targets intersect with line-fit pre-delivery programs.
Installation Type:
Customer type and timing preference separate OEM-integrated procurement from aftermarket retrofit decision cycles.
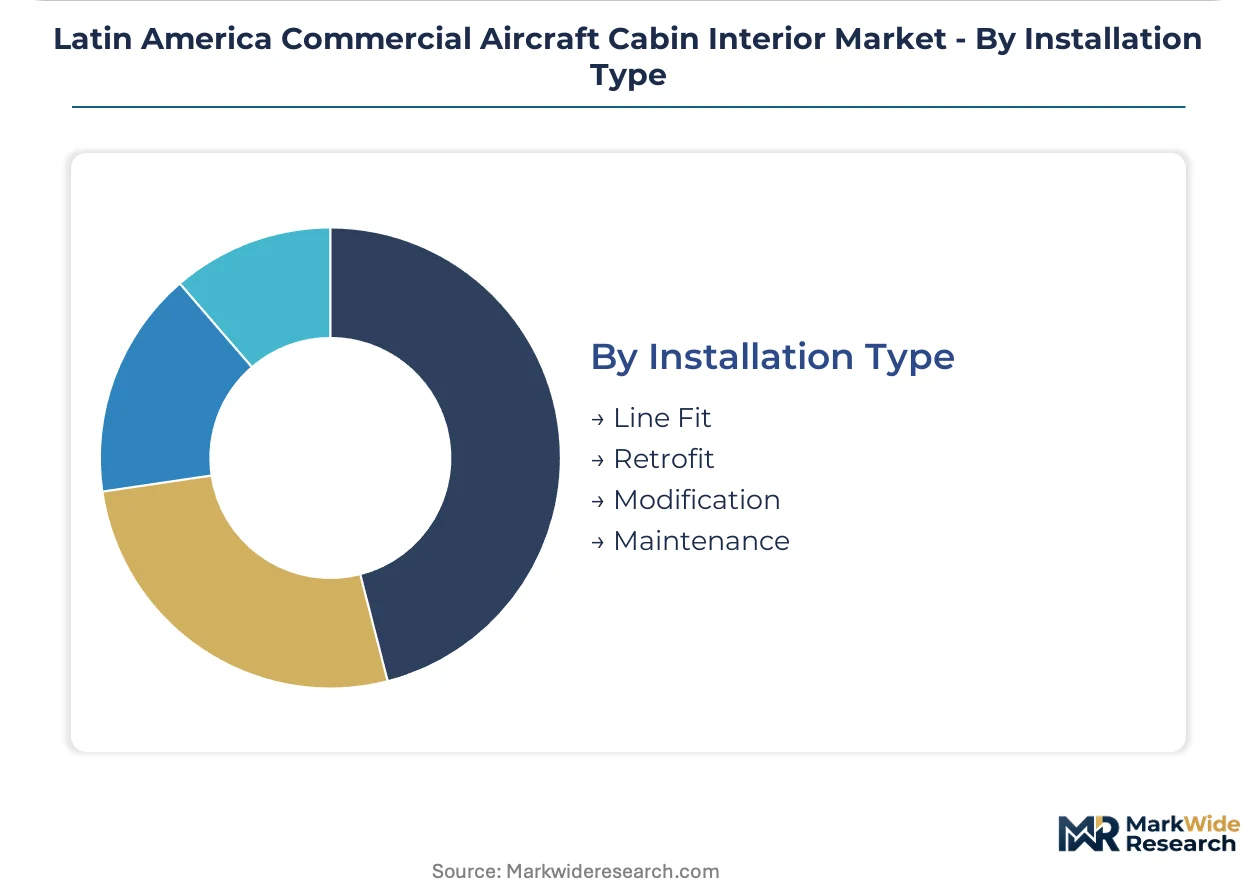
- Line Fit:Factory installation at Airbus São José dos Campos and Mobile assembly centers before aircraft delivery. Aeroméxico and Volaris leverage direct supplier contracts that bypass airline procurement departments entirely, compressing specification finalization to 7-month windows.
- Retrofit:Post-delivery cabin reconfiguration at maintenance, repair, and overhaul facilities. Brazilian low-cost carriers accelerate narrowbody refresh programs at Belo Horizonte and Rio de Janeiro-Galeão to capture ancillary revenue from densified seating.
- Modification:Structural alterations including emergency exit reconfiguration and galley repositioning for fleet harmonization.
- Maintenance:Scheduled replacement of wear components including upholstery, armrest mechanisms, and tray table surfaces.
Retrofit commands current spending concentration. Line fit is gaining share fastest as direct OEM-supplier relationships disintermediate traditional airline procurement structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Guarulhos international corridor anchors Latin America's cabin interior demand, with dedicated air freight links connecting Embraer's São José dos Campos assembly complex to retrofit facilities across the metropolitan region.
Brazil
Azul and Gol drive narrowbody densification programs at Belo Horizonte and Rio de Janeiro-Galeão maintenance bases. ANAC harmonizes fire safety certification with FAA Part 25 standards, compressing supplier approval timelines. São Paulo state's Guarulhos-Campinas industrial corridor concentrates three-quarters of certified seat assembly capacity within 200 kilometers of the international airport.
Mexico
Volaris and Aeroméxico accelerate A320neo and 737 MAX cabin refreshes to capture ancillary revenue from premium seating. DGAC enforces airworthiness directives equivalent to FAA standards for interior material flammability. Mexico City International Airport's maintenance complex anchors the central retrofit cluster, with Guadalajara emerging as a secondary hub for low-cost carrier programs.
Colombia
Avianca's fleet harmonization initiative drives demand for integrated cabin systems at Bogotá's El Dorado maintenance base. The national civil aviation authority applies ICAO-aligned certification protocols for imported interior components. Bogotá's emerging retrofit cluster attracts tier-two seating suppliers seeking proximity to Andean carrier operations previously served from São Paulo.
Chile
LATAM's Santiago hub sustains widebody interior refresh cycles for long-haul Pacific routes connecting to Asia and Europe. The Directorate General of Civil Aeronautication enforces fire-blocking and smoke toxicity standards harmonized with EASA REACH substance restrictions. Santiago's Arturo Merino Benítez International Airport hosts specialized composite panel repair facilities serving southern cone operators.
Argentina
Aerolíneas Argentinas maintains legacy narrowbody fleets requiring periodic upholstery and lighting replacements despite fleet modernization delays. The National Civil Aviation Administration applies ANAC-recognized reciprocal certification for Brazilian-manufactured interior components. Buenos Aires-Ezeiza's maintenance infrastructure supports regional retrofit demand, though political currency constraints compress import timelines for certified materials.
Latin America Commercial Aircraft Cabin Interior Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly. The Latin America commercial aircraft cabin interior market structures around three strategic tiers: full-service integrators delivering complete cabin programs, subsystem specialists anchoring single-product categories, and regional fabricators supplying wear-component replacements. Consolidation pressure intensifies as airlines unbundle procurement from OEM line-fit agreements, forcing component suppliers to deepen integration capabilities or accept margin compression on commoditized segments. Dominant competitive moves include backward integration into thermoplastic manufacturing and strategic partnerships with maintenance divisions seeking single-source retrofit accountability.
Among France-based system integrators, Safran SA occupies the platform tier through combined seating and cabin systems offerings. Diehl Aerospace GmbH, a German GmbH-structured specialist, exemplifies the subsystem archetype in lighting and overhead bin assemblies. Panasonic Avionics Corporation, a US-incorporated entity, represents the connectivity-hardware segment competing on IFE integration. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning across the value chain.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Triumph Group Inc |
| Thompson Aero Seating Ltd |
| Thales Group |
| RECARO Holding GmbH |
| Panasonic Avionics Corporation |
| Raytheon Technologies Corporation |
| Diehl Aerospace GmbH |
| Safran SA |
| Others |
Supply & Pricing Matrix
Brazilian petrochemical feedstock concentration in São Paulo's industrial corridor anchors margin capture at composite panel manufacturers, while downstream seat assemblers absorb volatility through long-term offtake contracts with LATAM and Azul maintenance divisions.
Pricing Analysis
Volume-discount tiering structures separate LATAM and Aeroméxico fleet-wide programs from spot procurement by charter operators and regional carriers. Pricing stratifies across premium, standard, and economy tiers based on ANAC certification grade and after-sales service bundling. Cost compression in slimline seating is intensifying because epoxy resin feedstock fluctuations constitute 35-40% of raw material costs for composite manufacturers. Charter operators exhibit highest price sensitivity due to irregular fleet utilization, while legacy carriers prioritize certification speed over unit cost.
Supply Chain Analysis
Upstream epoxy resin and carbon fiber feedstock supply draws from petrochemical complexes in Brazil, the United States, and Germany. Raw material dependencies center on bisphenol-A derivatives, acrylonitrile precursors, and aerospace-grade thermoplastic resins. Single-source vulnerability concentrates at three certified seat assembly facilities within 200 kilometers of Guarulhos. Distribution runs through OEM-direct channels at Airbus São José dos Campos and Mobile, plus airline maintenance divisions in Belo Horizonte and Mexico City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America commercial aircraft cabin interior market is recovering through narrowbody fleet densification cycles as Brazilian and Mexican low-cost carriers retrofit aging A320ceo and 737NG platforms to capture ancillary revenue.
For Market Incumbents: Insulate certification engineer capacity through captive training partnerships with Brazilian federal universities and ANAC-accredited testing laboratories. Deepen backward integration into thermoplastic stamping infrastructure to offset epoxy resin price volatility. Threat substitution from automotive-crossover manufacturers entering aerospace supply chains demands faster material approval cycles.
For New Entrants and Emerging Players: Colombia's Bogotá-El Dorado maintenance cluster offers underpenetrated retrofit demand as Avianca harmonizes fleets previously served from São Paulo. Target tier-two seating suppliers seeking proximity to Andean carrier operations. Go-to-market angle should emphasize DGAC-ANAC dual certification capability for European-leased aircraft operating Latin American routes.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed seating specialists holding LATAM and Azul retrofit contracts but lacking line-fit OEM relationships. Long-term viability hinges on integration into Airbus and Boeing pre-delivery programs at São José dos Campos and Mobile. Watch for ANAC flammability testing backlog resolution as inflection indicator for new material approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastics | Captures 60% tooling cost reduction for sub-500 unit production runs at regional carriers. |
| ANAC-DGAC Dual Certification Investment | Unlocks European-leased A350 and 787 retrofit contracts requiring EASA REACH compliance. |
| Maintenance Division Partnership | Positions suppliers for 7-month specification windows as Volaris and Gol bypass OEM procurement. |
| Line-Fit Pre-Delivery Program Access | Bypasses airline procurement departments entirely at Airbus São José dos Campos and Mobile. |
| Phosphorus-Based Flame Retardant Transition | Secures upholstery supply continuity ahead of 2026 EASA REACH halogenated compound phase-out. |
Research Methodology
Operator-level perspectives from fleet planning directors, MRO procurement managers, ANAC certification engineers, and cabin systems integrators anchored the qualitative base. Primary interviews combined with secondary validation against ANAC regulatory filings, DGAC airworthiness directives, EASA REACH substance restriction updates, and customs import records for aerospace-grade composites. Bottom-up seat and bin unit forecasts triangulated with top-down airline capex disclosure analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon based on A320neo and 737 MAX delivery trajectories, retrofit cycle compression rates, and ANAC testing capacity expansion. Segmentation dimensions modeled include product type, installation timing, material certification pathway, and operator economics. CAGRs derived from fleet age profiles, densification program announcements, and composite substitution elasticities relative to aluminum legacy platforms.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese thermoplastic suppliers or Gulf-based MRO consolidators would shift outcomes. Cross-checking against airline 10-K fleet plan disclosures and OEM delivery backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Management System Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Global Aircraft Enclosures Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market