
 Emergency Exit Hatch Lightweight Composite Structures Market | 2026-2036
Emergency Exit Hatch Lightweight Composite Structures Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Exit Hatch Lightweight Composite Structures Market Insights
Software-defined predictive maintenance contracts for emergency exit hatch assemblies is expanding the addressable revenue per shipset beyond hardware alone. Collins Aerospace leverages its integrated avionics-service platform to anchor long-term aftermarket agreements with major OEMs. GKN Aerospace competes through specialized thermoplastic welding expertise that sustains lighter-weight hatch architectures. Spirit AeroSystems dominates structural integration programs, while Saab navigates military certification pathways for fighter and transport applications.
Emergency exit hatch lightweight composite structures are load-bearing aeronautical closures fabricated from fiber-reinforced polymer matrices, typically achieving 25-40% weight reduction versus aluminum equivalents while maintaining burst-pressure ratings exceeding 9 psi differential. Carbon fiber composites lead commercial aviation programs due to specific strength advantages, though glass fiber variants occupy rail transit where cost sensitivity outweighs gram-level optimization. Prepreg layup technology controls premium aerospace hatch manufacturing, while resin transfer molding is displacing legacy methods in higher-volume narrow-body contracts where cycle-time compression determines margin pools.
FAA Part 25 certification requirements and EASA CS-25 airworthiness standards mandate flammability, smoke-toxicity, and structural-integrity testing that shapes composite formulation selection and supplier qualification timelines. The EU Green Deal emissions-trading framework and ICAO carbon-offsetting mechanisms are forcing OEMs to prioritize gram-level weight reductions across cabin and emergency systems. Stakeholders must monitor evolving MEE environmental standards in China and dual carbon goals that could redirect composite supply chains toward domestic prepreg sources.
Market Dynamics
Resin transfer molding is consolidating production economics across narrow-body and wide-body programs, compressing cycle times and displacing legacy prepreg layup methods that previously dominated aerospace hatch manufacturing.
Growth Catalysts
- FAA Part 25 Mandates:Weight-reduction requirements for emergency exit systems are accelerating carbon fiber substitution across Boeing and Airbus final assembly lines in the United States and France.
- EU Green Deal Framework:Emissions-trading mechanisms and carbon-offsetting obligations are forcing gram-level optimization priorities into cabin and emergency system procurement specifications.
- Out-of-Autoclave Curing:Advanced oven-based polymerization processes are reducing energy intensity and capital requirements for composite hatch production, expanding supplier participation.
Market Restraints
- Prepreg Carbon Fiber Concentration:Supply of aerospace-grade fiber and resin systems concentrates among Japanese and US chemical conglomerates, creating input cost volatility and allocation risk.
- EASA CS-25 Certification Timelines:Flammability, smoke-toxicity, and burst-pressure testing protocols extend qualification periods to 18-24 months, freezing design iterations and delaying revenue recognition.
- Aluminum-Lithium Alloys:Third-generation metallic formulations offer 8-12% weight reduction with lower unit costs, presenting substitution pressure in cost-sensitive regional jet programs.
Strategic Opportunities
- COMAC C919 Ramp:China's indigenous narrow-body program requires qualified domestic composite hatch suppliers, creating white space for tier-one entrants meeting CAAC certification pathways.
- Thermoplastic Welding Convergence:Automated fiber placement combined with induction welding enables recyclable, repairable hatch architectures without adhesive bonding, opening aftermarket service models.
- Rail Transit Expansion:High-speed rail programs in France, Germany, and Japan specify fire-resistant glass fiber hatches where cost sensitivity outweighs aerospace-grade performance requirements.
Industry Challenges
- Composite Repair Certification:NDT technician shortages and specialized training requirements for thermoset damage assessment are constraining MRO capacity expansion.
- Dual-Source Qualification Burden:OEMs require redundant qualified suppliers for each hatch variant, doubling certification investment without proportional volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Exit Hatch Lightweight Composite Structures Market |
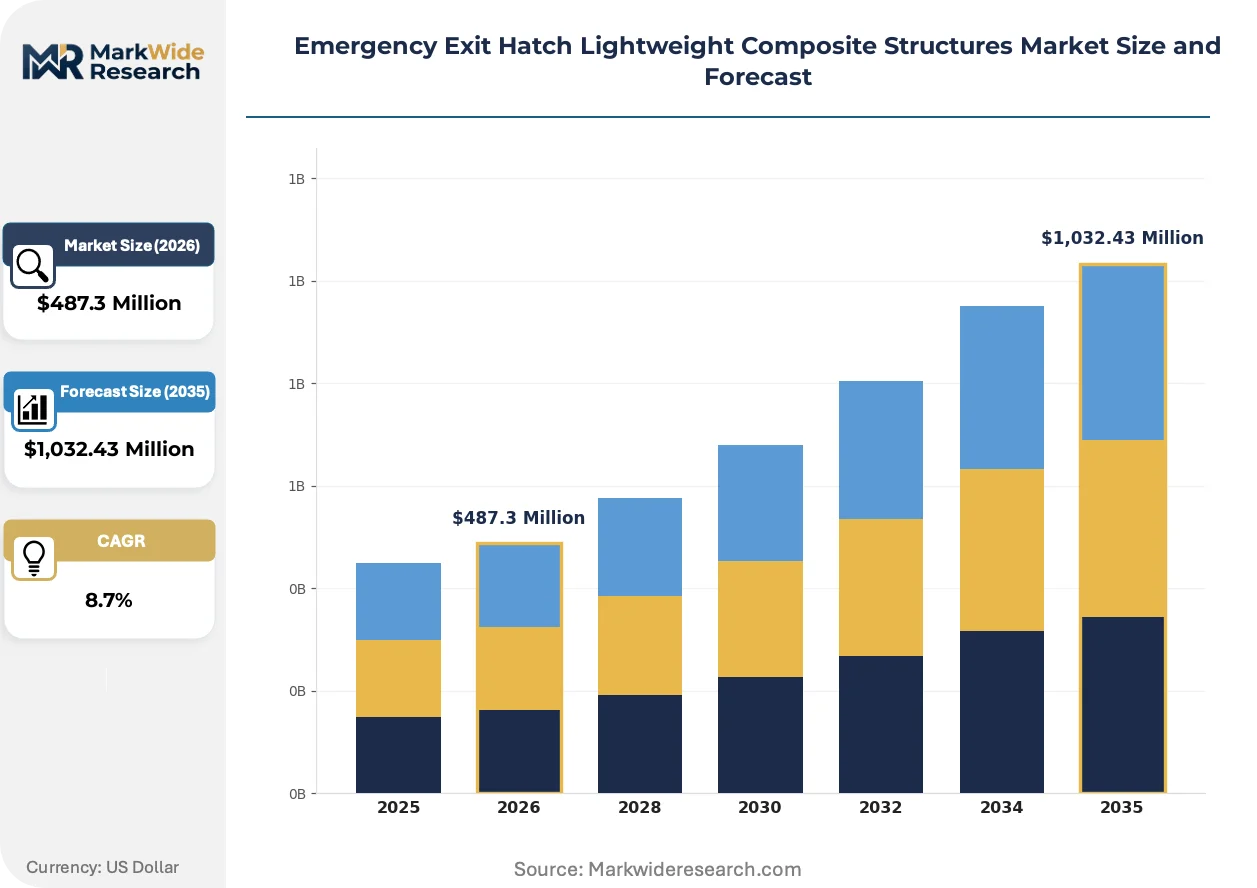
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
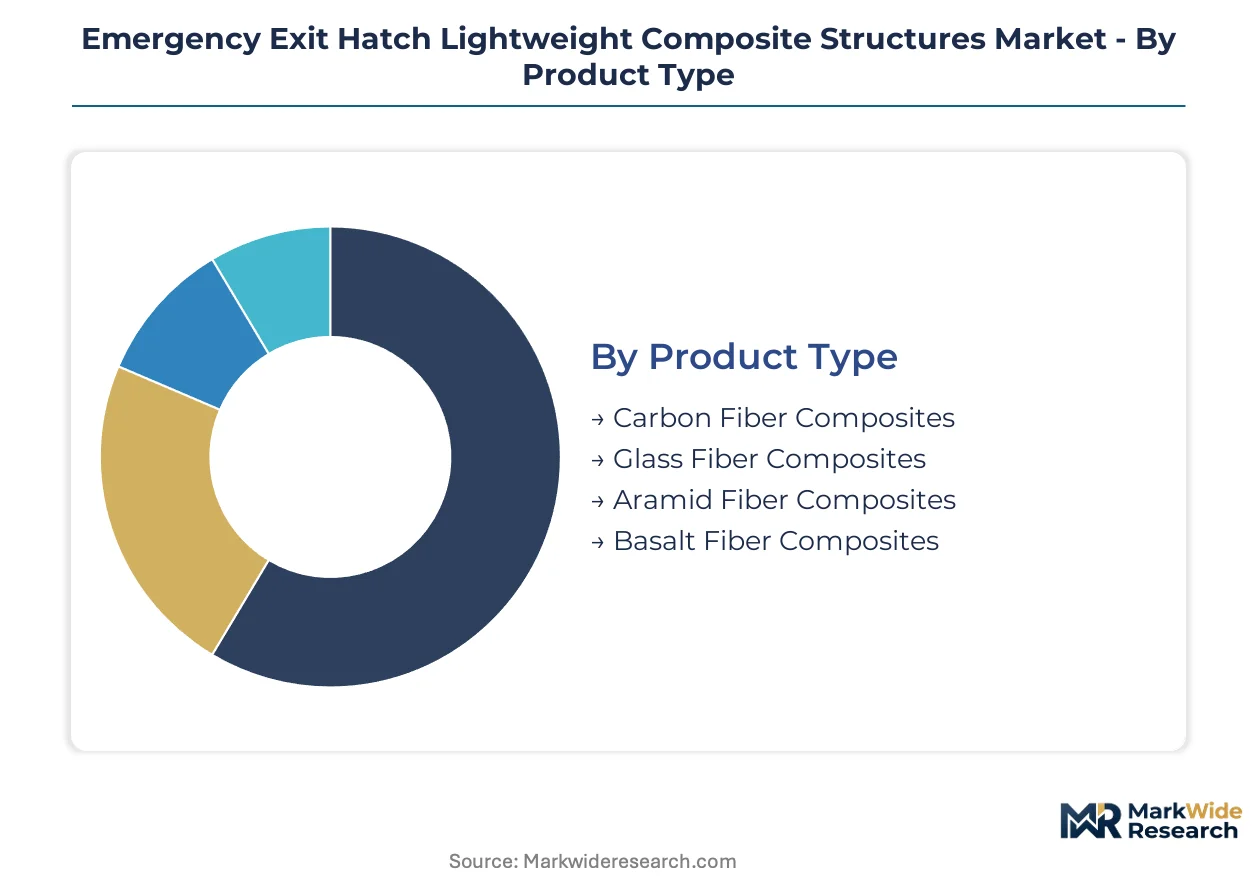
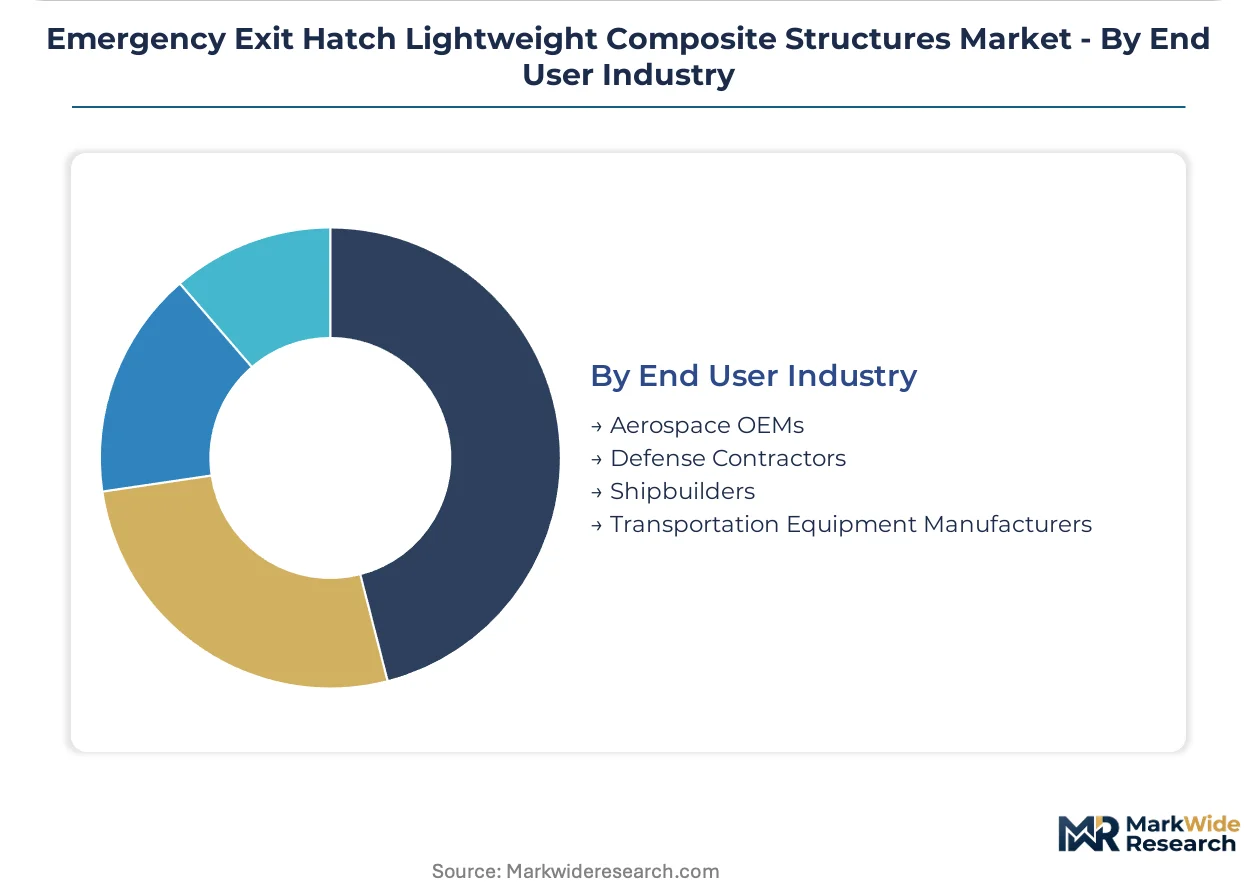
| Segmentation | Product Type: Carbon Fiber Composites, Glass Fiber Composites, Aramid Fiber Composites, Basalt Fiber Composites Application: Commercial Aircraft, Rail Transit Vehicles, Marine Vessels, Military Aircraft Technology: Resin Transfer Molding, Vacuum Infusion, Prepreg Layup, Pultrusion End User Industry: Aerospace OEMs, Defense Contractors, Shipbuilders, Transportation Equipment Manufacturers |
| Companies Covered | Collins Aerospace, Saab, Latécoère, Spirit AeroSystems, GKN Aerospace, Ducommun, Dynamatic Technologies, Astronics PECO, Sonaca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Exit Hatch Lightweight Composite Structures Market Trends and Innovations
Automated manufacturing systems and predictive service architectures are restructuring how composite hatch value is captured, with hardware margins compressing while data-enabled aftermarket contracts expand.
Thermoplastic composite welding is consolidating as the dominant joining methodology for next-generation hatch architectures. Airbus and Boeing narrow-body programs are specifying welded thermoplastic frames to eliminate fastener weight and corrosion pathways. This consolidation is enabling single-piece structural integration that previously required multi-component assembly.
EASA CS-25 Amendment 25-157 introduced revised flammability testing protocols for thermoplastic materials in pressurized compartments. European OEMs are reformulating resin matrices to meet smoke-density thresholds without sacrificing mechanical performance. Wide-body programs with extended certification cycles are absorbing the bulk of compliance costs and timeline extensions.
Airline procurement departments are unbundling hardware acquisition from long-term airworthiness support, separating shipset purchases from predictive maintenance subscriptions. Tier-one suppliers are responding with sensor-integrated hatch assemblies that transmit structural health data. This behavioral shift is most pronounced among US-based network carriers with centralized fleet management platforms.
Emergency Exit Hatch Lightweight Composite Structures Market Segmentation
Composite hatch procurement decisions cascade through four interlocking dimensions: material selection governs certification pathways, application context determines load specifications, manufacturing technology sets unit economics, and end-user integration requirements shape supplier qualification depth. Misalignment across any dimension triggers 18-24 month redesign cycles.
Product Type:
Buyers prioritize specific strength-to-weight ratios against flammability certification costs when selecting fiber systems for emergency closure applications.
- Carbon Fiber Composites:PAN-based and pitch-derived carbon fiber systems achieve 25-40% weight reduction versus aluminum equivalents while maintaining burst-pressure ratings exceeding 9 psi differential. Boeing 737 MAX and Airbus A320neo final assembly lines in the United States and France specify these formulations to meet FAA Part 25 and EASA CS-25 mandates.
- Glass Fiber Composites:E-glass and S-glass variants offer fire-resistant performance at 40-60% lower material cost than carbon fiber, dominating rail transit hatch specifications where cost sensitivity outweighs gram-level optimization. French and German high-speed rail programs source these formulations from domestic composite processors.
- Aramid Fiber Composites:Kevlar and Twaron-based systems deliver impact absorption and ballistic protection for military aircraft applications requiring fragmentation resistance.
- Basalt Fiber Composites:Volcanic rock-derived fibers provide intermediate mechanical properties between glass and carbon with superior chemical resistance for marine environments.
Volume sits with carbon fiber composites; growth tilts toward glass fiber composites.
Application:
Regulatory jurisdiction and operational duty cycles segment demand across mobility platforms with divergent certification timelines and performance thresholds.
- Commercial Aircraft:Narrow-body and wide-body programs require pressurized hatch assemblies meeting 9 psi differential burst ratings with 25-year service life. FAA Part 25 and EASA CS-25 flammability protocols drive carbon fiber prepreg selection for overwing and Type I/III exit configurations.
- Rail Transit Vehicles:EN 45545-2 fire safety standards govern glass fiber composite hatches for high-speed trains in France, Germany, and Japan where smoke toxicity thresholds override weight minimization priorities.
- Marine Vessels:SOLAS regulations and classification society rules shape hatch specifications for cruise ships and naval craft requiring corrosion resistance in salt-air environments.
- Military Aircraft:MIL-STD-810 environmental testing and STANAG ballistic requirements drive aramid-carbon hybrid architectures for fighter and transport platforms.
Procurement scale concentrates in commercial aircraft; steepest expansion trajectory appears in rail transit.
Technology:
Capital intensity and cycle-time compression determine process selection across production volume tiers and geometric complexity requirements.
- Resin Transfer Molding:Closed-mold injection processes consolidate fiber preforms with thermoset resins under controlled pressure and temperature, enabling 30-50% cycle-time reduction versus prepreg methods. Boeing and Airbus narrow-body programs are displacing legacy fabrication with RTM for higher-volume hatch variants.
- Prepreg Layup:Pre-impregnated carbon fiber sheets with controlled resin content deliver aerospace-grade laminate quality for complex-curvature hatches requiring precise fiber orientation. Wide-body programs with lower production rates absorb the 15-20% cost premium for autoclave curing.
- Vacuum Infusion:Single-sided mold processes with vacuum-driven resin flow reduce tooling investment for marine and rail applications with moderate geometric complexity.
- Pultrusion:Continuous pulling processes manufacture constant-cross-section profiles for structural frames and edge reinforcements in high-volume rail hatch programs.
Technology mix is shifting: RTM gains share in aerospace; vacuum infusion dominates marine.
End User Industry:
Integration depth and certification ownership distinguish customer types with divergent supplier relationship models and contract structures.
- Aerospace OEMs:Boeing, Airbus, and COMAC control tier-one supplier qualification and airworthiness certification for shipset-integrated hatch assemblies, requiring dual-source redundancy and predictive maintenance data rights.
- Defense Contractors:Lockheed Martin, Saab, and BAE Systems navigate military-specific STANAG and MIL-STD pathways with extended development cycles and classified performance requirements.
- Shipbuilders:Fincantieri, Meyer Werft, and Hyundai Heavy Industries specify SOLAS-compliant hatches with integrated sealing systems for cruise and naval newbuild programs.
- Transportation Equipment Manufacturers:Alstom, Siemens Mobility, and CRRC integrate fire-rated hatches into complete rail vehicle architectures with EN 45545-2 compliance documentation.
Contract value concentrates with aerospace OEMs; qualification activity is expanding fastest among transportation equipment manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in three nations with major final assembly lines, while certification-driven demand spreads across additional markets with indigenous aircraft programs. The United States and France anchor aerospace-grade composite hatch manufacturing through Boeing and Airbus supply chains. China's COMAC C919 program is redirecting procurement toward domestic qualification pathways.
United States
FAA Part 25 mandates drive carbon fiber hatch procurement across Boeing 737 MAX and 777X programs in Washington and South Carolina. The FAA's updated flammability testing protocols extend qualification timelines for new resin formulations. Wichita, Kansas hosts tier-one structural integration facilities supplying shipset-integrated assemblies to multiple OEM platforms.
France
Airbus A320neo and A350 final assembly lines in Toulouse anchor European demand for aerospace-grade composite hatches. EASA CS-25 Amendment 25-157 revised thermoplastic flammability thresholds, forcing reformulation of resin matrices. The Nantes industrial cluster specializes in complex-curvature hatch components using automated fiber placement systems.
China
COMAC C919 narrow-body production in Shanghai requires qualified domestic composite hatch suppliers meeting CAAC certification pathways. MEE environmental standards and dual carbon goals redirect supply chains toward domestic prepreg sources. Xi'an and Chengdu aerospace clusters are developing thermoplastic welding capabilities for indigenous programs.
Germany
Airbus Hamburg final assembly lines and rail transit equipment manufacturers drive glass fiber hatch demand under EU Green Deal procurement specifications. EN 45545-2 fire safety standards govern high-speed rail applications where cost sensitivity outweighs gram-level optimization. Bavaria's composite processing centers supply fire-rated assemblies to Alstom and Siemens Mobility programs.
Japan
Toray and Teijin supply aerospace-grade carbon fiber prepreg to Boeing and Airbus programs, with domestic content requirements shaping tier-two sourcing. METI industrial policy supports development of out-of-autoclave curing technologies to reduce energy intensity. Nagoya's aerospace cluster maintains specialized facilities for complex laminate qualification under JIS standards.
Emergency Exit Hatch Lightweight Composite Structures Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure. Tier-one integrators dominate shipset contracts through airworthiness certification ownership and predictive maintenance data rights. Tier-two specialists concentrate on specific manufacturing processes or military qualification pathways. Consolidation pressures favor scale-driven acquisitions and strategic partnerships over greenfield capacity expansion.
Within the integrated systems tier, Collins Aerospace and Spirit AeroSystems exemplify platform-anchored suppliers with aftermarket service architectures. GKN Aerospace occupies a position among process specialists leveraging thermoplastic welding expertise. Saab represents the defense-qualified archetype navigating military-specific STANAG certification pathways. These three anchors illustrate how competitive positioning stratifies across certification ownership, manufacturing technology, and end-use segmentation.
| Leading Market Players |
|---|
| Collins Aerospace |
| Saab |
| Latécoère |
| Spirit AeroSystems |
| GKN Aerospace |
| Ducommun |
| Dynamatic Technologies |
| Astronics PECO |
| Sonaca |
| Others |
Pricing and Supply Chain Analysis
FAA Part 25 weight-reduction mandates are forcing Boeing and Airbus procurement teams toward carbon fiber hatch architectures, compelling tier-one suppliers to absorb resin reformulation costs and compress cycle times through resin transfer molding adoption. This specification-driven demand compression is reshaping how composite fabricators price shipset contracts and allocate capital across curing technologies.
Pricing Analysis
Margin tightening in aerospace-grade carbon fiber hatch tiers reflects EASA CS-25 Amendment 25-157 flammability compliance costs and extended qualification timelines stretching to 24 months. Contract structures stratify across FAA-certified premium tiers, EASA-equivalent standard tiers, and rail-transit economy tiers where EN 45545-2 fire ratings substitute for gram-level optimization. Cost-down pressure on narrow-body programs accelerates as COMAC C919 procurement teams demand domestic qualification pathways without volume guarantees. Rail transit buyers in France and Germany exhibit highest price sensitivity, accepting glass fiber performance tradeoffs for 40-60% material cost reduction versus carbon fiber equivalents.
Supply Chain Analysis
Certified NDT technician shortages in Wichita, Kansas and Toulouse, France are constraining MRO capacity expansion for thermoset damage assessment and repair authorization. Aerospace-grade carbon fiber prepreg concentrates in Japan, the United States, and China, drawing from Toray, Hexcel, and domestic Chinese chemical conglomerates for PAN-based fiber and specialized resin systems. Single-source vulnerability persists in aerospace-grade thermoplastic resin formulations qualified for induction welding processes. Distribution runs through tier-one structural integrators holding airworthiness certification ownership and predictive maintenance data rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emergency exit hatch composite structures market sits in a manufacturing-technology transition, with resin transfer molding displacing legacy prepreg layup methods across narrow-body programs and thermoplastic welding enabling recyclable architectures without adhesive bonding.
For Market Incumbents: To counter aluminum-lithium alloy substitution pressure in regional jet programs, tier-one suppliers should deepen backward integration into aerospace-grade thermoplastic resin formulation and expand out-of-autoclave curing capacity in South Carolina and Hamburg. Certification investment in CAAC pathways for COMAC C919 variants creates defensive moats against domestic Chinese entrants. For New Entrants and Emerging Players: Launch via specialized thermoplastic welding expertise targeting Airbus and Boeing narrow-body programs specifying welded frame architectures. White space concentrates in domestic Chinese qualification for C919 shipset contracts and fire-rated glass fiber hatch production for German and Japanese high-speed rail programs under EN 45545-2 standards. For Investors and Strategic Acquirers: The window for entry favors process specialists with thermoplastic welding capabilities and military STANAG certification pathways. Acquisition targets should demonstrate established FAA Part 25 or EASA CS-25 qualification ownership with sensor-integrated hatch architectures enabling predictive maintenance data monetization. Watch for EASA flammability protocol amendments as inflection indicators for resin matrix reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Welding Capability Investment | Airbus A320neo and Boeing 737 MAX programs specify welded frames to eliminate fastener weight and corrosion pathways. |
| CAAC Certification Pathway Development | COMAC C919 ramp requires qualified domestic suppliers meeting China's MEE environmental standards and dual carbon goals. |
| Predictive Maintenance Platform Integration | Collins Aerospace leverages sensor-integrated hatch assemblies to anchor long-term aftermarket agreements with US network carriers. |
| Out-of-Autoclave Curing Capacity Expansion | Advanced oven-based polymerization reduces energy intensity and capital requirements, expanding supplier participation in narrow-body contracts. |
| Rail Transit Fire-Rated Hatch Qualification | Alstom and Siemens Mobility programs in France and Germany specify EN 45545-2 compliant glass fiber architectures. |
Research Methodology
SEC 10-K filings, EASA certification databases, and FAA airworthiness directives formed the secondary backbone of this analysis, cross-referenced with primary interviews involving composite manufacturing engineers, tier-one supplier procurement directors, airline fleet management executives, and MRO facility operations managers. Bottom-up shipset volume estimates from Boeing, Airbus, and COMAC final assembly lines were triangulated against top-down composite materials demand data from Japanese and US chemical conglomerates.
Historical trendline analysis of carbon fiber prepreg pricing and resin transfer molding adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include fiber type, application platform, manufacturing technology, and end-user integration depth. CAGRs were derived from production rate forecasts for narrow-body and wide-body programs, incorporating EASA CS-25 flammability protocol amendments and EU Green Deal procurement specifications as demand modifiers.
Regulatory protocol revisions, aerospace-grade fiber supply allocation disruptions, and thermoplastic welding qualification delays are the dominant revision risks to forecast assumptions. Material deviation in these triggers warrants pause and re-evaluation of capacity investment timelines and supplier qualification strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market