
 Global Aircraft Enclosures Market | 2026-2036
Global Aircraft Enclosures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Enclosures Market Foresight
Multi-source procurement for critical structural housings is realigning how tier-one suppliers manage fabrication risk across their vendor bases. Collins Aerospace leverages composite manufacturing scale to sustain dominance in avionics housings for commercial platforms. Honeywell International Inc. anchors its position through backward integration into thermoplastic forming processes. TE Connectivity competes on interconnect-integrated enclosure designs that reduce wiring complexity.
Aircraft enclosures are sealed structural housings and protective covers, typically fabricated from aluminum alloys, carbon fiber composites, or high-performance thermoplastics, engineered to shield avionics, powerplants, and flight-critical systems from aerodynamic loads, thermal cycling, and electromagnetic interference. Their primary purpose is maintaining system reliability while contributing to overall airframe weight reduction targets. Cockpit enclosures command premium pricing due to bird-strike certification and optical clarity requirements. Engine covers represent the fastest-growing product category as OEMs pursue acoustic attenuation and quick-release maintenance access. Composite material segments capture expanding share as automated fiber placement reduces unit costs.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern flammability, smoke density, and structural integrity requirements for all civil aircraft enclosures. EPA regulations on hexavalent chromium surface treatments are forcing suppliers to convert to trivalent chrome or plasma electrolytic oxidation finishes. Military procurement through MIL-STD-810 further segments demand for ruggedized housings in defense applications. Stakeholders must monitor how emerging sustainable aviation fuel compatibility requirements reshape thermal management specifications in nacelle and engine cover designs.
Market Dynamics
Automated fiber placement is compressing composite enclosure unit costs while FAA Part 25 fire-resistance mandates tighten material specifications, forcing simultaneous investment in new fabrication and new chemistries across supplier bases.
Growth Catalysts
- FAA Airworthiness Directives:Updated flammability standards for thermoplastic housings are accelerating replacement cycles across aging narrowbody fleets.
- Acoustic Attenuation Mandates:Stage 5 noise regulations from ICAO member states are driving engine cover redesigns with integrated sound-dampening architectures.
- Quick-Release Maintenance Access:Airlines are specifying tool-less engine cowl designs to reduce turnaround times, pulling demand toward modular composite solutions.
Market Restraints
- Hexavalent Chromium Phase-Out:EPA surface treatment restrictions are forcing costly conversion to plasma electrolytic oxidation or trivalent chrome finishes.
- Prepreg Supply Concentration:Toray, Hexcel, and Solvay control 70% of aerospace-grade carbon fiber supply, creating input vulnerability for tier-two fabricators.
- Bird-Strike Certification Burden:Cockpit transparency enclosures face extended FAA structural integrity testing that extends development timelines.
Strategic Opportunities
- Urban Air Mobility Platforms:eVTOL manufacturers in Germany and China are sourcing lightweight EMI-shielded avionics housings without legacy certification baggage.
- Sustainable Aviation Fuel Compatibility:Thermal management specifications for nacelle designs are being rewritten to accommodate higher combustion temperatures.
- Interconnect-Integrated Architectures:TE Connectivity's approach to combining power distribution with structural housings is creating a template for reduced-wiring designs.
Industry Challenges
- Automated Fiber Placement Technician Shortage:Aerospace composites manufacturing lacks sufficient trained operators for multi-axis AFP systems.
- Dual Certification Burden:Suppliers must simultaneously satisfy FAA Part 25 and EASA CS-25 testing protocols, duplicating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Enclosures Market |
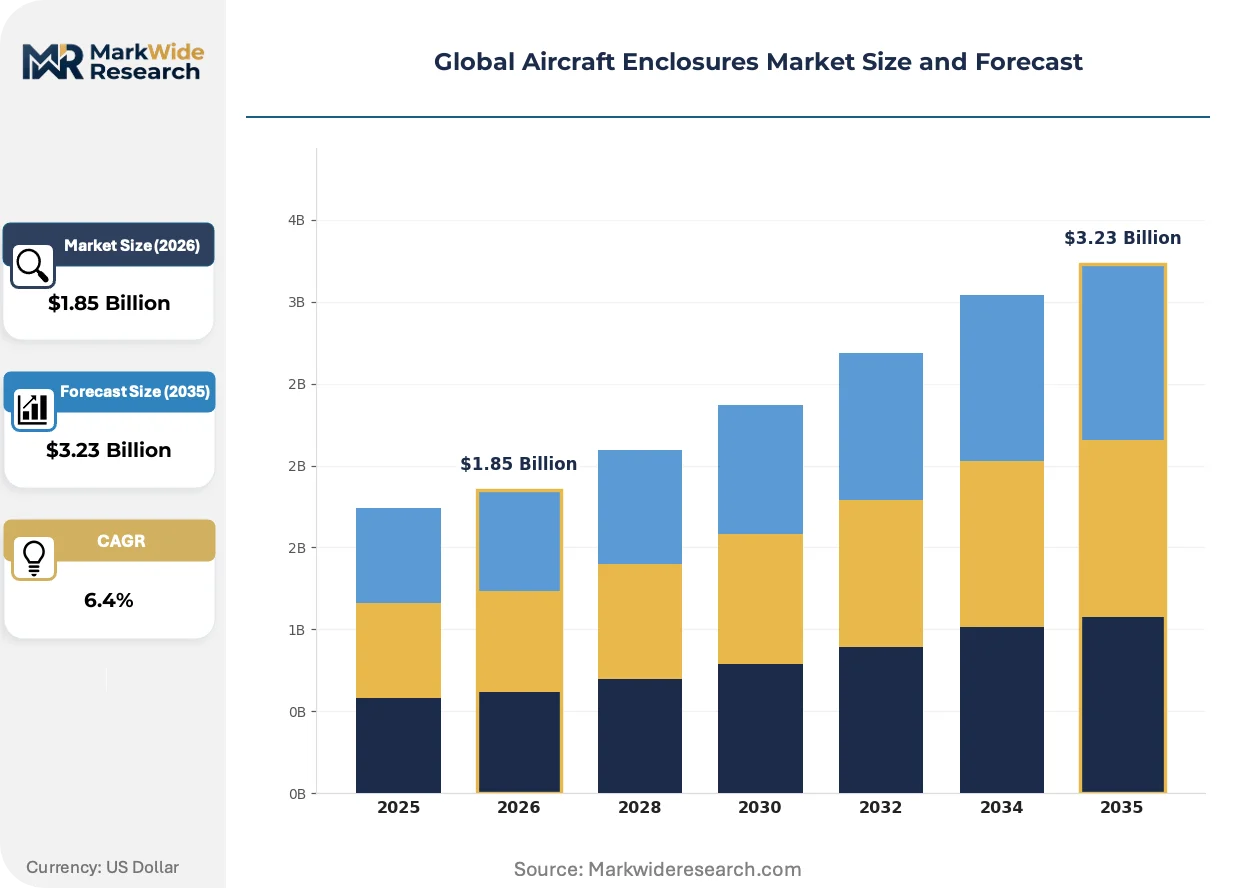
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cockpit Enclosures, Engine Covers, Landing Gear Covers, Avionics Housings, Cargo Bays Material: Composite, Aluminum Alloy, Titanium Alloy, Thermoplastics, Carbon Fiber Application: Commercial Aviation, Military Aviation, Business Jets, Unmanned Aerial Vehicles, Aero Structures End User: Aircraft Manufacturers, Maintenance Providers, Airframe Assemblers, Defense Contractors, Specialty Fabricators |
| Companies Covered | Collins Aerospace, Honeywell International Inc., TE Connectivity, Ducommun Incorporated, Amphenol Corporation, Thales Group, Safran SA, Liebherr Group, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Enclosures Market Shifts & Advancements
Material substitution and regulatory stringency are converging to reshape fabrication economics. Suppliers must now optimize for weight, fire resistance, and electromagnetic shielding simultaneously.
Thermoplastic composites are absorbing structural loads previously assigned to aluminum alloys in avionics housings. Tier-one integrators are specifying PEEK and PPS matrices for their weldability and damage tolerance. This shift is absorbing margin pressure from raw material volatility by enabling scrap recycling and automated welding versus mechanical fastening.
EASA's tightened CS-25 Appendix F flammability testing now requires 60-second vertical burn resistance for all electrical system enclosures. European suppliers are reformulating resin systems with phosphorus-based intumescent additives. Cockpit subsystems are most affected, with German and French integrators accelerating qualification of ceramic-fiber-reinforced alternatives.
Airline procurement departments are consolidating vendor lists around full-service enclosure suppliers capable of design-through-MRO support. Long-term service agreements are displacing transactional component purchases for nacelle and thrust reverser covers. This consolidation is most visible in United States narrowbody fleet renewals, where Boeing's tier-one partners now specify 15-year total cost of ownership contracts.
Global Aircraft Enclosures Market Segmentation
Aircraft enclosure procurement fragments across four structural dimensions, each carrying distinct capital requirements and certification burdens. Understanding these splits reveals where supplier margins concentrate and where fabrication complexity drives vendor consolidation.
Product Type:
Capital intensity peaks in segments requiring multi-axis automated fiber placement and extended FAA structural integrity testing.
- Engine Covers:Large-format composite structures integrate acoustic attenuation cores and quick-release latch mechanisms. Boeing and Airbus narrowbody programs in the United States and Germany are pulling demand toward modular designs that reduce line-replaceable unit turnaround times.
- Cockpit Enclosures:Laminated transparency assemblies must satisfy bird-strike certification and optical clarity specifications under EASA CS-25 Appendix F. German and French integrators face extended development timelines due to dual FAA-EASA validation protocols for windshield and canopy architectures.
- Landing Gear Covers:Aerodynamic fairings fabricated from hybrid aluminum-composite sandwiches.
- Avionics Housings:EMI-shielded enclosures for flight-critical electronics.
- Cargo Bays:Pressurized compartment linings with fire-resistant surface treatments.
Engine covers absorb the bulk of installed capacity; cockpit enclosures are expanding most quickly due to fleet renewal cycles.
Material:
Raw material selection determines scrap rates, recycling economics, and compliance with EPA hexavalent chromium restrictions.
- Composite:Automated fiber placement of carbon fiber prepreg enables complex geometries with 20-30% weight reduction versus metallic alternatives. United States-based tier-one suppliers leverage in-house AFP capacity to capture Boeing next-generation narrowbody contracts.
- Thermoplastics:PEEK and PPS matrices offer weldability and damage tolerance for avionics housings. European suppliers reformulate resin systems with phosphorus-based intumescent additives to meet tightened EASA flammability mandates.
- Aluminum Alloy:Legacy structural housings facing substitution pressure from composite alternatives.
- Titanium Alloy:High-temperature engine zone applications requiring plasma electrolytic oxidation finishes.
- Carbon Fiber:Discrete reinforcement category for hybrid material stacks.
Composite material demand dominates current procurement volumes; thermoplastics are climbing the fastest as welding automation displaces mechanical fastening.
Application:
End-use concentration shapes certification pathway selection and aftermarket service contract structures.
- Commercial Aviation:Narrowbody and widebody fleet renewals drive nacelle and thrust reverser cover demand. United States airline procurement departments are consolidating vendor lists around full-service suppliers capable of 15-year total cost of ownership agreements.
- Military Aviation:MIL-STD-810 ruggedization requirements segment demand for defense-specific housings. United States defense contractors specify EMI-hardened avionics enclosures with extended operational temperature ranges.
- Business Jets:Low-volume, high-customization cabin and cockpit enclosures.
- Unmanned Aerial Vehicles:Lightweight composite housings for surveillance and cargo platforms.
- Aero Structures:Secondary structural fairings and access panels.
Commercial aviation commands the largest share of fabrication capacity; unmanned aerial vehicles are gaining share fastest as defense and logistics applications multiply.
End User:
Customer type determines design authority retention and long-term service revenue capture.
- Aircraft Manufacturers:Boeing, Airbus, and Embraer retain design authority for primary structural enclosures, sourcing through tier-one integrators with backward integration into thermoplastic forming.
- Maintenance Providers:Airlines and MRO operators specify replacement cockpit transparencies and engine cowls under performance-based logistics contracts. United States carriers are accelerating enclosure replacement cycles as FAA airworthiness directives tighten flammability standards.
- Airframe Assemblers:Tier-one partners managing subsystem integration for OEM programs.
- Defense Contractors:Military-specific procurement with MIL-STD certification requirements.
- Specialty Fabricators:Niche suppliers for custom or low-volume enclosure variants.
Aircraft manufacturers anchor the majority of forward production; maintenance providers are expanding fastest as fleet age drives replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States airline procurement departments concentrate the bulk of forward demand as Boeing and its tier-one partners anchor narrowbody fleet renewals. FAA airworthiness directives are accelerating replacement cycles across aging commercial fleets. Regulatory stringency varies by jurisdiction, reshaping where suppliers locate fabrication capacity.
United States
Boeing's next-generation narrowbody programs pull composite enclosure demand toward Seattle and Charleston manufacturing clusters. FAA Part 25 fire-resistance mandates tighten material specifications for thermoplastic housings. Wichita, Kansas hosts a dense concentration of tier-two fabricators converting to plasma electrolytic oxidation finishes to satisfy EPA hexavalent chromium restrictions.
Germany
Airbus narrowbody and widebody assembly in Hamburg drives nacelle and thrust reverser cover procurement volumes. EASA CS-25 Appendix F flammability testing now requires 60-second vertical burn resistance for electrical system enclosures. Bavarian suppliers around Munich are reformulating PEEK and PPS resin systems with phosphorus-based intumescent additives to meet tightened standards.
France
Safran and Thales anchor domestic demand for avionics housings and engine zone enclosures across Toulouse and Paris industrial corridors. EASA certification frameworks govern structural integrity requirements for cockpit transparency assemblies. The Bordeaux cluster specializes in ceramic-fiber-reinforced alternatives for bird-strike-certified windshield architectures.
China
COMAC C919 fleet ramp-up generates procurement pull for lightweight EMI-shielded avionics housings. MIIT and CAAC certification pathways are converging toward FAA-EASA equivalence for export-bound components. Xi'an and Shanghai manufacturing zones concentrate automated fiber placement capacity for composite nacelle structures.
United Kingdom
Rolls-Royce engine programs sustain demand for high-temperature titanium alloy enclosures in Derby and Bristol supply chains. UK CAA alignment with EASA CS-25 governs flammability and smoke density standards. The Southwest England cluster around Yeovil maintains specialized capacity for military-grade ruggedized housings under MIL-STD-810 specifications.
Global Aircraft Enclosures Market Competitive Landscape
Backward integration into thermoplastic forming processes dominates the current landscape as tier-one suppliers absorb margin pressure from raw material volatility. The vendor base concentrates around full-service integrators capable of design-through-MRO support, displacing transactional component purchases. Three archetypes define competitive positioning: aerospace conglomerates with captive composite manufacturing, specialized interconnect-integrated housing designers, and defense-focused ruggedization specialists. M&A activity and 15-year total cost of ownership contracting represent the primary competitive vectors reshaping supplier relationships.
Among aerospace conglomerates, Collins Aerospace and Honeywell International Inc. exemplify the backward-integrated archetype, while TE Connectivity occupies a distinct position on interconnect-integrated architectures. These three entities anchor the premium tier where design authority retention and long-term service revenue capture determine competitive outcomes. Their geographic footprints span United States industrial clusters with fabrication capacity aligned to Boeing and Airbus final assembly lines.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| TE Connectivity |
| Ducommun Incorporated |
| Amphenol Corporation |
| Thales Group |
| Safran SA |
| Liebherr Group |
| General Dynamics Corporation |
| Others |
Supply & Pricing Matrix
FAA airworthiness directives mandating 60-second vertical burn resistance for electrical system enclosures are compressing supplier margins while forcing qualification investments that smaller fabricators cannot absorb. Tier-one integrators exploit this specification tightening to consolidate vendor lists around full-service partners capable of design-through-MRO support, shifting contract structures toward 15-year total cost of ownership agreements that embed aftermarket revenue.
Pricing Analysis
Volume concentration in narrowbody engine covers and nacelle structures operates on thinner margins than cockpit transparency assemblies where bird-strike certification creates scarcity rents. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales bundling depth. Cost compression in thermoplastic avionics housings is intensifying because EPA hexavalent chromium restrictions force expensive surface treatment conversions. Maintenance providers exhibit highest price sensitivity due to performance-based logistics contract structures, while aircraft manufacturers retain leverage through captive design authority.
Supply Chain Analysis
Multi-source procurement mandates from Boeing and Airbus tier-one partners require dual qualification of automated fiber placement suppliers, fragmenting order books across United States, Germany, and China manufacturing clusters. Aerospace-grade carbon fiber prepreg draws from Toray, Hexcel, and Solvay concentration in Japan and United States, creating input vulnerability for tier-two fabricators. Single-source vulnerability in PEEK resin supply chains threatens thermoplastic housing production schedules. Distribution runs through OEM-directed tier-one integrators with backward integration into composite forming, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EASA CS-25 Appendix F flammability mandates erect barrier-to-entry moats favoring incumbent suppliers with amortized certification infrastructure.
For Market Incumbents: Deepen captive thermoplastic welding capacity to capture margin erosion from mechanical fastening elimination. Consolidate tier-two fabricator relationships through 15-year service agreements before EPA surface treatment conversions accelerate supplier attrition. Threat substitution from Chinese automated fiber placement capacity requires preemptive capacity lock-in with Boeing Charleston and Airbus Hamburg final assembly lines. For New Entrants and Emerging Players: Automated fiber placement technician training platforms offer a technology-first wedge into the capacity bottleneck constraining tier-two supplier expansion. Target unmanned aerial vehicle avionics housings in Germany and China where legacy certification baggage is absent and EMI-shielding specifications remain fluid. Go-to-market through eVTOL original equipment manufacturers seeking lightweight structural solutions without FAA-EASA dual validation burdens. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with in-house AFP capacity and existing EASA qualification infrastructure. Long-term viability hinges on capturing aftermarket replacement cycles as fleet age drives cockpit transparency and engine cowl demand. Watch automated fiber placement labor pool expansion as the inflection signal for tier-two supplier viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermoplastic Forming | Captures margin compression from PEEK resin volatility for Honeywell-tier suppliers. |
| Dual Certification Investment | Enables access to Boeing Seattle and Airbus Hamburg procurement pools simultaneously. |
| Automated Fiber Placement Capacity Expansion | Addresses technician shortage constraining composite nacelle output for narrowbody programs. |
| Plasma Electrolytic Oxidation Conversion | Satisfies EPA hexavalent chromium phase-out for Wichita-based tier-two fabricators. |
| Interconnect-Integrated Architecture Development | Reduces wiring complexity for TE Connectivity-tier avionics housing designs. |
Research Methodology
Document review covered FAA airworthiness directive filings, EASA certification databases, and EPA surface treatment regulations, complemented by interviews with tier-one supplier procurement directors, composite manufacturing engineers, and MRO contract managers. Secondary validation drew from SEC 10-K disclosures of aerospace conglomerates, trade customs data for carbon fiber prepreg imports, and industry association capacity surveys. Bottom-up fabrication capacity estimates triangulated against top-down OEM procurement forecasts.
Historical production volumes for narrowbody and widebody platforms cross-referenced against expert panel inputs from Airbus Hamburg and Boeing Charleston supply chain planners. Segmentation modeling spanned product type, material matrix, application end-use, and customer archetype across the projection horizon. CAGRs derived from installed base replacement cycle analysis and fleet renewal order backlogs. Forecast inputs included automated fiber placement capacity expansion timelines and EASA flammability standard implementation schedules.
Several conditions sit outside the modeled scope, including military procurement volatility under MIL-STD-810, COMAC C919 export certification delays, and sustainable aviation fuel thermal specification rewrites. Forecasts reflect assumptions regarding Boeing next-generation narrowbody program timing and EPA enforcement consistency for hexavalent chromium. Deviation in automated fiber placement technician training throughput would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market