
 Commercial Aircraft Upholstery Market | 2026-2036
Commercial Aircraft Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Upholstery Market Outlook
Operating lease penetration and power-by-the-hour arrangements are reshaping capital deployment across the commercial aircraft upholstery supply chain. Collins Aerospace leverages its integrated interiors portfolio to sustain long-term contracts with global lessors. Safran Seats anchors European narrow-body programs through manufacturing scale in its Poitiers facility. Tapis Corporation competes on specialty leather finishing for premium cabin configurations.
Commercial aircraft upholstery encompasses fire-resistant textiles, synthetic leathers, foam cushioning, and decorative laminates engineered to meet 16 CFR Part 1633 and OSU heat-release thresholds while providing passenger comfort and durability across 15-20 year service lives. Fabric applications dominate volume across economy-class seating programs, while leather commands margin concentration in first-class and business-class retrofits. Foam segments face substitution pressure from lighter-weight silicone alternatives, yet remain entrenched in safety equipment applications due to crashworthiness certification pathways.
FAA Approved certification under 14 CFR 25.853 and EASA CS-25 fire-resistance protocols govern material qualification, creating barrier-to-entry effects for uncertified suppliers. ISO Certified quality systems, particularly AS9100, shape procurement eligibility for tier-one seating OEMs. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and emerging MEE standards in China, as regulatory divergence threatens to fragment material specifications across production lines.
Market Dynamics
Fleet renewal cycles across low-cost carriers are compressing upholstery replacement intervals while FAA 14 CFR 25.853 and EASA CS-25 amendments escalate material certification burdens. This dual pressure is restructuring supplier qualification pipelines and concentrating procurement among certified tier-one seating OEMs.
Growth Catalysts
- Narrow-body retrofit volumes:Low-cost carriers in the United States, India, and Indonesia are accelerating seat refurbishment programs to extend airframe service lives. These programs consume fire-resistant textiles and synthetic leathers in bulk quantities.
- 14 CFR 25.853 compliance mandates:FAA flammability testing protocols are disqualifying legacy material formulations. Certified suppliers gain exclusive access to aftermarket replacement contracts previously served by uncertified competitors.
- Silicone foam substitution:Lighter-weight cushioning materials are penetrating economy-class programs where weight reduction translates directly to fuel savings. Airlines specify these alternatives in new-build narrow-body configurations.
Market Restraints
- Petrochemical input volatility:Polyurethane foam and synthetic leather production depend on propylene oxide and adipic acid feedstocks. Price swings in these chemicals compress upholstery manufacturer margins unpredictably.
- Certification timeline friction:FAA and EASA coordinated type certification for new fire-resistant textiles extends 18-24 months. This duration blocks rapid material innovation cycles and favors incumbents with established test histories.
- Crashworthiness certification lock-in:Silicone alternatives struggle to displace polyurethane in safety equipment applications where existing crash-test documentation creates technical switching costs.
Strategic Opportunities
- EU Green Deal alignment:Bio-based leather finishing and recycled textile feedstocks qualify for preferential procurement scoring by European flag carriers. Suppliers with ISCC PLUS or equivalent chain-of-custody certification access premium contract tiers.
- Power-by-the-hour penetration:Operating lessors in Ireland and Singapore are consolidating upholstery procurement under long-term service agreements. This channel rewards suppliers with integrated MRO networks and predictive inventory systems.
- China MEE standards emergence:Evolving national fire-safety and environmental regulations are creating parallel certification requirements. Early movers establishing in-country testing partnerships position for domestic narrow-body production ramp-ups.
Industry Challenges
- AS9100 auditor scarcity:Aerospace-quality management system certification requires specialized assessor availability. Backlogs in audit scheduling delay supplier qualification for tier-one seating OEM procurement lists.
- Legacy fleet documentation gaps:Retrofit programs for aging airframes often lack original upholstery specification records. Material traceability failures trigger regulatory non-compliance exposure during cabin modification campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Upholstery Market |
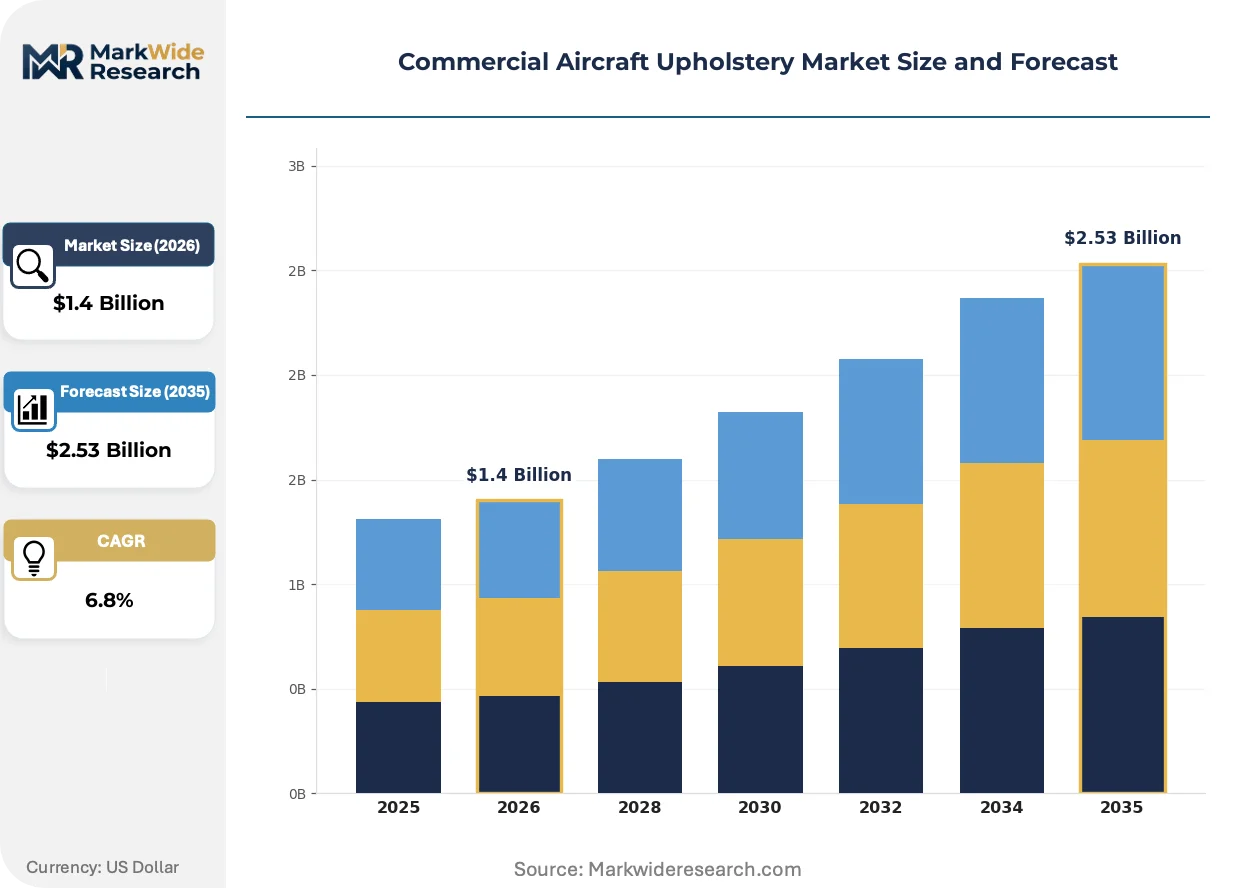
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fabric, Leather, Foam, Vinyl Application: Seating, Cabin Interiors, Safety Equipment, Decorative Elements End User: Airlines, Manufacturers, Interior Designers, Maintenance Providers Certification: FAA Approved, ISO Certified, Fire Resistance, Durability Standards |
| Companies Covered | RECARO Aircraft Seating GmbH & Co. KG, Tapis Corporation, Collins Aerospace, Aerotex Aircraft Interiors Inc., Aeristo AG, Safran Seats, Franklin Products, OmnAvia Interiors, LLC, Lantal Textiles AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Upholstery Market Strategic Shifts
Digital traceability systems and sustainable material platforms are displacing conventional supply chain architectures. Regulatory divergence between FAA, EASA, and emerging Chinese standards is fragmenting certification pathways.
Blockchain-enabled material provenance tracking is digitizing upholstery supply chain documentation from raw fiber through seat assembly. Airlines and lessors in Germany and the United Arab Emirates are mandating these systems for sustainability audit compliance. The technology is compressing supplier qualification timelines by automating certificate-of-conformity verification.
EASA CS-25 amendments incorporating heat-release rate thresholds beyond existing FAA 14 CFR 25.853 requirements are tightening European market entry. Upholstery manufacturers serving dual-certification programs must maintain parallel testing protocols. First-class and business-class retrofits face the steepest compliance cost escalation due to leather finishing process reformulation requirements.
Airline procurement departments are consolidating upholstery purchasing under fleet-wide lifecycle contracts rather than per-aircraft spot orders. Lessors in Ireland and Hong Kong are displacing traditional MRO channel relationships with direct manufacturer agreements. This concentration is most visible in narrow-body programs where standardized seat platforms enable volume commitment structures.
Commercial Aircraft Upholstery Market Segmentation
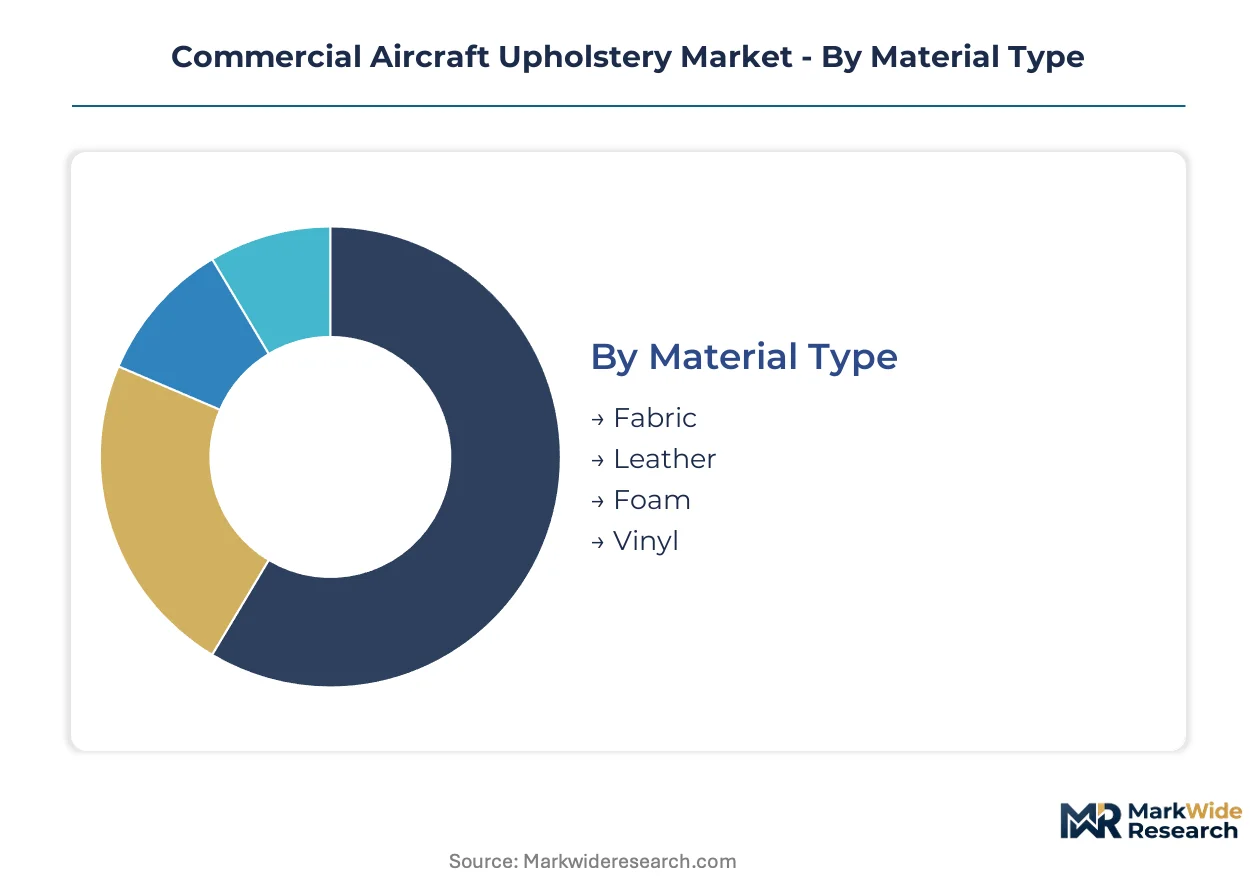
Upholstery procurement patterns diverge sharply across material grades, cabin zones, and regulatory tiers. Segmentation clarity enables suppliers to align certification investments with specific customer qualification pathways and margin structures.
Material Type:
Mature synthetic formulations dominate current volumes while emerging bio-based alternatives reshape supplier R&D allocation. Cost-performance positioning separates commodity feedstocks from specialty finishes.
- Fabric:Fire-resistant textiles woven from aramid and modacrylic fibers meet FAA 14 CFR 25.853 burn-through requirements. Narrow-body economy programs across United States low-cost carriers consume these materials in bulk for seat covers and sidewall panels. Certification lock-in favors incumbent weavers with established test histories at FAA-approved laboratories.
- Leather:Premium hides with specialized finishing treatments command margin concentration in first-class and business-class retrofits. European flag carriers specify these materials for long-haul fleet refurbishments under EU Green Deal sustainability scoring criteria. Tanneries with ISCC PLUS chain-of-custody certification access preferential procurement tiers.
- Foam:Polyurethane cushioning remains entrenched in safety equipment applications due to crashworthiness documentation pathways. Silicone alternatives penetrate economy-class seating where weight reduction translates to fuel savings.
- Vinyl:Synthetic polymer surfaces offer cost-efficient durability for high-wear cabin zones. Asian narrow-body production lines specify these materials for lavatory and galley applications.
Fabric handles the majority of throughput; leather is the fastest mover on share.
Application:
Volume concentrates in passenger-contact surfaces while safety-critical applications impose distinct certification burdens. Retrofit cycles vary dramatically across cabin zones.
- Seating:Seat covers, cushions, and headrest assemblies constitute the largest upholstery consumption category. Fire-resistant textiles and synthetic leathers face 15-20 year replacement cycles driven by wear patterns and regulatory refresh mandates. Airlines in India and Indonesia are accelerating refurbishment programs to extend airframe service lives.
- Cabin Interiors:Sidewall panels, overhead bin linings, and bulkhead coverings require coordinated material palettes across entire cabin sections. Lessors in Ireland consolidate these purchases under fleet-wide lifecycle contracts.
- Safety Equipment:Life vest pouches, oxygen mask compartments, and evacuation slide covers demand crashworthiness-certified cushioning. Polyurethane foam retains dominance here due to existing test documentation.
- Decorative Elements:Curtains, antimacassars, and branding accents complete cabin aesthetic programs. These applications tolerate shorter certification timelines.
Seating absorbs the dominant share of material volume; cabin interiors are expanding most quickly as lessors consolidate procurement.
End User:
Customer type determines contract structure, with operating lessors displacing traditional airline-direct purchasing. Power-by-the-hour arrangements reshape capital deployment patterns.
- Airlines:Flag carriers and low-cost operators drive spot replacement demand and scheduled retrofit programs. United States carriers with major MRO hubs in Miami and Dallas anchor aftermarket replacement cycles.
- Manufacturers:Boeing and Airbus tier-one seating OEMs specify materials for new-build production lines. These customers demand AS9100-certified quality systems and multi-year supply commitments.
- Interior Designers:Boutique cabin configuration firms source specialty finishes for VIP and head-of-state aircraft. These engagements command premium pricing for customized material development.
- Maintenance Providers:Independent MRO facilities perform unscheduled repairs and minor modifications. Documentation gaps in aging fleet records complicate material traceability compliance.
Airlines remain the anchor demand source; manufacturers are gaining procurement influence through new-build program consolidation.
Certification:
Regulatory tier functions as the primary market gate, with FAA and EASA protocols creating divergent qualification pathways. Certification status determines supplier eligibility for specific contract tiers.
- FAA Approved:14 CFR 25.853 flammability testing protocols govern United States market entry. Approved suppliers gain exclusive access to aftermarket contracts previously served by uncertified competitors.
- ISO Certified:AS9100 aerospace quality management systems shape tier-one seating OEM procurement eligibility. Auditor scarcity creates backlogs in supplier qualification timelines.
- Fire Resistance:EASA CS-25 amendments incorporate heat-release rate thresholds beyond existing FAA requirements. Dual-certification programs demand parallel testing protocols.
- Durability Standards:Abrasion, lightfastness, and cleaning chemical resistance specifications vary by customer tier. Premium cabin programs impose the most stringent performance criteria.
FAA Approved certification anchors the largest addressable market; Fire Resistance protocols are climbing the fastest as EASA tightens European requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operating lessors in Ireland and Singapore control fleet-wide procurement decisions, while major MRO hubs in Miami, Dallas, and Dubai anchor aftermarket replacement cycles. FAA 14 CFR 25.853 and EASA CS-25 regulations create divergent certification requirements across manufacturing and retrofit centers.
United States
Low-cost carriers drive narrow-body retrofit volumes through seat refurbishment programs extending airframe service lives. FAA 14 CFR 25.853 flammability testing protocols govern material qualification, disqualifying legacy formulations and concentrating supply among certified vendors. Major MRO hubs in Miami and Dallas process aftermarket upholstery replacement cycles for domestic fleet operators.
Germany
European flag carriers specify premium leather finishing for long-haul fleet refurbishments under EU Green Deal sustainability scoring criteria. EASA CS-25 amendments incorporate heat-release rate thresholds beyond existing FAA requirements, tightening market entry for upholstery manufacturers. Frankfurt and Hamburg anchor specialized tanneries with ISCC PLUS chain-of-custody certification accessing preferential procurement tiers.
China
Domestic narrow-body production ramp-ups create demand for fire-resistant textiles and synthetic leathers in new-build configurations. Evolving MEE standards establish parallel certification requirements for national fire-safety and environmental compliance. Shanghai and Tianjin manufacturing clusters host in-country testing partnerships positioning suppliers for state-backed aviation programs.
India
Airlines accelerate refurbishment programs to extend aging narrow-body fleet service lives, consuming bulk quantities of economy-class fabrics. BIS standards and DGFT import regulations shape material procurement pathways for domestic carriers. Bangalore and Hyderabad MRO facilities expand capacity to process regional retrofit demand from low-cost operators.
Ireland
Operating lessors consolidate upholstery purchasing under fleet-wide lifecycle contracts rather than per-aircraft spot orders. EU Green Deal alignment requirements filter into procurement specifications for European-leased assets. Dublin-based lessor headquarters coordinate global supply chain decisions affecting narrow-body programs across multiple continents.
Commercial Aircraft Upholstery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply positions. Tier-one seating OEMs with integrated interiors portfolios sustain long-term contracts with global lessors and flag carriers. Three archetypes dominate: aerospace conglomerates with bundled interiors offerings, specialized upholstery manufacturers with certification depth, and regional fabricators serving aftermarket MRO channels. Consolidation concentrates among certified suppliers while M&A activity and capacity expansion in low-cost manufacturing regions reshape competitive positioning.
Among European-based specialists, RECARO Aircraft Seating GmbH & Co. KG and Safran Seats occupy positions within the integrated-systems tier, exemplifying manufacturers with manufacturing scale and regulatory breadth. Tapis Corporation anchors the specialty-finishing archetype, representing suppliers competing on material differentiation for premium cabin configurations. These three entities illustrate the competitive spectrum from bundled interiors platforms to focused material specialists.
| Leading Market Players |
|---|
| RECARO Aircraft Seating GmbH & Co. KG |
| Tapis Corporation |
| Collins Aerospace |
| Aerotex Aircraft Interiors Inc. |
| Aeristo AG |
| Safran Seats |
| Franklin Products |
| OmnAvia Interiors, LLC |
| Lantal Textiles AG |
| Others |
Value Chain & Pricing Dynamics
Petrochemical input volatility in polyurethane foam and synthetic leather feedstocks compresses manufacturer margins unpredictably while simultaneously widening pricing spreads between certified and uncertified supply tiers. This cost instability forces tier-one seating OEMs toward long-term offtake agreements with indexed pricing clauses, restructuring procurement relationships across narrow-body retrofit programs.
Pricing Analysis
Cost-plus contracts with propylene oxide and adipic acid indexation dominate procurement between certified upholstery manufacturers and tier-one seating OEMs. Price differentiation hinges on FAA 14 CFR 25.853 certification status and AS9100 quality system tier, with certified suppliers commanding substantial premiums over uncertified competitors. Cost compression in economy-class fabric segments is intensifying because low-cost carriers in India and Indonesia negotiate volume commitments against spot-market alternatives. Airlines with power-by-the-hour arrangements exhibit lowest price sensitivity due to bundled service structures, while independent MRO facilities face acute margin pressure from documentation compliance costs.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized textile weavers in Germany, tanneries with ISCC PLUS certification in Italy, and foam converters in the United States. Raw material flows draw from aramid fiber producers in the United States, premium hide suppliers in Europe, and silicone feedstock providers in Asia. Single-source vulnerability concentrates in FAA-approved testing laboratory capacity, where 18-24 month certification timelines create bottleneck exposure for new material formulations. Distribution runs through tier-one seating OEM direct contracts with operating lessors in Ireland and Singapore, displacing traditional spot-market MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FAA, EASA, and emerging Chinese MEE standards fragments certification pathways, creating specialized niches for suppliers with parallel testing capabilities and multi-jurisdictional approval depth.
For Market Incumbents: Pre-empt silicone foam substitution threats by securing exclusive crashworthiness documentation for safety equipment applications through accelerated polyurethane formulation R&D. Consolidate backward integration into aramid fiber weaving capacity to lock in fire-resistant textile supply for narrow-body retrofit volumes. Channel control through predictive inventory systems for power-by-the-hour contracts protects margin position against emerging regional competitors. For New Entrants and Emerging Players: Underpenetration in China's domestic narrow-body production ramp-ups offers accessible entry points for suppliers establishing in-country MEE testing partnerships. Target economy-class vinyl applications for Asian lavatory and galley programs where certification timelines tolerate shorter qualification cycles. A specialized leather finishing focus for VIP and head-of-state aircraft commands premium pricing with reduced incumbent competition. For Investors and Strategic Acquirers: EASA CS-25 heat-release rate amendments beyond existing FAA thresholds reshape the acquisition landscape toward European-certified suppliers with reformulation-ready tannery operations. Long-term viability centers on suppliers with dual-certification infrastructure spanning United States and European regulatory clusters. The signal to watch is operating lessor consolidation of fleet-wide lifecycle contracts displacing per-aircraft spot orders as procurement concentration indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Fiber Production | Captive supply of fire-resistant textile feedstock locks in FAA 14 CFR 25.853 certification pathways. |
| Dual-Certification Testing Infrastructure Expansion | Parallel FAA and EASA laboratory capacity accesses premium contract tiers for transatlantic fleet operators. |
| Blockchain-Enabled Material Provenance Platform | Automated certificate-of-conformity verification compresses supplier qualification timelines for lessor sustainability audits. |
| ISCC PLUS Chain-of-Custody Certification | Bio-based leather finishing qualifies for EU Green Deal preferential procurement scoring by European flag carriers. |
| Predictive Inventory System Deployment | Power-by-the-hour contract eligibility requires integrated MRO network coordination with lessor fleet management platforms. |
Study Parameters
Initial hypotheses were tested against primary input from tier-one seating OEM procurement directors, FAA-approved laboratory test engineers, operating lessor fleet managers, and specialty tannery technical directors and refined through secondary validation against EASA CS-25 amendment filings, FAA 14 CFR 25.853 test documentation databases, customs records for aramid fiber and synthetic leather trade flows, and AS9100 certification registry data. Bottom-up triangulation across material type consumption patterns and top-down reconciliation against fleet renewal cycle projections anchored volume estimates.
Demand-supply-balance framing modeled upholstery consumption against narrow-body retrofit schedules and new-build production rates across the analysis window. Segmentation dimensions included material grade tier, cabin zone application, end-user contract structure, and regulatory certification cluster. CAGRs were derived from fitted trend extrapolation against fleet age distributions and replacement interval compression factors. Industry-specific inputs incorporated power-by-the-hour penetration rates and EU Green Deal procurement scoring adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic suppliers or accelerated silicone foam crashworthiness certification would shift outcomes beyond modeled ranges. Quarterly review of EASA-FAA regulatory harmonization progress, operating lessor contract consolidation announcements, and propylene oxide price index movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market
Aircraft Cabin Interior
Lightweight High-Strength Passenger Window Systems for Next-Gen Aircraft Market