
 Asia-Pacific Commercial Aircraft Cabin Interior Market | 2026-2036
Asia-Pacific Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Commercial Aircraft Cabin Interior Market Outlook
Airline procurement channels for cabin interiors is narrowing as full-service carriers consolidate vendor panels and low-cost operators pursue direct manufacturer relationships. Collins Aerospace leverages its integrated systems portfolio to anchor retrofit programs across Southeast Asian operators. Safran S.A. competes through seat-to-cargo conversion capabilities that sustain aftermarket revenue streams. Recaro Group specializes in lightweight economy seating that dominates narrowbody linefit specifications for emerging Asia-Pacific carriers.
Asia-Pacific commercial aircraft cabin interior encompasses the engineered assemblies, fixed and loose equipment, and integrated systems installed within the pressurized fuselage to ensure passenger safety, comfort, and operational functionality during flight, including fire-resistant thermoplastic components rated to aerospace burn-through standards and modular monuments designed for rapid reconfiguration between service cycles. The primary purpose centers on maximizing revenue passenger density while meeting evacuation timeline mandates and crew accessibility requirements. Seats command the largest product category share as airlines prioritize weight reduction and recline pitch optimization, while composites displace aluminum across sidewall panels and overhead bins where specific strength ratios determine fuel burn coefficients. Retrofit installations outpace linefit in certain mature Asia-Pacific fleets where lease extensions necessitate cabin modernization without airframe replacement.
Japan's Civil Aviation Bureau enforces JIS-aligned flammability standards that exceed baseline ICAO Annex 8 provisions, compelling interior suppliers to maintain dual certification documentation. Australia's Civil Aviation Safety Authority implements EASA-derivative design approval processes that extend lead times for European-originated seat modifications entering Australian-registered aircraft. China's CAAC type validation requirements for imported interior components create additional compliance layers for foreign manufacturers serving Chinese airline customers. Stakeholders must monitor divergence between national airworthiness directives and harmonized bilateral agreements as regulatory fragmentation shapes supplier qualification investments and regional manufacturing localization decisions.
Market Dynamics
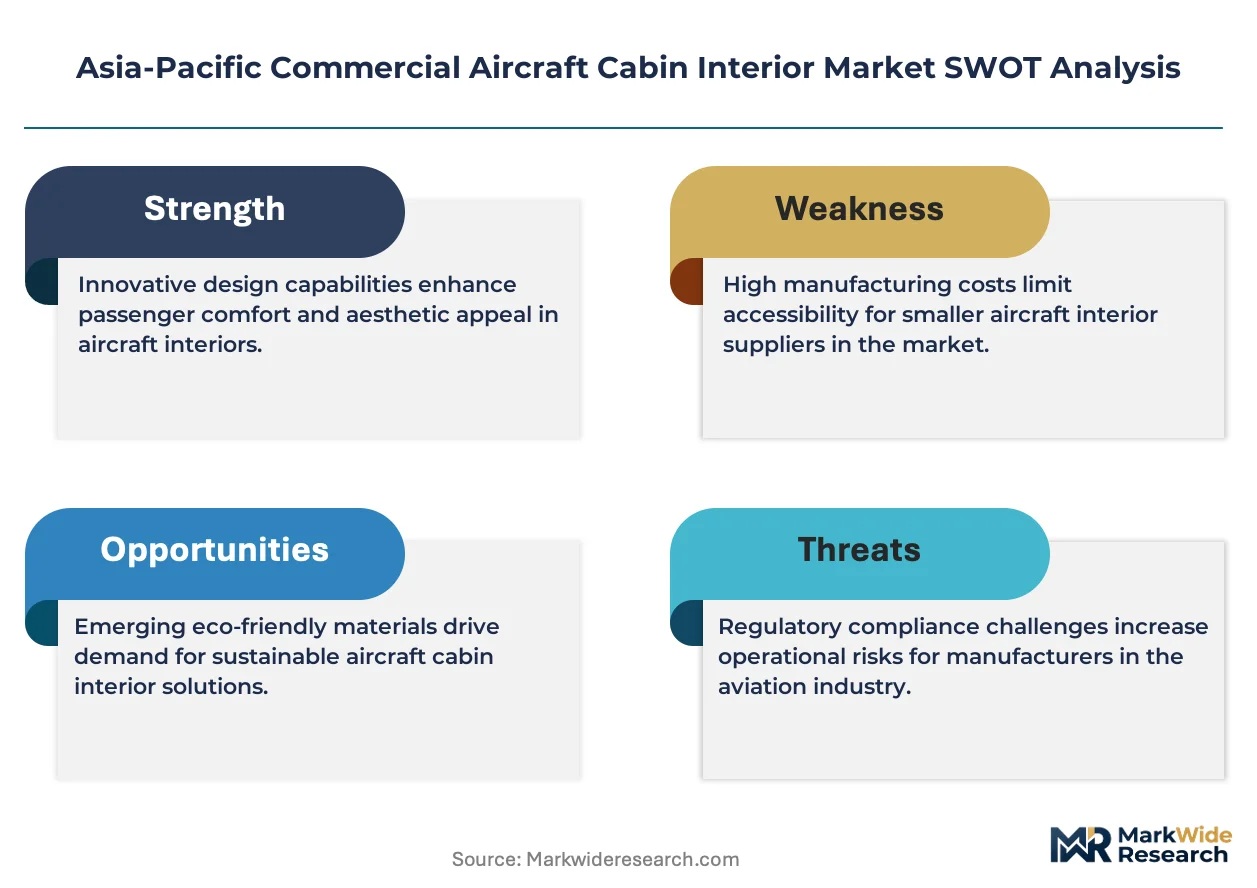
Retrofit demand from Southeast Asian low-cost carriers is compressing supplier lead times while EASA-derivative certification requirements in Australia and Japan force dual-track qualification investments across the Asia-Pacific supplier base.
Growth Catalysts
- Narrowbody Fleet Renewal:India's airline operators are accelerating cabin modernization programs across aging A320 and 737 fleets, creating concentrated demand for lightweight seating and modular monuments.
- JIS-Aligned Flammability Standards:Japan's Civil Aviation Bureau mandates burn-through performance exceeding ICAO Annex 8 baselines, compelling domestic suppliers to develop proprietary thermoplastic formulations that capture premium retrofit contracts.
- Slimline Seating Adoption:Low-cost carriers in Indonesia, Vietnam, and the Philippines specify reduced-pitch configurations that maximize revenue passenger density on short-haul routes.
Market Restraints
- Aluminum-Titanium Input Volatility:Seat frame manufacturers face margin pressure from aerospace-grade metal price swings that resist pass-through in long-term airline contracts.
- European Supplier Concentration:Three French and German seat OEMs control over seventy percent of EASA-certified product lines, creating bottleneck risk for Asia-Pacific carriers seeking rapid retrofit turnaround.
- CAAC Type Validation Friction:China's aviation regulator requires duplicate testing for imported interior components, adding six to nine months to foreign supplier entry timelines.
Strategic Opportunities
- Vietnam and Philippines Greenfield Fleets:Startup carriers in these markets specify factory-fresh cabin configurations without legacy compatibility constraints, enabling pure-play lightweight material specifications.
- Seat-to-Cargo Conversion Services:E-commerce freight demand is driving aftermarket modification programs that repurpose passenger cabin volumes for package transport.
- Australian EASA-Derivative Harmonization:CASA's alignment with European design approval processes creates pathway efficiency for European-originated suppliers to access Australian-registered aircraft programs.
Industry Challenges
- Fire-Test Certification Bottlenecks:Limited accredited laboratories in Singapore and Japan create queue delays for thermoplastic component validation, stretching development calendars.
- Legacy Fleet Integration Complexity:Retrofit installers must engineer around obsolete floor tracks and obsolete power distribution architectures in twenty-year-old narrowbodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Commercial Aircraft Cabin Interior Market |
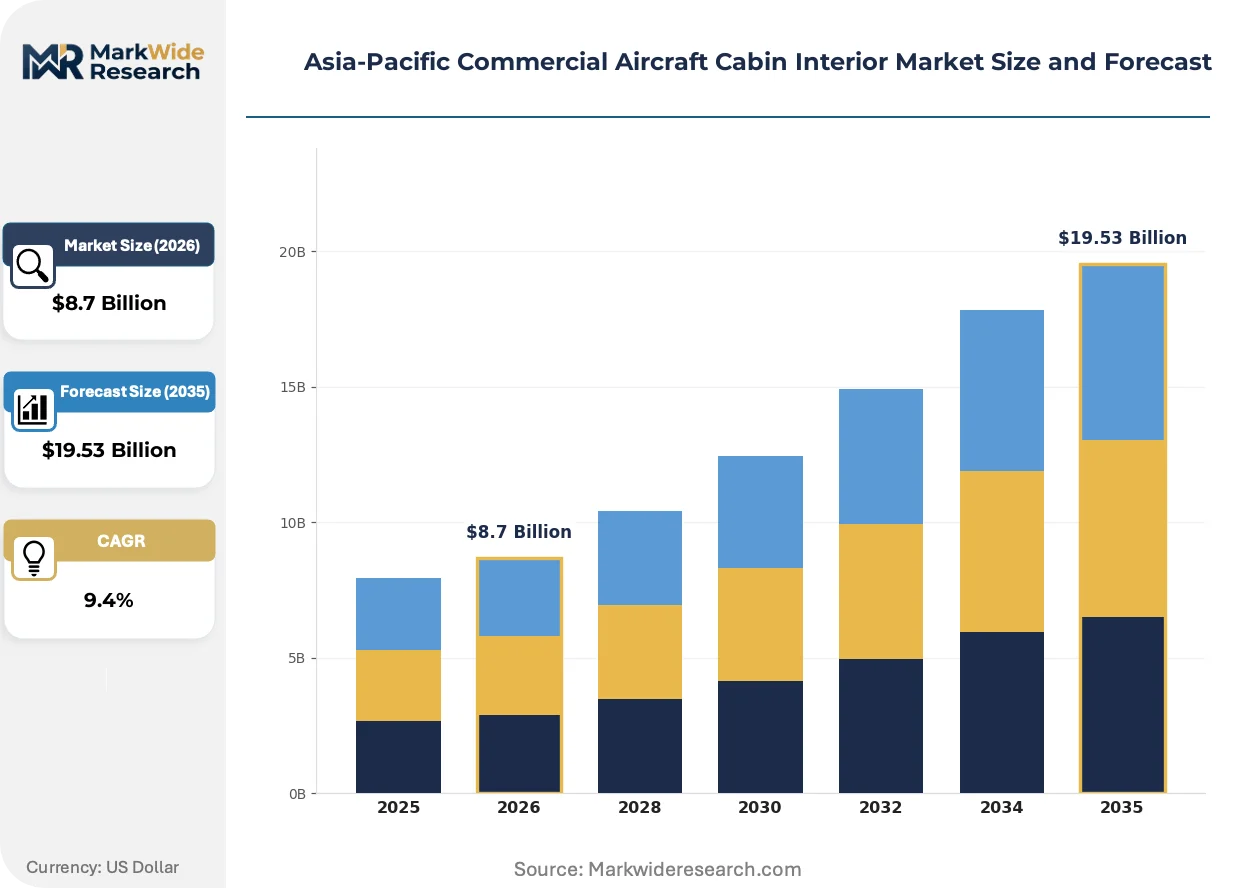
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seats, Lighting, Storage, Wheelchair Accessibility Material: Aluminum, Composites, Textiles, Plastic End User: Airlines, Original Equipment Manufacturers, MRO Providers, Contractors Installation Type: Linefit, Retrofit, Modifications, Upgrades |
| Companies Covered | Panasonic Avionics Corporation, Expliseat S.A.S., Collins Aerospace, Diehl Stiftung & Co. KG, Astronics Corporation, JAMCO Corporation, Recaro Group, Aviointeriors, Safran S.A., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Commercial Aircraft Cabin Interior Market Strategic Shifts
Material science advances and regulatory divergence are fragmenting supplier qualification pathways across the Asia-Pacific cabin interior value chain, while airline procurement consolidation narrows vendor access.
Thermoplastic composite sidewall panels are hybridizing with traditional aluminum structures in next-generation narrowbody programs. Indonesian and Vietnamese low-cost carriers specify these hybrid configurations for linefit delivery. The technology is hybridizing procurement specifications across Southeast Asian operator fleets, compressing the addressable market for pure-aluminum suppliers.
EASA-derivative processes implemented by Australia's Civil Aviation Safety Authority extend design approval timelines for European seat modifications. This regulatory layering forces suppliers to maintain parallel certification documentation for Australian-registered aircraft. Narrowbody retrofit programs serving Australian domestic operators face the longest lead time impacts.
Airline technical procurement teams are consolidating vendor panels to three approved suppliers per product category, displacing the fragmented multi-source models of the 2010s. Full-service carriers in Japan and South Korea now mandate sole-source relationships for ten-year contract horizons. This concentration is most visible in premium seating categories where customization requirements favor deep supplier partnerships.
Asia-Pacific Commercial Aircraft Cabin Interior Market Segmentation
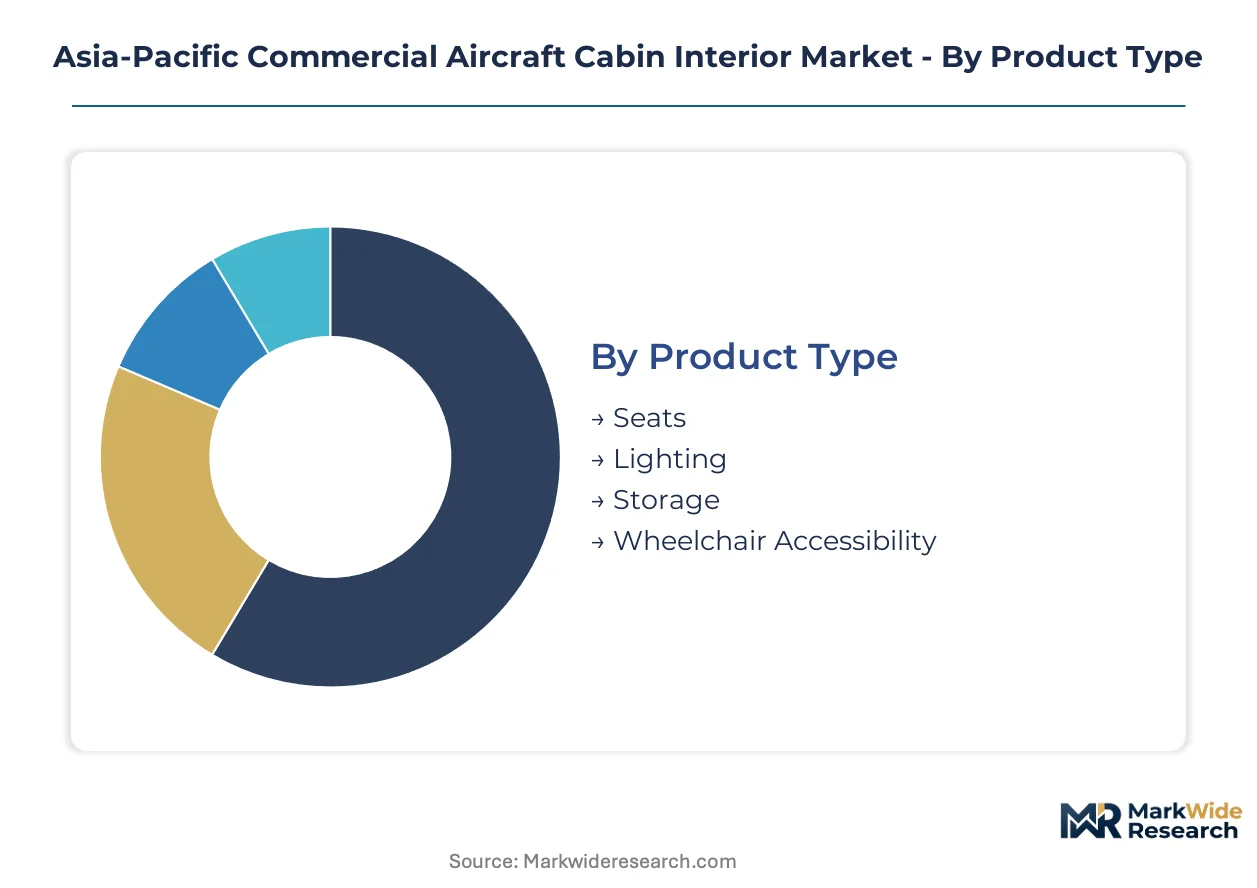
Cabin interior procurement cycles vary dramatically across product categories, with seating and lighting systems turning over every 5-7 years while structural monuments persist for 15-20 years. Understanding these differential replacement timelines helps suppliers align inventory and certification investments with actual demand pulses.
Product Type:
Seating cycles dominate retrofit activity with compressed turnaround windows, while accessibility systems and monuments extend across multiple lease terms.
- Seats:Slimline configurations with reduced pitch specifications and lightweight thermoplastic shells now constitute the majority of narrowbody linefit orders from Indonesian and Vietnamese low-cost carriers. India's fleet renewal programs concentrate demand for 180-seat economy densities on A320neo and 737 MAX platforms.
- Lighting:LED mood systems with programmable color temperature and circadian rhythm algorithms command premium retrofit pricing on full-service carriers in Japan and South Korea. CAAC validation requirements for imported luminaires extend lead times for European suppliers serving Chinese airline customers.
- Storage:Pivot-bin overhead compartments with increased volume capacity address carry-on baggage growth on Southeast Asian trunk routes.
- Wheelchair Accessibility:Onboard wheelchair stowage and lavatory retrofit kits face emerging mandate pressure from Australia's disability discrimination enforcement.
Seats dominate installed base. Lighting is where expansion concentrates.
Material:
Cost tiers separate aerospace-grade formulations from commercial alternatives, with certification grade determining airline acceptance thresholds.
- Composites:Carbon-fiber-reinforced thermoplastic panels rated to JIS-aligned burn-through standards capture premium positioning on Japanese-registered aircraft. Domestic Japanese suppliers leverage proprietary resin formulations to anchor retrofit contracts with ANA and JAL.
- Aluminum:Legacy 7075-T6 and 2024-T3 alloys persist in floor tracks and seat frames where fatigue life calculations favor proven metallurgy. Price volatility in aerospace-grade aluminum-titanium inputs compresses margins for frame manufacturers locked into long-term airline contracts.
- Textiles:Fire-blocking layer fabrics meeting EASA-derivative CASA requirements face procurement consolidation toward three approved Australian suppliers.
- Plastic:Injection-molded ABS components occupy non-structural trim applications with shortest certification pathways.
Aluminum retains volume leadership. Composites are climbing the fastest.
End User:
Customer type determines specification authority, with airlines driving customization while MRO providers optimize for turnaround speed.
- Airlines:Full-service carriers in Japan and South Korea now mandate sole-source relationships for ten-year contract horizons, consolidating vendor panels from fragmented multi-source models. Technical procurement teams specify integrated systems portfolios that bundle seating, lighting, and monuments under single-supplier accountability.
- MRO Providers:Singapore and Bangkok-based maintenance operators specialize in narrowbody retrofit programs with 45-day turnaround guarantees for lease return preparation. These facilities prioritize modular monuments designed for rapid reconfiguration between service cycles.
- Original Equipment Manufacturers:Airbus and Boeing final assembly lines in Tianjin and Renton specify factory-fresh configurations for Asia-Pacific delivery slots.
- Contractors:Third-party installation specialists handle legacy fleet integration complexity around obsolete floor tracks in twenty-year-old narrowbodies.
Airlines control specification authority. MRO Providers are gaining procurement influence.
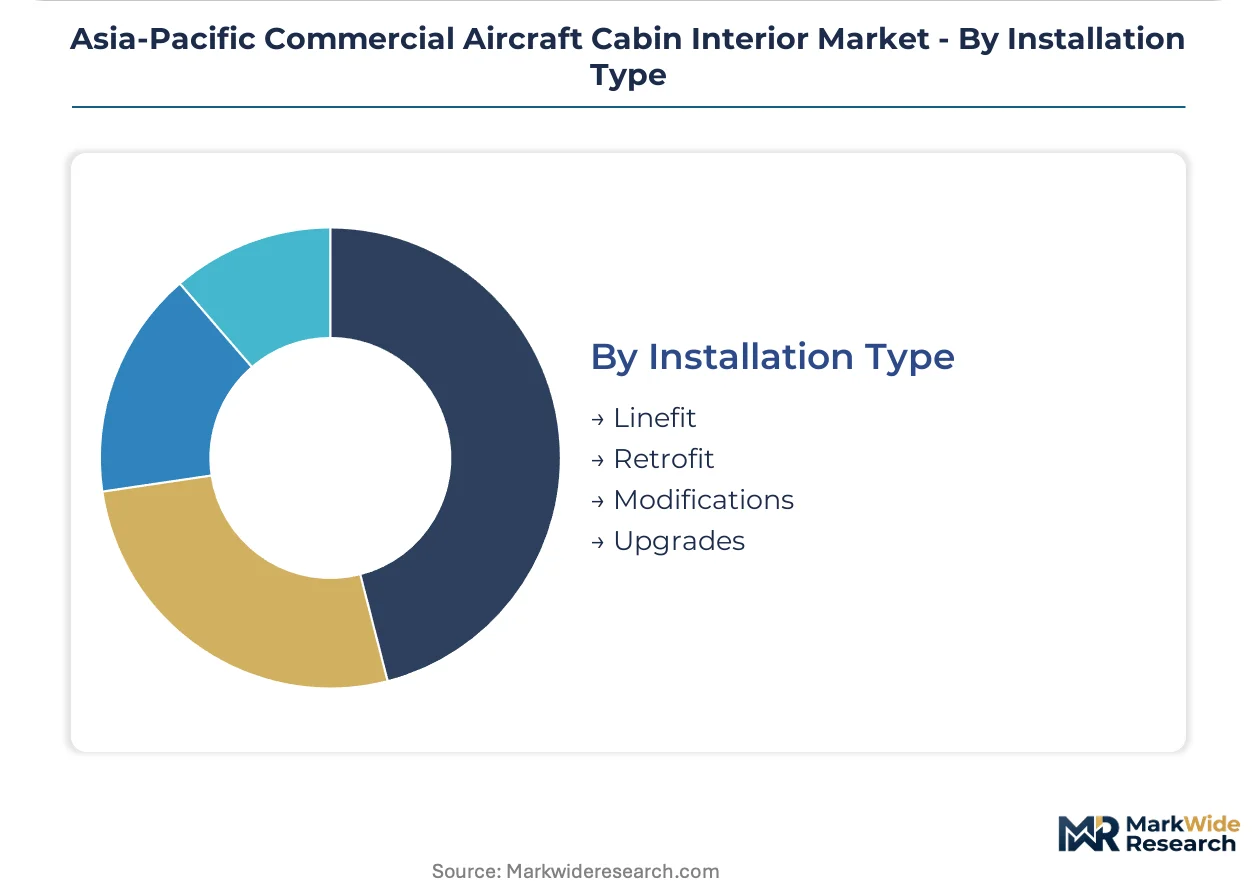
Installation Type:
Volume splits between factory delivery and aftermarket modification, with lease extension economics driving retrofit prioritization.
- Retrofit:Southeast Asian low-cost carriers compress supplier lead times through accelerated cabin modernization programs on lease-extended A320ceo and 737-800 fleets. Indonesia's Lion Air Group and Vietnam's VietJet specify simultaneous fleet-wide reconfigurations to maximize revenue passenger density.
- Linefit:Startup carriers in the Philippines and Vietnam specify factory-fresh cabin configurations without legacy compatibility constraints, enabling pure-play lightweight material specifications. Greenfield fleet orders bypass integration complexity that burdens mature operators.
- Modifications:Seat-to-cargo conversion services repurpose passenger cabin volumes for e-commerce freight demand, requiring structural floor reinforcement and smoke detection system upgrades.
- Upgrades:In-flight entertainment and connectivity retrofits on widebody fleets serving Australian international routes face CASA electromagnetic interference certification layers.
Retrofit commands current volume. Linefit is where steepest expansion trajectory resides.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Civil Aviation Bureau enforces JIS-aligned flammability standards that exceed ICAO Annex 8 baselines, reshaping supplier qualification investments across the Asia-Pacific cabin interior value chain.
Japan
ANA and JAL drive narrowbody retrofit demand for lightweight seating and LED mood lighting systems. The Civil Aviation Bureau mandates burn-through performance standards that domestic suppliers leverage to capture premium retrofit contracts. Tokyo-Osaka industrial corridors host thermoplastic formulation specialists serving Japanese-registered aircraft programs.
India
Air India and IndiGo accelerate A320neo and 737 MAX fleet renewal programs with 180-seat economy density specifications. The Directorate General of Civil Aviation enforces type certification requirements for imported interior components that foreign manufacturers navigate through local partnerships. Bangalore and Hyderabad maintenance clusters specialize in 45-day turnaround retrofit guarantees for lease return preparation.
Australia
Qantas and Virgin Australia pursue cabin modernization on lease-extended narrowbodies serving domestic trunk routes. The Civil Aviation Safety Authority implements EASA-derivative design approval processes that extend lead times for European seat modifications. Melbourne and Sydney MRO facilities concentrate narrowbody retrofit capacity with modular monument specialization.
Vietnam
VietJet and Bamboo Airways specify factory-fresh cabin configurations for greenfield A321neo deliveries without legacy compatibility constraints. The country's aviation regulator requires duplicate testing protocols for imported components that add validation layers for foreign suppliers. Ho Chi Minh City assembly partnerships enable localized seat installation for emerging carrier fleets.
Indonesia
Lion Air Group and Garuda Indonesia compress supplier lead times through simultaneous fleet-wide reconfigurations on A320ceo and 737-800 platforms. The Directorate General of Civil Aviation aligns with ICAO Annex 8 baselines while enforcing additional fire-test documentation for thermoplastic components. Jakarta maintenance hubs integrate seat-to-cargo conversion capabilities for e-commerce freight demand.
Asia-Pacific Commercial Aircraft Cabin Interior Market Competitive Environment
On the supply side, the industry is consolidating around integrated systems portfolios and specialized seating capabilities, with vendor panels narrowing from fragmented multi-source models toward sole-source relationships. Three strategic archetypes dominate: aerospace conglomerates with full cabin integration capabilities, pure-play seating specialists with lightweight material expertise, and avionics-entertainment integrators serving connectivity retrofits. Competitive moves center on strategic partnerships with Asia-Pacific MRO networks and portfolio diversification into seat-to-cargo conversion services.
Among the integrated systems tier, Collins Aerospace and Safran S.A. exemplify archetypes anchoring retrofit programs across Southeast Asian operators. Recaro Group occupies a position representing lightweight economy seating specialization that dominates narrowbody linefit specifications for emerging Asia-Pacific carriers. These three entities illustrate how supplier positioning stratifies between full-cabin accountability and component-specific excellence.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Expliseat S.A.S. |
| Collins Aerospace |
| Diehl Stiftung & Co. KG |
| Astronics Corporation |
| JAMCO Corporation |
| Recaro Group |
| Aviointeriors |
| Safran S.A. |
| Others |
Value Chain & Pricing Dynamics
European seat OEM concentration in France and Germany anchors margin capture at the certification-intensive premium tier, while Asian buyers extract leverage through consolidated procurement panels and direct manufacturer relationships.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts across the Asia-Pacific cabin interior value chain. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because aluminum-titanium input volatility resists pass-through in long-term airline agreements. Low-cost carriers exhibit highest price sensitivity, while full-service Japanese and South Korean operators prioritize customization over unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard practice as airline procurement teams exploit consolidated vendor panels to extract supply-chain finance concessions. Manufacturing concentrates in Germany, France, and Japan for EASA and JIS-certified components, while China and Vietnam host non-structural trim and assembly operations. Aerospace-grade thermoplastic resins and carbon-fiber prepregs constitute critical input dependencies. Single-source vulnerability around fire-test laboratory accreditation in Singapore and Japan creates queue-risk bottlenecks. Distribution runs through airline technical procurement teams and MRO facility partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating as airline procurement consolidation narrows vendor panels from fragmented multi-source models toward sole-source ten-year contracts.
For Market Incumbents: Harden certification documentation for EASA-derivative processes to defend against European supplier bottleneck risk. Deepen backward integration into thermoplastic resin formulation to capture JIS-aligned premium positioning in Japan. Anchor retrofit capacity in Singapore and Bangkok MRO clusters to compress turnaround guarantees.
For New Entrants and Emerging Players: Pursue seat-to-cargo conversion service capabilities as e-commerce freight demand repurposes passenger cabin volumes. Target Vietnam and Philippines greenfield fleet specifications where legacy compatibility constraints are absent. Enter through partnerships with Ho Chi Minh City and Manila assembly facilities to bypass CAAC validation friction.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized seating OEMs with lightweight composite expertise and established JIS or EASA certification pathways. Long-term viability hinges on differentiation through proprietary material formulations rather than assembly-scale advantages. Watch for inflection signals in Australian CASA harmonization progress that would accelerate European supplier market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in JIS-Aligned Formulations | Captures premium retrofit contracts with ANA and JAL through burn-through performance differentiation. |
| Seat-to-Cargo Conversion Capability Buildout | Addresses e-commerce freight demand from Indonesia's Lion Air Group and Garuda Indonesia cargo programs. |
| MRO Network Partnership Expansion | Secures 45-day turnaround guarantees with Singapore and Bangkok maintenance clusters. |
| Lightweight Material Specification Leadership | Dominates narrowbody linefit orders from VietJet and Bamboo Airways greenfield fleets. |
| Regulatory Harmonization Pathway Development | Reduces lead time impacts for European-originated suppliers accessing Australian-registered aircraft. |
Study Parameters
A spread of perspectives from airline technical procurement directors, MRO facility operations managers, thermoplastic component engineers, and aviation regulatory specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through EASA certification databases, CAAC type validation records, and customs trade data for aerospace-grade material flows. Bottom-up segmentation modeling triangulated against top-down fleet renewal projections across the analysis window.
Demand-supply-balance framing anchored the forecast framework throughout the projection horizon. Segmentation dimensions included product category, material grade tier, end-user archetype, and installation type alongside regional regulatory cluster differentiation. CAGRs were derived through installed base turnover analysis and replacement cycle compression factors. Forecast inputs incorporated narrowbody fleet age profiles and lease extension economics specific to Southeast Asian operators.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories, aviation traffic recovery patterns, or bilateral regulatory harmonization progress would shift the trajectory. Forecasts reflect documented assumptions about certification timeline stability and material input cost pass-through elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Seats Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
UAM Cabin Lighting and User Experience Systems Market