
 Global Commercial Aviation Aircraft Cabin Lighting Market | 2026-2036
Global Commercial Aviation Aircraft Cabin Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Aviation Aircraft Cabin Lighting Market Analysis
The capability gap between vertically integrated lighting OEMs and component assemblers is collapsing as LED module costs fall and system integration expertise becomes commoditized. Collins Aerospace leverages its airframe-tier supplier relationships to bundle cabin lighting with avionics packages on new Boeing and Airbus programs. Diehl Aviation sustains engineering-intensive programs across German and Chinese final assembly lines, anchoring its position in mood-lighting retrofits for A350 and A320neo families.
Commercial aviation aircraft cabin lighting encompasses electroluminescent and solid-state illumination systems engineered to deliver minimum 0.5 foot-candle emergency egress lighting while supporting circadian-rhythm management through tunable color temperatures from 2700K to 6500K. These systems serve dual commercial purposes: regulatory compliance with 90-second evacuation visibility standards and passenger experience differentiation on long-haul routes where jet lag mitigation commands premium cabin pricing. LED product types now dominate new installation flows given their 40,000-hour operational life and weight advantages over legacy fluorescent tubes, though halogen persists in specific reading-light niches where instant-on intensity remains valued. Smart lighting technology is displacing conventional architectures fastest in wide-body premium cabins, where programmable scene control creates measurable passenger satisfaction differentiation.
FAA airworthiness directives on flammability testing for interior materials directly shape lighting housing specifications and polymer selection across US-registered fleets. EASA's CS-25 certification framework and the EU's REACH chemical restrictions constrain phosphor and solder compositions in European-operated aircraft, while China's CAAC aligns with GB standards that increasingly reference indigenous reliability benchmarks. Stakeholders must weigh whether to standardize platforms across regulatory jurisdictions or fragment product lines to capture regional compliance premiums.
Market Dynamics
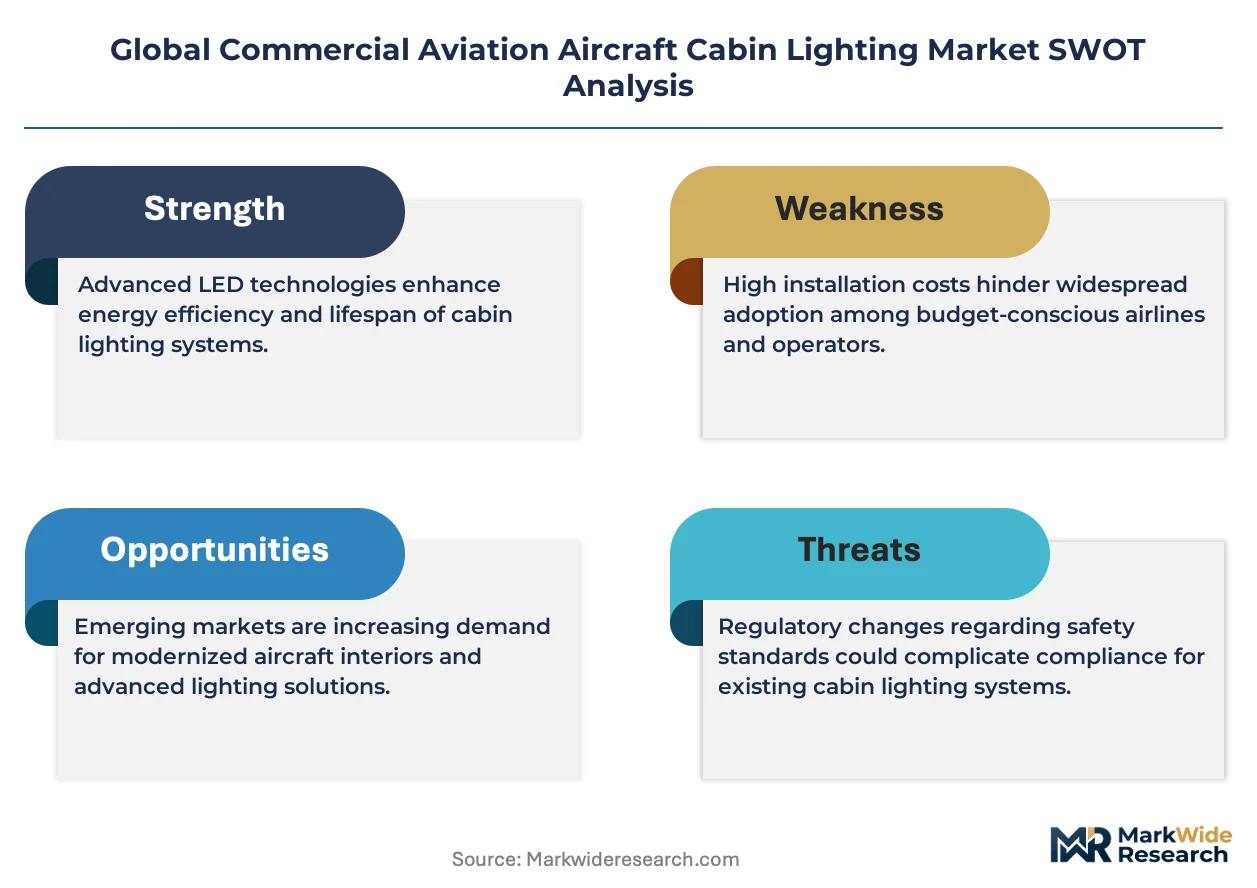
LED module cost compression is collapsing the traditional supplier hierarchy, enabling component assemblers to challenge vertically integrated OEMs on wide-body retrofit programs and narrow-body line-fit contracts.
Growth Catalysts
- CS-25 Emergency Luminance Mandates:EASA's tightened evacuation visibility standards are forcing European operators into accelerated lighting system upgrades ahead of scheduled maintenance windows.
- COMAC Delivery Scaling:China's expanding domestic airline sector is absorbing cabin customization packages at rates unmatched by mature North American or European markets.
- Circadian-Rhythm LED Tuning:Tunable color temperature systems from 2700K to 6500K are commanding premium pricing on long-haul routes where jet lag mitigation differentiates cabin products.
Market Restraints
- Phosphor Supply Concentration:Rare-earth phosphor processing capacity clusters in Chinese refining corridors, exposing European and North American luminaire manufacturers to input volatility.
- REACH Chemical Restrictions:EU constraints on solder compositions and polymer housings fragment product lines, preventing true global platform standardization.
- Halogen Persistence:Instant-on intensity requirements in reading-light niches sustain fluorescent and halogen architectures, complicating full-fleet LED transitions.
Strategic Opportunities
- CAAC Indigenization Drive:China's GB reliability benchmarks are creating captive demand for locally certified lighting systems on indigenous airframe programs.
- Avionics-Lighting Bundling:Integration of cabin illumination with flight-deck systems offers pathway for suppliers to capture line-fit contracts on next-generation Boeing and Airbus programs.
- 90-Second Evacuation Compliance:FAA airworthiness directives on flammability testing are accelerating replacement cycles for aging electroluminescent systems in US-registered fleets.
Industry Challenges
- Cross-Jurisdictional Certification:Divergent FAA, EASA, and CAAC testing protocols force manufacturers to maintain parallel qualification tracks, stretching engineering resources.
- Legacy System Integration:Programmable scene control architectures face friction when interfacing with conventional 28V DC distributions on in-service aircraft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Aviation Aircraft Cabin Lighting Market |
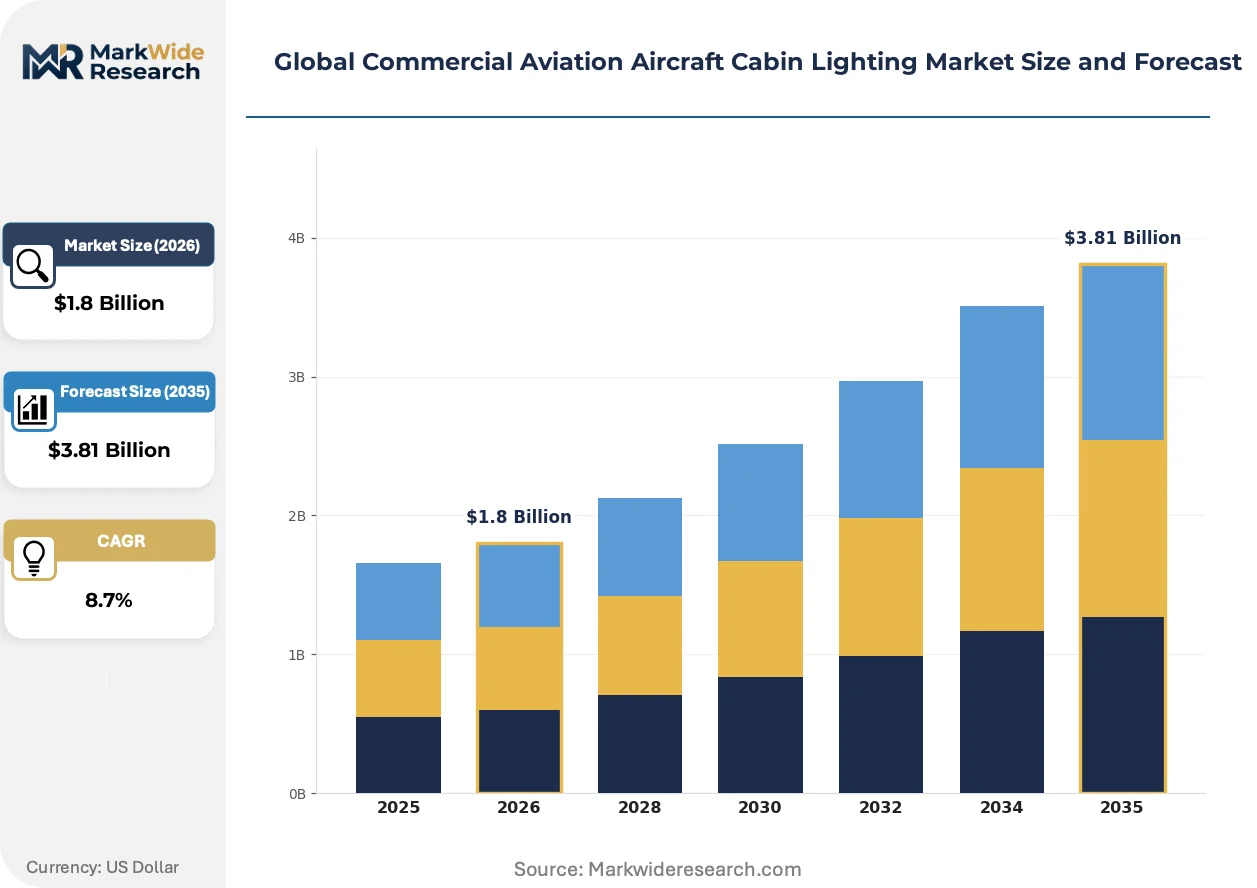
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Other Technology: Smart Lighting, Dynamic Lighting, Conventional Lighting, Adaptive Lighting End User: Commercial Airlines, Charter Services, Cargo Carriers, Private Jets Deployment: Retrofitting, New Installations, Upgrades, Maintenance |
| Companies Covered | Collins Aerospace, Safran S.A., Astronics Corporation, Diehl Aviation, Honeywell International Inc., Cobham Limited, Luminator Aerospace, STG Aerospace Limited, Zodiac Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Aviation Aircraft Cabin Lighting Market Emerging Trajectories
Smart lighting architectures are compressing hardware footprints while expanding software-defined functionality, reshaping how suppliers compete on wide-body premium cabin contracts.
Chip-on-board LED arrays are miniaturizing optical engines without sacrificing lumen output, enabling thinner ceiling profiles and reclaimed headroom in narrow-body configurations. Airlines retrofitting A320neo and 737 MAX families are specifying these compact modules to resolve spatial constraints from larger overhead bins. The form-factor reduction is miniaturizing power distribution units and simplifying harness routing through crown spaces.
REACH chemical restrictions on phosphor dopants and solder alloys are forcing reformulation of LED packages destined for European-registered aircraft. Luminaire manufacturers must now qualify alternative rare-earth compositions or absorb compliance premiums on legacy product lines. German final assembly lines are responding fastest, with engineering-intensive programs already transitioning to RoHS-compliant architectures.
Carrier procurement teams are unbundling after-sales service from hardware contracts, pitting independent MRO providers against OEM service divisions on retrofit campaigns. This disintermediation is most visible in China's domestic sector, where COMAC operators are negotiating separate technical support agreements from line-fit lighting purchases. The separation compresses upfront capital commitments while extending supplier liability windows.
Global Commercial Aviation Aircraft Cabin Lighting Market Segmentation
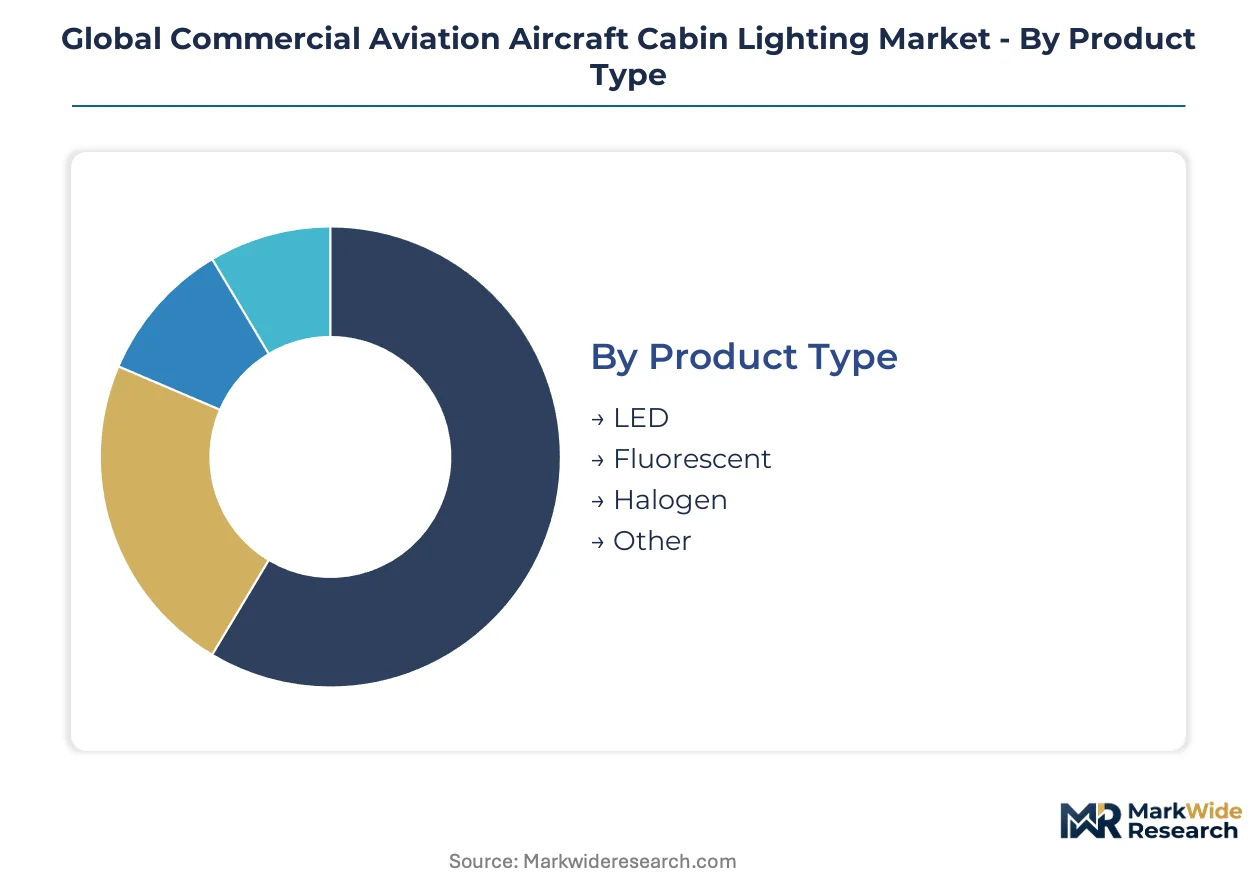
Cabin lighting procurement splits along technology lifecycle curves and regulatory compliance horizons. Each segment carries distinct margin profiles and certification burdens that reshape supplier positioning across retrofit versus line-fit opportunities.
Product Type:
LED architectures face substitution pressure from emerging chip-on-board arrays that compress optical footprints, while legacy technologies defend niche intensity requirements.
- LED:Solid-state modules delivering 40,000-hour operational life and tunable color temperatures from 2700K to 6500K. Demand concentrates in wide-body premium cabins where circadian-rhythm programming commands pricing premiums on long-haul routes.
- Fluorescent:Legacy tube architectures persist in narrow-body fleets where 28V DC distribution systems resist programmable scene control upgrades. Airlines operating aging A320ceo and 737NG families in India and Indonesia sustain replacement demand for compatible form factors.
- Halogen:Instant-on intensity specifications in first-class reading-light niches.
- Other:Electroluminescent egress strips and experimental OLED panels.
LED anchors the volume base while fluorescent gains share at the steepest rate among cost-constrained retrofit programs.
Technology:
Cost tier separation distinguishes programmable architectures from fixed-output systems, with premium cabins absorbing software-defined functionality while economy cabins prioritize hardware reliability.
- Smart Lighting:Networked systems enabling centralized scene control through cabin management interfaces. Adoption concentrates in A350 and 787 premium cabins where programmable mood sequences differentiate passenger experience on ultra-long-haul routes to Singapore and Doha.
- Dynamic Lighting:Tunable white systems with automated circadian-rhythm algorithms. Chinese carriers retrofitting COMAC C919 cabins specify these for domestic trunk routes where jet lag mitigation marketing resonates with business travelers.
- Conventional Lighting:Fixed-output architectures without programmable control.
- Adaptive Lighting:Sensor-responsive systems adjusting output to ambient conditions.
Conventional lighting retains the installed base while smart lighting climbs the fastest on new wide-body deliveries.
End User:
Volume concentration varies by fleet scale and customization appetite, with flag carriers driving specification complexity while low-cost operators standardize across aircraft types.
- Commercial Airlines:Scheduled passenger operators with fleet-wide standardization protocols. Legacy carriers in Germany and France mandate EASA CS-25 compliant mood-lighting retrofits across A320neo and A350 families ahead of tightened evacuation visibility deadlines.
- Charter Services:Seasonal and ad-hoc operators with irregular procurement cycles.
- Cargo Carriers:Freighter operators prioritizing crew-rest illumination over passenger amenities.
- Private Jets:VIP completion centers specifying bespoke cabin lighting.
Commercial airlines anchor the volume base while private jets gain share at the steepest rate on customization premiums.
Deployment:
Maturity gradients separate in-service fleet modifications from factory-delivered systems, with regulatory compliance windows accelerating replacement cycles independent of scheduled maintenance.
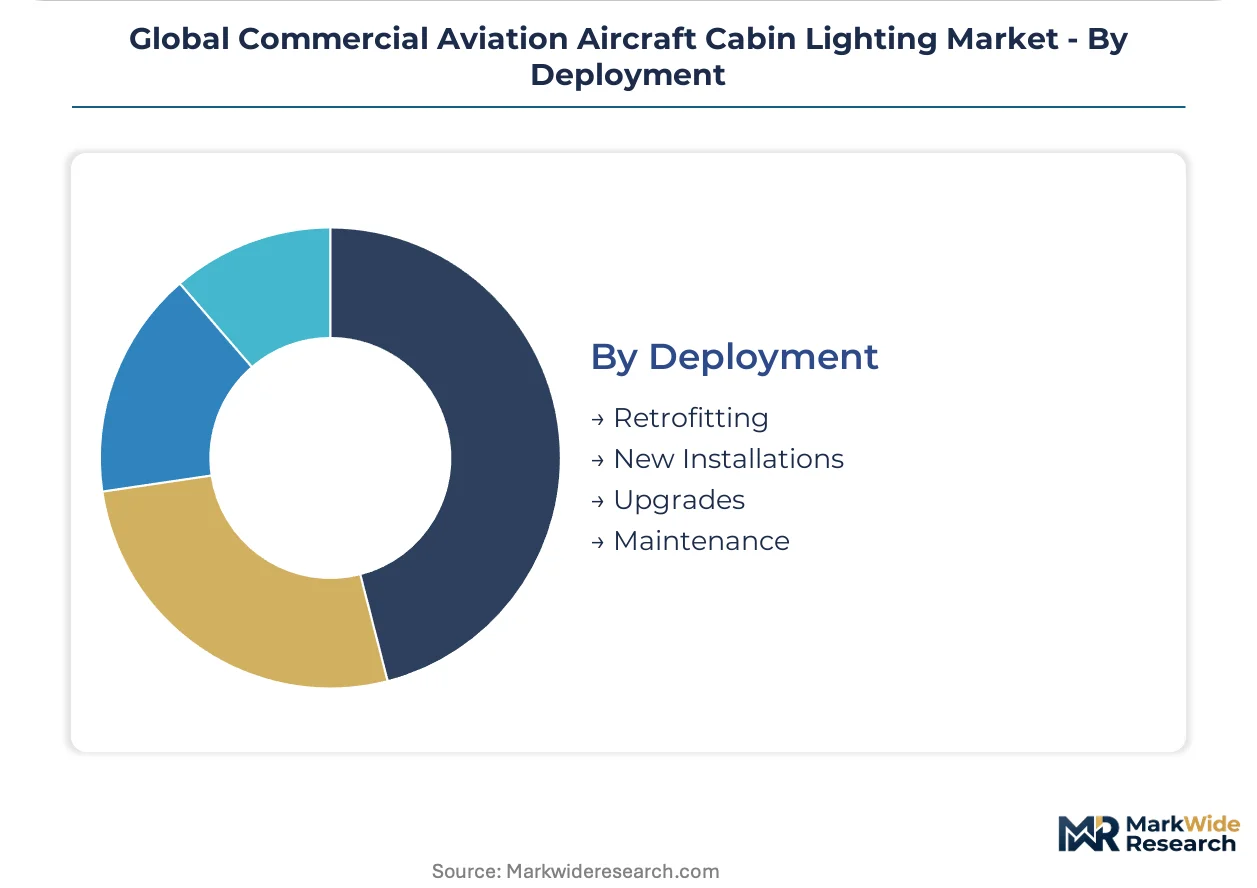
- Retrofitting:In-service modification programs replacing legacy fluorescent and electroluminescent systems. US-registered fleets face FAA airworthiness directive deadlines on flammability testing that compress installation timelines for aging 737 and 767 aircraft.
- New Installations:Line-fit specifications on airframes exiting final assembly lines.
- Upgrades:Mid-life enhancement programs adding functionality to existing LED architectures.
- Maintenance:Component-level replacement preserving original system specifications.
Retrofitting anchors the volume base while new installations gain share at the steepest rate on COMAC delivery scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in aircraft cabin lighting track final assembly line locations and MRO hub concentrations. Germany and France run structural surpluses in engineered luminaire systems, while China's import dependency on high-reliability LED modules persists despite domestic packaging gains. The United States maintains balanced trade in retrofit services against Asian component inflows.
United States
FAA airworthiness directives on flammability testing are compressing replacement timelines for aging 737 and 767 fleets. The agency's 90-second evacuation visibility standards force operators into accelerated upgrade cycles outside scheduled maintenance windows. Wichita's aviation cluster hosts engineering centers where MRO providers integrate programmable scene control with legacy 28V DC distributions.
Germany
EASA CS-25 certification mandates on emergency luminance are driving mood-lighting retrofits across Lufthansa Group's A320neo and A350 families. REACH chemical restrictions on phosphor dopants and solder alloys fragment product lines for European-registered aircraft. Hamburg's final assembly corridor anchors engineering-intensive programs transitioning to RoHS-compliant LED architectures ahead of regulatory deadlines.
China
COMAC delivery scaling absorbs cabin customization packages at rates unmatched by mature markets, with C919 operators specifying circadian-rhythm systems for domestic trunk routes. CAAC alignment with GB reliability benchmarks creates captive demand for locally certified lighting on indigenous airframe programs. Shanghai's Yangtze River Delta cluster concentrates phosphor refining capacity that exposes European luminaire manufacturers to input volatility.
France
Airbus final assembly lines in Toulouse anchor specification-setting power for wide-body premium cabin lighting, where programmable mood sequences differentiate passenger experience on ultra-long-haul routes. ANSM oversight of REACH implementation constrains polymer housing selections for European export configurations. The Occitanie aerospace cluster sustains backward integration into optical engine design for A350 family line-fit contracts.
United Kingdom
STG Aerospace and Cobham Limited heritage positions UK suppliers in emergency egress lighting niche where EASA visibility standards concentrate procurement. Post-Brexit regulatory divergence from EU REACH frameworks complicates cross-border component flows for Northern Ireland assembly operations. Southwest England's defense-aerospace corridor maintains electroluminescent strip production for military derivative programs requiring instant-on reliability.
Global Commercial Aviation Aircraft Cabin Lighting Market Vendor Landscape
Concentration sits with vertically integrated airframe-tier suppliers and specialized cabin systems engineers. The supplier base organizes around three archetypes: avionics-bundling conglomerates with airframe OEM relationships, engineering-intensive German specialists with final assembly line proximity, and component assemblers exploiting LED module cost compression. Dominant competitive moves include strategic partnerships for CAAC certification access and portfolio diversification into smart lighting software layers.
Within the avionics-bundling tier, Collins Aerospace and Honeywell International Inc. occupy positions leveraging flight-deck system integration to capture line-fit contracts on next-generation Boeing and Airbus programs. Diehl Aviation exemplifies the engineering-intensive archetype with sustained programs across German and Chinese final assembly lines. Safran S.A. sits within the diversified aerospace conglomerate category, anchoring its position in mood-lighting retrofits through Zodiac Aerospace heritage capabilities.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran S.A. |
| Astronics Corporation |
| Diehl Aviation |
| Honeywell International Inc. |
| Cobham Limited |
| Luminator Aerospace |
| STG Aerospace Limited |
| Zodiac Aerospace |
| Others |
Supply Flow & Price Mechanics
LED module scale economies at Chinese packaging facilities compress unit costs while simultaneously concentrating upstream phosphor refining capacity, creating asymmetric pricing power that favors buyers with volume commitment leverage and squeezes mid-tier assemblers on margin.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across line-fit programs, with three-tier pricing stratification across premium certified, standard compliant, and economy retrofit tiers. Price differentiation rests on EASA CS-25 certification grade and after-sales service bundling, where European-registered fleet mandates command premiums. Cost compression in LED chip-on-board arrays is intensifying because die-shrink yields improve faster than demand absorption, pressuring luminaire margins. Charter operators and regional carriers exhibit highest price sensitivity, while flag carriers with wide-body premium cabins prioritize circadian-rhythm functionality over unit cost.
Supply Chain Analysis
China and Germany anchor phosphor refining and optical engine production respectively, with Taiwan supplying high-reliability LED die. Rare-earth phosphor processing draws from Jiangxi and Inner Mongolia mining corridors, while precision optics manufacturing rests on Stuttgart-Toulouse supplier networks. Single-source vulnerability concentrates in Chinese rare-earth corridors, exposing European and North American luminaire manufacturers to export quota volatility. Distribution runs through airframe OEM line-fit channels and independent MRO retrofit networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cabin lighting is shifting toward platform-economics dynamics where software-defined scene control and avionics interoperability create winner-take-most contracting structures around Boeing and Airbus ecosystem standards.
For Market Incumbents: Shield line-fit positions on next-generation programs by deepening backward integration into chip-on-board LED die packaging and securing CAAC certification for COMAC C919 family contracts. Counter component-assembler encroachment on wide-body retrofits through exclusive technical support agreements that extend liability windows and raise switching costs for European operators facing EASA deadlines. For New Entrants and Emerging Players: Anchor in narrow-body retrofit whitespace where legacy 737NG and A320ceo fleets resist full smart-lighting upgrades due to 28V DC distribution constraints. Target Indian and Indonesian operators with fluorescent-compatible LED form factors that minimize aircraft downtime. Pursue direct procurement relationships with carrier engineering departments, bypassing OEM service divisions that bundle hardware with inflated support contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart-lighting software layer specialists with airline fleet management system integration, suggesting long-term viability concentrates in platform-enabling technology rather than commodity luminaire hardware. Target acquisition archetypes include chip-on-board optical engine designers with CAAC qualification and cabin management interface software developers. Watch for inflection when COMAC delivery rates force Western suppliers into joint-venture structures for GB standard compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Avionics-Lighting System Integration | Collins Aerospace and Honeywell leverage flight-deck relationships to capture Boeing 777X and Airbus A321XLR line-fit contracts. |
| CAAC Certification Investment | Diehl Aviation and Safran establish Shanghai engineering centers to qualify for COMAC C919 indigenous content mandates. |
| Chip-on-Board Optical Engine Development | Miniaturized LED arrays enable thinner ceiling profiles that reclaim headroom for retrofitted A320neo overhead bin expansions. |
| After-Sales Service Unbundling | Independent MRO providers in China's Yangtze River Delta separate technical support from hardware procurement, compressing upfront capital commitments. |
| REACH-Compliant Material Transition | German final assembly lines reformulate phosphor dopants and solder alloys ahead of EASA chemical restriction deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from airline procurement executives, MRO engineering directors, airframe OEM platform integration teams, and EASA certification specialists, and refined through secondary validation against FAA airworthiness directive filings, EASA CS-25 amendment records, COMAC delivery schedules, and customs trade data on LED module imports. Bottom-up fleet retirement projections and top-down airframe delivery forecasts were triangulated to establish volume anchors.
Variance decomposition across technology adoption curves, regulatory compliance windows, and carrier customization rates shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product architecture, smart versus conventional control systems, end-user fleet scale, and deployment type across retrofit versus line-fit channels. CAGRs were synthesized from installation flow projections and unit value erosion curves, with specific inputs drawn from wide-body premium cabin specification rates and COMAC delivery scaling assumptions.
Material uncertainties — rare-earth export quota disruptions, REACH chemical restriction expansion, and CAAC indigenization policy shifts — sit outside the modeled envelope. Forecasts reflect assumptions about LED cost compression trajectories and regulatory deadline adherence that could revise with supply chain reconfiguration or airframe program delays. Recalibration cycles align with material shifts in phosphor pricing, certification timeline announcements, and COMAC production rate disclosures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Aircraft Interior Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market