
 Thrust Vector Control Market | 2026-2036
Thrust Vector Control Market Size, Share, and Industry Trends Forecast 2026-2036
Thrust Vector Control Market Analysis
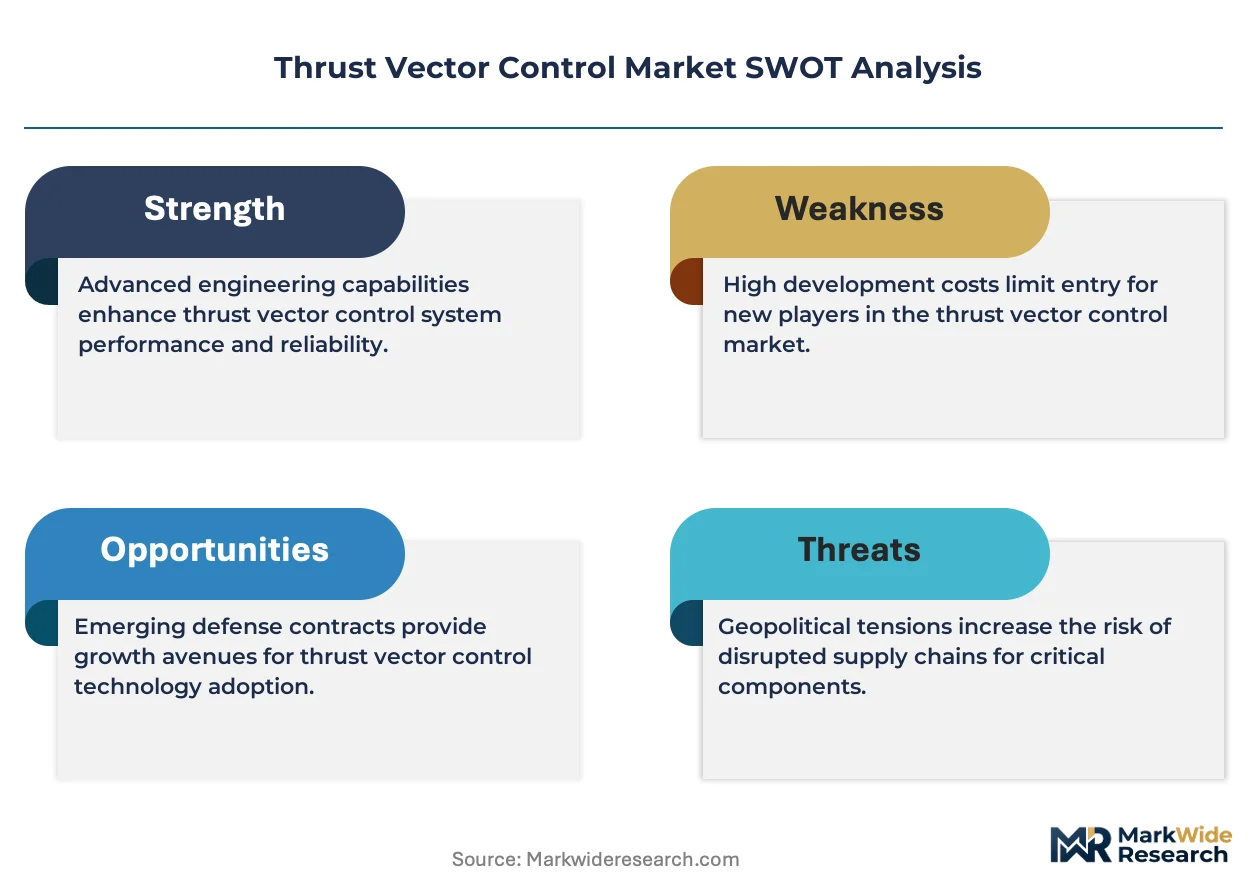
The Thrust Vector Control market is pivoting around a widening capability gap between radiation-hardened digital control systems and legacy electromechanical actuators. Moog Inc. leverages its dominance in precision servo actuation for gimbaled nozzle architectures across multiple defense programs. Honeywell International Inc. sustains technology leadership through in-house production of flight-critical control electronics. BAE Systems Plc anchors European supply chains with specialized military-grade thrust redirection systems.
Thrust vector control encompasses the dynamic manipulation of exhaust nozzle geometry and auxiliary control surfaces to redirect propulsive force and achieve vehicle attitude control during powered flight, typically operating across temperature extremes exceeding 2,500°C and response latencies under 50 milliseconds. Gimbaled nozzle technology occupies the largest installed base due to decades of ballistic missile heritage, while digital control methods are displacing analog architectures fastest in new space launch vehicle programs. Space agencies and defense contractors represent the deepest margin pools because qualification cycles and long-term service contracts lock in supplier relationships for decades.
FAA certification requirements for commercial spaceflight vehicles, ITAR restrictions administered by the US State Department, and EAR dual-use export classifications administered by the Bureau of Industry and Security collectively constrain market access and shape product development roadmaps. EMA and EU AI Act emerging standards for autonomous flight control systems are beginning to influence European qualification protocols. Stakeholders must monitor how proliferating national space launch licensing regimes redefine cross-border component eligibility before committing to platform-specific design investments.
Market Dynamics
The Thrust Vector Control market is being pulled by a fundamental transition from analog electromechanical architectures toward radiation-hardened digital flight control electronics, a shift that requalifies supplier relationships and compresses development timelines across defense and space launch programs.
Growth Catalysts
- ITAR modernization:Streamlined US State Department licensing for allied defense programs accelerates cross-border component flows between American Southwest manufacturers and NATO missile integrators.
- Next-generation missile platforms:Precision maneuvering requirements for hypersonic glide vehicles and advanced ballistic systems drive procurement of multi-axis nozzle actuation systems.
- Silicon carbide power electronics:Wide-bandgap semiconductor adoption in servo motor controllers enables higher switching frequencies and thermal tolerance for gimbaled nozzle drives.
Market Restraints
- Tungsten and rhenium supply concentration:Aerospace-grade refractory metal sourcing concentrates in Chinese and Russian primary extraction, exposing nozzle throat insert producers to export restriction volatility.
- EAR dual-use classification friction:Bureau of Industry and Security commodity jurisdiction determinations delay commercial space vehicle component shipments by 6-18 months.
- Legacy actuator obsolescence:Analog servo valve manufacturers face component discontinuation as semiconductor foundries retire 180nm fabrication lines.
Strategic Opportunities
- Indian space launch expansion:ISRO's SSLV and NGLV programs create qualification pathways for foreign thrust vector control suppliers under offset and technology transfer agreements.
- Reusable launch vehicle retrofits:Grid fin and gimbaled engine integration for Falcon 9-class recovery systems opens aftermarket service contracts for flight-proven actuation hardware.
- EU AI Act autonomous flight provisions:Emerging certification frameworks for self-diagnosing control electronics favor European suppliers with embedded software verification capabilities.
Industry Challenges
- Radiation-hardened ASIC design talent:Qualified integrated circuit architects with aerospace qualification experience command premium compensation and extended recruitment cycles.
- Hot-fire test facility access:Limited static test stand availability at Eglin AFB and Edwards AFB compresses development schedules for new nozzle designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrust Vector Control Market |
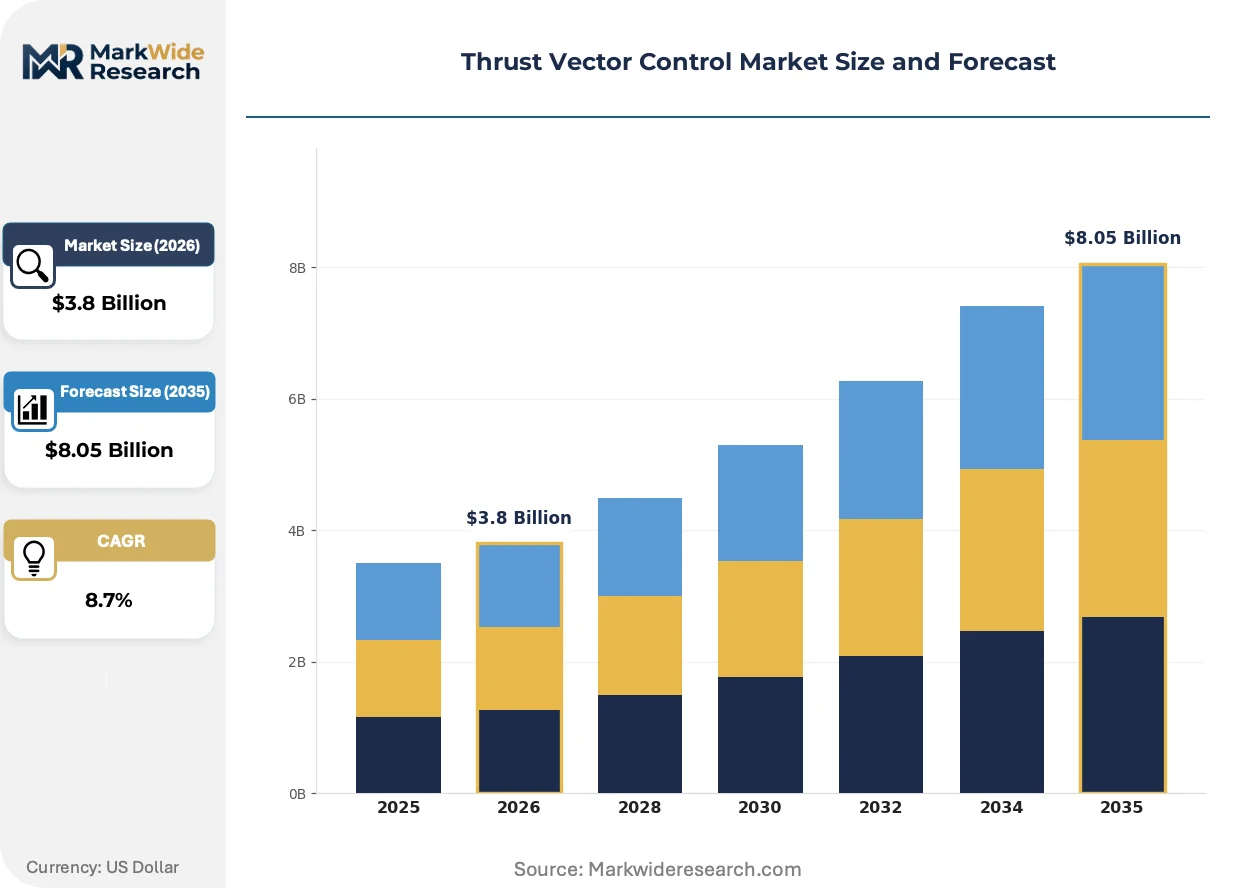
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Gimbaled Nozzle, Variable Nozzle, Thrust Redirection, Control Surfaces Application: Aerospace, Military, Space Exploration, Commercial Aircraft End User: Defense Contractors, Aerospace Manufacturers, Space Agencies, Research Institutions Control Method: Active Control, Passive Control, Hybrid Control, Digital Control |
| Companies Covered | Honeywell International Inc., Moog Inc., BAE Systems Plc, RTX Corporation, Woodward Inc., Northrop Grumman Corp., Collins Aerospace, Parker Hannifin Corporation, Space Exploration Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrust Vector Control Market Emerging Trajectories
Digital control architectures are displacing legacy analog systems across the thrust vector control stack, while additive manufacturing refractory metal techniques and modular qualification approaches reshape how suppliers enter the market.
Model predictive control algorithms with embedded thermal protection logic are expanding into next-generation gimbaled nozzle drives. SpaceX and Blue Origin procurement teams specify these architectures for Starship and New Glenn main engine vectoring. The technology is expanding into previously cost-prohibitive small launch vehicle segments by reducing flight computer redundancy mass.
FAA's updated Part 450 commercial space launch licensing framework tightens flight safety analysis requirements for thrust termination systems. Operators must now demonstrate independent channel verification for all safety-critical actuation commands. Reusable vehicle developers in California and Texas face extended certification timelines as they adapt control electronics to meet deterministic latency specifications.
Defense prime contractors now unbundle long-term sustainment contracts from initial platform awards. Raytheon and Lockheed Martin Missiles and Fire Control have separated actuator overhaul services from new production lots, creating direct procurement relationships between military depots and component OEMs. This pattern concentrates in Arizona and Florida test ranges where missile refurbishment cycles run shortest.
Thrust Vector Control Market Segmentation
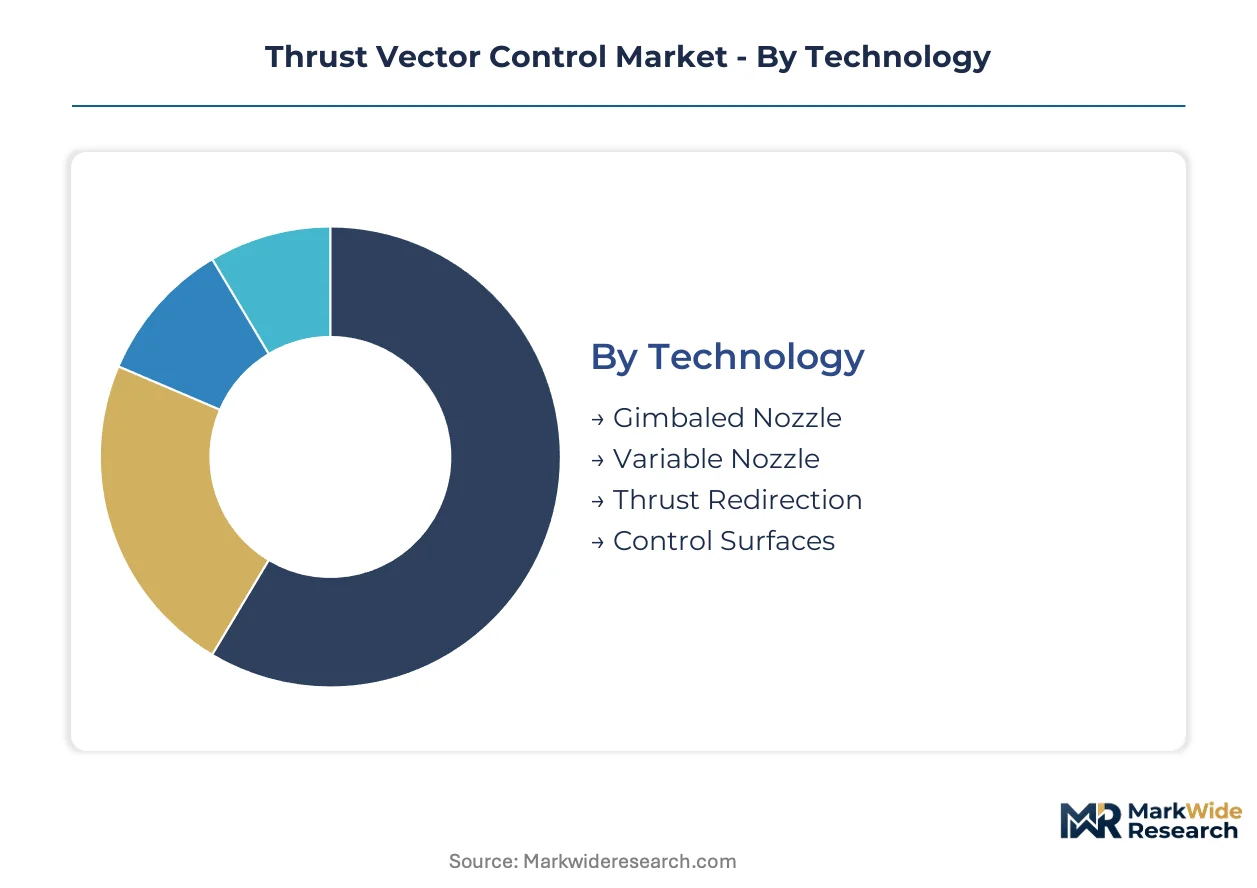
Thrust vector control procurement decisions hinge on thermal tolerance thresholds, qualification heritage, and long-term sustainment liability. Segment boundaries blur as multi-axis digital architectures displace legacy single-purpose actuation systems across defense and commercial programs.
Technology:
Buyer selection prioritizes specific impulse preservation and response latency under extreme thermal cycling.
- Gimbaled Nozzle:Full-hemisphere angular deflection through precision servo actuation maintains exhaust stream coherence across ballistic missile heritage programs. Demand concentrates in Arizona and Texas test corridors where hot-fire qualification infrastructure supports multi-axis validation for next-generation platforms.
- Variable Nozzle:Continuous geometry modulation via sliding sleeve or pintle mechanisms optimizes expansion ratio across altitude regimes. SpaceX Starship and Blue Origin New Glenn specifications drive procurement in California and Texas manufacturing clusters seeking throttle-range flexibility for reusable ascent profiles.
- Thrust Redirection:Auxiliary injection or fluidic deflection methods redirect exhaust momentum without mechanical nozzle articulation.
- Control Surfaces:Aerodynamic vanes and grid fins provide vectoring authority in atmospheric flight phases where nozzle gimbal authority degrades.
Gimbaled Nozzle leads on scale; Variable Nozzle leads on momentum.
Application:
End-use qualification requirements create divergent margin structures and supplier lock-in durations.
- Military:Multi-axis maneuvering for hypersonic glide vehicles and advanced ballistic systems demands ITAR-compliant supply chains with radiation-hardened electronics. Procurement flows through Eglin AFB and Edwards AFB test ranges where electromagnetic pulse resilience is mandatory.
- Space Exploration: Human-rated fault tolerance specifications from NASA Johnson Space Center and FAA Commercial Space Transportation impose deterministic latency ceilings and redundant channel architectures.
- Aerospace:Supersonic business jet and experimental aircraft programs require lightweight electromechanical actuation with rapid prototype-to-flight cycles.
- Commercial Aircraft:Emergency thrust termination and thrust asymmetry compensation systems face FAA Part 25 certification timelines.
Military leads on scale; Space Exploration leads on momentum.
End User:
Contracting mechanisms and intellectual property ownership terms reshape supplier relationship economics.
- Defense Contractors:Raytheon and Lockheed Martin Missiles and Fire Control unbundle sustainment contracts from production awards, creating direct depot-to-OEM procurement channels. Long-term service agreements lock in component suppliers across Arizona and Florida refurbishment cycles.
- Space Agencies:NASA and ISRO qualification pathways emphasize technology transfer provisions and offset agreements that favor suppliers with in-country assembly capabilities.
- Aerospace Manufacturers:Commercial tier-one integrators specify modular control electronics to reduce platform-specific redesign costs.
- Research Institutions:University-affiliated test programs and defense laboratory R&D contracts prioritize rapid iteration over flight-proven heritage.
Defense Contractors lead on scale; Space Agencies lead on momentum.
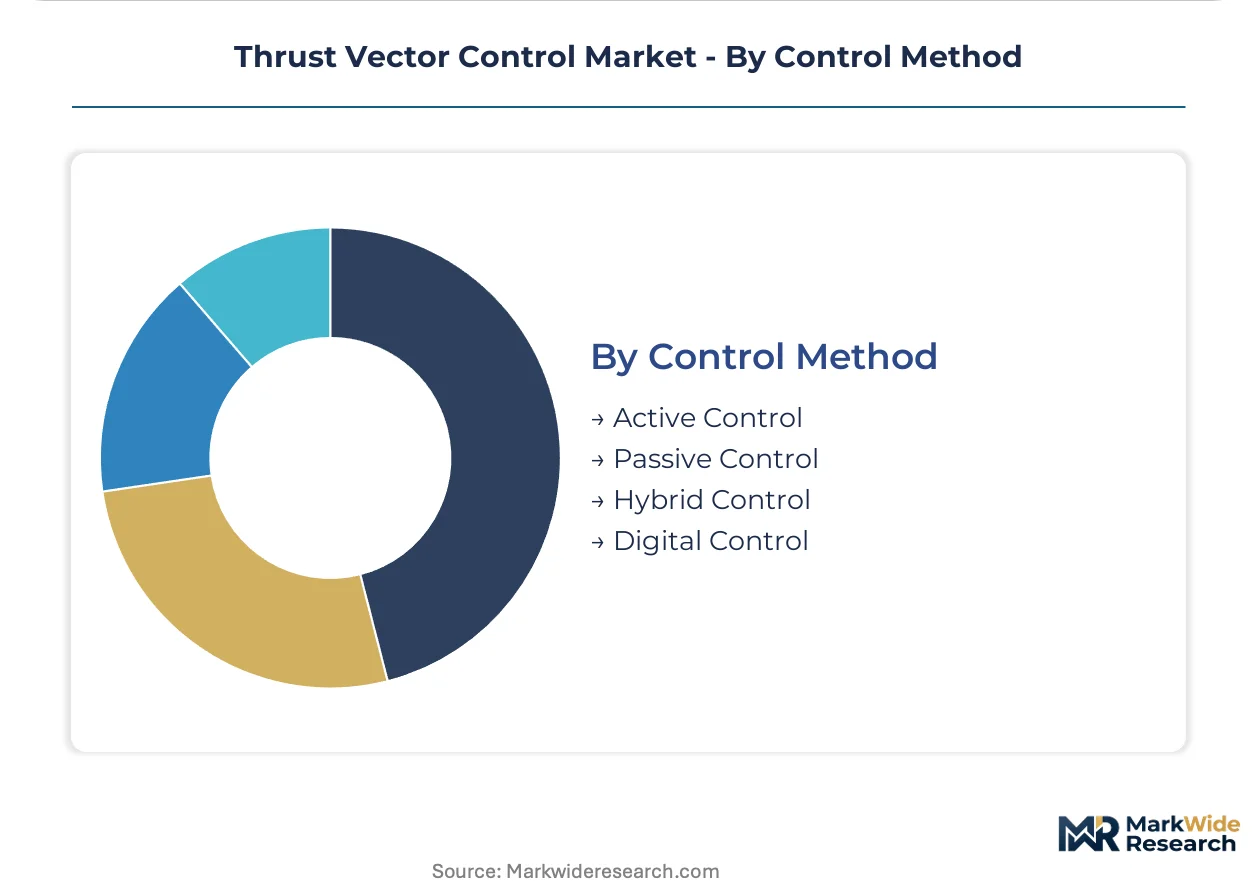
Control Method:
Signal processing architecture determines radiation tolerance, thermal drift compensation, and certification pathway complexity.
- Digital Control:Model predictive algorithms with embedded thermal protection logic displace analog architectures fastest in new space launch vehicle programs. Silicon carbide power electronics enable switching frequencies above 100kHz for gimbaled nozzle servo drives.
- Hybrid Control:Analog front-end signal conditioning with digital back-end processing bridges legacy platform upgrade paths.
- Active Control:Closed-loop feedback with inertial measurement unit integration provides real-time disturbance rejection.
- Passive Control:Fixed geometry or pressure-balanced designs eliminate electronic failure modes in highest-reliability applications.
Digital Control leads on scale; Hybrid Control leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerospace engineers and precision manufacturing technicians concentrate in the American Southwest corridor, anchoring global thrust vector control production capacity. Their expertise in radiation-hardened electronics and high-temperature materials processing sustains the industry's technical frontier.
United States
Defense prime contractors and commercial space operators drive procurement of multi-axis gimbaled nozzle systems for hypersonic and reusable launch platforms. FAA Part 450 commercial space licensing and ITAR State Department controls shape supplier qualification pathways. California, Arizona, and Texas host concentrated manufacturing clusters where hot-fire test infrastructure at Edwards AFB and Eglin AFB validates new actuator designs.
United Kingdom
Specialized military-grade thrust redirection systems serve European missile integrators and NATO defense programs. BAE Systems anchors domestic supply chains with sovereign capability in flight-critical control electronics. Export licensing under UK Strategic Export Controls and alignment with EU dual-use regulations govern cross-border component flows to continental partners.
France
ArianeGroup and defense contractors sustain demand for variable nozzle geometries in space launch and ballistic systems. Direction générale de l'armement procurement frameworks emphasize European sourcing for strategic autonomy. The Paris-Saclay aerospace cluster and Toulouse space corridor concentrate subsystem integration and thermal protection expertise.
India
ISRO's SSLV and NGLV programs create qualification pathways for foreign suppliers under offset and technology transfer agreements. Bureau of Indian Standards and Department of Space regulations govern import substitution timelines for critical flight components. Bengaluru and Sriharikota anchor domestic assembly capabilities with expanding private launch vehicle participation.
Japan
METI space industry development programs and JAXA H3 launch vehicle procurement sustain precision actuator demand. Domestic suppliers emphasize radiation-hardened ASIC design and ceramic matrix composite nozzle components. Nagoya and Tsukuba manufacturing corridors concentrate thermal management and high-reliability electronics production.
Thrust Vector Control Market Vendor Landscape
Top-tier vendors anchor defense and space agency procurement channels, while mid-tier specialists occupy commercial launch vehicle niches and aftermarket sustainment contracts. The vendor base stratifies across ITAR-compliant defense integrators, radiation-hardened electronics specialists, and precision electromechanical fabricators. Two dominant competitive moves are reshaping positioning: long-term service contract unbundling from initial platform awards, and silicon carbide power electronics integration into next-generation servo architectures.
Within the defense prime tier, Honeywell International Inc., Moog Inc., and BAE Systems Plc represent distinct archetypes of competitive positioning. Honeywell exemplifies vertical integration through in-house flight-critical control electronics production. Moog occupies a position centered on precision servo actuation heritage across gimbaled nozzle architectures. BAE Systems anchors European supply chains with specialized military-grade thrust redirection capabilities. These three entities collectively illustrate how qualification heritage and sovereign capability requirements fragment competitive dynamics across Atlantic defense procurement channels.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Moog Inc. |
| BAE Systems Plc |
| RTX Corporation |
| Woodward Inc. |
| Northrop Grumman Corp. |
| Collins Aerospace |
| Parker Hannifin Corporation |
| Space Exploration Technologies Corp. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide power electronics integration simultaneously compresses servo controller unit economics and concentrates procurement leverage among radiation-hardened semiconductor foundries in the United States and Japan. This technology transition feeds back into supplier selection, as buyers with captive qualification heritage command premium positioning while late adopters face extended requalification timelines and cost penalties.
Pricing Analysis
The bundled-vs-unbundled service split between initial platform awards and long-term sustainment contracts now dominates contract structures. Three-tier pricing structure across radiation-hardened, ITAR-compliant, and commercial-grade qualification levels separates defense prime procurement from space agency and research institution buyers. Pricing pressure stems from legacy analog actuator obsolescence as semiconductor foundries retire mature fabrication nodes. Defense contractors exhibit lowest price sensitivity due to locked-in qualification heritage, while commercial launch vehicle developers face acute cost compression.
Supply Chain Analysis
Reverse-logistics flows for flight-proven actuator refurbishment now anchor aftermarket revenue pools, with Raytheon and Lockheed Martin Missiles and Fire Control unbundling overhaul services from new production. Supply concentrates in the United States, United Kingdom, and France where ITAR and EU dual-use regulations govern component eligibility. Aerospace-grade tungsten and rhenium sourcing draws from Chinese and Russian primary extraction, exposing nozzle throat insert producers to export restriction volatility. Distribution runs through defense prime contractor procurement channels and direct depot-to-OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thrust vector control market reads as a late-cycle quality story where radiation-hardened digital architectures displace legacy systems, concentrating margin capture among suppliers with flight-proven heritage and sovereign capability credentials.
For Market Incumbents: To counter silicon carbide power electronics commoditization, deepen backward integration into radiation-hardened ASIC design and secure captive access to hot-fire test infrastructure at Eglin AFB and Edwards AFB. Lock in long-term service contracts with defense depot operators before sustainment unbundling accelerates.
For New Entrants and Emerging Players: The price-point gap between ITAR-compliant defense-grade systems and commercial space launch hardware creates entry corridors. Target Indian space launch expansion under ISRO offset agreements and European autonomous flight certification under EU AI Act provisions. Pursue modular qualification approaches to compress development timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier electromechanical fabricators with legacy actuator heritage but limited digital control electronics capabilities. Long-term viability hinges on technology transition execution across the analysis window. Monitor FAA Part 450 certification timeline compression as an inflection signal for commercial space vehicle supplier qualification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Servo Integration | Wide-bandgap semiconductor adoption enables higher switching frequencies for gimbaled nozzle drives at SpaceX and Blue Origin. |
| Long-Term Sustainment Contract Unbundling | Defense primes separating overhaul services from production awards creates direct depot procurement channels in Arizona and Florida. |
| Radiation-Hardened ASIC Design Investment | In-house integrated circuit production locks in qualification heritage for ITAR-compliant flight control electronics. |
| Indian Offset Agreement Pursuit | ISRO SSLV and NGLV technology transfer provisions open qualification pathways for foreign thrust vector control suppliers. |
| EU AI Act Autonomous Flight Certification | Self-diagnosing control electronics standards favor European suppliers with embedded software verification capabilities. |
Methodological Framework
Multiple input streams — primary interviews with defense procurement officers, space agency qualification leads, and servo actuator engineering directors, plus secondary validation against FAA certification databases, ITAR licensing records, and SEC defense contractor filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement pattern shifts across the American Southwest manufacturing corridor and European missile integrator channels. Secondary sources included customs trade data for refractory metal flows, hot-fire test facility utilization records, and dual-use export classification determinations from the Bureau of Industry and Security.
Cross-referencing historical program award patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application category, end-user contracting mechanism, and control method architecture. CAGRs were derived from program-level procurement visibility and platform production rate assumptions. Industry-specific forecast inputs captured ITAR modernization timeline effects and silicon carbide adoption curves in servo motor controllers.
Caveats apply where tungsten and rhenium export restrictions, FAA Part 450 certification delays, or radiation-hardened ASIC design talent scarcity could materially shift the outlook. Practitioners should monitor Bureau of Industry and Security commodity jurisdiction determination backlogs and legacy semiconductor fabrication line retirement announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Aerospace Nuts Market