
 Asia Pacific Commercial Aircraft Aerostructures Market | 2026-2036
Asia Pacific Commercial Aircraft Aerostructures Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Commercial Aircraft Aerostructures Market Outlook
Chinese state-backed aerostructure producers is decoupling from Western tier-one dependency as COMAC ramps C919 output. Airbus SE leverages its Tianjin final assembly line to anchor composite wing sourcing within the region. Mitsubishi Heavy Industries sustains narrowbody fuselage expertise through sustained defense-aerospace cross-subsidies. TATA Advanced Systems Ltd. competes on titanium machining precision for Boeing 787 pylon structures.
Asia Pacific commercial aircraft aerostructures encompass load-bearing airframe assemblies—fuselage barrels, wing boxes, empennage sets, and landing gear support structures—typically fabricated from aluminum-lithium alloys, carbon fiber reinforced polymers, or titanium forgings through automated fiber placement, high-speed machining, and chemical milling processes, serving to generate lift, enclose payloads, and withstand pressurization cycles across commercial flight envelopes. Fuselage segments command the largest share of material throughput given cylindrical shell complexity and riveted joint density, while composite wings represent the fastest-expanding margin pool as Boeing and Airbus push resin transfer molding for next-generation aspect ratios. Aluminum retains dominance in landing gear and empennage brackets where fatigue resistance and repairability outweigh weight savings.
China's MIIT enforces airworthiness certification standards through CAAC coordination that mandate domestic supplier qualification for COMAC programs, effectively walling off certain component tiers. Japan's METI administers JIS material specifications and export control frameworks that govern titanium alloy flows to Korean and Chinese tier-two fabricators. India's DGCA aligns type certification with EASA benchmarks while BIS imposes localized testing protocols on aluminum plate imports. Stakeholders must monitor how CAAC-EASA reciprocity negotiations evolve, as mutual recognition would unlock European supplier access to Chinese final assembly lines while threatening indigenous tier-three margins.
Market Dynamics
COMAC's C919 production ramp is forcing tier-one suppliers to relocate composite wing fabrication capacity to China's Yangtze River Delta aerospace cluster, restructuring regional procurement corridors around domestic content mandates.
Growth Catalysts
- Narrowbody Fleet Renewal:Southeast Asian low-cost carriers are accelerating component procurement for next-generation single-aisle programs. This demand surge concentrates in fuselage barrel and wing box assemblies.
- MIIT Localization Mandates:China's Ministry of Industry and Information Technology enforces domestic supplier qualification thresholds for COMAC airworthiness certification. Foreign tier-two fabricators must joint-venture with state-backed entities to access final assembly lines.
- Automated Fiber Placement:Carbon fiber reinforced polymer wing manufacturing is reducing labor hours per square meter while improving laminate consistency. Korean and Japanese tier-one suppliers are deploying this technology for Boeing 787 and Airbus A350 derivative programs.
Market Restraints
- Titanium Alloy Supply Concentration:Russian VSMPO-AVISMA historically supplied 30-40% of global aerospace titanium sponge. Western sanctions have forced Japanese and Chinese mills to expand vacuum arc remelting capacity at 40% higher unit cost.
- CAAC-EASA Reciprocity Friction:Mutual recognition delays between China's aviation regulator and the European Union Aviation Safety Agency block European supplier access to Chinese final assembly lines. Indigenous tier-three margins remain protected but certification timelines extend 18-24 months.
- Aluminum-Lithium Plate Shortage:Constellium and Alcoa control 70% of qualified aerospace plate supply. Chinese SMIC and Southwest Aluminum are 3-5 years from achieving equivalent damage tolerance certification.
Strategic Opportunities
- India Titanium Machining:Bangalore and Hyderabad clusters are developing precision forging capabilities for Boeing 787 pylon structures. DGCA alignment with EASA benchmarks enables direct supplier qualification without redundant testing.
- Defense-Aerospace Cross-Subsidies:Japan's METI channels F-X fighter program R&D into commercial narrowbody fuselage expertise. Mitsubishi Heavy Industries sustains composite panel production lines through military volume commitments.
- Resin Transfer Molding Scale-Up:Next-generation aspect ratio wings require out-of-autoclave processing. Korean Air's Busan facility is positioning for Airbus A320neo family winglet and sharklet derivative contracts.
Industry Challenges
- Certification Engineer Scarcity:CAAC and EASA dual-qualified structural analysts command 200% salary premiums. Chinese universities produce 12,000 aerospace graduates annually but fewer than 800 complete airworthiness specialization tracks.
- Legacy Fleet Reverse Engineering:MRO providers in Singapore and Kuala Lumpur struggle to source OEM-approved repair schemes for aging A320ceo and 737NG fuselage sections. Alternative repair methodologies face 14-18 month validation cycles.
- Composite Recycling Infrastructure:Thermoset carbon fiber waste from wing trimming operations lacks economically viable reclamation pathways. Japanese chemical milling facilities report 15-20% scrap rates with landfill disposal as the only current option.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Commercial Aircraft Aerostructures Market |
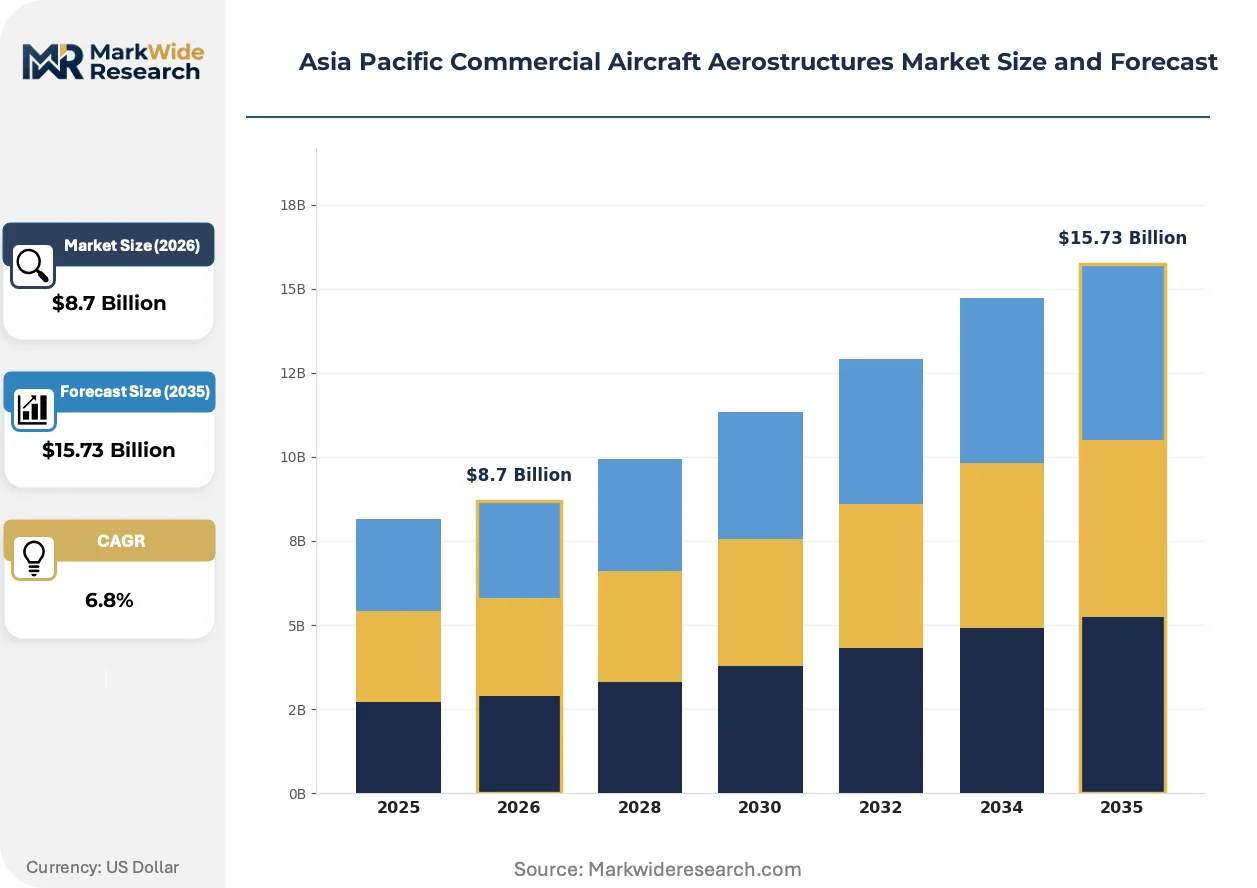
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
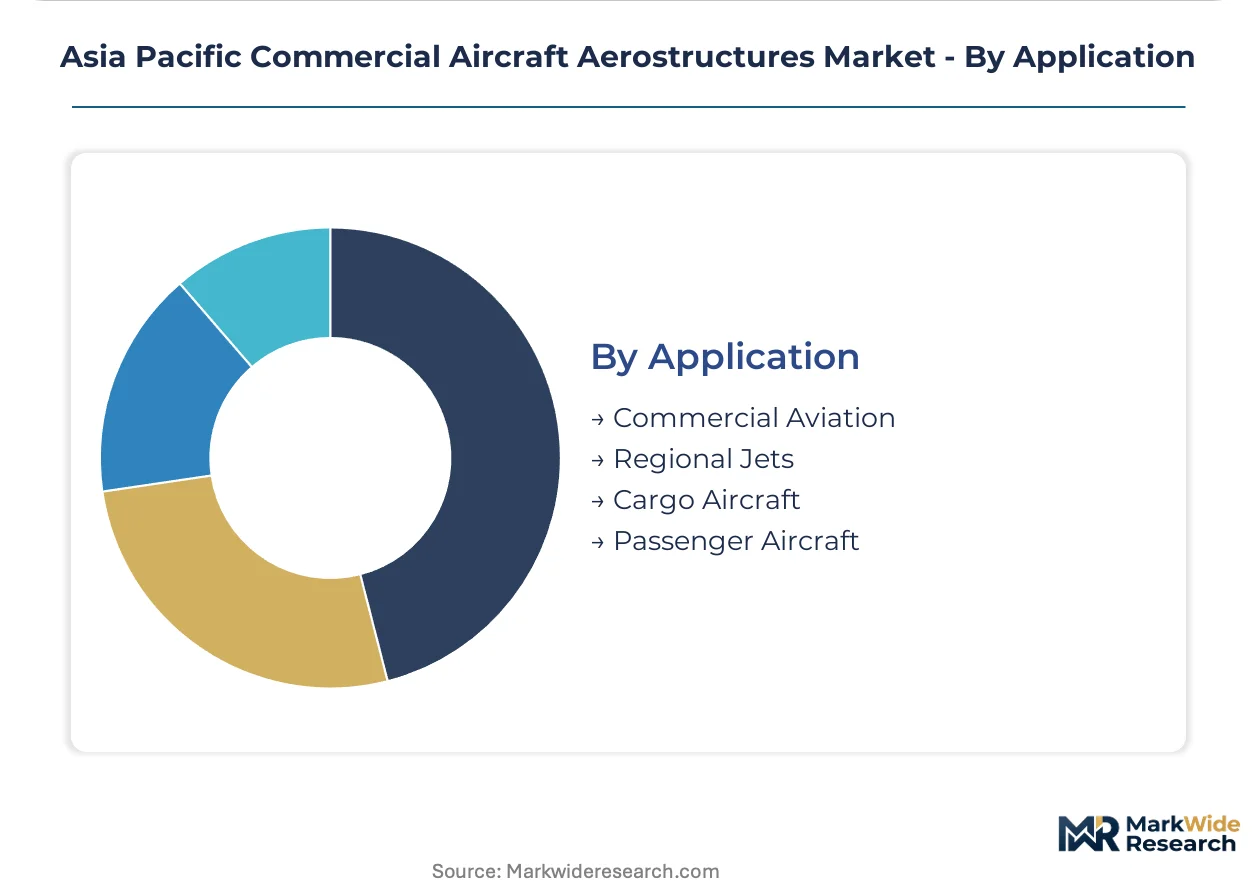
| Segmentation | Product Type: Fuselage, Wing, Empennage, Landing Gear Material: Aluminum, Composite, Steel, Titanium Manufacturing Stage: Design, Assembly, Testing, Repairs Application: Commercial Aviation, Regional Jets, Cargo Aircraft, Passenger Aircraft |
| Companies Covered | Airbus SE, The Boeing Company, Commercial Aircraft Corporation of China (COMAC), TATA Advanced Systems Ltd., Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Korea Aerospace Industries, Aviation Industry Corporation of China (AVIC), Hindustan Aeronautics Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Commercial Aircraft Aerostructures Market Strategic Shifts
Resin transfer molding and thermoplastic welding are compressing wing assembly cycle times while regulatory reciprocity negotiations reshape supplier access corridors across Northeast and Southeast Asian manufacturing hubs.
Thermoplastic composite welding is overtaking mechanical fastening for wing box assembly. Airbus and Boeing derivative programs specify fusion bonding for rib-to-skin joints. Korean tier-one suppliers at Sacheon are installing continuous ultrasonic welding lines to capture A321XLR work packages.
METI's JIS material specifications govern titanium alloy flows to Korean and Chinese tier-two fabricators. Export control frameworks require end-use certification for dual-use aerospace grades. Japanese mills are redirecting sponge supply toward domestic F-X and SpaceJet programs, constraining regional spot market availability.
Airline technical procurement teams are consolidating supplier audits around IAQG 9100 and NADCAP accreditation bundles. Previously fragmented MRO sourcing across Jakarta, Bangkok, and Manila is concentrating through Singapore-based pooled purchasing consortia. Philippine Airlines and VietJet are piloting this model for landing gear overhaul contract negotiation.
Asia Pacific Commercial Aircraft Aerostructures Market Segmentation
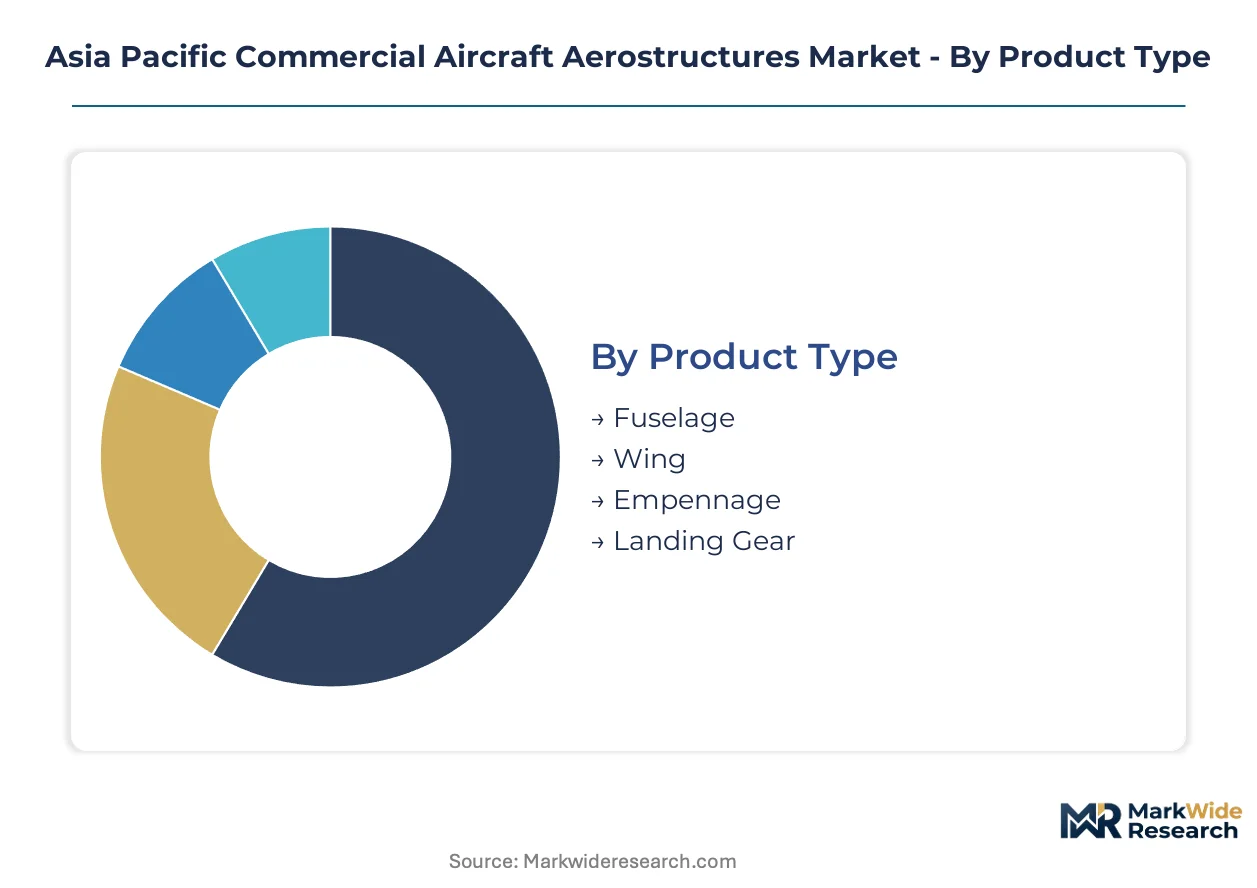
Aerostructure procurement patterns diverge sharply across product architectures and material systems. Component selection dictates tier-one supplier relationships, certification pathways, and final assembly line access within China's Yangtze River Delta cluster.
Product Type:
Fuselage assemblies function as standalone pressure vessels requiring riveted joint expertise, while wing and empennage systems embed into broader lift-generation architectures with deeper composite integration.
- Fuselage:Cylindrical barrel sections fabricated from aluminum-lithium alloys or carbon fiber reinforced polymers enclose passenger cabins and cargo holds. China's COMAC C919 program concentrates demand in the Yangtze River Delta, where MIIT-mandated domestic content ratios force joint-venture structures upon foreign tier-two fabricators.
- Wing:Wing boxes and control surfaces generate primary lift through resin transfer molding and automated fiber placement processes. Korean Air's Busan facility and Japanese tier-one suppliers at Sacheon are capturing Boeing 787 and Airbus A350 derivative work packages as next-generation aspect ratios drive out-of-autoclave processing adoption.
- Empennage:Tail assemblies stabilize aircraft through aluminum or composite horizontal and vertical stabilizers.
- Landing Gear:Forged and machined support structures withstand high-cycle fatigue loads.
Volume placements concentrate in Fuselage; the faster expansion belongs to Wing.
Material:
Material selection stratifies across weight-critical versus fatigue-critical applications, with procurement corridors shifting as sanctions disrupt historical titanium flows.
- Aluminum:Aluminum-lithium alloys dominate fuselage skins and empennage brackets where damage tolerance and repairability outweigh mass reduction. Constellium and Alcoa control qualified aerospace plate supply, while China's SMIC and Southwest Aluminum pursue equivalent certification.
- Composite:Carbon fiber reinforced polymers displace metal in wing boxes through thermoplastic welding and resin transfer molding. Korean tier-one suppliers deploy continuous ultrasonic welding lines for A321XLR rib-to-skin joints, compressing assembly cycle times.
- Steel:High-strength alloys serve landing gear and engine pylon attachment fittings.
- Titanium:Sponge and forging grades withstand thermal and corrosive stresses in engine nacelles and fasteners. Japanese mills redirect supply toward domestic F-X programs as Russian VSMPO-AVISMA sanctions force regional spot market constraints.
Procurement volume clusters in Aluminum; Composite gains share fastest as Boeing and Airbus push resin transfer molding scale-up.
Manufacturing Stage:
Stage sequencing determines CAAC airworthiness certification timelines, with design and testing phases commanding premium engineering margins.
- Design:Structural analysis and digital twin modeling establish load paths and fatigue life predictions. Chinese universities produce 12,000 aerospace graduates annually, yet fewer than 800 complete airworthiness specialization tracks, creating 200% salary premiums for CAAC-EASA dual-qualified analysts.
- Assembly:Automated fiber placement and high-speed machining integrate subcomponents into major assemblies. Airbus leverages its Tianjin final assembly line to anchor composite wing sourcing within the region.
- Testing:Static and fatigue validation protocols verify structural integrity under pressurization cycles.
- Repairs:MRO providers in Singapore and Kuala Lumpur struggle to source OEM-approved repair schemes for aging narrowbody fleets, with alternative methodologies facing 14-18 month validation cycles.
Assembly commands the greatest labor allocation; Design captures the steepest margin expansion as digital engineering penetrates tier-three supplier bases.
Application:
End-use segmentation reflects fleet renewal priorities across Southeast Asian low-cost carriers and Chinese state-backed operators.
- Commercial Aviation:Single-aisle and widebody programs drive fuselage barrel and wing box procurement. Narrowbody fleet renewal across VietJet, Philippine Airlines, and Indonesian Lion Air concentrates component demand in China's Yangtze River Delta aerospace cluster.
- Regional Jets:Smaller gauge aircraft require scaled-down empennage and landing gear structures. Mitsubishi Heavy Industries sustains composite panel production lines through Japan's F-X fighter program cross-subsidies.
- Cargo Aircraft:Freighter conversions and dedicated cargo platforms prioritize floor beam reinforcement and large door cutouts.
- Passenger Aircraft:Cabin pressurization cycles and payload density specifications influence material selection thresholds.
Commercial Aviation absorbs the dominant procurement share; Regional Jets climb fastest as indigenous programs emerge in Japan and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge from Japanese mills and aluminum-lithium plate from Australian bauxite corridors anchor Asia Pacific aerostructure supply chains. China's Yangtze River Delta aerospace cluster concentrates composite wing fabrication capacity under MIIT domestic content mandates. Southeast Asian low-cost carriers drive narrowbody fuselage demand across procurement networks spanning four national manufacturing hubs.
China
COMAC's C919 production ramp consumes fuselage barrel and wing box assemblies from the Yangtze River Delta cluster. MIIT enforces domestic supplier qualification thresholds that force joint-venture structures upon foreign tier-two fabricators seeking final assembly line access. Shanghai and Jiangsu province host automated fiber placement facilities producing carbon fiber reinforced polymer wing structures for indigenous narrowbody programs.
Japan
Mitsubishi Heavy Industries sustains composite panel production lines through METI-administered F-X fighter program cross-subsidies. JIS material specifications govern titanium alloy flows to Korean and Chinese tier-two fabricators under export control frameworks requiring end-use certification. Nagoya and Sacheon aerospace corridors deploy continuous ultrasonic welding lines for A321XLR rib-to-skin joint contracts.
South Korea
Korean Air's Busan facility positions for Airbus A320neo family winglet and sharklet derivative contracts through out-of-autoclave resin transfer molding scale-up. Busan-Ulsan manufacturing belts integrate automated fiber placement technology for Boeing 787 and Airbus A350 derivative work packages. Regional suppliers face titanium sponge constraints as Japanese mills redirect supply toward domestic defense programs.
India
Bangalore and Hyderabad clusters develop precision forging capabilities for Boeing 787 pylon structures through DGCA-EASA alignment enabling direct supplier qualification. TATA Advanced Systems Ltd. competes on titanium machining precision without redundant testing protocols. BIS localized testing requirements on aluminum plate imports constrain raw material sourcing flexibility for tier-three fabricators.
Asia Pacific Commercial Aircraft Aerostructures Market Competitive Environment
Global majors compete with regional champions across certification access and composite manufacturing scale. Airbus SE leverages its Tianjin final assembly line to anchor composite wing sourcing within China while Boeing maintains tier-one relationships across Japanese and Korean supplier networks. Three archetypes dominate: state-backed national champions with defense cross-subsidies, independent tier-one fabricators with OEM direct contracts, and emerging precision machining specialists in titanium and aluminum-lithium alloys. Capacity expansion through automated fiber placement deployment and strategic joint-ventures under MIIT localization mandates represent the dominant competitive moves reshaping procurement corridors.
Among state-backed national champions, Commercial Aircraft Corporation of China (COMAC) and Aviation Industry Corporation of China (AVIC) occupy positions within China's domestic content mandate architecture. Airbus SE and The Boeing Company exemplify global OEM tier-one anchoring strategies across the region's manufacturing clusters. TATA Advanced Systems Ltd. represents the precision machining specialist archetype competing on titanium forging capabilities for Western platform pylon structures.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| Commercial Aircraft Corporation of China (COMAC) |
| TATA Advanced Systems Ltd. |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Korea Aerospace Industries |
| Aviation Industry Corporation of China (AVIC) |
| Hindustan Aeronautics Limited |
| Others |
Value Chain & Pricing Dynamics
COMAC's C919 production ramp is forcing foreign tier-two fabricators into joint-venture structures under MIIT domestic content mandates, compressing margins for Western suppliers while elevating qualified indigenous producers to premium pricing tiers. This procurement corridor restructuring concentrates pricing power among state-backed entities with final assembly line access.
Pricing Analysis
Warranty and airworthiness certification bundling separates qualified suppliers from commodity fabricators, with CAAC-EASA dual-certified analysts commanding 200% salary premiums that flow through to component pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with narrowbody fleet procurement from Southeast Asian low-cost carriers driving cost compression in fuselage barrel assemblies. Price differentiation hinges on automated fiber placement capability and resin transfer molding scale, while margins tighten for aluminum-lithium plate suppliers facing Constellium and Alcoa duopoly constraints. Tier-three fabricators exhibit highest price sensitivity due to BIS localized testing requirements on raw material imports.
Supply Chain Analysis
Reverse logistics for composite wing trimming operations remains underdeveloped, with Japanese chemical milling facilities reporting 15-20% scrap rates and landfill disposal as the only current pathway. Raw material flows draw from Japanese titanium sponge mills, Australian bauxite corridors, and Korean carbon fiber prepreg suppliers, while component fabrication concentrates in China's Yangtze River Delta, Japan's Nagoya-Sacheon corridor, and Korea's Busan-Ulsan belt. Single-source vulnerability permeates qualified aerospace aluminum-lithium plate supply as Chinese mills remain 3-5 years from damage tolerance certification equivalence. Distribution runs through Singapore-based pooled purchasing consortia consolidating previously fragmented MRO sourcing across Jakarta, Bangkok, and Manila.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into titanium sponge vacuum arc remelting and automated fiber placement equipment represents the decisive competitive lever as sanctions disrupt historical Russian supply flows and COMAC domestic content mandates harden.
For Market Incumbents: Anchor composite wing fabrication capacity within China's Yangtze River Delta cluster through MIIT-compliant joint-venture structures to defend final assembly line access against emerging Korean and Japanese tier-one competitors. Invest in CAAC-EASA dual-qualified certification engineering pipelines to offset 200% salary premiums eroding structural analysis margins. Prioritize backward integration into carbon fiber prepreg supply as Korean Air's Busan facility scales resin transfer molding capacity for Airbus derivative programs. For New Entrants and Emerging Players: Capture precision titanium machining contracts for Boeing 787 pylon structures by establishing Bangalore or Hyderabad presence under DGCA-EASA alignment enabling direct supplier qualification without redundant testing. Target India's aluminum-lithium plate testing and certification gap as BIS localized protocols create captive demand for indigenous tier-three fabricators. Lead with defense-aerospace cross-subsidy positioning to sustain production lines through military volume commitments while commercial narrowbody qualifications mature. For Investors and Strategic Acquirers: The window for entry favors automated fiber placement specialists with established OEM relationships and scalable out-of-autoclave processing capabilities. Long-term viability rests on positioning within COMAC's domestic supplier qualification architecture or Airbus-Boeing tier-one anchoring networks. Monitor CAAC-EASA reciprocity negotiation progress as the critical inflection signal—mutual recognition would unlock European supplier access to Chinese final assembly lines while threatening indigenous tier-three margins.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | MIIT-mandated domestic content thresholds force foreign tier-two fabricators into state-backed partnerships for C919 access. |
| Automated Fiber Placement Deployment | Korean and Japanese suppliers compress wing assembly cycle times while improving laminate consistency for Boeing and Airbus programs. |
| Titanium Sponge Capacity Expansion | Japanese and Chinese mills invest in vacuum arc remelting at 40% higher unit cost as Russian VSMPO-AVISMA sanctions constrain supply. |
| CAAC-EASA Dual Certification Investment | Chinese universities produce fewer than 800 airworthiness specialization graduates annually against 12,000 aerospace graduates. |
| Defense-Aerospace Cross-Subsidy Structuring | METI channels F-X fighter program R&D into commercial narrowbody fuselage expertise at Mitsubishi Heavy Industries. |
Study Parameters
Document review covered OEM procurement disclosures, CAAC and EASA airworthiness certification databases, MIIT domestic content mandate filings, and customs trade data, complemented by interviews with tier-one supplier procurement directors, composite manufacturing engineers, CAAC certification specialists, and airline technical fleet managers. Secondary validation drew from aerospace production databases, aluminum and titanium trade flow records, and defense program budget disclosures. Bottom-up component demand modeling triangulated against top-down fleet renewal projections across Southeast Asian low-cost carriers.
Market size and growth outputs reflect segmentation across product type, material system, manufacturing stage, and application, with CAGRs derived from production rate ramp schedules for COMAC C919, Boeing 737 MAX, and Airbus A320neo family programs. Forecast inputs incorporated narrowbody fleet renewal timelines, MIIT localization mandate enforcement trajectories, and resin transfer molding adoption curves for next-generation aspect ratio wings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CAAC-EASA reciprocity negotiations, titanium sponge supply normalization, and aluminum-lithium plate qualification progress at Chinese mills. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Seat Frames Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Inlet Lip Anti-Icing and De-Icing Component Systems Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Aircraft Tube and Duct Assemblies Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market