
 Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market | 2026-2036
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market Insights
The gap between premium-certified and commodity-tier fuselage panel supply is expanding as OEM qualification timelines stretch and raw material traceability requirements tighten. Spirit AeroSystems leverages its position as a tier-one integrator with captive autoclave capacity across multiple sites. GKN Aerospace anchors European supply through its automated fiber placement specialization for single-aisle programs. Hexcel dominates prepreg qualification pipelines, sustaining multi-year offtake agreements with major airframers.
Advanced composite fuselage panel systems for next-generation narrow-bodies consist of cured carbon fiber-reinforced polymer skins bonded to stiffening elements, typically measuring 3-5 millimeters in skin gauge and designed to withstand 18 psi cabin pressure differential plus limit load conditions. These structures replace aluminum alloys to achieve 15-20% weight reduction in barrel and panel architectures for single-aisle aircraft. Carbon fiber material type commands the dominant share of qualification activity and unit value, though thermoplastics represent the fastest-growing segment as out-of-autoclave cycle times attract OEM interest. Automated tape laying leads manufacturing process adoption for large contoured panels, while resin transfer molding captures emerging programs seeking reduced touch labor and improved fiber volume fraction control.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks govern damage tolerance and fatigue life requirements that directly dictate ply schedules, resin selection, and non-destructive inspection protocols for fuselage panels. EPA emissions regulations and REACH chemical restrictions in Europe constrain resin chemistry options, pushing suppliers toward reduced-VOC formulations and bio-based precursor development. Stakeholders must monitor evolving OEM platform decisions and qualification scope for successor narrow-body families, as these commitments will lock in material and process standards for two decades of production.
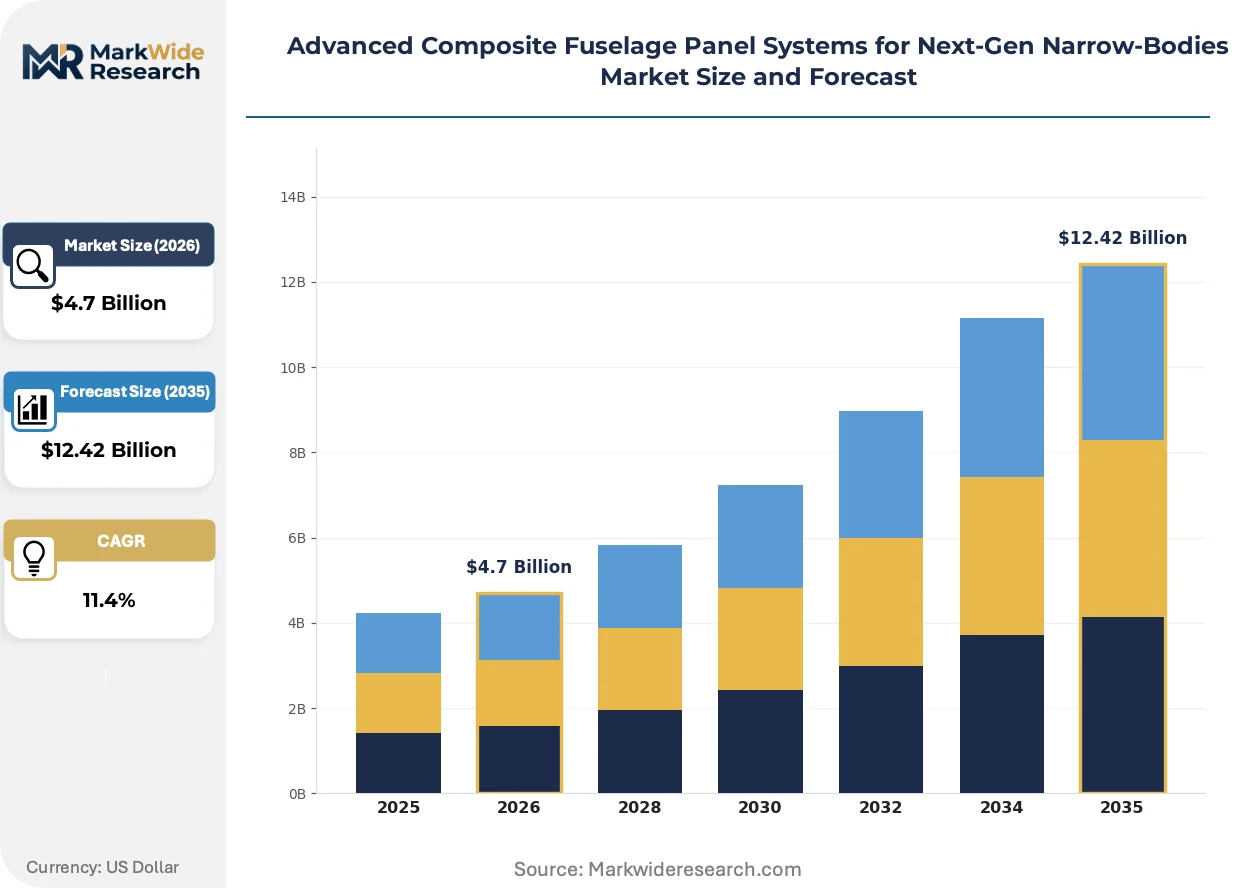
Market Dynamics
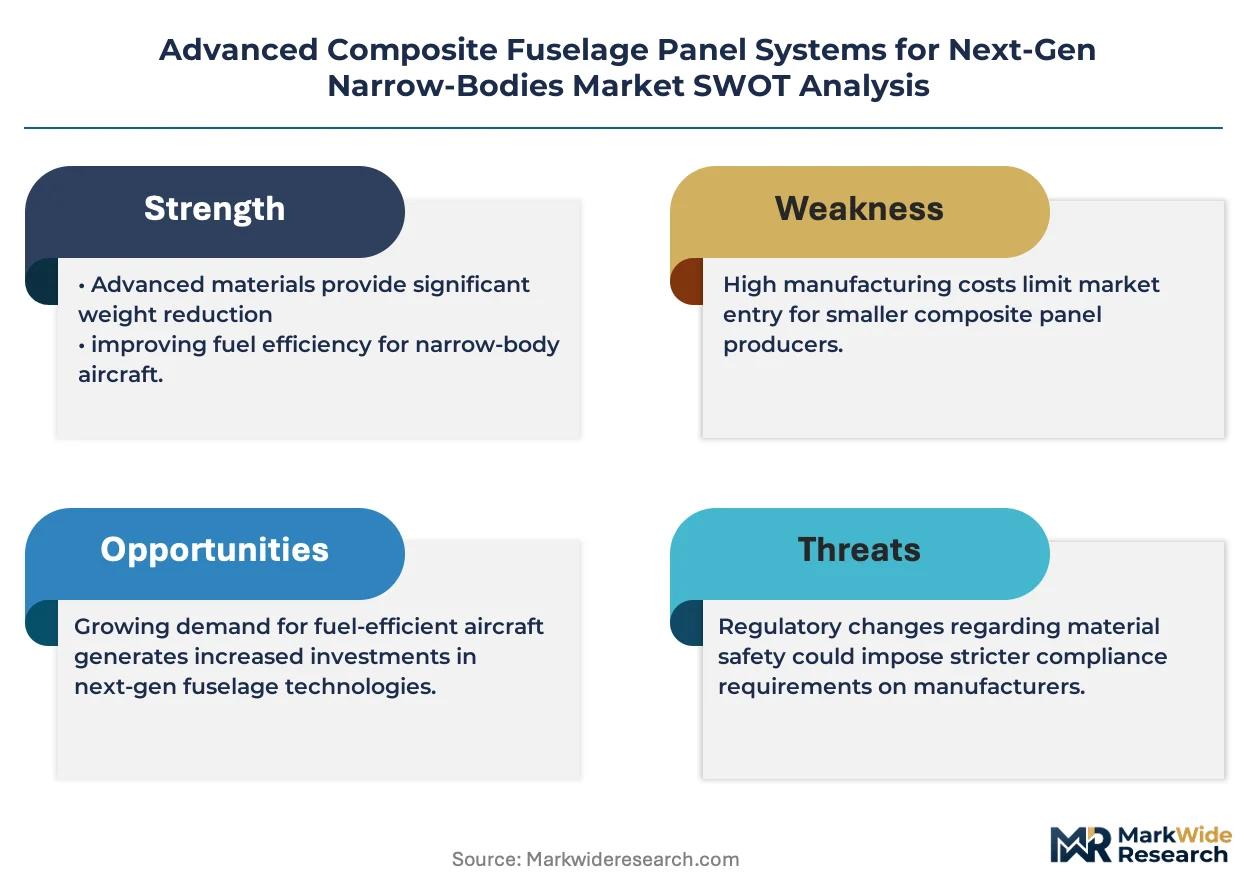
OEM qualification timelines stretching to 36-48 months for new material systems are compressing supplier margins and accelerating consolidation among tier-two prepreg converters unable to sustain dual-track R&D and production investments.
Growth Catalysts
- FAA damage tolerance mandates:Airworthiness standards for 18 psi cabin pressure differential and limit load survivability compel carbon fiber adoption over aluminum alloys in single-aisle barrel sections.
- Thermoplastic out-of-autoclave cycles:PEEK and PPS matrix systems cut cure times from 8 hours to 45 minutes, attracting Boeing and Airbus evaluation for successor narrow-body families.
- United States manufacturing concentration:Wichita, Kansas and Charleston, South Carolina clusters anchor Boeing supplier ecosystems with captive autoclave capacity and trained composite workforces.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs fluctuate with propylene feedstock markets, squeezing prepreg margins when oil benchmarks exceed $80 per barrel.
- Single-source qualification risk:Hexcel and Toray control 70% of aerospace-qualified PAN precursor supply, creating concentration exposure for tier-one integrators.
- REACH chemical restrictions:ECHA substance of very high concern listings constrain bisphenol-A epoxy formulations, forcing reformulation investments without performance guarantees.
Strategic Opportunities
- India narrow-body assembly:Tata-Airbus joint venture in Vadodara creates demand for localized fuselage panel supply as domestic content requirements tighten.
- Resin transfer molding scale-up:Liquid molding processes enable 40% fiber volume fraction control with reduced touch labor for emerging single-aisle programs.
- EU Green Deal sustainable aviation fuels linkage:Bio-based precursor development aligns with EASA environmental certification incentives for reduced-lifecycle-emission airframes.
Industry Challenges
- NDE technician scarcity:Ultrasonic and thermography inspection certification programs produce fewer qualified personnel than autoclave capacity expansion requires.
- Dual qualification burden:Simultaneous FAA Part 25 and EASA CS-25 certification campaigns demand parallel documentation systems, stretching engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.42 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites, Thermoplastics Application: Passenger Cabin, Cargo Hold, Wing-Fuselage Fairing, Tail Cone, Cockpit Section Manufacturing Process: Resin Transfer Molding, Automated Tape Laying, Resin Infusion, Compression Molding, Vacuum Bagging End User: Aircraft OEMs, Tier-1 Suppliers, Aircraft Retrofitters, Component Assemblers |
| Companies Covered | Airbus Atlantic, Spirit AeroSystems, GKN Aerospace, Daher, Hexcel, Toray Industries, Toray Advanced Composites, Syensqo, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market Trends and Innovations
Automated fiber placement and thermoplastic welding are displacing conventional hand layup and mechanical fastening across narrow-body fuselage production, compressing cycle times while elevating capital intensity barriers for new entrants.
Out-of-autoclave thermoplastic composites are converging with induction welding for stiffener-to-skin joints. Airbus and Boeing supplier development teams evaluate PEEK-based panels for 2028-2032 service entry targets. This convergence is collapsing the traditional 12-month tooling lead time for barrel section assembly fixtures.
EPA emissions regulations and REACH chemical restrictions are constraining epoxy resin chemistry options. Suppliers reformulate toward reduced-VOC systems and bio-based alternatives. European prepreg manufacturers face the steepest compliance costs as ECHA substance evaluations expand.
Airline procurement teams now mandate 20-year material traceability and digital thread documentation for damage tolerance claims. Long-term offtake agreements with raw material suppliers replace spot purchasing. United States carriers lead this documentation intensity, followed by Lufthansa Technik-influenced European operators.
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market Segmentation
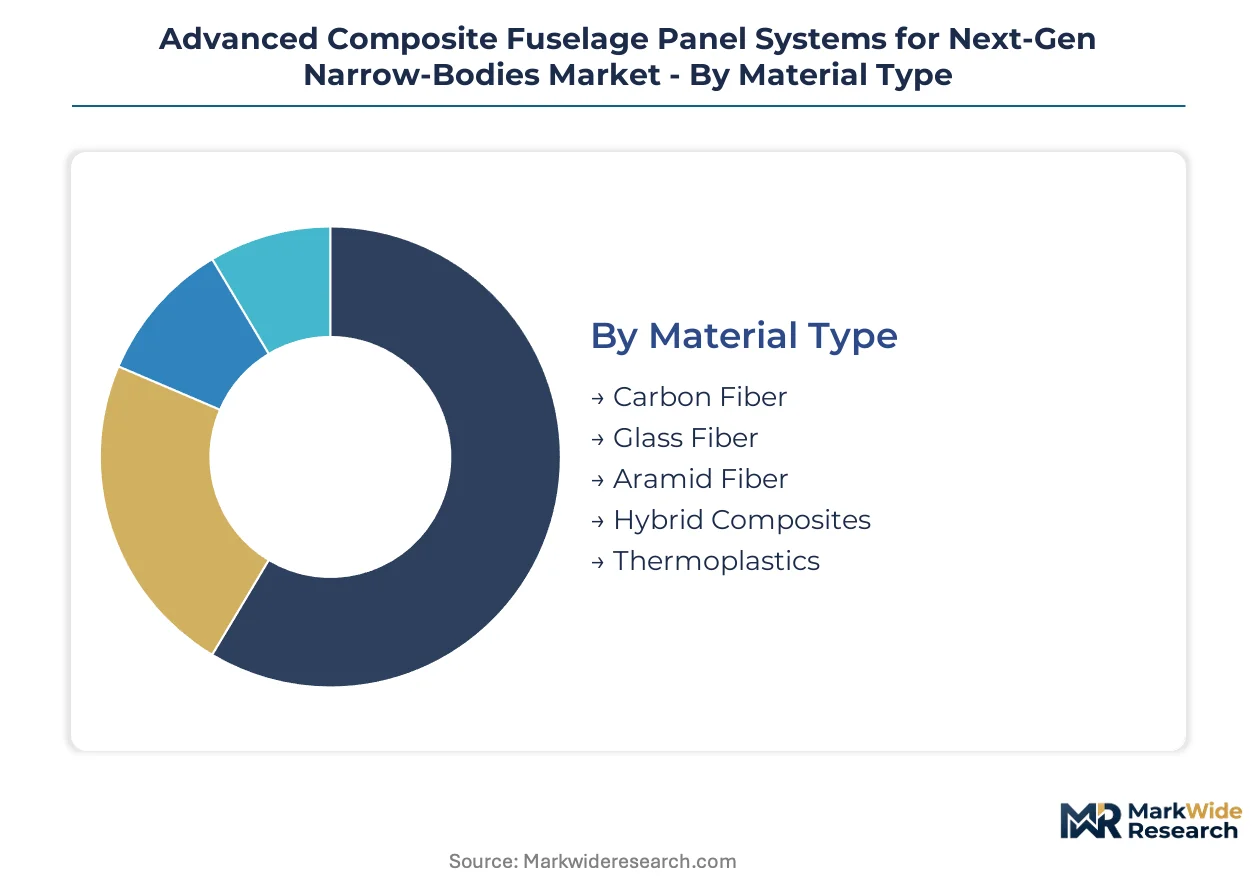
Fuselage panel segmentation reveals how OEM platform decisions cascade through material specifications, manufacturing investments, and supplier qualification burdens. Each dimension carries distinct margin profiles and capital intensity requirements that shape competitive positioning.
Material Type:
Customization intensity varies sharply across this category, from qualified legacy systems to emerging formulations requiring multi-year certification campaigns.
- Carbon Fiber:PAN-based prepreg systems dominate current narrow-body programs with established damage tolerance databases. Boeing 737 MAX and Airbus A320neo families anchor demand in Wichita, Kansas and Hamburg, Germany supplier clusters, though acrylonitrile price volatility squeezes margins when oil benchmarks spike.
- Thermoplastics:PEEK and PPS matrix systems enable out-of-autoclave processing with 45-minute cure cycles versus 8-hour thermoset equivalents. Airbus and Boeing supplier development teams are evaluating these panels for successor narrow-body families, attracted by reduced energy consumption and recyclability alignment with EU Green Deal targets.
- Glass Fiber:Lower-cost reinforcement for non-structural fairings and interior panels where electromagnetic transparency matters.
- Aramid Fiber:Ballistic protection layers in cockpit sections and engine nacelle adjacent structures.
- Hybrid Composites:Tailored fiber combinations optimizing cost-performance tradeoffs for specific load paths.
Most installed capacity flows through Carbon Fiber. Expansion is steepest in Thermoplastics.
Application:
Cost tier segmentation separates flight-critical primary structure from secondary panels with relaxed qualification requirements.
- Passenger Cabin:Pressure-bearing barrel sections require 18 psi differential containment plus limit load survivability under FAA Part 25 and EASA CS-25 mandates. These panels command premium pricing and multi-year offtake agreements.
- Cargo Hold:Lower pressure differential requirements permit lighter ply schedules and reduced inspection protocols, opening volume opportunities for second-source suppliers.
- Wing-Fuselage Fairing:Aerodynamic smoothing panels with complex double-curvature geometries favor automated fiber placement specialization.
- Tail Cone:Tapered geometries with stiffness-driven designs concentrate demand in specialist tooling houses.
- Cockpit Section:Bird-strike and hail-impact resistance requirements drive hybrid material stacks with aramid layers.
Revenue concentration sits in Passenger Cabin applications. Fastest volume growth is occurring in Cargo Hold segments as e-commerce freight conversions expand.
Manufacturing Process:
Volume scalability separates capital-intensive automated lines from labor-dependent methods struggling with NDE technician scarcity.
- Automated Tape Laying:Multi-axis gantry systems deposit pre-impregnated tape across large contoured molds with precision fiber orientation control. Spirit AeroSystems and GKN Aerospace have anchored capacity in this segment for single-aisle programs.
- Resin Transfer Molding:Liquid molding achieves 40% fiber volume fraction with reduced touch labor, attracting emerging programs seeking cost positioning below established thermoset panels.
- Resin Infusion:Vacuum-assisted processes for medium-volume production with lower capital barriers than automated alternatives.
- Compression Molding:Thermoplastic-specific high-pressure forming for PEEK and PPS matrix systems.
- Vacuum Bagging:Manual layup methods constrained to prototyping and low-rate specialty production.
Capital deployment concentrates in Automated Tape Laying. Resin Transfer Molding is climbing the fastest as OEMs seek labor cost reduction.
End User:
Customer type segmentation maps to radically different procurement patterns, from multi-decade platform commitments to spot-market retrofit demand.
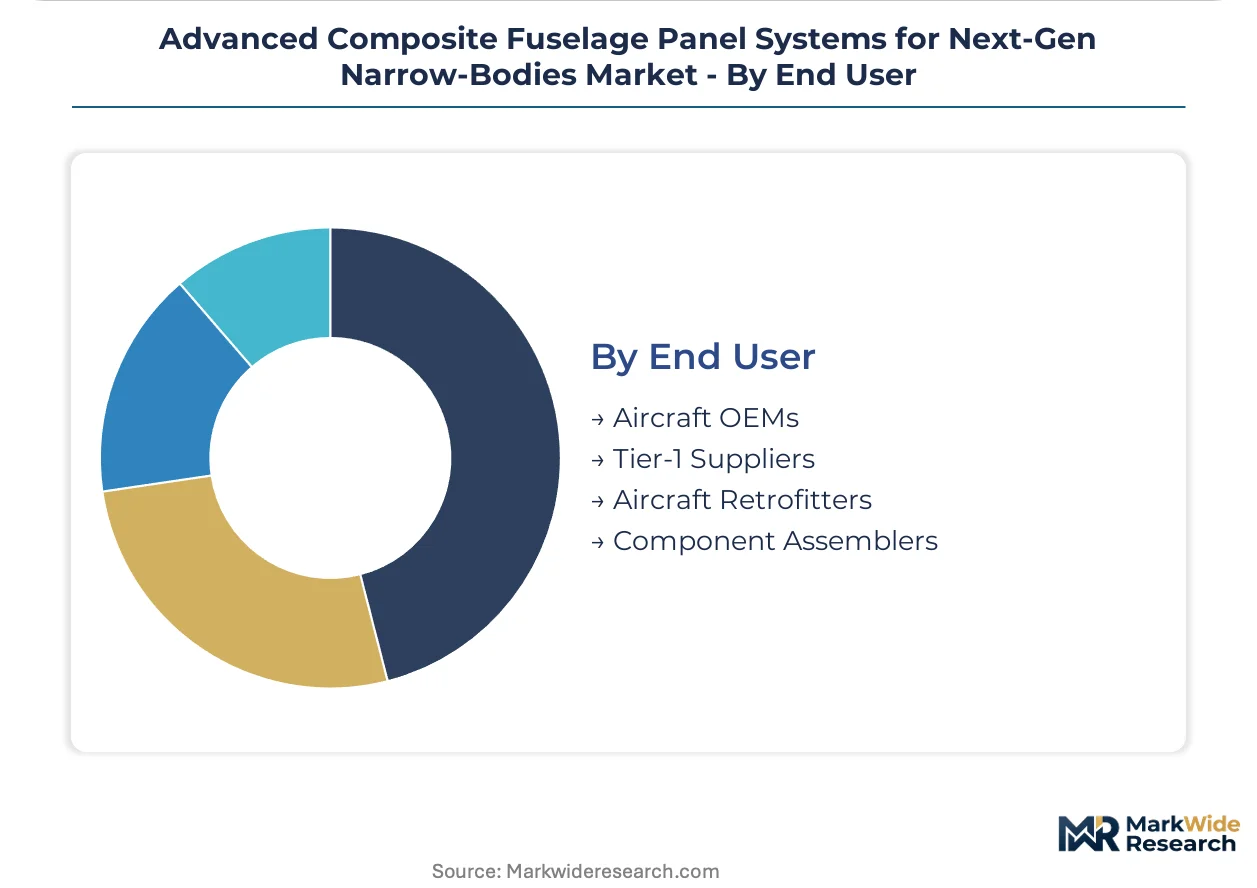
- Aircraft OEMs:Boeing and Airbus drive material qualification pipelines with 20-year traceability mandates and digital thread documentation requirements for damage tolerance claims.
- Tier-1 Suppliers:Spirit AeroSystems, GKN Aerospace, and Leonardo consolidate panel integration risk while managing captive autoclave networks across multiple sites.
- Aircraft Retrofitters:Fragmented demand for cargo conversion and passenger-to-freighter programs with compressed lead times and reduced certification scope.
- Component Assemblers:Sub-tier specialists handling stiffener bonding, edge trimming, and finish operations under OEM-directed supply agreements.
Procurement volume flows through Tier-1 Suppliers. Direct OEM engagement is expanding most quickly as platform decisions consolidate supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates Airbus Atlantic's advanced composite operations, while the United States anchors Boeing's supplier ecosystem with parallel autoclave networks in Kansas and South Carolina.
United States
FAA Part 25 certification mandates drive demand for damage-tolerant fuselage architectures in Wichita, Kansas and Charleston, South Carolina manufacturing clusters. The FAA's continued emphasis on 18 psi cabin pressure differential survivability compels carbon fiber adoption over legacy aluminum. Boeing supplier ecosystems in these locations maintain captive autoclave capacity and trained composite workforces for single-aisle programs.
France
Airbus Atlantic's integration of aerostructures capabilities sustains demand for automated fiber placement specialization in Nantes and Saint-Nazaire. EASA CS-25 frameworks parallel FAA requirements while REACH chemical restrictions push reformulation toward reduced-VOC epoxy systems. The country's prepreg manufacturers face compliance investments as ECHA substance evaluations expand.
Germany
Airbus Hamburg final assembly lines anchor demand for qualified fuselage panel supply in Northern Germany. The country's national aviation regulator enforces EASA certification standards with additional scrutiny on damage tolerance documentation. Supplier clusters in Bremen and Augsburg specialize in automated tape laying equipment and NDE inspection protocols.
Japan
Toray Industries' PAN precursor production sustains aerospace-qualified carbon fiber supply chains for export to Western airframers. METI industrial policy supports advanced materials R&D through targeted funding mechanisms. Nagoya-area manufacturing concentrations serve as technical service hubs for Asian airline customers seeking composite repair capabilities.
India
Tata-Airbus joint venture activity in Vadodara creates emerging demand for localized fuselage panel fabrication as domestic content requirements tighten. The country's national aviation regulator aligns certification protocols with EASA standards to facilitate export qualification. Gujarat state industrial corridors attract composite manufacturing investments targeting narrow-body assembly integration.
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market Competitive Landscape
Top-tier vendors anchor qualification-intensive supply relationships with Boeing and Airbus, while mid-tier prepreg converters struggle against 36-48 month material certification timelines. The market structure concentrates around tier-one integrators with captive autoclave networks and raw material suppliers controlling PAN precursor supply. Three archetypes dominate: aerospace-qualified prepreg manufacturers, automated fabrication specialists, and full-service aerostructures integrators. Competitive moves center on backward integration into precursor supply and strategic partnerships for out-of-autoclave thermoplastic development.
Within the integrator tier, Spirit AeroSystems and GKN Aerospace exemplify capital-intensive positioning through multi-site autoclave capacity and automated fiber placement specialization. Hexcel occupies a distinctive position as a prepreg qualification gatekeeper with multi-year offtake agreements anchoring raw material flows. These three companies represent the dominant competitive archetypes: captive manufacturing networks, process automation leadership, and material science control.
| Leading Market Players |
|---|
| Airbus Atlantic |
| Spirit AeroSystems |
| GKN Aerospace |
| Daher |
| Hexcel |
| Toray Industries |
| Toray Advanced Composites |
| Syensqo |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Captive autoclave networks at tier-one integrators anchor both supply security and premium pricing power in fuselage panel procurement. Spirit AeroSystems and GKN Aerospace leverage in-house curing capacity across Wichita, Kansas and Charleston, South Carolina to command long-term offtake premiums from Boeing and Airbus while insulating against spot-market acrylonitrile volatility.
Pricing Analysis
Capacity additions in South Carolina and Gujarat are reshaping price floors for commodity-tier panels even as FAA-qualified carbon fiber prepreg maintains contract-based long-term offtake premiums. Pricing stratifies across damage-tolerance-certified primary structure, standard-grade cargo hold panels, and economy-tier retrofit applications. Cost compression in thermoplastic out-of-autoclave systems is intensifying because PEEK and PPS matrix suppliers compete for 2028-2032 platform slots. Aircraft retrofitters exhibit highest price sensitivity; Boeing and Airbus direct procurement teams show lowest sensitivity due to 20-year traceability mandates.
Supply Chain Analysis
Regional distribution centers in Wichita, Hamburg, and Nagoya feed hub-and-spoke patterns to final assembly lines. Supply concentrates in the United States, Japan, and France for aerospace-qualified PAN precursor and prepreg conversion. The chain draws from acrylonitrile feedstocks, epoxy resin formulations, and automated tape laying equipment. Single-source vulnerability at the Hexcel-Toray precursor duopoly creates concentration exposure. Distribution runs through tier-one integrators with captive logistics networks rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic cycle-time reductions and out-of-autoclave energy savings are expanding margin capture for suppliers who qualify early on successor narrow-body platforms. Premium-tier shifts toward damage-tolerance-certified primary structure reward qualification investments with decade-long offtake security.
For Market Incumbents: Deepen backward integration into PAN precursor supply or secure multi-year resin offtake agreements to defend against acrylonitrile price volatility. Expand automated fiber placement capacity in Charleston, South Carolina to capture Boeing's next-generation single-aisle volume. Lock in thermoplastic welding process patents before 2028 platform decisions crystallize supplier tiers. For New Entrants and Emerging Players: Cargo conversion specialists represent an underserved buyer archetype with compressed lead times and reduced certification scope compared to OEM direct procurement. Target India's Tata-Airbus Vadodara ecosystem as domestic content requirements tighten. Lead with resin transfer molding cost positioning below established thermoset panel suppliers. For Investors and Strategic Acquirers: Roll-up economics work for automated fabrication specialists because 36-48 month OEM qualification timelines prevent rapid organic entry. Platform standardization across Boeing and Airbus successor families will concentrate supplier bases over a 5-10 year horizon. Watch for thermoplastic qualification announcements as the inflection signal for process-automation acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Hexcel and Toray's PAN duopoly creates margin capture for captive acrylonitrile sourcing. |
| Out-of-Autoclave Thermoplastic Scale-Up | PEEK and PPS systems align with EU Green Deal energy reduction targets for EASA certification. |
| Automated Fiber Placement Capacity Expansion | Spirit AeroSystems' multi-site gantry networks secure Boeing single-aisle panel demand. |
| India Localization Partnership | Tata-Airbus Vadodara assembly triggers domestic content requirements for Gujarat manufacturing. |
| Resin Transfer Molding Process Investment | Liquid molding achieves 40% fiber volume fraction with reduced touch labor for emerging programs. |
Research Methodology
Direct dialogue with tier-one aerostructures procurement directors, FAA certification engineers, composite materials R&D leads, and airline fleet planning executives grounded the qualitative foundation. Secondary validation drew from FAA Part 25 airworthiness directives, EASA CS-25 certification databases, EPA emissions filings, and REACH substance restriction updates. Bottom-up build-ups of autoclave capacity and prepreg qualification pipelines were cross-checked against top-down OEM platform delivery schedules.
Bottom-up segment modeling by material type, manufacturing process, and end-user category fed value projections across the analysis window. The analytical framework incorporated carbon fiber versus thermoplastic adoption curves, automated tape laying versus resin transfer molding capital intensity differentials, and tier-one integrator versus direct OEM procurement mix. CAGRs were derived from platform production rate assumptions and content-per-aircraft estimates for successor narrow-body families.
Underlying measurement precision varies by segment; thermoplastic emerging qualification activity carries wider uncertainty bands than established carbon fiber prepreg volumes. Forecasts reflect documented assumptions around Boeing and Airbus platform launch timing, oil price scenarios affecting acrylonitrile input costs, and ECHA substance evaluation outcomes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Aerospace and Defense C-Class Parts Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Europe Drone Motor Market