
 Aircraft Insulation Market | 2026-2036
Aircraft Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Insulation Market Analysis
Aerogel is hardening its position as the preferred replacement for heavier fiberglass blankets in thermal protection systems, cutting weight by substantial margins on long-haul platforms. DuPont leverages its polymer science heritage to supply high-performance barrier films that integrate with composite insulation stacks. BASF SE anchors European supply through its engineered foam formulations certified to multiple aviation fire standards. Triumph Group competes as a tier-one aerostructures integrator with in-house insulation installation capabilities at its Texas and Connecticut facilities.
Aircraft insulation encompasses engineered materials and multi-layer systems designed to manage heat flux, attenuate noise, inhibit flame propagation, and damp structural vibration across airframes, with typical thermal conductivity specifications below 0.025 W/m·K for advanced systems and operating temperature ranges spanning -55°C to 1,100°C depending on engine-proximity placement. Foam formulations dominate volume shipments for cabin sidewall and overhead applications where acoustic absorption coefficients above 0.85 are required, while aerogel commands premium positioning in engine nacelle and auxiliary power unit compartments where space constraints and thermal extremes converge. The application dimension shows fire protection materials outpacing acoustic segments in value growth as regulatory test protocols tighten post-certification compliance burdens on retrofit fleets.
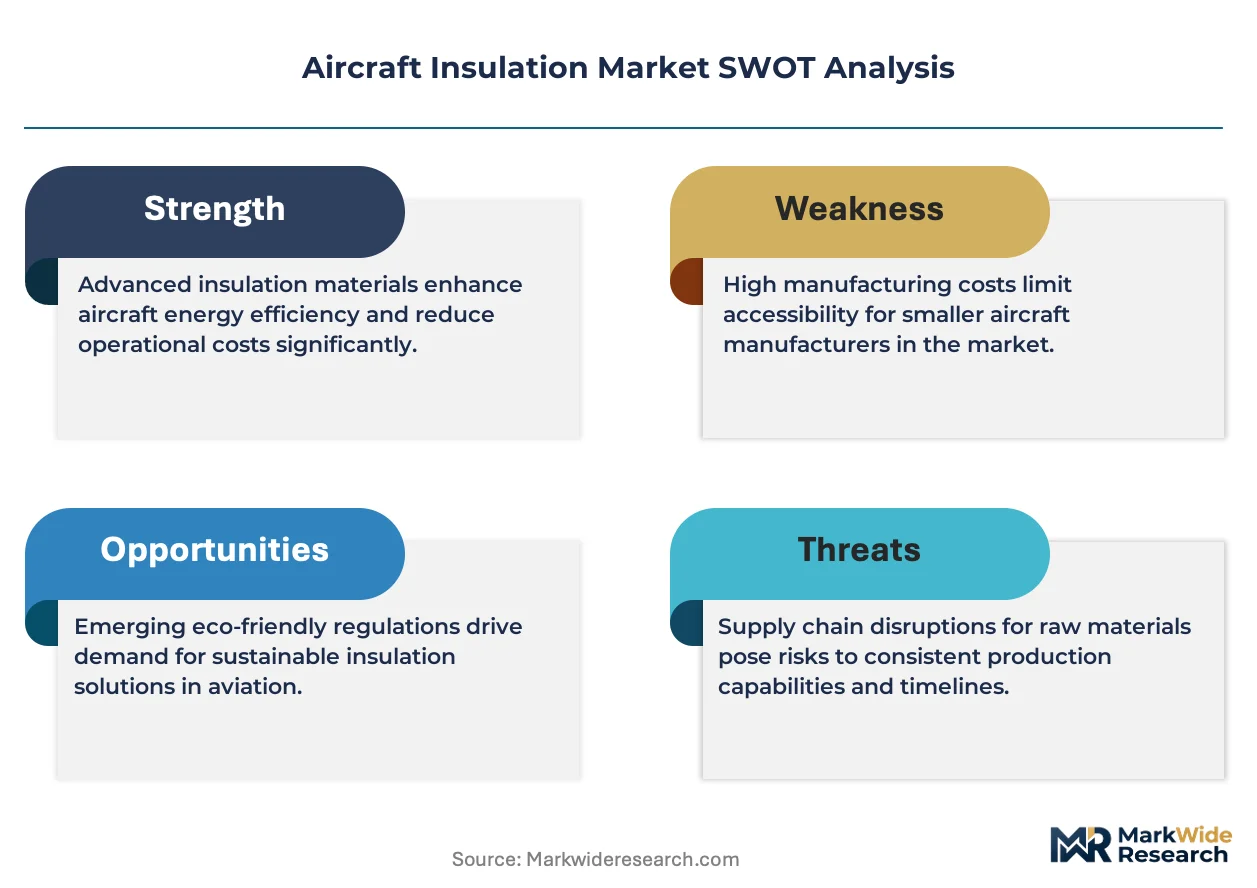
FAA Part 25.856 fire-blocking standards and EASA CS-25 Appendix F test methods shape material selection by mandating 12-second vertical burn resistance and heat-release limits that exclude conventional petroleum-based foams from new type certificates. The EU Green Deal's industrial emissions framework and REACH chemical restrictions are pressuring European suppliers to reformulate halogenated flame retardants out of production lines. Stakeholders must monitor pending updates to ISO 2685 fire-containment test protocols and decide on qualification investments before revised editions lock in competitive positioning across OEM supply bases.
Market Dynamics
Fire-blocking regulatory stringency is compressing material qualification timelines while simultaneously fragmenting supplier bases, as FAA Part 25.856 and EASA CS-25 Appendix F test protocols now exclude legacy foam chemistries from new type certificates.
Growth Catalysts
- FAA Part 25.856 Mandates:Fire-blocking standards for thermal/acoustic insulation now require 12-second vertical burn resistance, forcing OEM procurement toward certified aerogel and ceramic fiber stacks.
- Commercial Narrow-Body Ramp:Boeing and Airbus production rate increases for next-generation single-aisle programs are pulling insulation volume through tier-one aerostructures integrators.
- Silica Aerogel Maturation:Manufacturing scale-up of ambient-dried aerogel blankets is reducing unit costs for engine nacelle thermal protection systems.
Market Restraints
- Petrochemical Feedstock Volatility:Polyimide and polyetherimide foam precursors track benzene and propylene pricing, compressing formulation margins for engineered insulation suppliers.
- Qualification Concentration Risk:FAA-approved fire-test laboratories in Wichita, Seattle, and Montreal create bottlenecks for new material certifications.
- Technical Substitution Ceiling:Aerogel brittleness limits deployment in high-vibration zones where flexible fiberglass retains structural integrity.
Strategic Opportunities
- APAC MRO Expansion:Singapore and Guangzhou maintenance facilities are retrofitting wide-body fleets with lightweight insulation during heavy checks.
- Urban Air Mobility Thermal Management:Electric vertical takeoff aircraft require compact thermal runaway containment systems adjacent to battery packs.
- EU Green Deal Chemistry Incentives:REACH-compliant halogen-free flame retardant formulations qualify for accelerated OEM qualification pathways.
Industry Challenges
- Multiphysics Simulation Talent Gap:Coupled thermal-acoustic-structural modeling for insulation stack optimization requires scarce aerospace materials engineers.
- Certification Timeline Compression:ISO 2685 fire-containment protocol updates demand requalification investments before competitive positioning locks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Insulation Market |
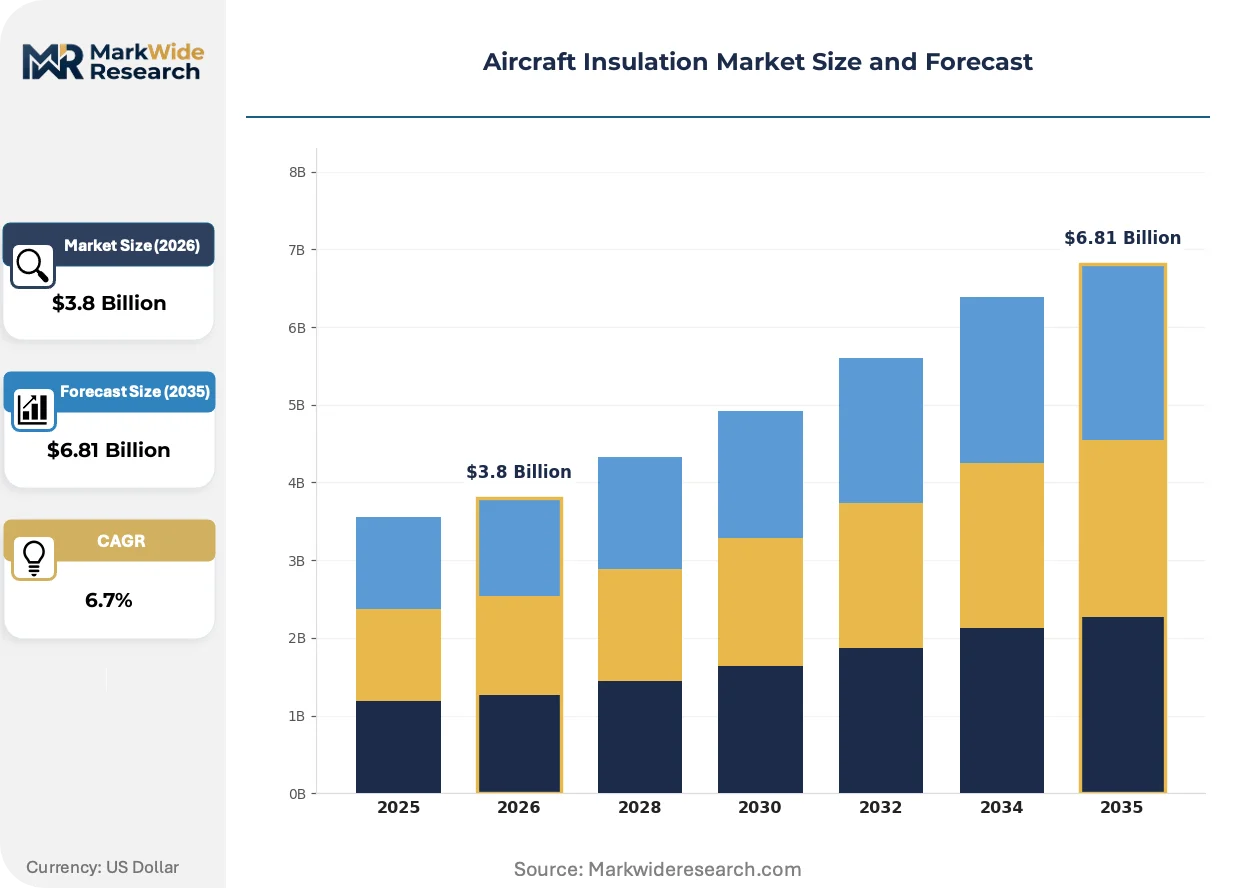
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Fiberglass, Mineral Wool, Aerogel Application: Thermal, Acoustic, Fire Protection, Vibration Damping Aircraft Type: Commercial, Military, Cargo, Private End User: OEMs, Maintenance Providers, Refurbishment Companies, Airlines |
| Companies Covered | DuPont, BASF SE, Triumph Group, Rogers Corporation, Safran Group, Transdigm Group, Zotefoams, Duracote Corporation, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Insulation Market Emerging Trajectories
Material science convergence with digital qualification workflows is collapsing development cycles for next-generation insulation systems while redistributing competitive advantage toward vertically integrated compounders.
Ambient-pressure dried silica aerogel is decentralizing thermal protection system design by enabling conformable blankets that match complex nacelle geometries without rigid panel constraints. Engine manufacturers are adopting these formulations for auxiliary power unit compartments where space allowances tightened across recent platform generations. This material transition is decentralizing supply chain power from traditional fiberglass weavers toward specialty chemical compounders with sol-gel processing expertise.
EASA's tightening of CS-25 smoke-density limits through 2025 implementation timelines is forcing reformulation of phenolic resin binders in European-produced insulation cores. Manufacturers serving Airbus final assembly lines in Toulouse and Hamburg must demonstrate optical density readings below 200 in four-minute tests. The acoustic foam segment bears the heaviest compliance burden, with several incumbent formulations failing revised Appendix F protocols without halogenated flame retardant redesign.
Airline procurement departments are consolidating insulation specifications across mixed fleets to reduce MRO inventory complexity, compressing supplier bases toward full-stack providers. Single-source contracts covering thermal, acoustic, and fire-blocking materials are displacing discrete component purchasing for cabin retrofit programs. This consolidation pattern is most visible among US network carriers operating Boeing 737 MAX and Airbus A320neo mixed fleets from consolidated maintenance hubs in Dallas-Fort Worth and Charlotte.
Aircraft Insulation Market Segmentation
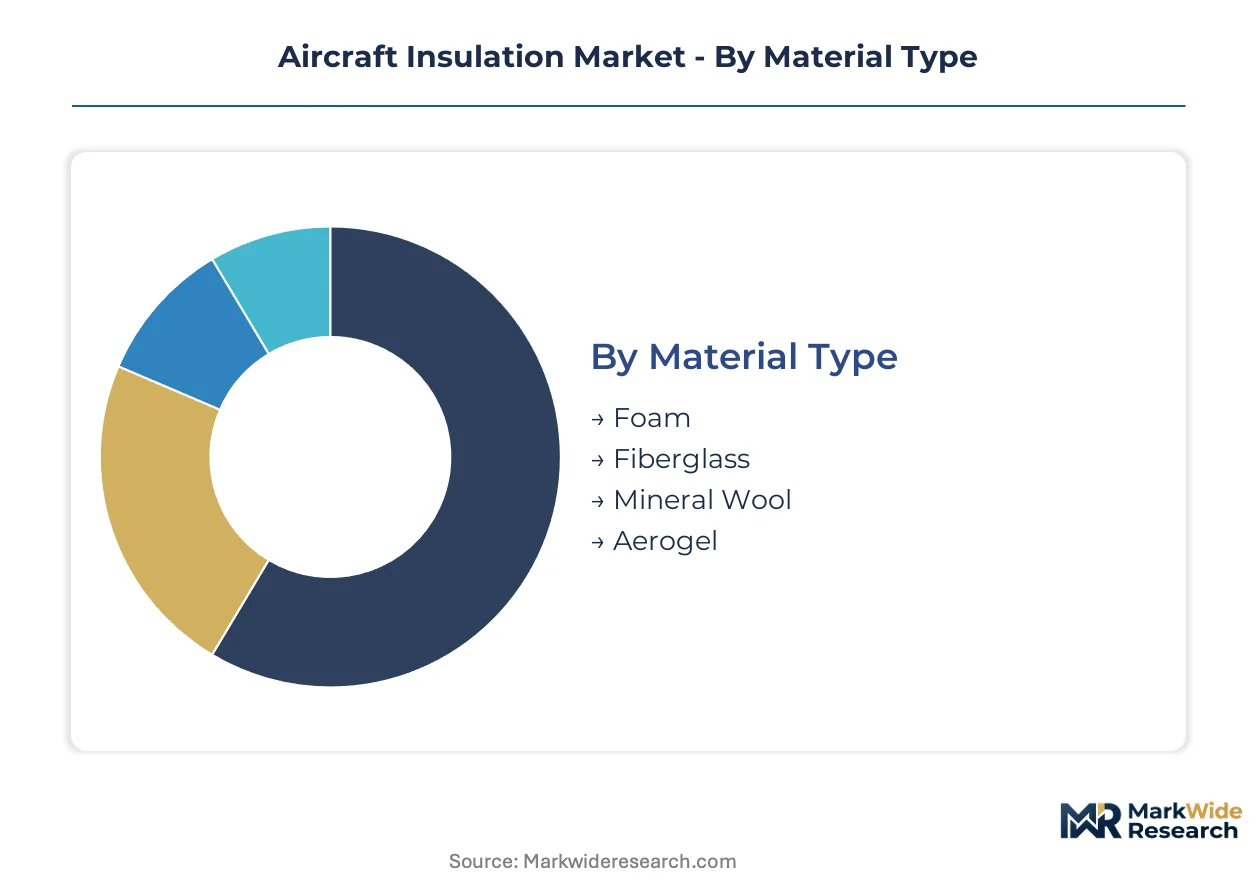
Aircraft insulation segmentation reveals how material science, regulatory pressure, and platform economics intersect. Procurement decisions increasingly favor integrated thermal-acoustic-fire systems over discrete components, compressing supplier bases toward full-stack providers.
Material Type:
Thermal conductivity specifications and fire-blocking certification status separate premium formulations from commodity alternatives.
- Aerogel:Silica-based blankets with thermal conductivity below 0.020 W/m·K enable conformable nacelle geometries without rigid panel constraints. Boeing's 737 MAX and 777X programs specify ambient-dried aerogel for auxiliary power unit compartments where space allowances tightened across platform generations. FAA Part 25.856 certification timelines favor established sol-gel processors with fire-test laboratory relationships in Wichita and Seattle.
- Foam:Polyimide and polyetherimide formulations dominate cabin sidewall and overhead volumes where acoustic absorption coefficients above 0.85 are mandatory. EASA CS-25 Appendix F smoke-density limits through 2025 implementation timelines force phenolic resin binder reformulation for European-produced cores serving Airbus final assembly lines in Toulouse and Hamburg.
- Fiberglass:Flexible woven blankets retain structural integrity in high-vibration zones where aerogel brittleness limits deployment. Legacy narrow-body retrofit programs specify fiberglass for cost-sensitive MRO procurement.
- Mineral Wool:Basalt and slag wool formulations offer intermediate thermal performance for cargo compartment fire-blocking where weight constraints relax relative to passenger cabin specifications.
Mature deployment sits with fiberglass across retrofit fleets. Newer deployment is concentrated in aerogel as next-generation narrow-body programs ramp production.
Application:
Functional requirements determine stack complexity and certification burden, with fire protection commanding premium pricing relative to acoustic-only systems.
- Fire Protection:Multi-layer barrier films and intumescent coatings must demonstrate 12-second vertical burn resistance per FAA Part 25.856. Heat-release limits exclude conventional petroleum-based foams from new type certificates, concentrating procurement toward ceramic fiber and aerogel stacks.
- Thermal:Engine nacelle and thrust reverser applications specify operating temperature ranges spanning -55°C to 1,100°C depending on proximity to hot-section components. Silica aerogel maturation through ambient-pressure drying is reducing unit costs for these high-performance zones.
- Acoustic:Open-cell melamine and polyurethane foams absorb broadband noise in cabin sidewalls and overhead stowage compartments. EASA's tightening smoke-density standards impose the heaviest compliance burden on this segment, with several incumbent formulations failing revised protocols without halogenated flame retardant redesign.
- Vibration Damping:Constrained-layer polymer composites and viscoelastic interlayers reduce structural resonance in fuselage skins and floor beams. Military rotorcraft applications specify these materials for mission equipment bay protection.
Volume concentration rests with acoustic systems across commercial cabin retrofits. Value expansion is climbing the fastest in fire protection as regulatory test protocols tighten post-certification compliance burdens.
Aircraft Type:
Platform economics and production rates determine insulation specification consolidation versus customization.
- Commercial:Narrow-body programs at Boeing's Renton and Airbus's Hamburg final assembly lines anchor insulation consumption. Mixed fleet operators consolidate specifications across 737 MAX and A320neo platforms to reduce MRO inventory complexity at consolidated maintenance hubs.
- Military:Survivability requirements and electromagnetic shielding specifications drive specialized multi-functional insulation stacks. Thrust vectoring nozzles and afterburner sections demand ceramic fiber systems with extended temperature capability.
- Cargo:Main-deck fire suppression integration and lower passenger-safety certification burdens permit simplified thermal-acoustic configurations. Converted freighter programs at Singapore and Guangzhou facilities specify cost-optimized retrofit packages.
- Private:Custom cabin interiors and VIP completion centers in Wichita and Savannah source boutique acoustic treatments with premium aesthetic finishes. Low production volumes sustain discrete component purchasing rather than full-stack consolidation.
Procurement scale concentrates with commercial platforms. Specification innovation is gaining share fastest in private aviation where completion centers differentiate through cabin quietness claims.
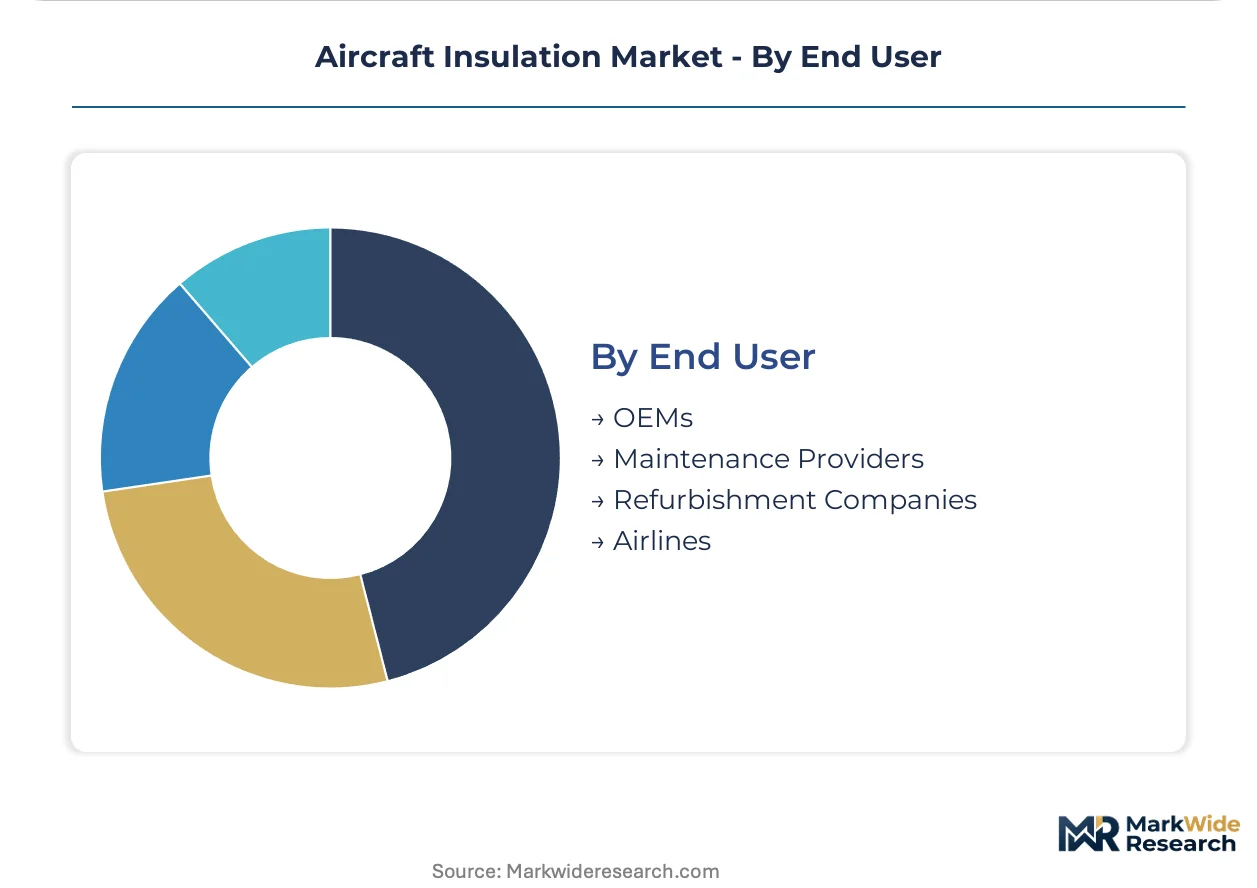
End User:
Supply chain position determines whether insulation is specified at original design or adapted through lifecycle maintenance events.
- OEMs:Boeing and Airbus engineering teams specify insulation stacks at type certificate stage, locking supplier relationships for program lifecycles. Fire-blocking material qualifications for new platforms require 18-24 month certification timelines through FAA-approved laboratories.
- Maintenance Providers:Heavy check facilities in Dallas-Fort Worth and Charlotte retrofit mixed fleets with consolidated insulation specifications. Singapore and Guangzhou MRO centers specialize in wide-body thermal protection system replacement during C-check intervals.
- Refurbishment Companies:Cabin reconfiguration specialists source acoustic and aesthetic insulation for interior modernization programs. VIP completion centers demand rapid-turn customization with boutique material finishes.
- Airlines:Procurement departments increasingly negotiate direct insulation supply agreements to bypass tier-one aerostructures integrator markups. Single-source contracts covering thermal, acoustic, and fire-blocking materials are displacing discrete component purchasing.
Specification authority rests with OEMs at program launch. Procurement flexibility is expanding most quickly among airlines seeking direct supplier relationships for retrofit fleet standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation OEM final assembly concentration dictates insulation procurement geography, with Boeing's Washington and South Carolina facilities anchoring North American demand and Airbus's European lines shaping material specifications across the Atlantic.
United States
Boeing's Renton and Everett facilities in Washington state, plus its North Charleston complex, drive specification authority for next-generation narrow-body programs. FAA Part 25.856 fire-blocking standards mandate 12-second vertical burn resistance, forcing procurement toward certified aerogel and ceramic fiber stacks. Wichita, Kansas hosts FAA-approved fire-test laboratories where qualification bottlenecks compress supplier certification timelines.
Germany
Airbus's Hamburg final assembly line anchors European insulation consumption for A320neo family production. EASA CS-25 Appendix F smoke-density standards through 2025 implementation timelines force phenolic resin binder reformulation for cores produced in the Hamburg-Toulouse supply corridor. BASF SE's Ludwigshafen headquarters anchors engineered foam formulations certified to multiple aviation fire standards.
France
Airbus's Toulouse facility drives thermal protection system specifications for wide-body platforms including A350 and A330 programs. EASA's tightening smoke-density limits impose optical density readings below 200 in four-minute tests, burdening acoustic foam segment compliance. Safran Group's Paris-region operations influence engine nacelle insulation requirements for LEAP and Pearl powerplants.
China
COMAC's Shanghai final assembly lines for C919 narrow-body programs are scaling domestic insulation procurement as production rates climb. The country's national aviation regulator aligns fire-blocking certification with FAA and EASA protocols, creating parallel qualification pathways for foreign suppliers. Guangzhou maintenance facilities specialize in wide-body thermal protection system replacement during heavy check intervals.
Singapore
Seletar Aerospace Park and Changi-based MRO facilities retrofit wide-body fleets with lightweight insulation during C-check cycles. The city-state's maintenance hubs consolidate specifications across mixed Boeing and Airbus fleets to reduce inventory complexity. Direct airline procurement agreements are displacing tier-one aerostructures integrator markups for thermal-acoustic-fire material stacks.
Aircraft Insulation Market Vendor Landscape
Portfolio diversification dominates the current landscape as compounders expand from core chemistries into full-stack insulation systems. The vendor base organizes around three strategic archetypes: specialty chemical compounders with sol-gel processing expertise, tier-one aerostructures integrators with in-house installation capabilities, and engineered materials suppliers with polymer science heritage. M&A activity and qualification-driven partnerships represent the dominant competitive moves, as OEMs consolidate supplier relationships to reduce program risk.
Among chemical compounders with aviation certification depth, DuPont and BASF SE exemplify the polymer-science-to-insulation-stack expansion pattern, while Triumph Group anchors the aerostructures-integrator archetype with installation capabilities at Texas and Connecticut facilities. These three occupy positions across the value chain from raw formulation through final assembly integration.
| Leading Market Players |
|---|
| DuPont |
| BASF SE |
| Triumph Group |
| Rogers Corporation |
| Safran Group |
| Transdigm Group |
| Zotefoams |
| Duracote Corporation |
| Morgan Advanced Materials |
| Others |
Supply Flow & Price Mechanics
FAA Part 25.856 fire-blocking mandates are compressing supplier qualification timelines while simultaneously concentrating procurement toward certified aerogel and ceramic fiber formulations, forcing supply chains to absorb extended certification costs and pass through premium pricing for compliant material stacks.
Pricing Analysis
Volume shipments of fiberglass blankets for retrofit narrow-body programs trade at compressed margins, while certified aerogel stacks for engine nacelle applications command substantial premiums due to sol-gel processing complexity and fire-test laboratory bottlenecks. Pricing stratifies across certified premium tiers for OEM new-build programs, qualified standard tiers for airline retrofit consolidation, and economy tiers for cost-sensitive MRO procurement. Price differentiation hinges on FAA certification status and volume scale commitments, with airline direct procurement agreements displacing tier-one integrator markups and intensifying cost transparency. Cost compression in acoustic foam formulations is accelerating because EASA smoke-density compliance burdens force halogen-free flame retardant redesign.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Boeing's Renton and Airbus's Hamburg final assembly lines, while tier-one aerostructures integrators manage installation logistics at Texas and Connecticut facilities. Raw material supply draws from silica precursor production in the United States, engineered foam formulations from Germany, and ceramic fiber processing from Japan. Distribution runs through FAA-approved fire-test laboratories in Wichita, Seattle, and Montreal, creating qualification chokepoints that tether supply responsiveness to certification capacity. Single-source vulnerability concentrates in sol-gel processing expertise for ambient-dried aerogel, where limited compounder bases control critical thermal protection system inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA-approved fire-test laboratory capacity constraints are propping pricing power for qualified material suppliers, as 18-24 month certification timelines create structural bottlenecks that limit rapid supply expansion.
For Market Incumbents: Acquire sol-gel processing expertise and fire-test laboratory relationships to lock in certification capacity before ISO 2685 protocol updates demand requalification investments. Threat from emerging chemical compounders with halogen-free flame retardant formulations demands backward integration into phenolic resin binder production to preserve margin position in European Airbus supply corridors. For New Entrants and Emerging Players: Tier-two MRO facilities in Guangzhou and Singapore represent the most penetrable channel partner type for lightweight insulation retrofit packages, as these hubs consolidate specifications across mixed Boeing and Airbus fleets during C-check intervals. White-space opportunity sits with urban air mobility thermal runaway containment systems, where electric vertical takeoff aircraft battery pack adjacencies require compact, conformable insulation absent established supplier relationships. For Investors and Strategic Acquirers: The window for entry favors specialty chemical compounders with aviation fire certification depth and sol-gel processing capabilities. Long-term viability over a 5-10 year horizon rests on qualification moats widening as regulatory test protocols tighten post-certification compliance burdens. Signal to monitor: EASA implementation timelines for revised smoke-density limits forcing incumbent formulation failures and supplier base consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Test Laboratory Capacity Expansion | FAA-approved facilities in Wichita and Seattle reduce certification bottlenecks for aerogel qualification timelines. |
| Halogen-Free Flame Retardant Reformulation | REACH-compliant chemistry qualifies for accelerated OEM pathways under EU Green Deal incentives. |
| Direct Airline Procurement Agreements | Singapore and Dallas-Fort Worth hubs bypass tier-one integrator markups for thermal-acoustic-fire stacks. |
| Ambient-Pressure Dried Aerogel Scale-Up | Manufacturing maturation reduces unit costs for Boeing 737 MAX auxiliary power unit compartments. |
| Urban Air Mobility Thermal Containment Development | Battery pack adjacency specifications for electric vertical takeoff aircraft create new application demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with FAA Part 25.856 certification databases and EASA CS-25 Appendix F test result repositories providing material qualification benchmarks. Primary interviews with thermal protection system engineers, airline procurement directors, MRO facility managers, and fire-test laboratory technical leads combined with bottom-up and top-down triangulation across production volume disclosures from Boeing and Airbus final assembly lines.
Data-stream reconciliation across shipment volumes, certification timelines, and procurement contract values informed analytical framework development over the projection horizon. Segmentation dimensions modeled include material type, application function, aircraft platform, and end-user supply chain position, with CAGRs derived from production rate trajectories at Renton, Hamburg, and Toulouse facilities coupled with regulatory implementation schedules for smoke-density and fire-blocking standards.
Caveats apply where petrochemical feedstock volatility, qualification laboratory capacity constraints, or ISO 2685 protocol revision timing could materially shift the outlook. Forecasts reflect assumptions regarding Boeing and Airbus production rate sustainability, EASA enforcement intensity for phenolic resin binder reformulation, and aerogel manufacturing scale-up economics. Periodic stress-testing of base assumptions against actual certification timeline experiences and airline procurement consolidation patterns is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
South America Rotor Blade Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Solenoid Valves in Aerospace Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market