

Aircraft Structural Health Monitoring Access Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Structural Health Monitoring Access Panels Market Insights
The EU Green Deal's aviation decarbonization targets are expanding the addressable market for lightweight, sensor-embedded access panels across European and export-bound fleets. GKN Aerospace leverages its composite manufacturing scale to supply integrated panel-sensor assemblies for next-generation narrowbody programs. Spirit AeroSystems anchors North American production through its Wichita fabrication complex, sustaining long-term contracts with Boeing. Collins Aerospace differentiates through avionics-to-structure integration, positioning its smart panel architectures as retrofit solutions for existing aircraft.
Aircraft structural health monitoring access panels are removable fuselage and wing surface elements engineered to house or protect embedded sensor arrays, typically manufactured from carbon fiber-reinforced polymer laminates or titanium sheet with EMI-shielding coatings and quick-release fastening systems, enabling non-destructive evaluation of airframe fatigue, corrosion, and impact damage without structural disassembly. Composite access panels dominate commercial programs due to weight savings and radio-frequency transparency for wireless sensor telemetry, while titanium variants retain preference in military applications where ballistic tolerance and thermal cycling resistance command premium positioning. Fiber optic sensor technology leads the instrumentation segment for immunity to electromagnetic interference in composite-intensive airframes, whereas wireless sensor networks represent the fastest-growing category as airlines pursue reduced wiring harness complexity during retrofit campaigns.
FAA airworthiness directives and EASA CS-25 certification standards mandate continuous structural integrity verification for transport-category aircraft, compelling operators to specify SHM-capable panels during heavy maintenance checks. The EPA's emerging aircraft lifecycle emissions tracking requirements intersect with these airworthiness frameworks, creating dual compliance pressure on panel material selection and sensor longevity. Stakeholders must monitor the convergence of airworthiness mandates with sustainability disclosure rules to anticipate procurement specification changes before next-generation fleet commitments lock in design standards.
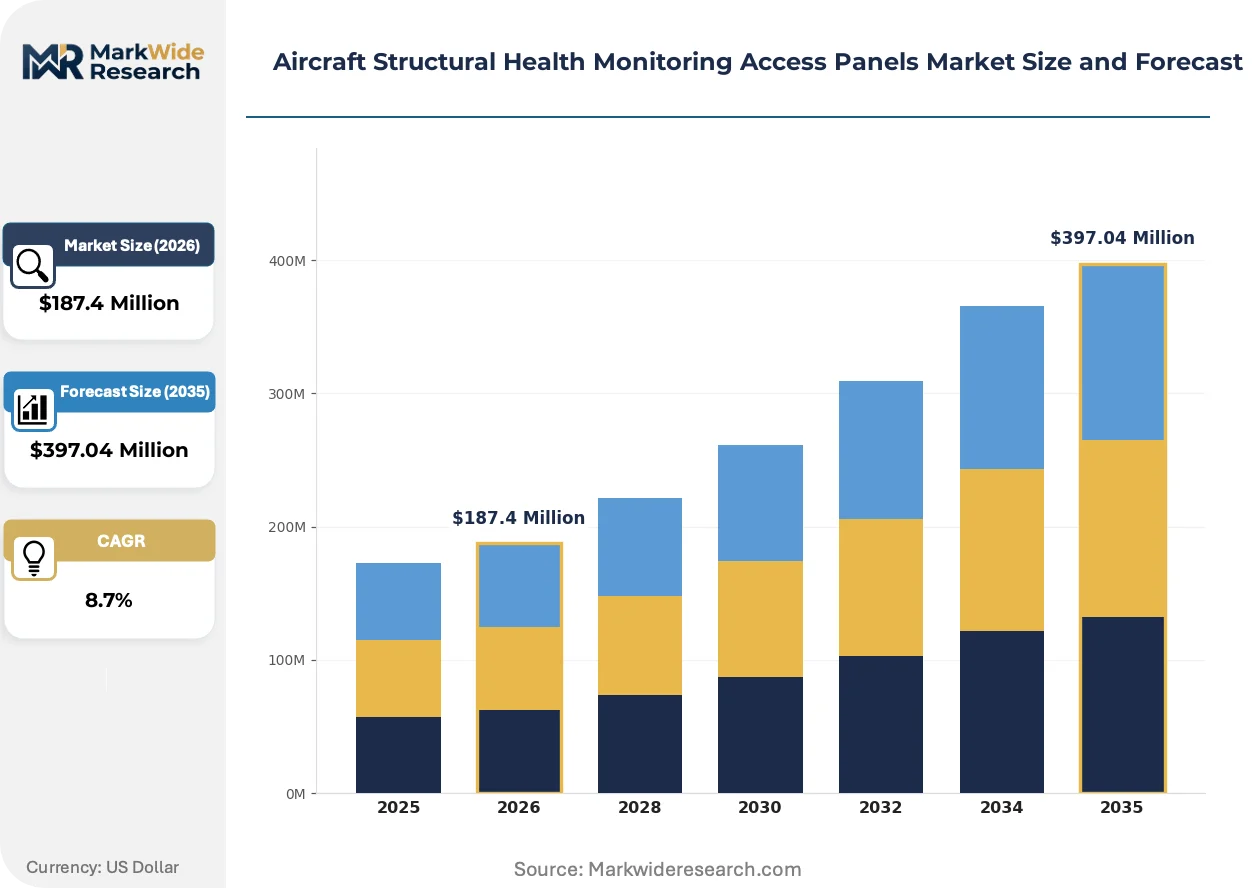
Market Dynamics
Retrofit cycles for aging commercial fleets are compressing as FAA airworthiness directives mandate continuous structural integrity verification, forcing airlines to accelerate panel replacement timelines and integrate embedded sensor networks during heavy maintenance checks.
Growth Catalysts
- FAA-EASA Regulatory Convergence:Harmonized airworthiness standards for transport-category aircraft compel operators to specify SHM-capable panels, eliminating grandfathered exemptions for legacy fleets.
- Carbon Fiber Composite Maturation:Radio-frequency transparent laminates enable wireless sensor telemetry without signal degradation, reducing wiring harness weight and installation complexity.
- MRO Provider Consolidation:Specialized maintenance networks in Wichita and Toulouse are standardizing panel-sensor integration protocols, accelerating retrofit throughput.
Market Restraints
- Titanium Input Volatility:Aerospace-grade titanium sheet pricing fluctuates with sponge supply from Russian and Ukrainian feedstock sources, compressing margins on military-specification panels.
- EMI Shielding Technical Ceiling:Current conductive coating formulations degrade under repeated thermal cycling above 150°C, limiting sensor longevity in engine-adjacent installations.
- Substitution by Bonded Access Doors:Permanent structural health monitoring arrays with non-removable sensor embedding threaten demand for traditional quick-release panel architectures.
Strategic Opportunities
- India Fleet Expansion:IndiGo and Air India's narrowbody order commitments create first-fit specification windows for integrated panel-sensor assemblies on domestic assembly lines.
- Fiber Optic-Wireless Convergence:Hybrid instrumentation combining fiber Bragg grating immunity with Bluetooth Low Energy transmission addresses composite airframe electromagnetic interference without full rewiring.
- EU Green Deal Aviation Decarbonization:Lifecycle emissions tracking mandates incentivize lightweight panel selection, creating procurement preference for sensor-embedded carbon fiber over metallic alternatives.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Coupled thermal-structural-electromagnetic modeling for panel-sensor interaction requires specialized aerospace engineering expertise concentrated at Wichita State and TU Delft programs.
- CS-25 Certification Timeline Compression:EASA's revised means of compliance for structural monitoring systems extends validation periods, delaying revenue recognition on new panel designs.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Structural Health Monitoring Access Panels Market Trends and Innovations
Sensor fusion architectures are displacing single-modality instrumentation as airlines demand consolidated damage detection covering fatigue, corrosion, and impact events through unified data streams.
Wireless sensor networks are consolidating discrete wiring harnesses into mesh telemetry systems that self-organize across fuselage sections. Regional carriers operating Bombardier and Embraer fleets are adopting these architectures fastest to minimize A-check downtime. The technology is consolidating aftermarket panel suppliers into systems integrators capable of avionics-to-structure certification.
EPA aircraft lifecycle emissions tracking requirements are intersecting with FAA airworthiness frameworks, creating dual compliance pressure on material selection and sensor longevity specifications. Panel manufacturers must now document carbon footprint per unit alongside fatigue test data. Commercial operators in California and Washington state face the earliest enforcement timelines as state environmental regulators align with federal disclosure rules.
Airline procurement departments are unbundling sensor hardware from installation services, issuing separate RFPs for panel supply and MRO integration. This bifurcation disrupts traditional turnkey contracts held by tier-one aerostructures suppliers. Low-cost carriers in Southeast Asia are driving this pattern fastest, leveraging competitive tension between Korean sensor manufacturers and Singaporean maintenance providers.
Aircraft Structural Health Monitoring Access Panels Market Segmentation
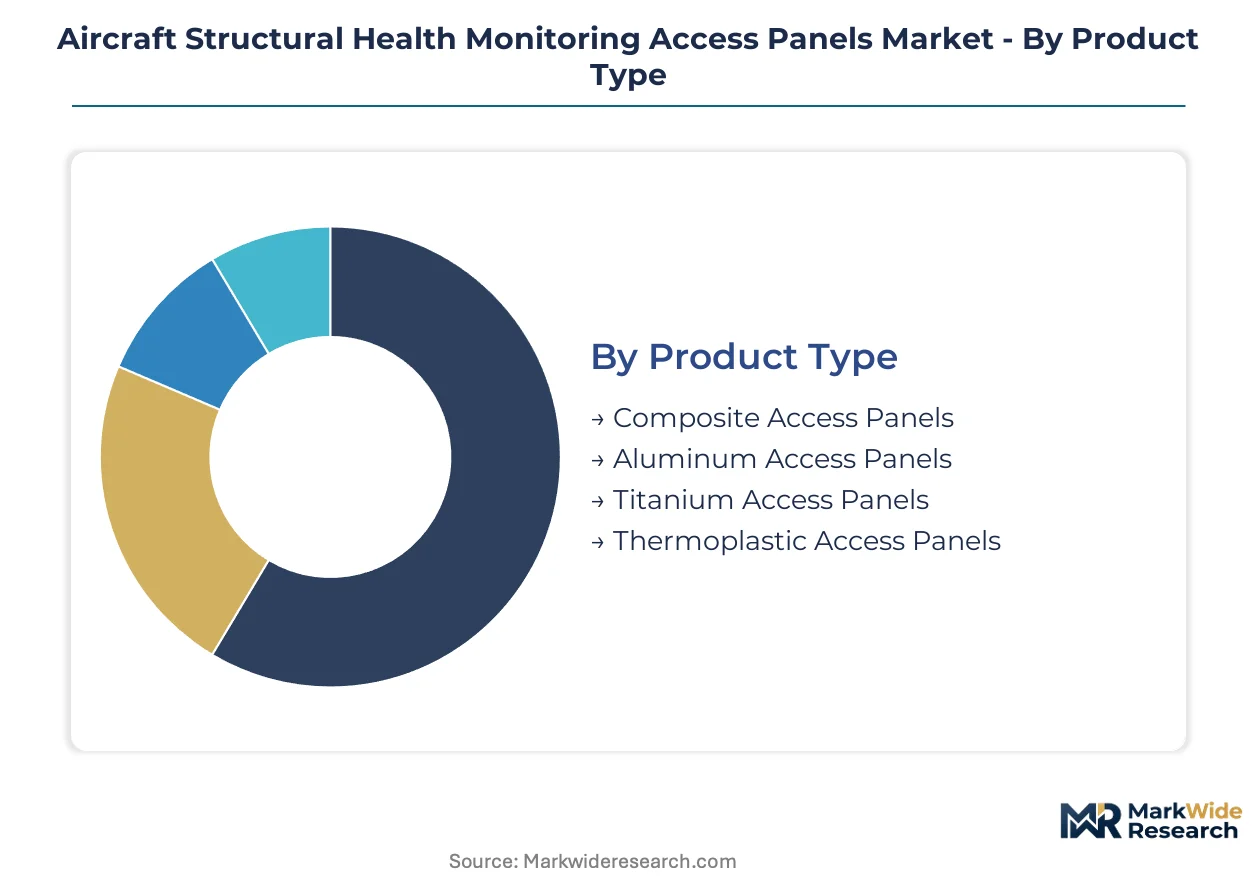
Segmentation in aircraft structural health monitoring access panels reveals how procurement specifications diverge across airframe programs and regulatory jurisdictions. Material selection, sensor instrumentation, and end-user maintenance capabilities each create distinct commercial pockets with specialized certification requirements and supply chain configurations.
Product Type:
Buyers differentiate primarily by weight targets and electromagnetic transparency needs across fleet categories.
- Composite Access Panels:Carbon fiber-reinforced polymer laminates with radio-frequency transparency enable wireless sensor telemetry without signal degradation. Commercial narrowbody operators in the United States specify these panels most heavily during retrofit campaigns to reduce wiring harness complexity.
- Titanium Access Panels:Aerospace-grade titanium sheet construction delivers ballistic tolerance and thermal cycling resistance above 150°C. Military platforms operating in high-threat environments anchor demand, though Russian and Ukrainian sponge supply volatility compresses margins.
- Aluminum Access Panels:Legacy alloy construction persists on aging regional jet fleets where grandfathered airworthiness certificates permit continued metallic specification without SHM retrofit mandates.
- Thermoplastic Access Panels:Emerging recyclable thermoplastic composites align with EU Green Deal lifecycle emissions tracking requirements, creating procurement preference among European flag carriers.
Volume sits with composite variants; growth tilts toward thermoplastic alternatives.
Application:
Operational intensity and inspection interval frequency determine panel replacement velocity across aircraft categories.
- Commercial Airliners:High-cycle narrowbody and widebody fleets generate the largest installed base, with FAA airworthiness directives mandating continuous structural monitoring during heavy maintenance checks. Panel replacement timelines compress as carriers retrofit aging Boeing and Airbus platforms.
- Military Aircraft:Fighter and transport programs require ballistic-rated titanium panels with embedded fiber optic arrays immune to electromagnetic pulse environments. Defense procurement cycles extend validation periods but lock in long-term supply agreements.
- Business Jets:Low-volume bespoke manufacturing favors quick-release panel architectures that MRO providers can service without OEM dependency.
- Unmanned Aerial Vehicles:Swappable sensor-embedded panels enable rapid airframe reconfiguration between surveillance and cargo missions.
- Helicopters:Rotorcraft vibration environments demand specialized strain gauge integration with fatigue-resistant fastening systems.
Revenue concentrates in commercial airliners; unmanned aerial vehicles are expanding most quickly.
End User:
Technical integration capabilities and regulatory liability exposure separate procurement behaviors across the value chain.
- Airframe Manufacturers:First-fit specification on new production lines locks in panel-sensor architectures for program lifespans exceeding two decades. Wichita and Toulouse assembly complexes standardize supplier qualification protocols.
- Maintenance Repair Operators:Specialized MRO networks perform retrofit integration during C-check and D-check intervals, unbundling sensor hardware from panel supply in competitive tender processes.
- Airlines:Low-cost carriers in Southeast Asia drive fastest adoption of wireless sensor networks to minimize A-check downtime and crew training requirements.
- Defense Contractors:Classified program security requirements mandate domestic panel fabrication with cleared personnel and ITAR-compliant sensor supply chains.
Procurement volume rests with airframe manufacturers; retrofit activity is climbing fastest among MRO providers.
Technology:
Signal fidelity requirements and installation labor intensity determine instrumentation selection for composite versus metallic airframes.
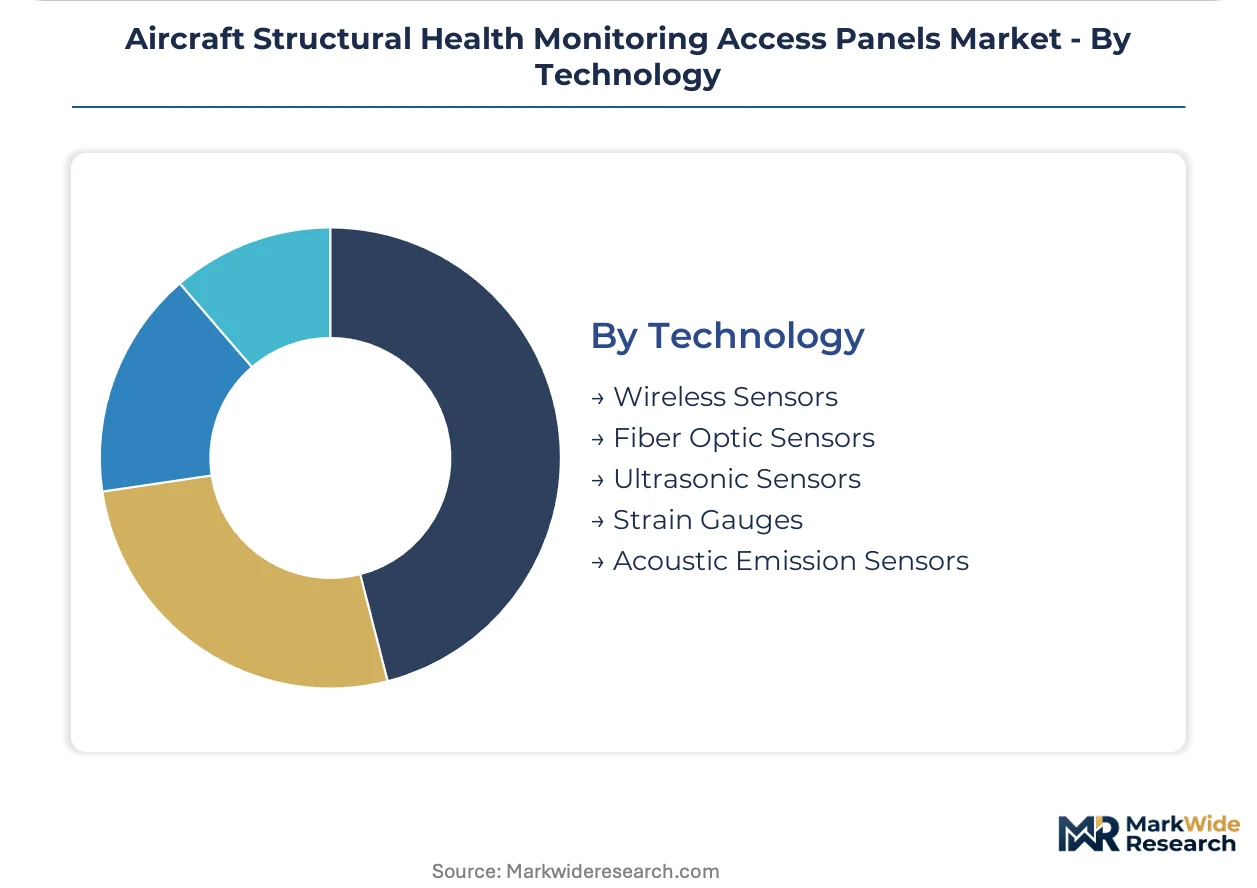
- Wireless Sensors:Mesh telemetry networks self-organize across fuselage sections, eliminating discrete wiring harnesses. Regional carriers operating Bombardier and Embraer fleets specify these architectures to compress maintenance turnaround times.
- Fiber Optic Sensors:Fiber Bragg grating technology delivers immunity to electromagnetic interference in carbon fiber-intensive airframes. EASA CS-25 certification standards favor this instrumentation for transport-category aircraft.
- Ultrasonic Sensors:Piezoelectric arrays detect subsurface delamination and corrosion without structural disassembly, preferred for metallic panel inspection protocols.
- Strain Gauges:Conventional electrical resistance sensors persist on legacy platforms with existing wiring infrastructure and grandfathered certification baselines.
- Acoustic Emission Sensors:Passive crack detection arrays capture stress wave propagation from fatigue initiation, deployed primarily on military platforms with continuous mission-critical monitoring requirements.
Deployment volume favors fiber optic instrumentation; wireless networks are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita anchors global fabrication capacity for integrated panel-sensor assemblies, with Spirit AeroSystems' complex supplying Boeing production lines and retrofit programs. FAA airworthiness directives compress replacement timelines across North American fleets, while EASA certification standards reshape procurement specifications in Europe.
United States
Boeing's 737 and 787 production rates drive first-fit demand for composite access panels with embedded wireless telemetry. FAA mandates for continuous structural integrity verification eliminate grandfathered exemptions for aging narrowbody fleets. Wichita's aerostructures corridor concentrates MRO integration capacity, with specialized providers standardizing panel-sensor protocols during C-check intervals.
France
Airbus A320 and A350 assembly lines in Toulouse generate specification pull for lightweight thermoplastic panel alternatives. EASA CS-25 revised means of compliance extend validation timelines but lock in long-term sensor integration standards. The EU Green Deal's aviation decarbonization targets create procurement preference for recyclable composite architectures over metallic alternatives.
Germany
Premium widebody operators Lufthansa and cargo carriers drive retrofit demand for fiber optic sensor arrays immune to electromagnetic interference. REACH regulations and emerging lifecycle emissions tracking rules intersect with airworthiness frameworks, pressuring material selection documentation. Hamburg's MRO cluster specializes in heavy maintenance integration for aging A330 and 777 fleets.
United Kingdom
GKN Aerospace's composite manufacturing scale supplies integrated panel assemblies for next-generation narrowbody programs and export-bound fleets. The UK's post-Brexit regulatory alignment negotiations with EASA create certification uncertainty for dual-registered aircraft. Bristol's aerospace engineering base concentrates multiphysics simulation talent for coupled thermal-structural-electromagnetic modeling.
India
IndiGo and Air India's narrowbody order commitments create first-fit specification windows for domestic assembly line integration. The country's national aviation regulator mandates structural monitoring compliance for imported transport-category aircraft. Bangalore's defense-aerospace corridor develops indigenous panel fabrication capacity for military UAV and helicopter programs.
Aircraft Structural Health Monitoring Access Panels Market Competitive Landscape
The competitive structure tilts toward integrated aerostructures suppliers with captive composite manufacturing and established OEM certification pathways. Tier-one suppliers with Wichita and Toulouse fabrication assets dominate first-fit production, while specialized sensor-technology firms capture retrofit instrumentation margins. Two archetypes prevail: composite panel fabricators with in-house sensor integration capabilities, and avionics-to-structure integrators positioning smart architectures as aftermarket solutions. Consolidation pressure intensifies through MRO provider vertical integration and technology licensing agreements for wireless telemetry protocols.
Among UK-based aerostructures specialists, GKN Aerospace exemplifies the composite manufacturing archetype with scale advantages in integrated panel-sensor supply. Spirit AeroSystems anchors the North American fabrication tier through its Wichita complex and long-term Boeing relationships. Collins Aerospace occupies the avionics-to-structure integration position, differentiating through retrofit-focused smart panel architectures for existing fleet upgrades.
| Leading Market Players |
|---|
| GKN Aerospace |
| Spirit AeroSystems |
| Hutchinson |
| Daher |
| Collins Aerospace |
| Luna Innovations |
| Acellent Technologies |
| Boeing |
| Airbus |
| Others |
Pricing and Supply Chain Analysis
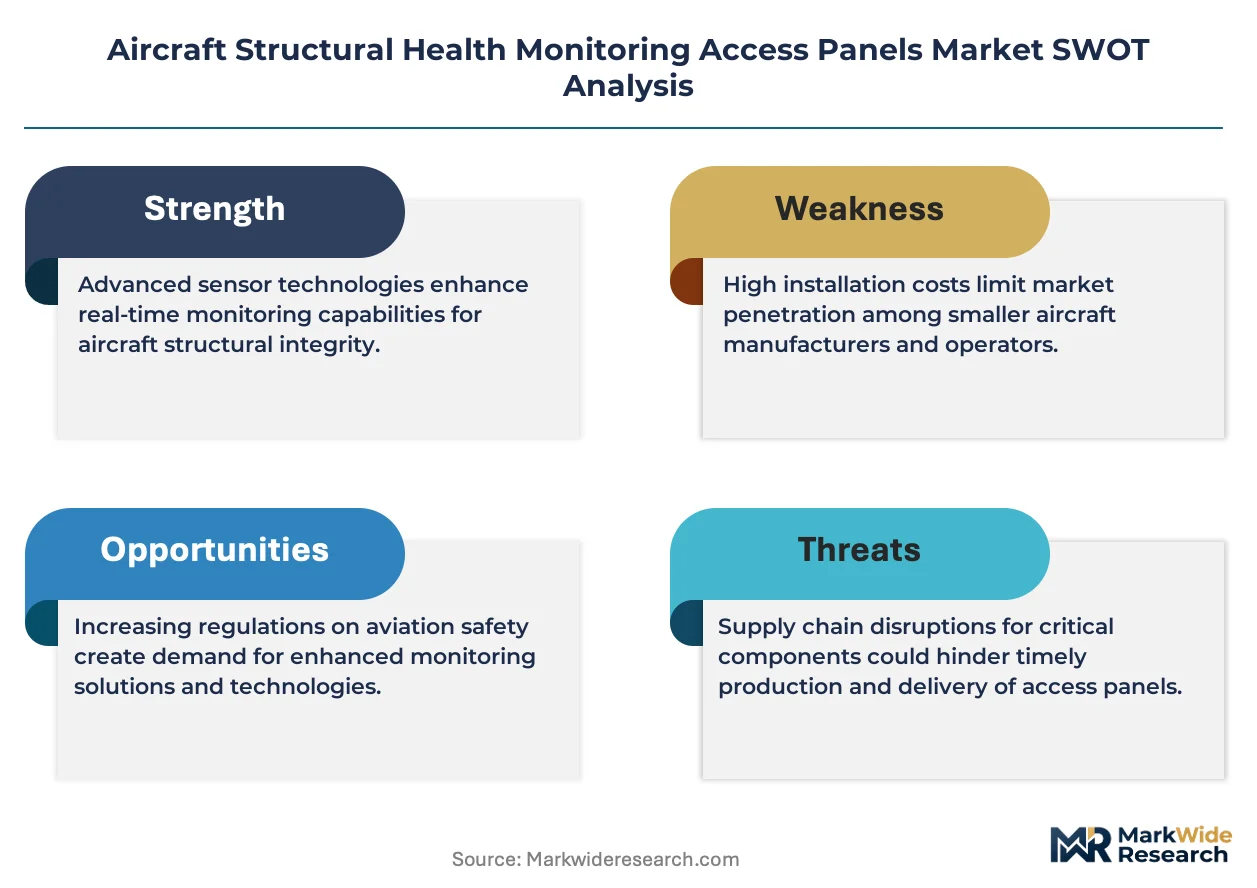
Wireless sensor network maturation is compressing installation labor costs while concentrating procurement leverage among MRO providers capable of avionics-to-structure certification. This technology shift simultaneously erodes turnkey panel premiums and rewards suppliers with captive composite fabrication and sensor integration capabilities.
Pricing Analysis
Certification-grade pricing anchors commercial transactions, with EASA CS-25 validation tiers commanding substantial premiums over grandfathered retrofit specifications. Price differentiation separates fiber optic-integrated composite panels from basic wireless-sensor variants, with titanium military-grade specifications least exposed to cost compression. Pricing pressure stems from airline procurement departments unbundling sensor hardware from installation services, though defense contractors exhibit minimal price sensitivity due to ITAR compliance requirements and classified program security protocols.
Supply Chain Analysis
Aerospace-grade titanium sponge supply rests on Russian and Ukrainian feedstock sources, creating margin volatility for military-specification panel fabricators. Carbon fiber prepreg draws from Japanese and US specialty chemical producers, while EMI-shielding conductive coatings hinge on South Korean and German electronics materials suppliers. Single-source vulnerability concentrates in titanium sheet rolling capacity, with distribution running through Wichita and Toulouse aerostructures corridors to Boeing and Airbus assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with panel fabricators pursuing backward control over fiber Bragg grating sensor production to capture retrofit instrumentation margins.
For Market Incumbents: Acquire fiber optic sensor manufacturing capabilities to defend against avionics-to-structure integrators unbundling hardware from panel supply. Consolidate Wichita and Toulouse MRO network relationships through long-term C-check and D-check service agreements, locking out emerging sensor-technology specialists before wireless telemetry protocols standardize. For New Entrants and Emerging Players: The premium-economy tier gap in regional carrier retrofit programs offers immediate white-space access, particularly for Bombardier and Embraer fleets seeking compressed A-check downtime. Target Southeast Asian low-cost carriers with Bluetooth Low Energy mesh architectures that minimize crew retraining requirements, positioning hybrid fiber-wireless convergence as the go-to-market differentiator against established fiber optic suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to tier-one aerostructures suppliers seeking avionics integration capabilities, with financial sponsor roll-ups of regional MRO providers as secondary liquidity routes. Across the five-to-ten year viability window, acquisition targets with EASA CS-25 validation assets and established Boeing or Airbus supplier codes offer defensive positioning. Watch FAA airworthiness directive expansion to non-transport categories as the inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures retrofit instrumentation margins previously lost to avionics specialists like Collins Aerospace. |
| EASA CS-25 Validation Investment | Locks in long-term specification standards for transport-category aircraft across European and export-bound fleets. |
| Wireless Telemetry Protocol Licensing | Creates recurring revenue streams as regional carriers standardize mesh network architectures. |
| Thermoplastic Composite Capacity Expansion | Aligns production with EU Green Deal lifecycle emissions tracking requirements for recyclable panel alternatives. |
| MRO Network Joint Venture | Secures C-check and D-check integration slots against unbundling trends in airline procurement departments. |
Research Methodology
Document review covered FAA airworthiness directives, EASA CS-25 certification standards, and EPA aircraft lifecycle emissions frameworks, complemented by interviews with aerostructures procurement managers, MRO integration specialists, fiber optic sensor R&D directors, and airline fleet engineering executives. Secondary validation drew from SEC filings of tier-one suppliers, Boeing and Airbus production rate disclosures, and customs data on aerospace-grade titanium and carbon fiber imports. Bottom-up panel shipment estimates triangulated against top-down fleet retrofit cycle projections.
Segment-level outputs across material type, sensor technology, aircraft application, and end-user category were generated through driver-based modeling. CAGRs were derived from fleet age demographics, regulatory mandate timelines, and technology substitution curves for wireless versus fiber optic instrumentation. Forecast inputs incorporated narrowbody and widebody production rates, heavy maintenance check intervals, and emerging thermoplastic composite qualification timelines.
Underlying measurement precision varies by segment; commercial airliner retrofit volumes carry tighter precision than military UAV and helicopter projections due to classified program opacity. Forecasts reflect assumptions on regulatory harmonization between FAA and EASA, titanium supply chain stabilization, and wireless sensor network adoption velocity. A small set of triggers warrants ongoing watch: FAA airworthiness directive scope expansion, EU Green Deal aviation decarbonization enforcement timelines, and fiber optic-wireless hybrid technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.