

eVTOL Rapid-Access Exterior Inspection Port Systems Market Size, Share, and Industry Trends Forecast 2026-2036
eVTOL Rapid-Access Exterior Inspection Port Systems Market Insights
Subscription-based predictive maintenance for inspection port wear and lifecycle tracking is rebalancing vendor revenue streams from pure hardware sales toward recurring service contracts. TransDigm Group leverages its aerospace fastening heritage to dominate quick-release mechanism supply for original equipment programs. Southco anchors aftermarket service networks with standardized port architectures that reduce fleet downtime for operators. Howmet Aerospace specializes in lightweight alloy formulations that meet eVTOL weight budgets without sacrificing structural integrity.
eVTOL rapid-access exterior inspection port systems are specialized apertures integrated into composite airframes, typically manufactured from carbon-fiber-reinforced polymers or aluminum-lithium alloys with quick-release latching mechanisms rated for thousands of duty cycles, designed to enable technician access to avionics bays, battery compartments, and flight control surfaces without structural disassembly. Hinged ports lead product type demand due to their proven sealing performance against electromagnetic interference and moisture ingress during flight operations. Quick-release mechanisms within the technology segment represent the fastest-growing category as operators prioritize turnaround speed over conventional threaded fastening approaches. Maintenance operations application generates the deepest margin pools because recurring inspection intervals create predictable replacement part demand across expanding eVTOL fleets.
FAA Part 27 and Part 29 airworthiness standards, alongside EASA SC-VTOL special condition frameworks, shape product certification pathways and testing burdens for port system suppliers seeking market access. ISO 2700-series quality management protocols and ASTM F3061 standards for electrical propulsion aircraft further constrain material selection and fatigue validation requirements. Stakeholders must monitor how emerging type certification reciprocity agreements between regulators affect qualification costs and geographic market entry sequencing.
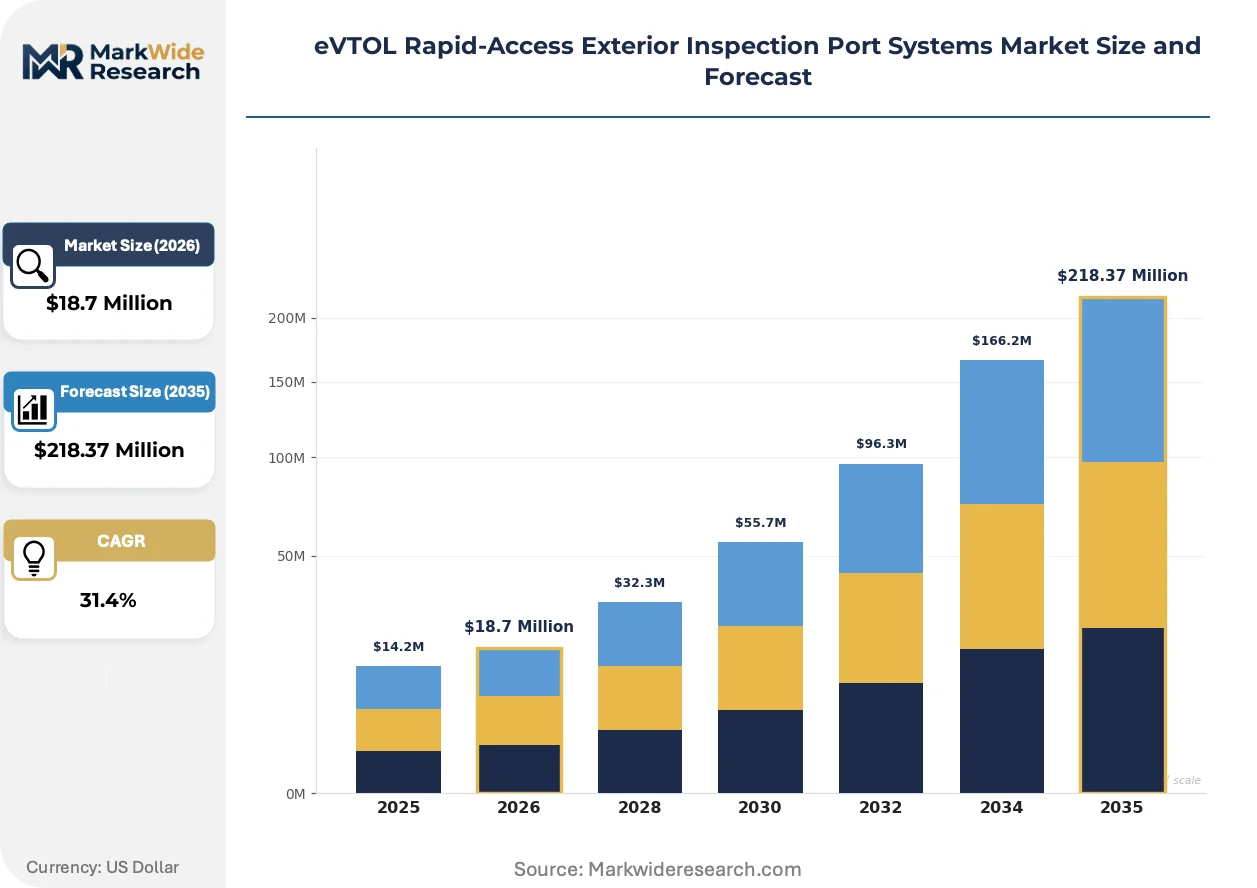
Market Dynamics
Fleet certification timelines and airframe production ramps are compressing supplier qualification windows, forcing inspection port vendors to pre-certify modular architectures that adapt across multiple eVTOL platforms without redesign.
Growth Catalysts
- FAA Part 27/29 Harmonization:Unified airworthiness standards between US and European regulators reduce duplicate testing burdens for port system manufacturers seeking dual-market entry.
- Carbon-Fiber-Reinforced Polymer Adoption:Composite airframe penetration in urban air mobility prototypes creates demand for inspection ports engineered to bond with thermoset substrates without galvanic corrosion.
- Urban Air Mobility Corridor Expansion:California's advanced air mobility network and Germany's manufacturing cluster generate concentrated procurement volumes from early fleet operators.
Market Restraints
- Aluminum-Lithium Alloy Price Volatility:Aerospace-grade lightweight alloy supply concentrates among specialty smelters, exposing port manufacturers to input cost swings that compress margin on fixed-price OEM contracts.
- Specialized Composite Bonding Labor Scarcity:Technician certification for thermoset adhesive application in cleanroom environments limits production scaling for integrated port-airframe assemblies.
- Quick-Release Mechanism Patent Thickets:Incumbent aerospace fastener holders control IP around duty-cycle-rated latching systems, forcing new entrants into costly licensing or design-around investments.
Strategic Opportunities
- Subscription Predictive Maintenance:Fleet operators in California's urban air mobility corridor seek lifecycle tracking contracts that convert hardware sales into recurring revenue streams.
- Emerging Middle East Certification:UAE and Saudi Arabia aviation authorities are establishing eVTOL regulatory frameworks ahead of commercial service launches, creating first-mover qualification advantages for port suppliers.
- Additive Manufacturing Convergence:Topology-optimized titanium port brackets produced via electron beam melting are converging with traditional CNC-machined quick-release housings to reduce part count and assembly labor.
Industry Challenges
- Electromagnetic Interference Shielding Validation:Port sealing systems must demonstrate consistent EMI attenuation across temperature cycles, requiring expensive anechoic chamber testing that extends certification timelines.
- Cross-Platform Standardization Resistance:OEMs specify proprietary port geometries to lock in aftermarket service revenue, fragmenting demand and preventing scale economies for component suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
eVTOL Rapid-Access Exterior Inspection Port Systems Market Trends and Innovations
Inspection port architectures are evolving from passive access panels to intelligent, sensor-integrated systems that communicate seal integrity and wear status to fleet maintenance software in real time.
Shape-memory alloy sealing gaskets are converging with conventional elastomer compression seals to enable automatic thermal compensation across the wide temperature swings experienced during eVTOL climb and descent profiles. Beta fleet operators in Germany are piloting these hybrid seals on battery compartment ports. This convergence is compressing maintenance intervals from calendar-based schedules toward condition-based replacement triggered by actual thermal cycling exposure.
EASA SC-VTOL special conditions now mandate traceable fatigue testing documentation for all flight-critical access hardware, extending validation timelines but creating competitive moats for suppliers with established aerospace testing infrastructure. Port manufacturers must submit full duty-cycle test data under combined vibration and pressure loading. European OEMs are responding by consolidating supplier lists to partners with pre-validated test matrices, accelerating procurement decisions for qualified vendors.
Fleet operators are unbundling after-sales service contracts from original equipment purchases, creating standalone procurement channels for inspection port replacement and upgrade programs. This disintermediation of OEM service networks is most visible among California-based urban air mobility startups operating mixed-vendor fleets. Third-party maintenance providers are capturing port replacement volumes by offering faster turnaround times than manufacturer-direct service channels.
eVTOL Rapid-Access Exterior Inspection Port Systems Market Segmentation
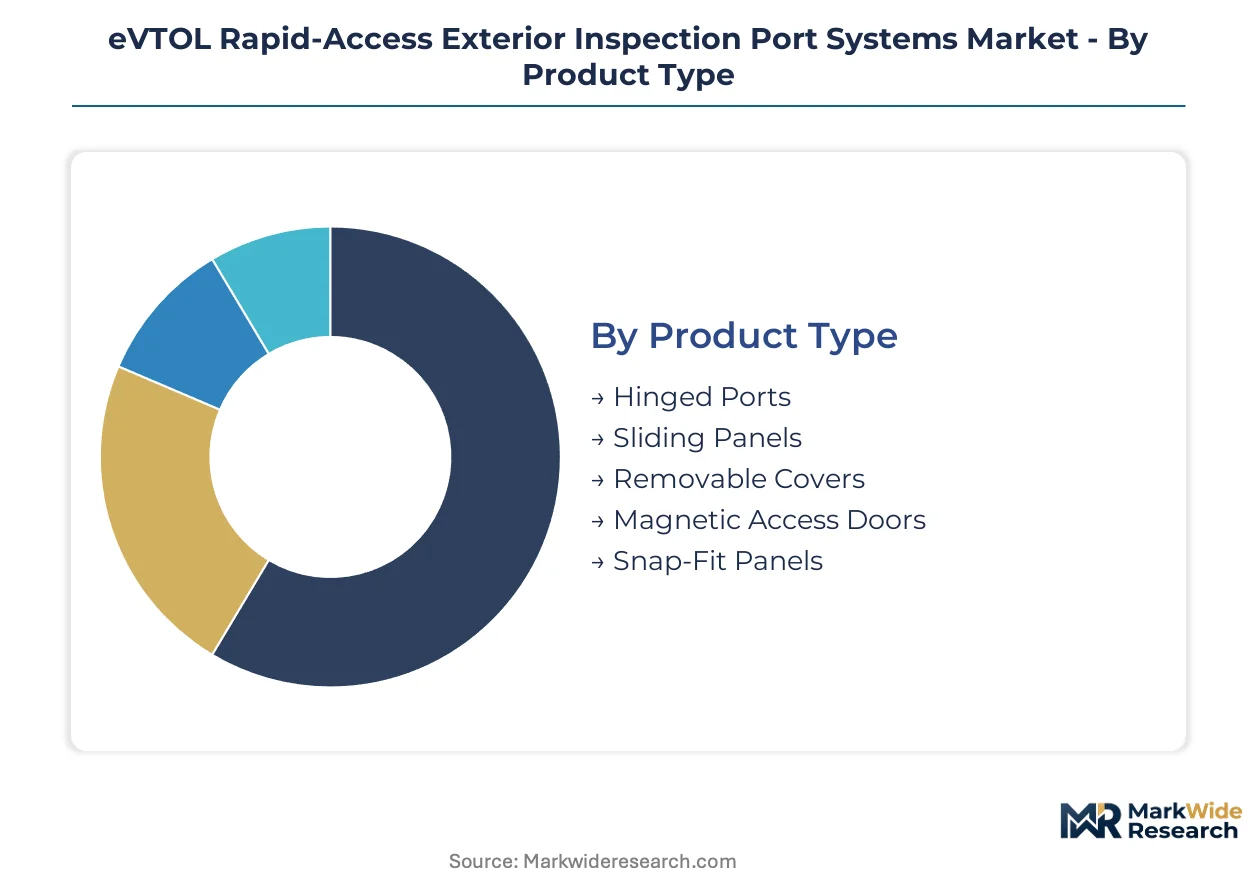
eVTOL inspection port demand fragments across five product architectures, five technology stacks, five operational applications, and five end-user constituencies. Each dimension carries distinct margin profiles, certification burdens, and supplier qualification requirements that reshape competitive positioning.
Product Type:
Volume deployment concentrates in proven architectures with established duty-cycle validation, while premium procurement targets emerging geometries that compress technician access time.
- Hinged Ports:These apertures integrate sealed pivot mechanisms rated for thousands of open-close cycles without EMI degradation or moisture ingress. Fleet operators in California's urban air mobility corridor specify hinged architectures for battery compartment access due to their proven sealing performance under thermal cycling stress.
- Sliding Panels:Linear translation mechanisms enable access in confined airframe zones where swing radius is constrained. German eVTOL manufacturing clusters favor sliding configurations for avionics bay integration where adjacent structural members limit hinged deployment arcs.
- Removable Covers:Fully detachable panels suit non-flight-critical inspection zones with relaxed access frequency requirements. These configurations reduce mechanism complexity but increase foreign object debris risk during ground operations.
- Magnetic Access Doors:Rare-earth latch systems enable tool-free technician entry for rapid turnaround scenarios. Magnetic architectures remain limited by temperature-induced flux degradation concerns in high-thermal-load compartments.
- Snap-Fit Panels:Elastic retention features suit lowest-cost, lowest-duty-cycle applications where speed outweighs longevity. These configurations dominate early prototype fleets with limited flight-hour accumulation.
Mature deployment sits with Hinged Ports. Newer deployment is concentrated in Magnetic Access Doors.
Technology:
Material selection directly determines airframe bonding compatibility, weight budget compliance, and corrosion resistance across operational environments.
- Composite Materials:Carbon-fiber-reinforced polymer substrates bond co-cured with thermoset port frames to eliminate galvanic coupling. California-based OEMs specify composite-integrated ports for next-generation airframes pursuing maximum weight reduction.
- Lightweight Alloys:Aluminum-lithium formulations deliver metallic fatigue resistance at 15-20% density reduction versus conventional aerospace aluminum. German manufacturers source alloy ports where electromagnetic shielding requirements exceed composite conductivity limits.
- Corrosion-Resistant Coatings:Anodized and conversion-coated surfaces protect metallic port hardware in coastal operating environments. Coating specifications vary by OEM based on projected route profiles and ground handling exposure.
- Quick-Release Mechanisms:Cam-over latching systems enable sub-30-second technician access without tooling. These mechanisms are climbing the fastest as fleet operators prioritize turnaround velocity over legacy threaded fastening approaches.
- Acoustic Insulation:Multi-layer dampening materials reduce cabin noise transmission through port perimeters. Insulation integration adds mass penalty that conflicts with eVTOL weight budgets, limiting adoption to passenger-carrying configurations.
Technology maturation centers on Composite Materials and Lightweight Alloys. Emerging differentiation is concentrated in Quick-Release Mechanisms.
Application:
Operational use case determines access frequency, environmental exposure, and regulatory documentation requirements.
- Pre-Flight Checks:Rapid visual and tactile verification protocols require ports positioned for technician ergonomics without work platforms. These applications demand highest sealing reliability due to minimal inspection depth.
- Maintenance Operations:Deep-access procedures for component replacement and system troubleshooting generate recurring parts demand. Fleet operators unbundle these service contracts from OEM agreements, creating third-party procurement channels.
- Damage Assessment:Post-incident inspection access following hard landings or foreign object strikes requires ports sized for borescope and manual probe entry. Damage assessment applications drive demand for oversized port geometries.
- Sensor Integration:Port-mounted external sensor pods for environmental monitoring and navigation augmentation require electromagnetic-transparent sealing. These configurations integrate antenna and LIDAR window functions.
- Cleaning Procedures:Wash rack compatibility and drainage features enable automated exterior cleaning without seal degradation. Cleaning-optimized ports incorporate self-draining channels and chemical-resistant gasket materials.
Application maturity sits with Pre-Flight Checks. Expanding deployment is concentrated in Maintenance Operations.
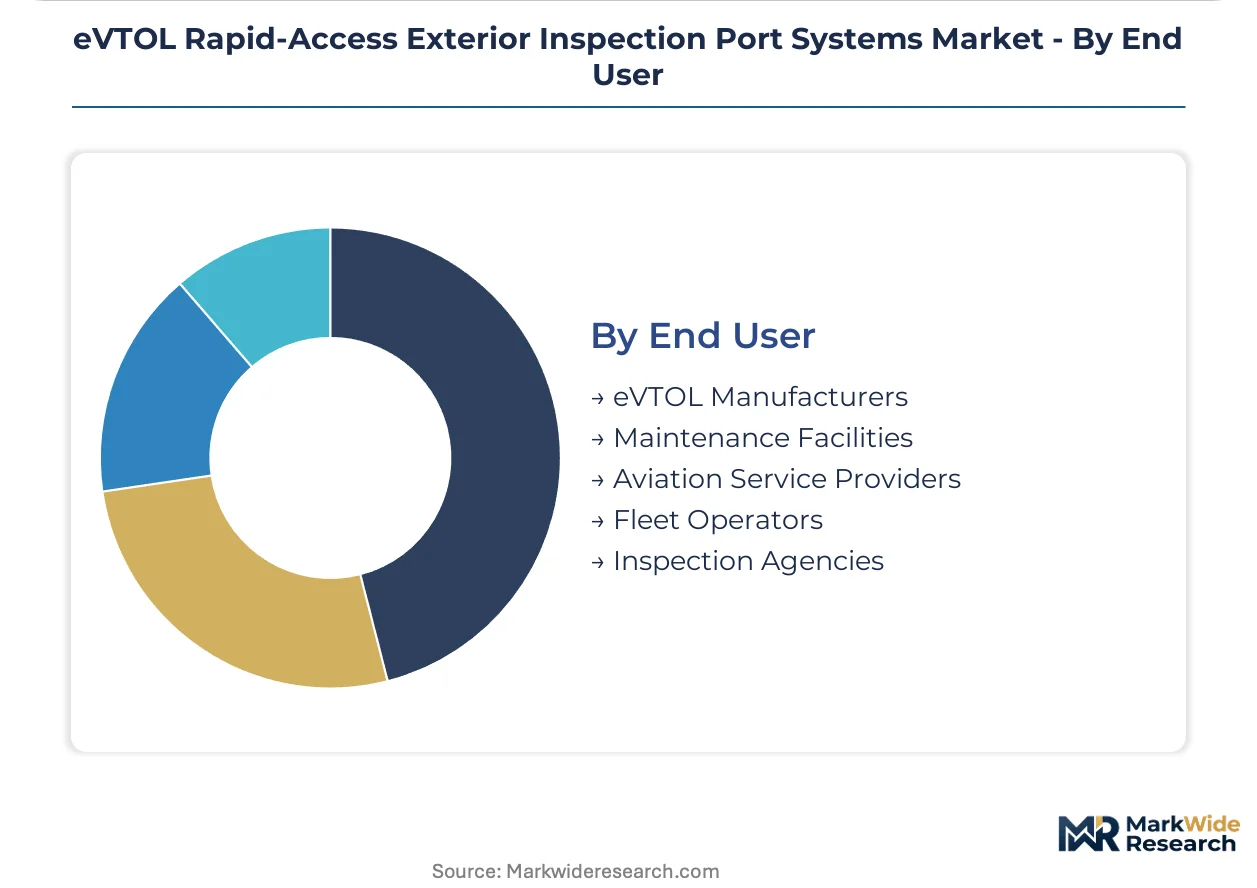
End User:
Procurement authority and specification control vary sharply across the value chain, fragmenting supplier engagement models.
- eVTOL Manufacturers:Airframe integrators specify port geometries during type design and control aftermarket service revenue through proprietary architectures. These stakeholders demand longest duty-cycle validation and full certification traceability.
- Maintenance Facilities:Third-party MRO providers procure replacement ports based on turnaround time and parts availability rather than OEM exclusivity. California-based urban air mobility startups increasingly source from independent maintenance networks.
- Aviation Service Providers:Ground handling and support contractors specify portable inspection equipment compatibility with fleet port geometries. These stakeholders drive standardization pressure across mixed-vendor operations.
- Fleet Operators:Asset owners with direct maintenance responsibility negotiate lifecycle service contracts converting hardware sales to recurring revenue. Subscription-based predictive maintenance models originate from operator procurement teams.
- Inspection Agencies:Regulatory and insurance surveyors mandate port accessibility for airworthiness verification without structural disassembly. Agency requirements influence minimum port sizing and labeling standards.
Procurement concentration sits with eVTOL Manufacturers. Disintermediation is accelerating through Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States, while fleet deployment concentrates in California's urban air mobility corridor and the UAE's emerging commercial routes. This production-consumption divide shapes supplier qualification sequencing and regional certification priorities.
United States
California's advanced air mobility corridor drives procurement volumes from early eVTOL fleet operators establishing commercial service. FAA Part 27 and Part 29 airworthiness standards govern port system certification pathways, with harmonization efforts reducing duplicate testing burdens. The Greater Los Angeles and San Francisco Bay Area clusters host beta testing programs for hinged port architectures on battery compartment access points.
Germany
The emerging eVTOL manufacturing cluster in Bavaria and Baden-Württemberg generates concentrated demand for lightweight alloy port formulations. EASA SC-VTOL special conditions mandate traceable fatigue testing documentation, extending validation timelines for suppliers. Munich-area OEMs are consolidating supplier lists to partners with pre-validated test matrices under combined vibration and pressure loading protocols.
United Arab Emirates
Dubai and Abu Dhabi aviation authorities are establishing eVTOL regulatory frameworks ahead of commercial service launches, creating first-mover qualification advantages for port suppliers. The country's General Civil Aviation Authority is developing certification reciprocity agreements with FAA and EASA. NEOM and Dubai South aerotropolis projects are specifying rapid-access port geometries for planned urban air mobility networks.
China
Yangtze River Delta and Pearl River Delta manufacturing bases are scaling composite airframe production, creating demand for inspection ports engineered to bond with thermoset substrates. MIIT and CAAC are developing domestic airworthiness standards for electrical propulsion aircraft that reference ASTM F3061 frameworks. Shenzhen and Shanghai clusters host prototype fleets testing quick-release mechanism duty cycles.
United Kingdom
The Southeast England aerospace corridor maintains specialized testing infrastructure for electromagnetic interference shielding validation. UK CAA participation in EASA rulemaking processes influences port sealing standards across European markets. Farnborough and Bristol clusters house anechoic chamber facilities that extend certification timelines but create competitive moats for qualified vendors.
eVTOL Rapid-Access Exterior Inspection Port Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the eVTOL inspection port supply base. The market structure concentrates around aerospace heritage suppliers with established airworthiness testing infrastructure and emerging specialists in quick-release mechanism design. Three archetypes dominate: legacy aerospace fastener conglomerates with duty-cycle validation libraries, composite bonding specialists with thermoset integration expertise, and subscription-service platform builders converting hardware sales to recurring revenue. Competitive moves center on pre-certification of modular architectures across multiple OEM platforms and vertical integration into predictive maintenance software stacks.
Within the legacy aerospace tier, TransDigm Group and Howmet Aerospace exemplify capital-intensive producers with deep aerospace fastening heritage and metallurgical capabilities. Southco occupies a position bridging hardware supply and aftermarket service network standardization. These three anchors demonstrate how incumbent suppliers leverage existing airworthiness relationships to compress qualification windows for emerging eVTOL platforms, while specialized composite integrators and additive manufacturing specialists challenge from the technology frontier.
| Leading Market Players |
|---|
| TransDigm Group |
| Howmet Aerospace |
| Southco |
| TriMas Aerospace |
| Collins Aerospace |
| LISI Aerospace |
| Camloc Motion Control |
| Hartwell Corporation |
| Piasecki Aircraft Corporation |
| Others |
Pricing and Supply Chain Analysis
Aluminum-lithium alloy ingot pricing volatility cascades through three-tier pricing structures across premium, standard, and economy levels, compressing margin on fixed-price OEM contracts while freight premiums from German specialty smelters to California assembly plants amplify landed cost differentials between qualified suppliers.
Pricing Analysis
Margin tightening in standard-tier quick-release mechanisms reflects aluminum-lithium alloy price swings and specialized composite bonding labor scarcity. Three-tier pricing structure across premium, standard, and economy levels segments by duty-cycle validation depth and FAA/EASA certification traceability. California fleet operators exhibit highest price sensitivity due to unbundled after-sales procurement, while German OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Freight premiums on aerospace-grade lightweight alloys from German smelters concentrate upstream supply in Germany, the United States, and China. Raw material dependencies rest on aluminum-lithium formulations, carbon-fiber-reinforced polymers, and rare-earth magnetic latch components. Single-source vulnerability around duty-cycle-rated quick-release mechanism IP creates chokepoint risk. Distribution runs through OEM-direct channels and third-party MRO networks fragmenting procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
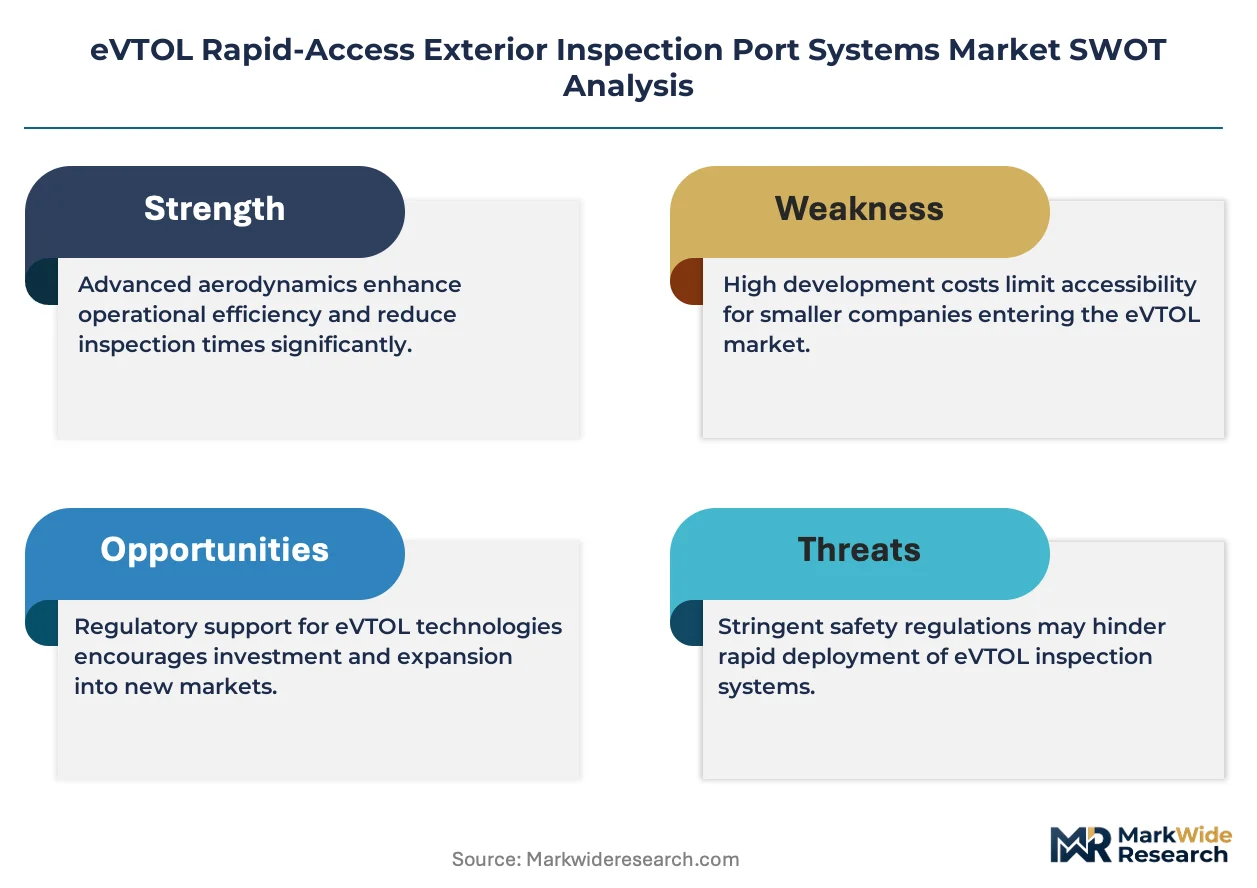
This market consolidates around pre-certified modular architectures as EASA SC-VTOL fatigue documentation requirements and quick-release mechanism patent thickets force subscale vendors into licensing arrangements or exit.
For Market Incumbents: Hedge against emerging additive manufacturing specialists by securing captive supply of topology-optimized titanium brackets through electron beam melting partnerships in Germany. Reinforce qualification moats through expanded anechoic chamber testing infrastructure for EMI shielding validation. Prioritize backward integration into predictive maintenance software stacks to capture subscription revenue from California fleet operators unbundling service contracts. For New Entrants and Emerging Players: Direct-to-fleet-operator digital channels bypass OEM service network lock-in and capture replacement port volumes from California urban air mobility startups operating mixed-vendor fleets. Target maintenance operations applications with sub-30-second quick-release mechanisms where turnaround velocity commands premium positioning. Pursue UAE General Civil Aviation Authority first-mover qualification ahead of Dubai South aerotropolis deployment timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor composite bonding specialists with thermoset integration expertise in China's Yangtze River Delta manufacturing cluster. Long-term viability hinges on subscription-platform conversion capability and pre-validated test matrix libraries. Watch for FAA-EASA type certification reciprocity agreements as inflection signal accelerating dual-market entry economics.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Pre-Certification | Compresses qualification windows across multiple eVTOL platforms without redesign cycles. |
| Subscription Predictive Maintenance Platform | Converts hardware sales into recurring revenue from California fleet operator contracts. |
| Electron Beam Melting Integration | Reduces titanium bracket part count and assembly labor via topology-optimized additive production. |
| UAE Regulatory First-Mover Qualification | Captures procurement preference ahead of NEOM and Dubai South commercial service launches. |
| Anechoic Chamber Testing Infrastructure | Creates competitive moat for EMI shielding validation under EASA SC-VTOL special conditions. |
Research Methodology
Multi-period observation of fleet certification timelines and airframe production ramps anchored the trend analysis, supplemented by interviews with eVTOL platform engineers, FAA certification leads, MRO procurement managers, and composite bonding technicians. Secondary validation drew from FAA Part 27/29 airworthiness filings, EASA SC-VTOL special condition documentation, ASTM F3061 standards, and OEM supplier qualification disclosures. Bottom-up segment sizing triangulated against top-down fleet deployment projections across the analysis window.
Segment-weighting across product architecture, technology stack, operational application, and end-user constituency informed volume and value outputs throughout the forecast period. CAGRs derived from regression analysis against fleet operator procurement patterns and OEM production ramp schedules. Industry-specific inputs included duty-cycle testing documentation requirements and thermoset adhesive application labor availability curves.
The model holds under stable regulatory harmonization between FAA and EASA; deviation in certification reciprocity timelines or aluminum-lithium alloy supply disruptions would shift supplier qualification sequencing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.