
 Light and Very Light Jets Market | 2026-2036
Light and Very Light Jets Market Size, Share, and Industry Trends Forecast 2026-2036
Light and Very Light Jets Market Foresight
Next-generation avionics suites and enhanced cabin pressurization standards are redrawing competitive boundaries in light jet manufacturing. Textron Aviation leverages its Wichita production infrastructure to dominate the high-volume light jet segment. Cirrus Design Corporation differentiates through its single-engine jet platform and whole-airframe parachute system. Honda Aircraft Company anchors the very light jet category with its over-the-wing engine mount configuration that reduces cabin noise.
Light and very light jets are fixed-wing aircraft with maximum takeoff weights below approximately 10,000 kilograms, typically seating four to nine passengers and powered by turbofan engines with thrust ratings under 15,000 pounds. These aircraft serve point-to-point business aviation missions, offering jet speeds at operating costs below mid-size alternatives. The usage model dimension shows fractional ownership expanding fastest as fleet operators seek asset utilization gains, while private ownership retains the largest margin pool through customization and aftermarket service. Engine type segmentation reveals turbofan configurations leading unit deliveries, though electric propulsion research is attracting development capital for sub-regional routes.
FAA Part 23 certification standards and EASA CS-23 frameworks govern airworthiness requirements, with recent reforms enabling performance-based compliance that reduces development timelines for new entrants. EPA emissions regulations and ICAO carbon offset mechanisms are shaping engine technology roadmaps and fleet renewal decisions. Stakeholders must monitor evolving sustainability mandates and their impact on residual value calculations across ownership models.
Market Dynamics
FAA Part 23 certification reforms are compressing development timelines for new airframe designs while turbofan efficiency gains reshape operating economics across ownership models.
Growth Catalysts
- Fractional Ownership Expansion:Fleet operators in the United States are deploying shared-asset models to improve utilization rates among corporate travelers seeking flexible point-to-point mobility without full capital commitment.
- Performance-Based Certification:FAA Part 23 reforms enable streamlined compliance pathways that reduce technical barriers for innovative propulsion configurations and advanced avionics integration.
- Urban Air Mobility Infrastructure:Vertiport development in Florida and Kansas manufacturing clusters is creating operational density that supports light jet deployment for sub-regional business missions.
Market Restraints
- Jet-A Fuel Price Volatility:Operating cost sensitivity constrains flight-hour expansion for owner-operators in price-sensitive segments, particularly where fuel represents the dominant variable expense.
- Specialized MRO Concentration:Maintenance capability scarcity clusters in Wichita and limited secondary markets, creating geographic dependency for airframe-specific technical support.
- Single-Pilot Certification Limits:FAA operational restrictions on certain weight categories restrict fleet flexibility and crew scheduling optimization for charter operators.
Strategic Opportunities
- Electric Propulsion Research:Battery-hybrid architectures for sub-regional routes are attracting development capital from NASA and private ventures targeting 500-nautical-mile missions with reduced noise signatures.
- Intermodal Connectivity:Integration with commercial airline feeder networks at secondary airports offers repositioning efficiency gains for fractional fleet managers in underserved corridors.
- Enhanced Cabin Pressurization:Next-generation environmental systems enabling higher-altitude operations are creating differentiation opportunities for OEMs targeting executive comfort requirements.
Industry Challenges
- Airframe-Specific A&P Technician Shortage:Composite repair certification and turbofan powerplant expertise gaps constrain MRO throughput in expanding operational bases outside Kansas and Florida.
- Type Certificate Amendment Timelines:FAA validation procedures for avionics upgrades and engine retrofits extend downtime periods that compress revenue availability for charter fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light and Very Light Jets Market |
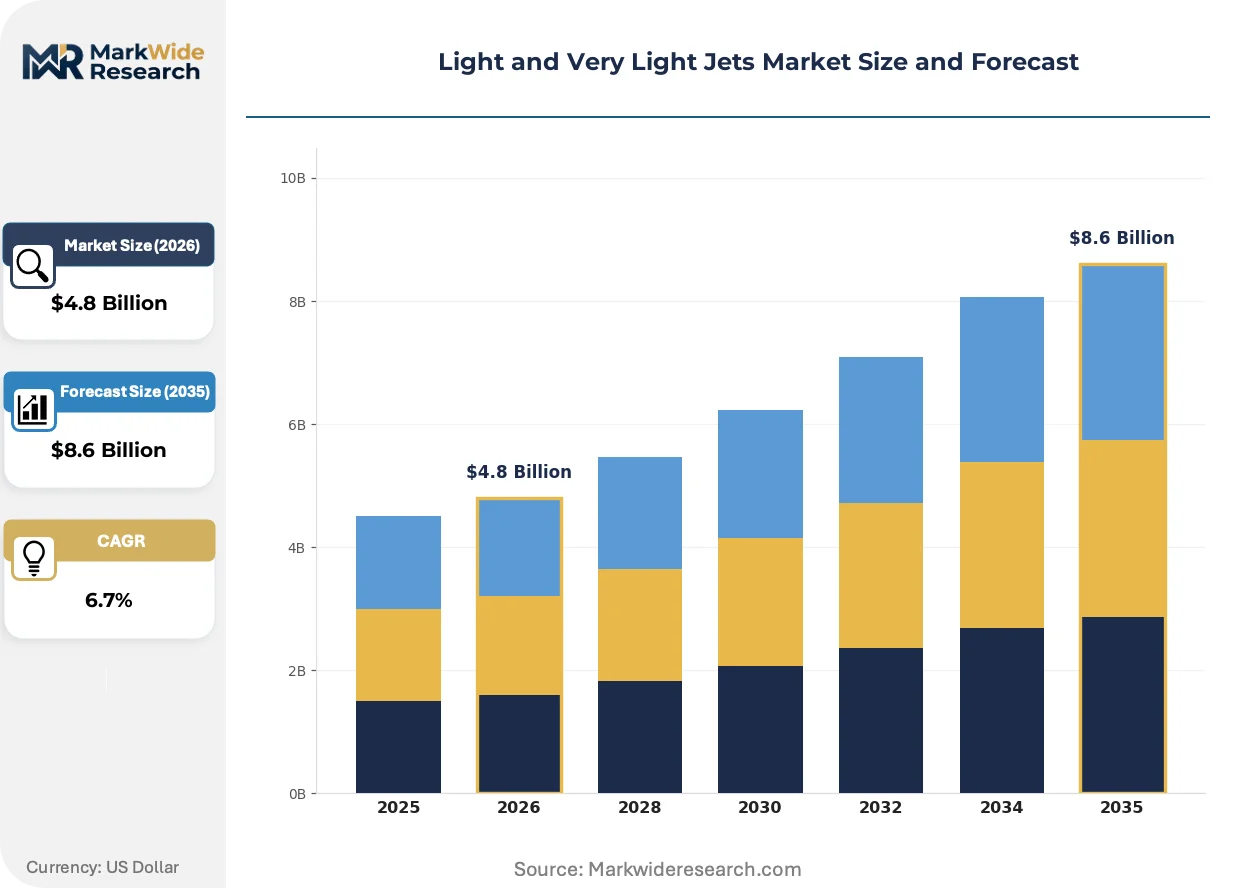
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Very Light Jets, Regional Jets, Business Jets Usage Model: Private Ownership, Charter Services, Fractional Ownership, Time-Share Engine Type: Turbojet, Turbofan, Turboprop, Electric End User: Civil Aviation, Corporate Professionals, Government Entities, Private Individuals |
| Companies Covered | Textron Aviation, Cirrus Design Corporation, Embraer SA, Honda Aircraft Company, Pilatus Aircraft Ltd, Bombardier Inc., Diamond Aircraft Industries, Piper Aircraft, Cessna Aircraft Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light and Very Light Jets Market Shifts & Advancements
Avionics architecture evolution and propulsion research trajectories are restructuring competitive differentiation while certification pathways adapt to accommodate novel airframe configurations.
Fly-by-wire control systems with envelope protection are decomposing traditional mechanical linkage requirements in light jet designs. Corporate flight departments and charter operators are specifying these configurations for single-pilot operations where reduced workload demands justify acquisition premiums. The technology is decomposing the historical correlation between airframe size and pilot staffing economics, enabling smaller jets to compete for missions previously requiring larger aircraft.
EPA emissions standards for non-road engines are tightening particulate and NOx thresholds that affect turbofan core designs. Engine manufacturers are responding with improved combustor architectures and exhaust treatment systems that add weight and complexity. The very light jet segment faces the most acute compliance cost pressure, as airframe size constraints limit thermal management system packaging options relative to larger platforms.
Subscription-based flight-hour access models are displacing traditional whole-aircraft ownership among mid-market corporate users. Charter brokers and fractional providers are capturing demand from executives who prioritize capital efficiency over asset control, particularly in technology and professional services verticals. This behavioral shift concentrates most visibly in the United States, where dense FBO networks and established regulatory frameworks support flexible access program scalability.
Light and Very Light Jets Market Segmentation
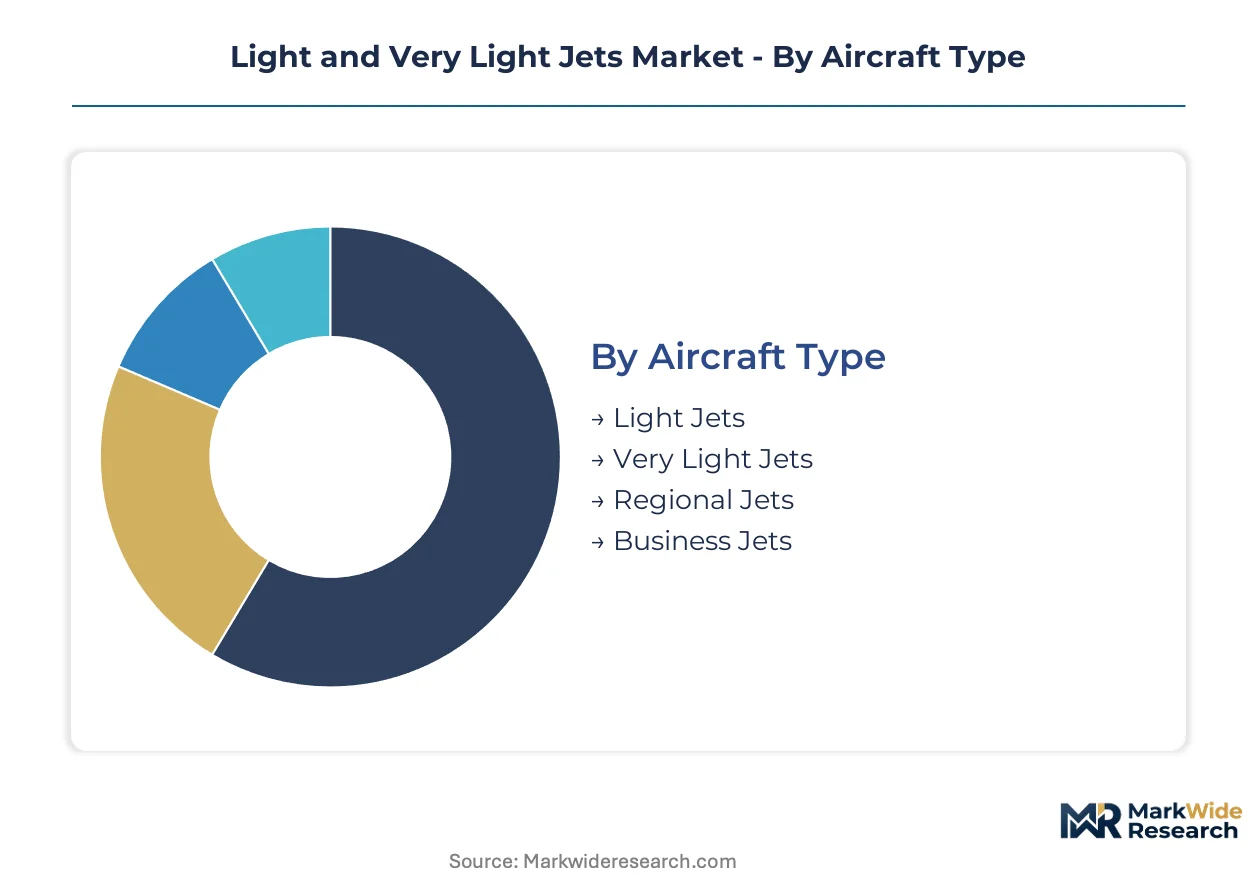
Segmentation in light and very light jets reveals how aircraft specifications, ownership structures, and propulsion technologies align with distinct mission profiles and regulatory environments. Understanding these divisions clarifies where capital deployment concentrates and which configurations face the steepest compliance cost pressures.
Aircraft Type:
Domestic manufacturing clusters in Kansas and Florida anchor production for lighter configurations, while export demand pulls larger business jet variants toward European and Middle Eastern markets.
- Light Jets:These aircraft carry six to nine passengers with maximum takeoff weights between 10,000 and 12,500 pounds. Demand clusters among U.S. corporate flight departments seeking point-to-point efficiency for 500-1,000 nautical mile stages. FAA Part 23 certification reforms compress development timelines for new airframe designs in this bracket.
- Very Light Jets:Single-pilot-certified aircraft seating four to six passengers dominate entry-level business aviation. Fractional ownership programs in the United States deploy these assets most intensively where capital efficiency outweighs cabin size requirements.
- Regional Jets:Larger configurations bridge commercial feeder routes and corporate shuttle missions.
- Business Jets:Premium cabin variants serve intercontinental executive transport with full galley and sleeping configurations.
Light Jets command the established base. The steepest expansion runs through Very Light Jets.
Usage Model:
Capital commitment thresholds separate ownership structures, with full acquisition requiring liquidity reserves that concentrate among private individuals while operating leases attract corporate treasury departments.
- Fractional Ownership:Fleet operators deploy shared-asset models to improve utilization rates across dispersed corporate traveler networks. NetJets and Flexjet structures in the United States demonstrate scalability where FAA regulatory clarity supports program standardization.
- Charter Services:On-demand access eliminates capital deployment while exposing users to aircraft availability constraints during peak demand windows. Part 135 certificate holders in Florida and Kansas manufacturing corridors capture the densest operational concentration.
- Private Ownership:Full asset control enables customization and aftermarket service capture.
- Time-Share:Structured hourly access programs reduce administrative burden versus traditional fractional structures.
Private Ownership retains the deepest margin pool through customization and aftermarket service. Fractional Ownership climbs the fastest as fleet operators pursue asset utilization gains.
Engine Type:
Thrust-to-weight specifications and emissions compliance costs differentiate propulsion choices, with turbofan architectures dominating where noise restrictions and altitude performance justify fuel burn premiums.
- Turbofan:High-bypass configurations power the majority of light jet deliveries, offering jet speeds with operating economics below mid-size alternatives. EPA emissions standards for non-road engines tighten particulate and NOx thresholds that reshape combustor architectures.
- Electric:Battery-hybrid research attracts NASA and private venture capital for sub-regional routes under 500 nautical miles. Noise signature reduction and vertiport compatibility position this configuration for urban air mobility integration.
- Turbojet:Lower-bypass designs persist in legacy platforms where retrofit economics delay fleet renewal.
- Turboprop:Propeller-driven efficiency dominates short-field operations below 300 nautical miles.
Turbofan configurations anchor current production volumes. Electric propulsion gains share fastest where development capital concentrates on noise-restricted corridors.
End User:
Mission requirements and procurement authority structures shape demand patterns, with corporate professionals prioritizing schedule flexibility while government entities emphasize multi-mission adaptability.
- Corporate Professionals:Technology and professional services verticals in the United States prioritize capital efficiency over asset control, driving subscription-based flight-hour access models. Dense FBO networks support flexible program scalability.
- Civil Aviation:Commercial feeder operations and air ambulance services deploy light jets where runway length constraints exclude larger aircraft.
- Government Entities:Multi-mission requirements including surveillance, training, and VIP transport sustain demand for specialized configurations.
- Private Individuals:High-net-worth owners capture customization premiums and residual value through established resale channels.
Corporate Professionals drive the steepest volume expansion. Private Individuals command the highest per-unit margin capture through bespoke configuration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net export positions in business aircraft concentrate in North American manufacturing clusters while import demand pulls European and Middle Eastern buyers toward Wichita and Florida production centers. Trade balances reflect certification advantages under FAA Part 23 reforms that accelerate delivery timelines versus EASA CS-23 pathways. Currency fluctuations and bilateral aviation agreements reshape cross-border transaction volumes across the forecast window.
United States
Fractional ownership programs from NetJets and Flexjet drive fleet expansion among corporate flight departments seeking capital-efficient mobility. FAA Part 23 certification reforms compress type certificate timelines for new airframe designs entering the market. Wichita anchors turbofan-powered light jet production while Florida vertiport development supports very light jet deployment for sub-regional business missions.
Brazil
Embraer's domestic manufacturing base sustains regional jet derivatives that bridge corporate shuttle and commercial feeder applications. ANAC alignment with FAA certification standards enables streamlined export approvals for aircraft destined to North American operators. São Paulo state concentrates executive aviation demand from commodity sector executives requiring point-to-point connectivity to remote extraction sites.
Switzerland
Pilatus Aircraft anchors single-engine turboprop and jet production for European owner-operator segments prioritizing short-field performance. Swissmedic-equivalent airworthiness standards under EASA CS-23 govern type certification for aircraft targeting alpine operations. Stans manufacturing facilities export to Middle Eastern markets where mountain-capable configurations command acquisition premiums.
Japan
Honda Aircraft Company's over-the-wing engine mount configuration reduces cabin noise signatures for domestic executive travelers. METI-supported aerospace development programs channel research funding toward advanced propulsion architectures. Nagoya-area engineering clusters collaborate with U.S. certification consultants to navigate FAA Part 23 compliance for export-bound very light jet variants.
United Arab Emirates
Dubai and Abu Dhabi flight departments import North American-manufactured light jets for regional business connectivity across Gulf Cooperation Council corridors. GCAA regulatory harmonization with FAA standards simplifies registration transfers for pre-owned aircraft entering the fleet. Sharjah's emerging MRO capabilities address maintenance scarcity that previously required ferry flights to European service centers.
Light and Very Light Jets Market Competitive Landscape
Listed aerospace conglomerates compete with private specialists across certification expertise and production scale dimensions. Market structure tilts toward consolidated manufacturing where type certificate portfolios create switching costs for fleet operators. Three archetypes dominate: diversified conglomerates with defense-aerospace cross-subsidies, pure-play business jet specialists, and diversified industrial groups with aviation divisions. Competitive moves concentrate on strategic partnerships for avionics integration and geographic expansion through fractional ownership platform acquisitions.
Within the diversified conglomerate tier, Textron Aviation and Embraer SA exemplify scale-driven positions anchored by Wichita and São Paulo manufacturing infrastructures. Cirrus Design Corporation and Honda Aircraft Company occupy specialist positions emphasizing single-pilot certification and noise-reduction engineering. These named entities represent archetype anchors rather than exhaustive market coverage, with private specialists including Pilatus Aircraft Ltd and Diamond Aircraft Industries sitting within owner-operator-focused segments where customization capabilities command margin premiums.
| Leading Market Players |
|---|
| Textron Aviation |
| Cirrus Design Corporation |
| Embraer SA |
| Honda Aircraft Company |
| Pilatus Aircraft Ltd |
| Bombardier Inc. |
| Diamond Aircraft Industries |
| Piper Aircraft |
| Cessna Aircraft Company |
| Others |
Supply & Pricing Matrix
Wichita production scale economies concentrate airframe assembly capacity for light jet OEMs, compressing unit costs for turbofan-powered configurations while elevating price floors for very light jet variants where manufacturing volume remains thinner. FAA Part 23 certification reforms reduce compliance overhead for new entrants, yet specialized MRO scarcity in secondary markets preserves pricing power for incumbent service networks in Kansas and Florida manufacturing corridors.
Pricing Analysis
Corporate flight departments anchor pricing stratification across premium, standard, and economy tiers differentiated by cabin pressurization performance and avionics architecture. Three-tier pricing structure separates fly-by-wire equipped platforms from conventional mechanical linkage alternatives, with single-pilot certification premiums commanding acquisition price spreads. Cost compression in the very light jet segment intensifies because EPA emissions compliance adds thermal management weight penalties that squeeze margins on smaller airframes. Charter operators exhibit the sharpest price sensitivity, while private individuals purchasing through fractional programs prioritize capital efficiency over per-unit acquisition cost.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes from Japan and China elevate inbound logistics costs for composite pre-preg materials and turbofan engine subassemblies. Manufacturing gravity centers on Wichita, Kansas and São Paulo, Brazil for airframe fabrication, with avionics suites sourcing from U.S. and Swiss suppliers. Supply chain risk concentrates in single-source vulnerability for specialized A&P technician certification programs that feed MRO networks. Distribution runs through fractional fleet operators and Part 135 certificate holders who capture flight-hour revenue across dense FBO networks in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward fractional fleet operators as NetJets and Flexjet consolidate flight-hour demand, fragmenting pricing leverage for individual owner-operators and concentrating procurement volume among corporate treasury departments.
For Market Incumbents: Fortify type certificate portfolios through avionics upgrade pathways that extend platform lifecycles against emerging electric propulsion substitutes. Expand captive MRO capacity in Florida vertiport corridors to preempt third-party service capture. Vertical integration into composite repair certification programs addresses technician scarcity threatening aftermarket revenue retention. For New Entrants and Emerging Players: Anchor in sub-regional routes under 500 nautical miles where battery-hybrid research attracts NASA development capital and noise-restricted vertiport infrastructure creates operational density. Target underserved corridors between secondary airports where fractional fleet repositioning inefficiencies leave demand gaps. Pursue FAA Part 23 performance-based certification as the primary go-to-market pathway to compress regulatory timelines versus traditional compliance routes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified conglomerates with defense-aerospace cross-subsidies that can absorb turbofan emissions compliance costs pressuring pure-play specialists. Long-term viability rests on type certificate portfolio breadth that creates switching costs for fleet operators renewing aging platforms. Watch electric propulsion certification milestones as the inflection signal for asset reallocation between turbofan and hybrid architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Certification Investment | FAA Part 23 reforms enable streamlined compliance that accelerates new airframe entry against legacy timelines. |
| Vertiport Infrastructure Partnership | Florida and Kansas operational density supports very light jet deployment for sub-regional business missions. |
| Electric Propulsion R&D Alliance | NASA and private venture capital channel development funding toward 500-nautical-mile battery-hybrid architectures. |
| Fractional Platform Acquisition | NetJets and Flexjet structures demonstrate scalability where dense FBO networks support program standardization. |
| MRO Capacity Expansion | Specialized A&P technician certification gaps constrain throughput outside Wichita and Florida manufacturing clusters. |
Research Methodology
Initial hypotheses were tested against primary input from fractional fleet operators, Part 135 certificate holders, airframe OEM procurement directors, and MRO service managers and refined through secondary validation against FAA type certificate databases, EASA CS-23 submission records, EPA emissions compliance filings, and ICAO carbon offset mechanism documentation. Bottom-up aircraft delivery forecasts were triangulated with top-down market sizing derived from corporate flight department capital expenditure surveys and charter broker transaction data.
Variance decomposition across the projection horizon isolates segmentation dimensions including aircraft type, ownership structure, engine configuration, and end-user mission profile. CAGRs were derived from installed base growth rates adjusted for fleet retirement patterns and replacement demand cycles. Industry-specific forecast inputs incorporate turbofan efficiency trajectories, vertiport development timelines, and fractional ownership penetration curves.
Material uncertainties — Jet-A fuel price volatility, FAA operational restriction amendments, and electric propulsion certification delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and technology transition pacing that could shift materially. Recalibration cycles align with material shifts in emissions mandates and urban air mobility infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Global Helicopter Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Aviation Crew Management System Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Aerospace Winglet System Market
Aircraft
Flight Management Systems Market
Aircraft
Evtol Aircraft Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Manned Evtol Crafts Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Global Aircraft Electric Brake Control System Market
Aircraft
Electric Aircraft Market