
 Aircraft Cargo Systems Market | 2026-2036
Aircraft Cargo Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cargo Systems Market Outlook
Composite-reinforced cargo flooring is broadening the performance envelope for lightweight payload systems. Collins Aerospace leverages its integrated aerostructures portfolio to dominate wide-body cargo deck solutions. Telair International GmbH sustains engineering leadership through pneumatic actuation technology for main-deck loaders. Ancra International anchors its position in restraint systems via specialized webbing and tie-down hardware.
Aircraft cargo systems encompass the mechanical, electromechanical, and pneumatic equipment used to load, secure, transport, and unload freight aboard fixed-wing and rotary-wing aircraft, typically rated for loads between 9g and 16g crashworthiness depending on installation class. These systems serve the primary commercial purpose of maximizing volumetric efficiency while ensuring airworthiness compliance during all flight phases. Unit Load Devices command the largest installed base due to standardized compatibility with wide-body lower decks and main-deck configurations, though RFID Tracking is expanding fastest as carriers pursue real-time inventory visibility across hub-and-spoke networks. Container Systems concentrate margin pools where custom fire-containment and temperature-controlled variants serve pharmaceutical and lithium-battery transport protocols.
FAA airworthiness directives and EASA CS-25 certification standards govern crashworthiness, fire suppression integration, and rapid-decompression safety for all cargo system installations on civil aircraft. The EU Green Deal and ICAO carbon-offset mechanisms are pressuring operators to reduce empty-container repositioning, which redirects procurement toward lighter, collapsible Unit Load Device designs. Stakeholders must monitor evolving lithium-battery transport rules from IATA and national aviation authorities, as these classifications determine which Container Systems and restraint configurations qualify for hazardous-material routes.
Market Dynamics
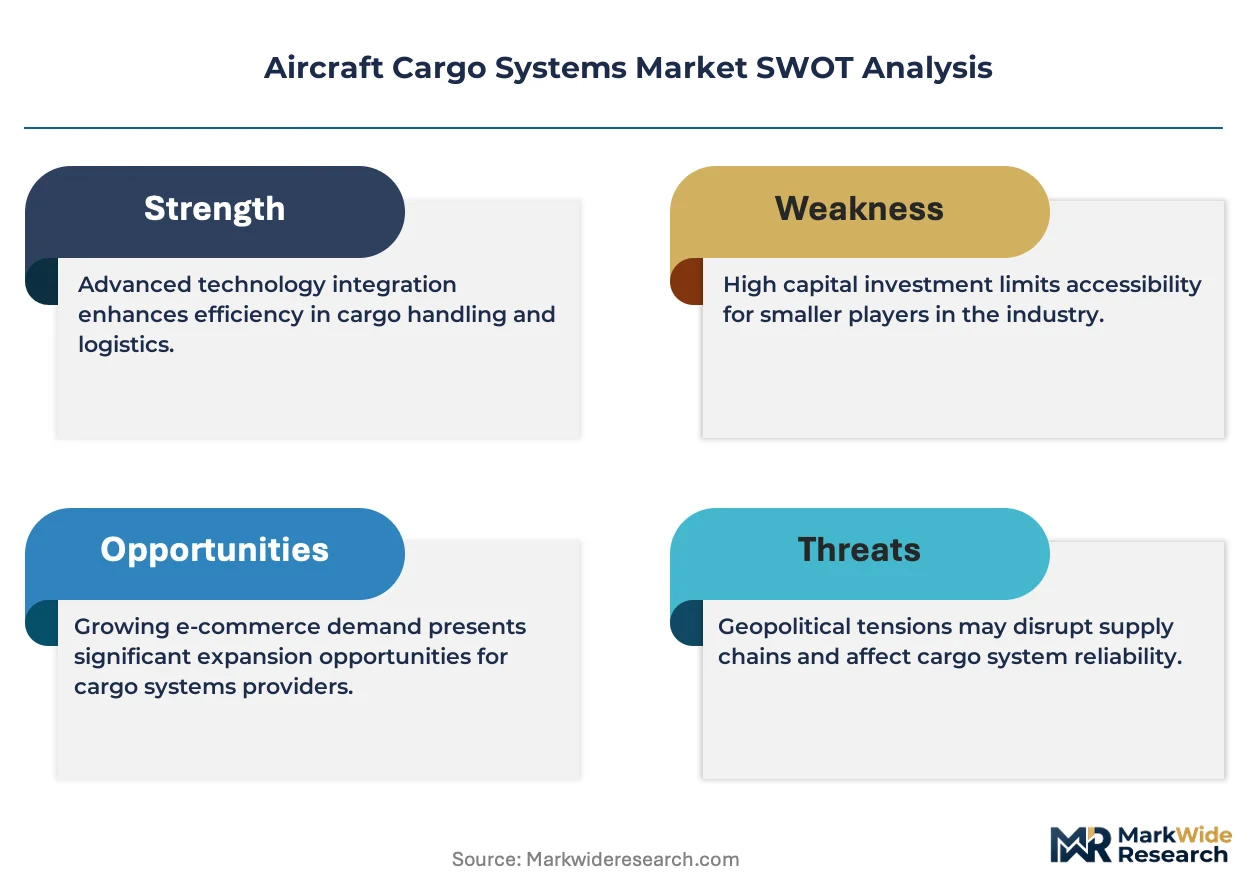
Freighter fleet expansion by e-commerce logistics carriers is compressing procurement cycles for lightweight cargo restraint systems as parcel volume surges strain legacy container inventories.
Growth Catalysts
- FAA Fire-Resistance Mandates:Tightened certification requirements for cargo restraint systems are forcing replacement cycles across North American freighter fleets.
- E-Commerce Parcel Surge:Express carriers are retrofitting narrow-body aircraft for quick-change cargo configurations to capture regional express volume.
- Composite Material Substitution:Carbon-fiber-reinforced flooring panels are displacing aluminum honeycomb structures in new-build wide-body programs.
Market Restraints
- Titanium Input Volatility:Aerospace-grade titanium pricing swings compress margin stability for precision-machined tie-down fittings.
- Single-Source Pneumatics Risk:Main-deck loader actuation systems concentrate engineering knowledge with German component specialists.
- Lithium-Battery Classification Friction:IATA Dangerous Goods Regulations create routing restrictions that disqualify standard container designs from high-yield pharmaceutical lanes.
Strategic Opportunities
- Indian Subcontinent Manufacturing:IndiGo and SpiceJet cargo subsidiary formation creates demand for narrow-body container systems at price points below European benchmarks.
- RFID-Enabled Unit Load Devices:Real-time location tracking integration with airline enterprise resource planning systems opens recurring software revenue streams.
- EU Green Deal Collapsible Designs:Empty-container repositioning penalties are redirecting procurement toward foldable pallet formats that reduce deadhead fuel burn.
Industry Challenges
- 16g Crashworthiness Engineering Talent:Finite-element analysis specialists with civil aviation certification experience command premium compensation and extended recruitment timelines.
- Dual Certification Parallelism:FAA-EASA harmonization gaps force redundant testing protocols for main-deck cargo door systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cargo Systems Market |
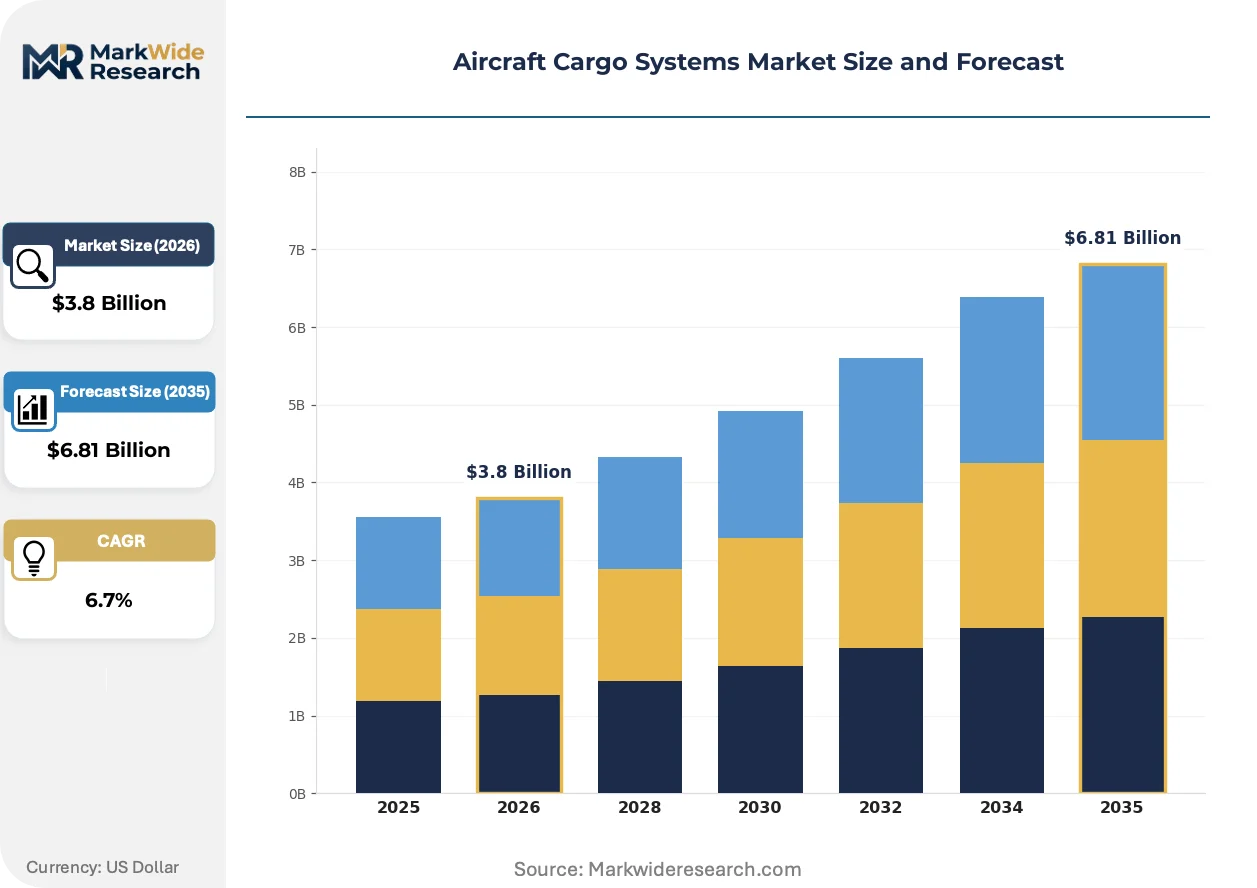
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load Devices, Cargo Nets, Cargo Handling Equipment, Container Systems End User: Airlines, Freight Forwarders, Cargo Airlines, Military Technology: Automated Systems, Manual Handling, RFID Tracking, Pneumatic Systems Application: Commercial Aviation, Military Transport, Humanitarian Aid, Emergency Response |
| Companies Covered | Collins Aerospace, Telair International GmbH, Ancra International, Kietek, Cargo Systems Inc., Onboard Systems International, CEF Industries, U.S. Cargo, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cargo Systems Market Strategic Shifts
Digital integration across cargo handling workflows is compressing the value capture window for hardware-only suppliers while expanding margins for connected system architectures.
Electro-mechanical actuation is consolidating pneumatic heritage positions in main-deck cargo loading systems. Cargo operators operating high-cycle hub networks are specifying servo-driven ball-screw mechanisms for reduced maintenance intervals. This transition is consolidating aftermarket service revenue around electrical system specialists with diagnostic software capabilities.
EASA CS-25 Amendment 25-157 introduced revised rapid-decompression testing protocols for Class E cargo compartments. European freighter conversion specialists now face extended certification timelines for fire-suppression integration. Container manufacturers serving transatlantic routes are redesigning pressure-relief venting to satisfy both FAA and EASA divergence in test pressure differentials.
Airline procurement departments are unbundling container purchase from long-term service agreements. Middle Eastern cargo hubs are negotiating direct manufacturer relationships for Unit Load Device fleets, bypassing traditional lessor intermediaries. This disintermediation is most visible in Dubai and Doha, where Emirates and Qatar Airways cargo divisions are consolidating supplier panels to capture volume pricing leverage.
Aircraft Cargo Systems Market Segmentation
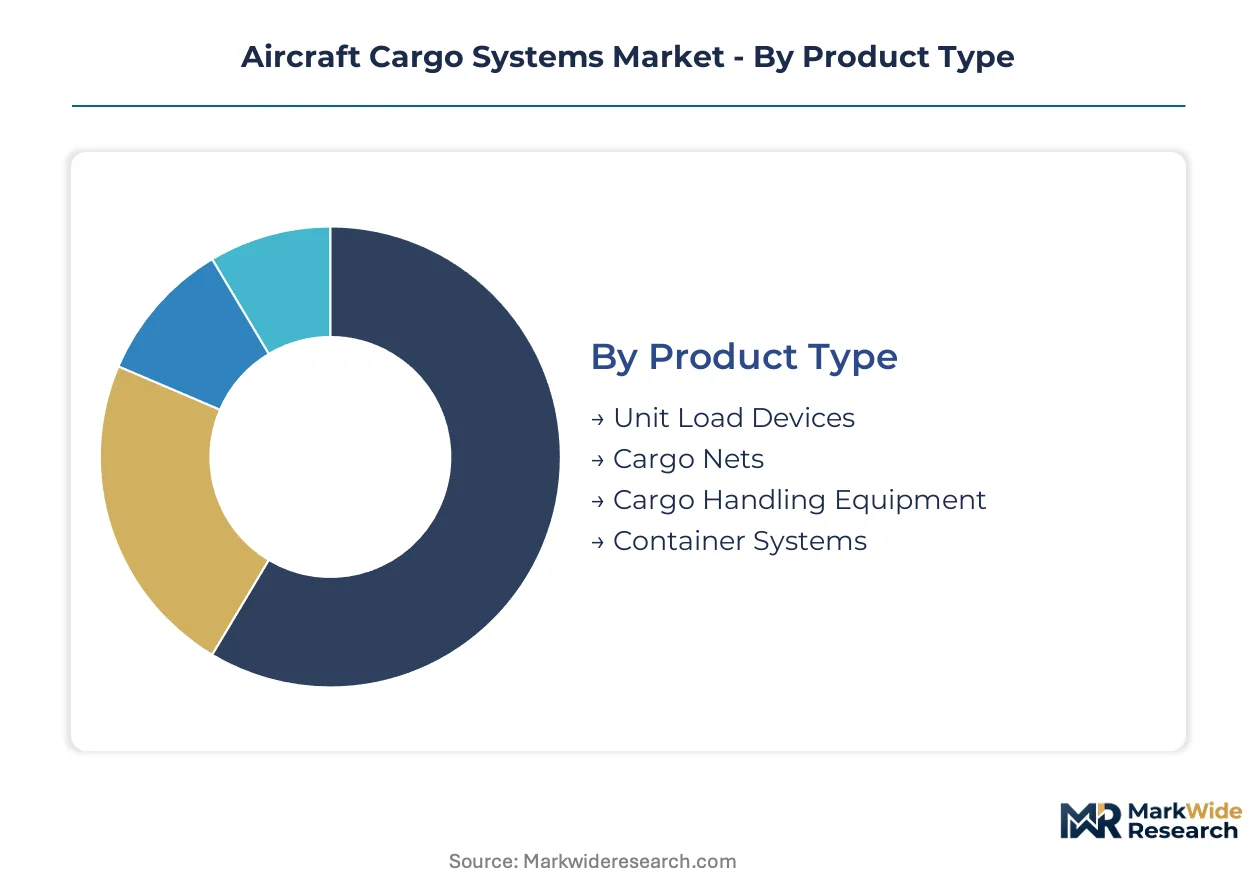
Cargo system procurement diverges sharply between high-cycle commercial operators seeking standardized interchangeability and specialized missions demanding custom restraint configurations. Understanding these segment boundaries clarifies where engineering investment concentrates versus where price competition dominates.
Product Type:
Unit Load Devices command the volume base while Container Systems capture premium margins through hazardous-material certifications.
- Unit Load Devices:Standardized pallets and containers rated for 9g crashworthiness dominate wide-body lower-deck configurations. Demand concentrates at integrator hubs in Louisville and Memphis where FedEx and UPS maintain massive container pools for overnight parcel networks.
- Container Systems:Fire-containment variants with pressure-relief venting serve pharmaceutical and lithium-battery transport under evolving IATA Dangerous Goods Regulations. European freighter operators at Frankfurt and Amsterdam Schiphol drive specification upgrades to satisfy both FAA and EASA divergence in rapid-decompression testing protocols.
- Cargo Nets:Webbing and tie-down assemblies rated for 16g crashworthiness secure irregular freight on main-deck configurations.
- Cargo Handling Equipment:Main-deck loaders and lower-deck conveyor systems interface directly with aircraft structural interfaces.
Mature deployment sits with Unit Load Devices across established express networks. Newer deployment is concentrated in Container Systems as hazardous-material routing restrictions multiply.
End User:
Airlines anchor procurement volume while Military buyers impose specialized survivability specifications.
- Airlines:Passenger carriers operating quick-change narrow-body freighters specify lightweight restraints to preserve payload-range economics. IndiGo and SpiceJet cargo subsidiaries in India are compressing price points below European benchmarks for narrow-body container systems.
- Cargo Airlines:Dedicated freighter operators at Dubai and Doha are disintermediating traditional lessor intermediaries through direct manufacturer relationships for Unit Load Device fleets.
- Freight Forwarders:Third-party logistics providers lease container capacity without asset ownership, driving demand for interchangeable ULD pooling systems.
- Military:Defense operators require 16g crashworthiness and ballistic protection for tactical airlift platforms.
Volume procurement concentrates with Cargo Airlines consolidating supplier panels. Specialized engineering investment flows toward Military programs with extended certification timelines.
Technology:
Manual Handling retains installed-base dominance while RFID Tracking climbs fastest on connectivity mandates.
- RFID Tracking:Real-time location integration with airline enterprise resource planning systems enables hub-and-spoke inventory visibility. Emirates and Qatar Airways cargo divisions are specifying RFID-enabled Unit Load Devices to compress ground-handling search times at Middle Eastern mega-hubs.
- Automated Systems:Servo-driven ball-screw mechanisms are displacing pneumatic heritage in high-cycle main-deck loaders.
- Manual Handling:Human-operated restraint and loading protocols persist at secondary airports with low freight volumes.
- Pneumatic Systems:German component specialists retain engineering concentration for legacy main-deck loader actuation, creating single-source supply risk.
Electro-mechanical architectures are gaining share fastest in new-build programs. Pneumatic maintenance revenue concentrates with established aftermarket service networks.
Application:
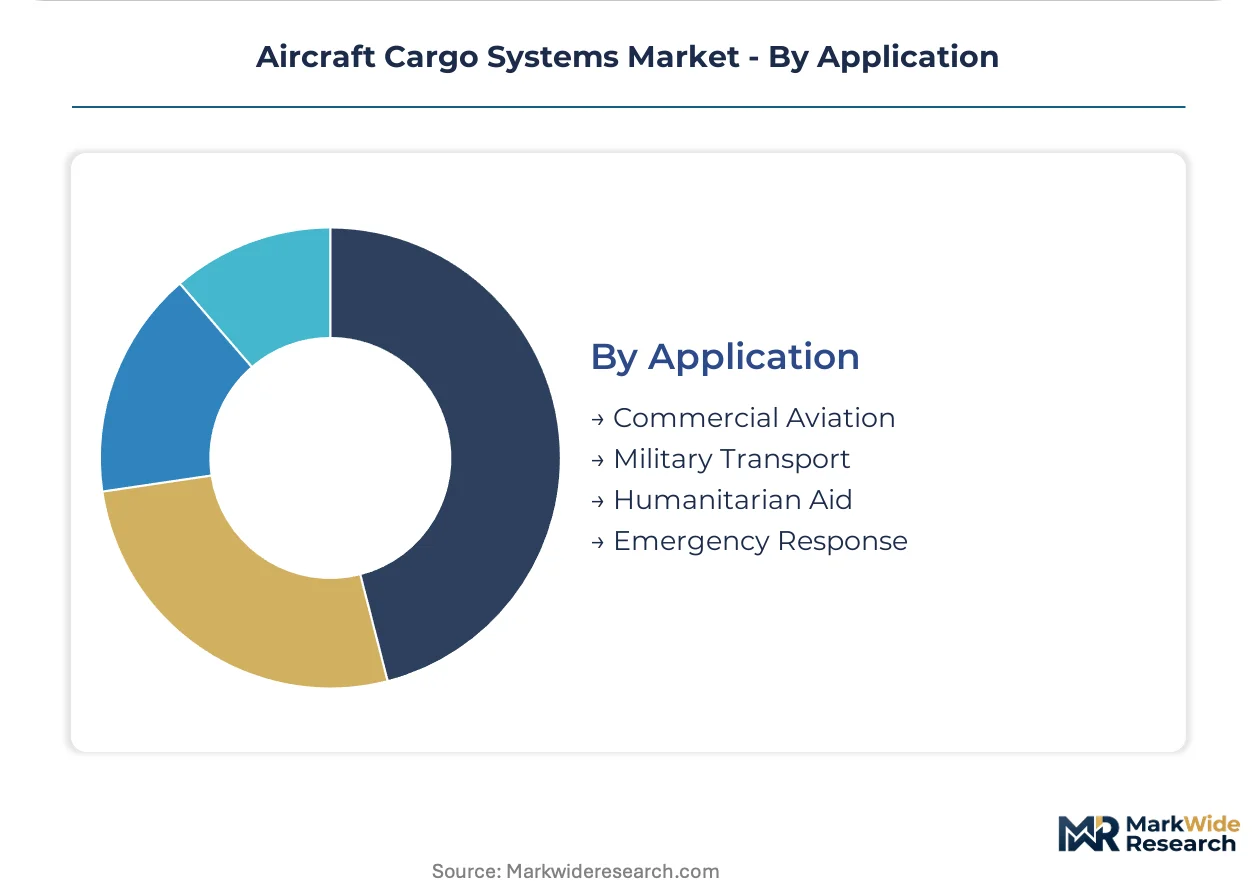
Commercial Aviation generates recurring replacement demand while Emergency Response requires rapid-deployment modularity.
- Commercial Aviation:Scheduled cargo and passenger belly-hold operations drive standardized container procurement cycles tied to fleet renewal.
- Military Transport:Tactical airlift platforms require rapid reconfiguration between passenger, palletized cargo, and airdrop modes.
- Humanitarian Aid:Non-governmental organizations specify collapsible pallet formats to reduce empty-container repositioning costs under EU Green Deal carbon-offset mechanisms.
- Emergency Response:Disaster relief operators demand quick-install restraint systems compatible with leased wide-body aircraft on short notice.
Steady revenue flow anchors in Commercial Aviation fleet expansion. Steepest expansion trajectory appears in Humanitarian Aid as foldable designs penetrate development-finance procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrator hub concentration in the United States drives the largest specialized container procurement volumes, while regulatory divergence between Washington and Brussels fragments certification timelines for transatlantic operators.
United States
FedEx and UPS maintain massive Unit Load Device pools at Louisville and Memphis for overnight parcel networks. FAA tightened fire-resistance standards for cargo restraint systems through updated airworthiness directives. Seattle-area engineering clusters supply composite-reinforced flooring panels to Boeing wide-body programs.
Germany
Lufthansa Cargo and DHL Express compress procurement cycles for pneumatic main-deck loader systems at Frankfurt hub operations. EASA CS-25 Amendment 25-157 introduced revised rapid-decompression testing protocols for Class E cargo compartments. Hamburg freighter conversion specialists face extended certification timelines for fire-suppression integration.
United Arab Emirates
Emirates and Qatar Airways cargo divisions consolidate supplier panels for RFID-enabled Unit Load Device fleets at Dubai and Doha mega-hubs. The country's General Civil Aviation Authority aligns with ICAO carbon-offset mechanisms pressuring lighter container designs. Dubai South logistics corridor anchors direct manufacturer relationships bypassing traditional lessor intermediaries.
India
IndiGo and SpiceJet cargo subsidiary formation creates demand for narrow-body container systems below European price benchmarks. The Directorate General of Civil India enforces BIS certification standards for imported restraint hardware. Bangalore and Hyderabad maintenance clusters retrofit quick-change cargo configurations for regional express volume capture.
China
E-commerce logistics carriers expand domestic freighter fleets to meet parcel volume surges across Yangtze River Delta manufacturing zones. CAAC harmonizes with FAA-EASA divergence on lithium-battery transport classifications for pharmaceutical lanes. Shanghai Pudong cargo terminals drive specification upgrades for pressure-relief venting designs.
Aircraft Cargo Systems Market Competitive Environment
Portfolio diversification dominates the current landscape as suppliers unbundle hardware sales from long-term service agreements to capture airline procurement department preferences. The vendor base concentrates around three strategic archetypes: integrated aerostructures conglomerates, pneumatic actuation specialists, and restraint hardware fabricators. M&A activity and technology licensing partnerships represent the two dominant competitive moves reshaping competitive positioning.
Within the integrated aerostructures tier, Collins Aerospace occupies a position exemplifying full-cargo-deck solution dominance. Telair International GmbH represents the pneumatic heritage concentration in German component engineering. Ancra International anchors the restraint systems specialization segment through webbing and tie-down hardware expertise.
| Leading Market Players |
|---|
| Collins Aerospace |
| Telair International GmbH |
| Ancra International |
| Kietek |
| Cargo Systems Inc. |
| Onboard Systems International |
| CEF Industries |
| U.S. Cargo |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
Cargo airline procurement departments at Emirates, Qatar Airways, and FedEx anchor pricing power through direct manufacturer relationships that bypass traditional lessor intermediaries. This buyer concentration compresses margin pools for hardware-only suppliers while expanding recurring revenue capture for connected system architectures with embedded service agreements.
Pricing Analysis
Volume procurement concentrates in standardized Unit Load Devices rated for 9g crashworthiness, while premium margins flow to fire-containment Container Systems with pharmaceutical and lithium-battery certifications. Price differentiation separates FAA-EASA dual-certified variants from single-jurisdiction alternatives, with composite-reinforced flooring commanding material premiums over aluminum honeycomb. Cost compression in narrow-body container systems intensifies because IndiGo and SpiceJet cargo subsidiaries in India are forcing European benchmarks downward. Express carriers operating high-cycle hub networks exhibit lowest price sensitivity, while regional freight forwarders leasing pooled capacity face acute margin pressure.
Supply Chain Analysis
Ocean freight and air cargo rates from German component specialists to Dubai and Doha mega-hubs feed directly into main-deck loader system pricing. Manufacturing concentrates in Germany for pneumatic actuation heritage, the United States for composite aerostructures integration, and India for narrow-body container fabrication at reduced labor benchmarks. Raw material dependencies draw from aerospace-grade titanium for precision-machined tie-down fittings, carbon fiber prepreg for reinforced flooring panels, and specialized aramid webbing for 16g crashworthiness restraint systems. Single-source vulnerability concentrates in German pneumatic engineering knowledge for legacy main-deck loader actuation. Distribution runs through direct airline procurement departments consolidating supplier panels, with Middle Eastern hubs disintermediating traditional lessor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft cargo systems suppliers are racing to capture downstream service revenue through RFID-enabled tracking integration and aftermarket diagnostics software, with vertical integration into connected system architectures determining margin sustainability.
For Market Incumbents: Extend certification investment into dual FAA-EASA harmonization for main-deck cargo door systems, closing the engineering gap created by Amendment 25-157 rapid-decompression protocol divergence. Anchor aftermarket service revenue through electro-mechanical actuation diagnostics capabilities as pneumatic heritage positions erode. Lock in long-term container fleet management contracts with Emirates and Qatar Airways cargo divisions before direct manufacturer relationships fully disintermediate lessor intermediaries. For New Entrants and Emerging Players: Regional MRO networks in Bangalore and Hyderabad represent the most penetrable channel for quick-change cargo configuration retrofits on narrow-body aircraft. Target price-sensitive Indian cargo subsidiaries with collapsible pallet designs certified under BIS standards that undercut European benchmarks. Pursue humanitarian aid procurement channels where EU Green Deal carbon-offset mechanisms favor foldable formats reducing empty-container repositioning costs. For Investors and Strategic Acquirers: The window for entry favors electro-mechanical system specialists with embedded software capabilities over hardware-only fabricators. Mid-cap targets with FAA-EASA dual certification portfolios and established relationships with Lufthansa Cargo or DHL Express at Frankfurt offer strongest 5-10 year viability. Monitor IATA lithium-battery classification revisions as the critical inflection signal—routing restrictions that disqualify standard container designs will concentrate premium margin pools in fire-containment variants.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Integration Partnership | Emirates and Qatar Airways cargo divisions are specifying real-time tracking to compress ground-handling search times at Dubai and Doha. |
| Dual Certification Investment | Hamburg freighter conversion specialists face extended timelines for fire-suppression integration under EASA CS-25 Amendment 25-157. |
| Composite Material Substitution | Seattle-area engineering clusters supply carbon-fiber-reinforced flooring panels displacing aluminum honeycomb in Boeing wide-body programs. |
| Direct Manufacturer Relationship | Middle Eastern cargo hubs are bypassing traditional lessor intermediaries to capture volume pricing leverage on Unit Load Device fleets. |
| Collapsible Design Development | EU Green Deal penalties on empty-container repositioning are redirecting procurement toward foldable pallet formats reducing deadhead fuel burn. |
Study Parameters
Independent corroboration across cargo airline procurement executives, MRO maintenance directors, and freighter conversion specialists underwrites the qualitative findings in this study. Primary fieldwork engaged fleet planners at FedEx and UPS hub operations in Louisville and Memphis, engineering leads at Lufthansa Cargo in Frankfurt, and regulatory affairs officers navigating FAA-EASA harmonization gaps. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 amendment documentation, IATA Dangerous Goods Regulations updates, and customs records tracking Unit Load Device trade flows. Bottom-up container inventory modeling triangulated against top-down freighter fleet expansion projections across the analysis window.
Rate-of-change decomposition across the modeling period isolated e-commerce parcel volume trajectories, composite material substitution elasticities, and regulatory compliance cost step-functions. Segmentation dimensions spanned product type (Unit Load Devices, Container Systems, cargo nets, handling equipment), end user (airlines, cargo airlines, freight forwarders, military), technology tier (RFID-enabled, automated, manual, pneumatic), and application context (commercial aviation, military transport, humanitarian aid, emergency response). CAGRs were derived from fleet renewal cycles, hazardous-material routing restriction intensities, and collapsible design adoption curves in EU-regulated corridors.
Caveats apply where lithium-battery classification friction, titanium input volatility, or FAA-EASA harmonization delays could materially shift the outlook. Forecasts reflect assumptions on e-commerce logistics carrier fleet expansion rates and carbon-offset mechanism enforcement stringency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
US Business Jet Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Flight Management Systems Market
Aircraft
Air Starter Market
Aircraft
Aircraft Door Market
Aircraft
Strategic Bomber Market
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
UK Aviation Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
UK Military Aviation Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Asia-Pacific Military Helicopters Market