
 Automotive Smart Helmet Market | 2026-2036
Automotive Smart Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Helmet Market Analysis
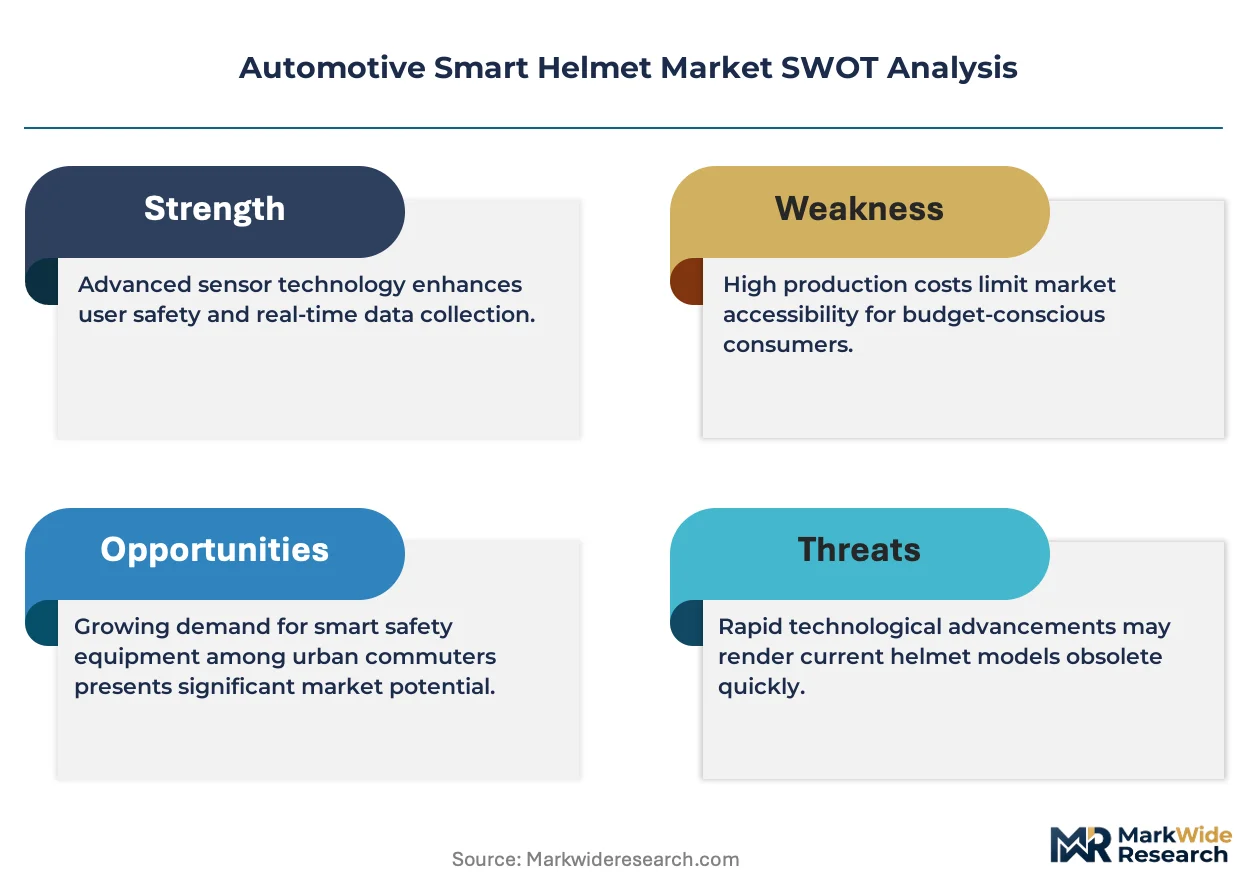
The capital-intensity divergence between players is bifurcating competitive tiers across the Automotive Smart Helmet Market. Schuberth GmbH leverages German engineering heritage and in-house acoustic testing to sustain premium positioning in modular systems. Livall competes through aggressive Bluetooth integration and price-accessible connected features for Asian markets.
An automotive smart helmet integrates sensor arrays, communication modules, and optical projection systems into protective headgear engineered to ECE 22.06 or DOT impact standards, with primary purpose of delivering real-time navigation, hazard alerts, and biometric monitoring to powered-two-wheeler operators. Full-face configurations anchor current revenue pools due to superior electronics packaging volume and aerodynamic stability for heads-up display projection. Augmented reality technology represents the fastest-expanding segment as micro-display luminance and field-of-view specifications mature for daylight-readable overlay applications.
ECE 22.06 enforcement across European markets and NHTSA DOT certification requirements in the United States shape baseline safety compliance, while FCC radio equipment authorization governs Bluetooth and cellular connectivity modules. India's BIS certification and mandatory two-wheeler helmet laws in Maharashtra and Karnataka create dual regulatory pressure for connected safety adoption. Stakeholders must monitor harmonization gaps between electromagnetic emission standards and crash-test protocols as software-defined helmet architectures proliferate.
Market Dynamics
Fleet operator mandates for connected safety equipment are compressing upgrade cycles across powered-two-wheeler segments, forcing helmet manufacturers to integrate sensor arrays and communication modules into certified protective shells faster than traditional product development timelines permit.
Growth Catalysts
- Last-mile logistics expansion:Food delivery and e-commerce fleet operators in India now require Bluetooth-enabled helmets with GPS tracking for rider accountability and route optimization.
- ECE 22.06 enforcement:European helmet certification standards now mandate rotational impact testing, accelerating replacement demand for legacy inventory across Germany, France, and Italy.
- Micro-display luminance advances:Heads-up display technology achieving daylight-readable brightness specifications is enabling augmented reality navigation overlays in premium motorcycle segments.
Market Restraints
- Lithium-ion battery thermal management:Energy density requirements for all-day communication module operation create fire-safety certification complications under UN 38.3 transport regulations.
- Optics supply concentration:Waveguide and micro-display manufacturing concentrates in Taiwanese and South Korean fabrication facilities, exposing helmet assemblers to single-source component risk.
- Smartphone navigation substitution:Handlebar-mounted phone holders with waterproofing remain the default rider choice for turn-by-turn directions, limiting heads-up display willingness-to-pay.
Strategic Opportunities
- Maharashtra and Karnataka state mandates:India's mandatory helmet laws for two-wheeler operators create regulatory tailwinds for connected safety equipment adoption in high-density urban corridors.
- Biometric monitoring integration:Convergence of photoplethysmography sensors with crash-detection algorithms enables emergency service dispatch automation for solo riders.
- Direct-to-fleet sales channels:Bypassing traditional motorcycle dealership networks through B2B procurement platforms reduces distribution friction for volume fleet contracts.
Industry Challenges
- ECE 22.06 homologation timelines:Rotational impact testing protocols extend certification cycles by four to six months, compressing product launch windows against fast-moving electronics refresh rates.
- Embedded software validation:Over-the-air update capabilities for helmet firmware require cybersecurity compliance frameworks that most protective equipment manufacturers lack internal expertise to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Helmet Market |
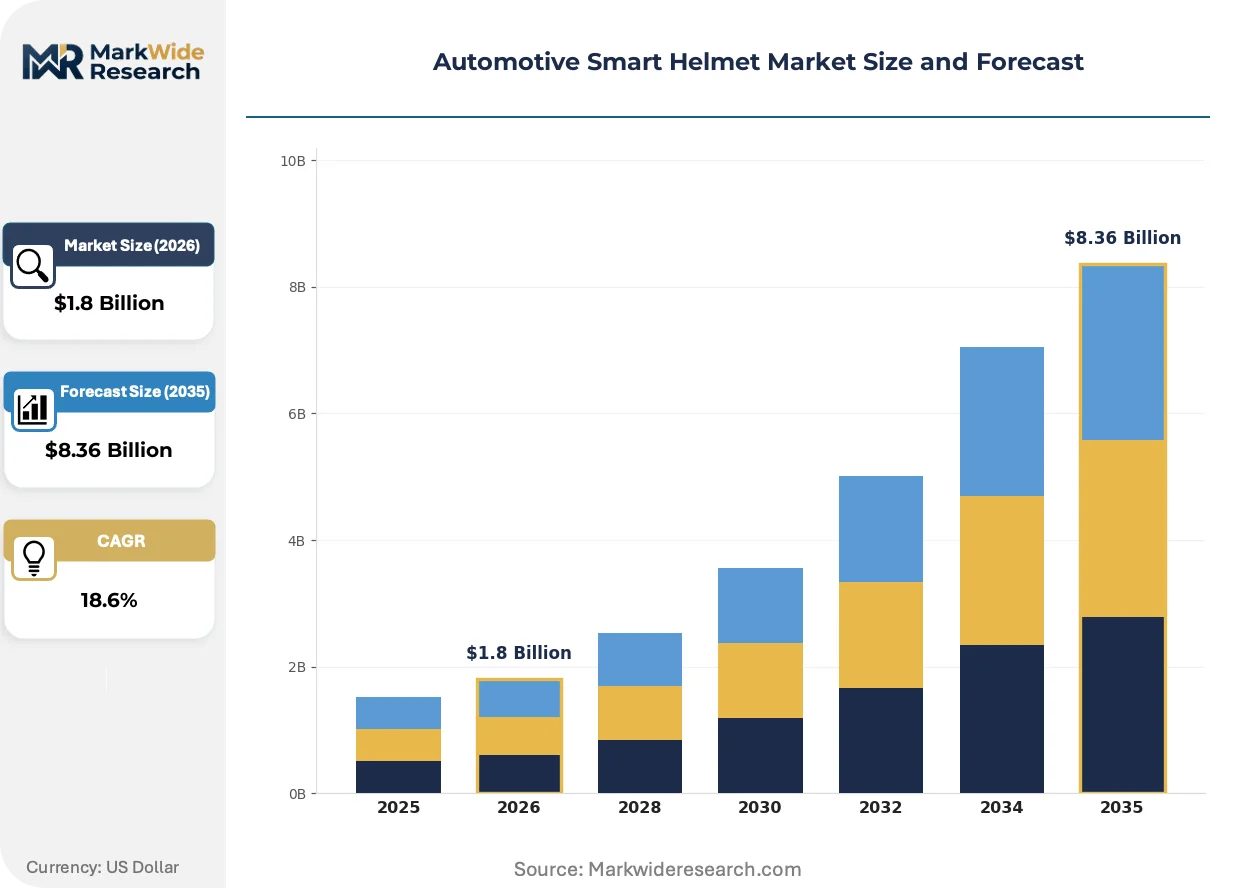
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Face, Open Face, Modular, Half Helmet Technology: Bluetooth, Augmented Reality, Voice Recognition, Heads-Up Display End User: Motorcyclists, Delivery Riders, Professional Racers, Leisure Riders Material: Carbon Fiber, Polycarbonate, Fiberglass, Thermoplastic |
| Companies Covered | HJC Europe SARL, Livall, Sena Technologies Inc., Schuberth GmbH, Jarvish, Forcite Helmet Systems Pty Ltd., Bell Helmets, Arai Helmet Europe BV, CrossHelmet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Helmet Market Emerging Trajectories
Electronics packaging density and regulatory test protocol evolution are the twin forces actively restructuring how helmet manufacturers balance protective performance against connected functionality.
Micro-display projection systems for augmented reality navigation is miniaturizing from bulky external pods to integrated visor-embedded waveguides. Premium motorcycle touring segments in Germany and Austria are adopting these systems fastest, with early fleet trials now underway among European postal delivery services. This compression of optical hardware volume is enabling full-face helmet designs that retain ECE 22.06 impact certification without the aerodynamic penalties of earlier bolt-on display modules.
REACH substance restrictions on persistent organic pollutants are forcing foam liner reformulations across European supply chains, with manufacturers substituting traditional polyurethane chemistries for bio-based alternatives. The industrial consequence is extended material qualification timelines as new compounds undergo accelerated aging tests. Modular helmet configurations with removable comfort liners face the steepest compliance burden, driving consolidation toward integrated shell designs.
Food delivery platform procurement departments now specify connected helmet requirements in rider equipment tenders, displacing individual rider purchase decisions with centralized fleet standardization. Traditional motorcycle accessory retailers in Mumbai, São Paulo, and Jakarta report declining premium helmet sales as platform-mediated bulk contracts capture volume. This channel shift concentrates buyer power among four to six global delivery aggregators, compressing manufacturer margin structures and accelerating private-label sourcing arrangements.
Automotive Smart Helmet Market Segmentation
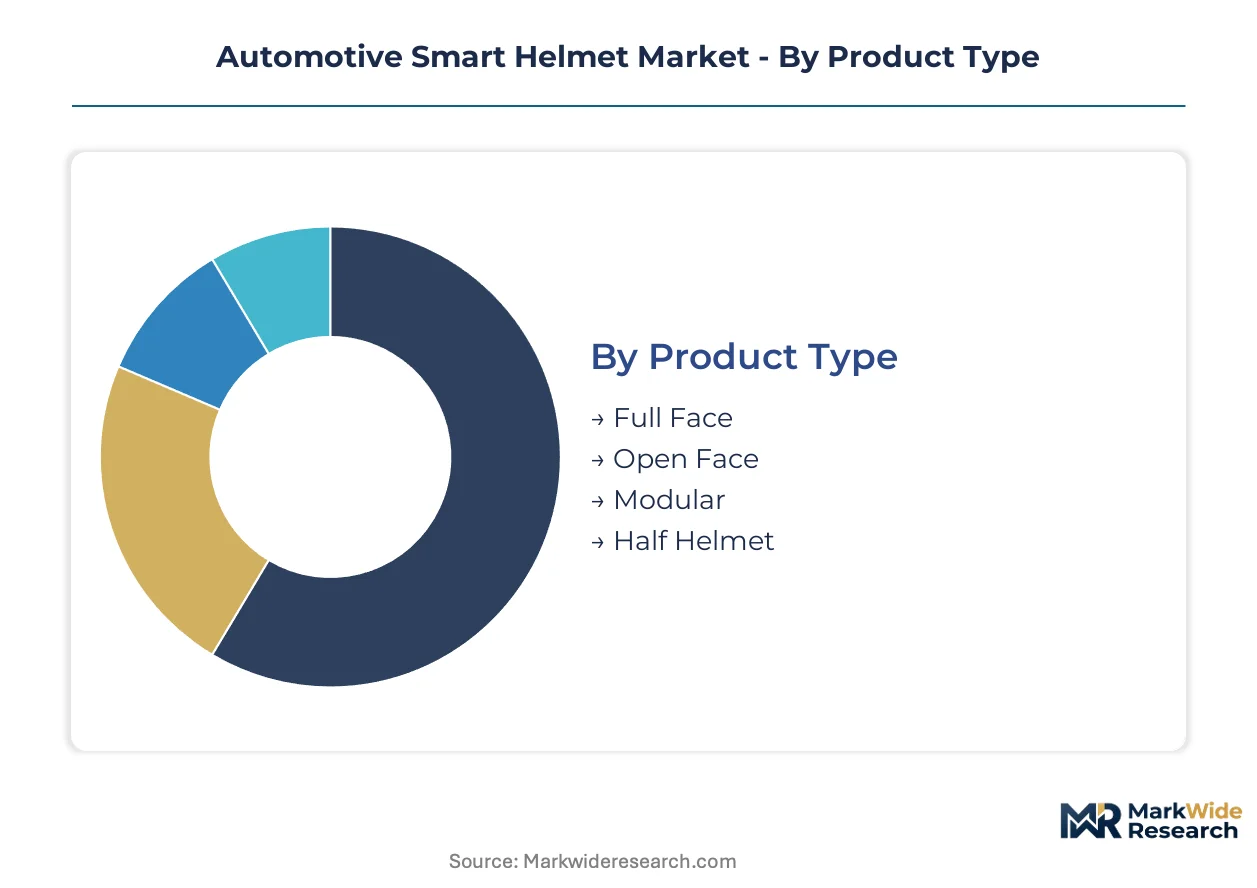
Segmentation in the Automotive Smart Helmet Market reveals how electronics packaging constraints, impact certification requirements, and fleet procurement standardization reshape competitive positioning across product tiers. Margin distribution follows helmet architecture complexity and sensor integration density rather than raw material costs alone.
Product Type:
Premium margin pools concentrate in configurations that balance electronics housing volume with aerodynamic stability for optical projection systems.
- Full Face:Enclosed shell architecture provides maximum interior volume for battery packs, antenna arrays, and micro-display projection hardware. Delivery fleet operators in India specify full-face designs for superior crash protection combined with integrated GPS tracking modules.
- Modular:Flip-up chin bar mechanisms accommodate communication device mounting while preserving ECE 22.06 certification integrity. German touring motorcyclists drive demand for modular systems with built-in Bluetooth intercom and retractable sun visor electronics.
- Open Face:Reduced shell coverage limits sensor mounting locations to brow and temple zones. Urban commuters in São Paulo favor open-face designs for ventilation in tropical climates despite restricted smart feature integration.
- Half Helmet:Minimal surface area permits only basic Bluetooth earpiece compatibility. Regulatory exclusion from ECE 22.06 rotational impact testing confines half-helmet smart variants to aftermarket accessory markets.
The dominant share belongs to Full Face, while Modular is closing the gap fastest.
Technology:
Technology tiering separates daylight-readable optical systems from basic connectivity modules on cost and certification complexity.
- Augmented Reality:Waveguide optics embedded in visor planes project navigation overlays without obstructing road view. Micro-display luminance advances from Taiwanese fabrication facilities enable AR adoption in Austrian premium motorcycle touring segments.
- Bluetooth:Short-range wireless protocols enable rider-to-rider communication and smartphone pairing for music streaming. Food delivery platforms in Maharashtra mandate Bluetooth-enabled helmets for real-time rider tracking and dispatch coordination.
- Heads-Up Display:Compact projection modules mount externally above the visor line, creating aerodynamic drag penalties. Early fleet trials among European postal services test HUD durability against daily vibration exposure.
- Voice Recognition:Noise-canceling microphone arrays process commands without handlebar button interaction. Highway wind noise above 80 km/h degrades recognition accuracy, limiting voice control to urban riding contexts.
Bluetooth maintains volume leadership, though Augmented Reality commands the steepest expansion trajectory.
End User:
End-user segmentation tracks the shift from individual retail purchase to centralized fleet procurement with standardized connectivity specifications.
- Delivery Riders:Platform-mediated employment concentrates buying power among four to six global aggregators. Swiggy and Zomato equipment tenders in Karnataka now specify connected helmet requirements displacing individual rider choice.
- Motorcyclists:Private ownership sustains premium pricing for integrated navigation and biometric monitoring features. German riders prioritize ECE 22.06-certified modular designs with factory-installed communication systems.
- Professional Racers:Telemetry integration demands for lean angle sensors and lap timing hardware create specialized development contracts. MotoGP team suppliers drive miniaturization requirements that cascade to consumer product lines.
- Leisure Riders:Weekend usage patterns prioritize comfort liners and ventilation over persistent connectivity. Traditional accessory retailers in Jakarta report declining leisure segment sales as fleet contracts capture manufacturing capacity.
Delivery Riders capture the dominant procurement volume, while Professional Racers push technical specification boundaries fastest.
Material:
Material selection balances impact energy absorption against electromagnetic transparency for antenna performance.
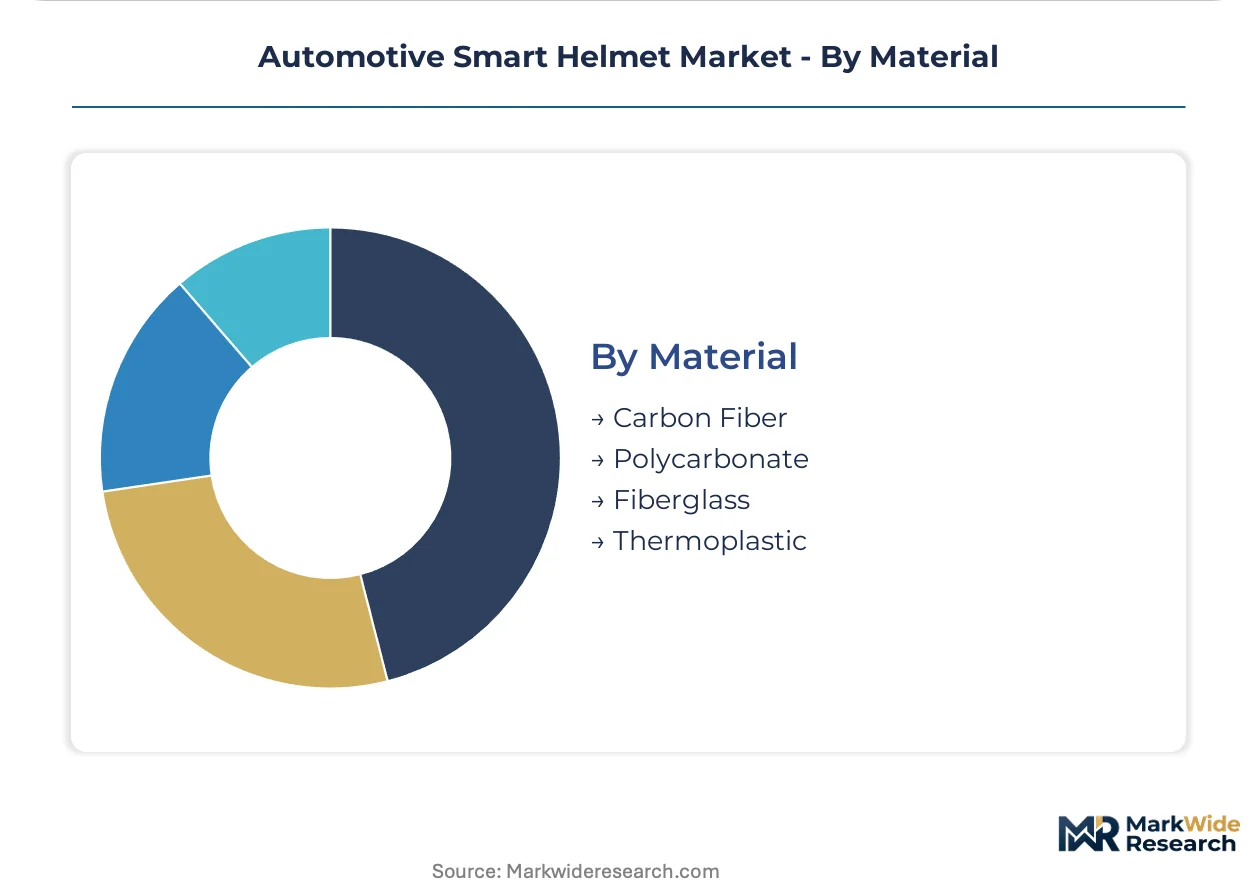
- Carbon Fiber:High stiffness-to-weight ratio enables thinner shell walls, expanding interior space for electronics packaging. REACH substance restrictions on persistent organic pollutants force foam liner reformulations in European carbon fiber helmet supply chains.
- Polycarbonate:Injection molding scalability supports high-volume fleet contract production with consistent shell thickness. Indian manufacturers leverage polycarbonate cost structures for BIS-certified connected helmet programs.
- Fiberglass:Intermediate cost positioning suits mid-tier modular configurations with moderate sensor integration. Italian helmet assemblers source fiberglass preforms from established automotive composite suppliers.
- Thermoplastic:Recyclability and impact resilience appeal to rental fleet operators with high helmet turnover rates. Brazilian urban mobility programs specify thermoplastic shells for shared electric motorcycle deployments.
Polycarbonate dominates unit economics, while Carbon Fiber gains share fastest in premium optical integration segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys smart helmets predominantly for delivery fleet compliance, whereas Germany and the United States prioritize premium touring configurations with integrated optics. This consumption-mix differential fragments regional product roadmaps and certification priorities.
India
Last-mile logistics platforms Swiggy and Zomato mandate Bluetooth-enabled helmets with GPS tracking for rider accountability across Karnataka and Maharashtra. BIS certification requirements and state-level mandatory helmet laws create dual regulatory pressure for connected safety equipment. Manufacturing concentrates in Pune and Chennai, where polycarbonate shell assemblers serve high-volume fleet contracts.
Germany
Premium motorcycle touring segments drive demand for ECE 22.06-certified modular systems with factory-installed communication modules. KBA homologation protocols enforce rotational impact testing that extends certification cycles. Industrial activity clusters in Bavaria and Baden-Württemberg, where Schuberth GmbH maintains in-house acoustic testing facilities for helmet audio integration.
United States
DOT certification requirements and NHTSA safety protocols shape baseline compliance for heads-up display integration in premium motorcycle segments. FCC radio equipment authorization governs Bluetooth and cellular connectivity module deployment. Development activity concentrates in California and the Pacific Northwest, where micro-display hardware startups partner with established helmet brands.
Japan
Professional racing telemetry demands from MotoGP suppliers cascade miniaturization requirements to consumer product lines. METI industrial standards and JIS certification frameworks govern protective equipment performance specifications. Manufacturing gravity sits in the Kansai region around Osaka, where precision electronics suppliers serve integrated helmet system assemblers.
Brazil
Urban mobility programs specify thermoplastic shells for shared electric motorcycle deployments with basic connectivity modules. ANVISA medical device regulations intersect with protective equipment standards for biometric monitoring integration. Fleet trials concentrate in São Paulo, where delivery platform iFood tests connected helmet specifications for rider safety compliance.
Automotive Smart Helmet Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with premium German engineering houses commanding modular system margins while Asian manufacturers compete on Bluetooth accessibility and fleet contract scale. The competitive structure rewards ECE 22.06 certification expertise and in-house electronics integration capability. Three archetypes dominate: heritage helmet brands with acoustic testing infrastructure, electronics-first entrants with aggressive connectivity pricing, and venture-backed HUD specialists pursuing augmented reality miniaturization. Capacity expansion and direct-to-fleet sales channel development represent the dominant competitive moves.
Among heritage European fabricators, Schuberth GmbH and HJC Europe SARL exemplify the integrated engineering archetype with established homologation expertise. Electronics-first specialists include Livall and Sena Technologies Inc., which occupy positions emphasizing wireless protocol integration and price-accessible connected features. Forcite Helmet Systems Pty Ltd. represents the venture-augmented tier pursuing optical projection miniaturization for premium motorcycle segments.
| Leading Market Players |
|---|
| HJC Europe SARL |
| Livall |
| Sena Technologies Inc. |
| Schuberth GmbH |
| Jarvish |
| Forcite Helmet Systems Pty Ltd. |
| Bell Helmets |
| Arai Helmet Europe BV |
| CrossHelmet Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day waveguide inventory cycles at Taiwanese micro-display foundries simultaneously constrain helmet OEM output schedules and inflate component premiums for non-contract buyers. This lead-time compression concentrates pricing power with optical suppliers while forcing assemblers into long-term offtake commitments to secure allocation.
Pricing Analysis
Long-term offtake agreements dominate procurement between major helmet manufacturers and Taiwanese waveguide suppliers, locking in volume commitments against spot-market volatility. Three-tier pricing structure across premium, standard, and economy levels separates ECE 22.06-certified modular systems with integrated AR optics from basic Bluetooth-enabled polycarbonate shells. Cost compression in the fleet-contract tier is intensifying because delivery platform procurement departments now consolidate buying power across four to six global aggregators. Individual motorcyclists in Germany and Austria exhibit lowest price sensitivity, prioritizing factory-installed communication systems and KBA homologation integrity over unit cost.
Supply Chain Analysis
Container availability constraints on the Kaohsiung-Rotterdam trade lane periodically disrupt inbound logistics for European helmet assemblers dependent on Asian electronics. Waveguide optics fabrication concentrates in Taiwan and South Korea, while polycarbonate shell molding clusters in India and China, creating geographic dispersion that complicates just-in-time coordination. Raw material dependencies span lithium-ion cells for battery modules, photopolymer resins for visor waveguides, and carbon fiber preforms for premium shell reinforcement. Single-source vulnerability in micro-display luminance components exposes helmet manufacturers to allocation rationing during semiconductor cycle upturns. Distribution runs through direct-to-fleet B2B platforms for delivery operator contracts, bypassing traditional motorcycle accessory retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as ECE 22.06 enforcement across European markets triggers replacement demand for legacy helmet inventory. Fleet operator mandates for connected safety equipment provide the cyclical impetus.
For Market Incumbents: Consolidate certification expertise into defensible moats by accelerating in-house acoustic testing infrastructure investments and securing captive supply agreements for waveguide components. Schuberth GmbH's Bavaria-based testing facilities exemplify how integrated engineering capabilities resist price erosion from Asian Bluetooth specialists. Priority lever: backward integration into micro-display sourcing through equity partnerships with Taiwanese fabrication facilities. For New Entrants and Emerging Players: Biometric monitoring integration for solo rider emergency dispatch represents the most penetrable service layer where incumbents under-serve, particularly in Maharashtra and Karnataka where state mandates create regulatory tailwinds. Target direct-to-fleet sales channels through procurement platform partnerships rather than contesting established retail networks. White-space opportunity: voice recognition systems optimized for Indian urban traffic noise profiles. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because helmet certification expertise compounds over multiple ECE revision cycles while electronics refresh rates accelerate. Acquisition target archetype: mid-tier modular specialists with existing KBA homologation pipelines but underutilized capacity. Signal to watch: harmonization progress between UN 38.3 battery transport regulations and ECE 22.06 rotational impact protocols as inflection indicator for software-defined helmet architectures.| Strategic Initiative | Industry Significance |
|---|---|
| ECE 22.06 Certification Acceleration | Extends product launch windows against electronics refresh cycles while locking out uncertified competitors from European fleet tenders. |
| Direct-to-Fleet Platform Partnership | Bypasses traditional dealership networks for Swiggy and Zomato procurement contracts in Karnataka and Maharashtra. |
| Waveguide Supplier Equity Stake | Secures allocation priority at Taiwanese micro-display foundries during semiconductor supply constraints. |
| Biometric Sensor Integration | Enables emergency service dispatch automation for solo riders through photoplethysmography crash-detection algorithms. |
| Polycarbonate Capacity Expansion | Serves high-volume BIS-certified connected helmet programs for Indian last-mile logistics platforms. |
Methodological Framework
Initial hypotheses were tested against primary input from helmet platform engineers, fleet procurement managers at delivery aggregators, regulatory affairs specialists at KBA and BIS, and aftermarket distribution channel heads, then refined against secondary validation. Primary fieldwork combined structured interviews with OEM product development executives and procurement leads at polycarbonate shell molders in Pune and Chennai. Secondary sources encompassed ECE 22.06 technical documentation, BIS certification registries, FCC radio equipment authorization filings, and customs records for waveguide optical component trade flows. Bottom-up unit economics from fleet contract tenders were triangulated against top-down market sizing from vehicle registration databases.
Variance decomposition across the projection horizon isolates volume drivers by helmet architecture, technology tier, and end-user procurement mode. Segmentation dimensions modeled include product type, connectivity protocol, optical integration level, material grade, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles overlaid with fleet penetration curves. Industry-specific forecast inputs span ECE 22.06 homologation timeline extensions and micro-display luminance specification advances from Taiwanese fabrication facilities.
Material uncertainties — lithium-ion thermal runaway incidents triggering stricter UN 38.3 enforcement, waveguide supply concentration disruptions, or smartphone navigation substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about fleet operator mandate expansion rates and ECE regulatory harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Start-Stop System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
ABS Sensors Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automotive ABS and ESC Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Asia-Pacific Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Automotive Seat Belt System Market
Automotive Safety and Security Systems
Automotive Active Safety Sensors Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Motorcycle E-Call Market