
 Corporate Social Responsibility (CSR) Software Market | 2026-2036
Corporate Social Responsibility (CSR) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Social Responsibility (CSR) Software Market Analysis
North American SaaS development capacity is rebalancing toward ESG-native architectures as investor pressure intensifies. Benevity leverages its grant management specialization to anchor nonprofit-corporate partnership workflows. EcoVadis sustains its supplier sustainability ratings dominance across European manufacturing supply chains. Workiva competes through integrated financial and non-financial reporting platforms that streamline SEC and CSRD alignment.
Corporate social responsibility software comprises modular digital platforms that collect, analyze, and disclose environmental, social, and governance performance data against standardized frameworks such as GRI, SASB, or TCFD. These systems automate carbon accounting, diversity metrics tracking, and stakeholder communication to satisfy board oversight and external audit requirements. Cloud-based deployment leads the architecture mix due to scalability demands from distributed enterprise operations, while compliance management software captures concentrated margin pools as regulatory complexity deepens. Reporting platforms represent the fastest-expanding category as mandatory disclosure regimes proliferate across jurisdictions.
The U.S. SEC climate disclosure rules and the EU CSRD framework are reshaping software procurement priorities by mandating machine-readable sustainability data and third-party assurance. ISO 26000 guidance and the EU AI Act intersect with CSR platforms where automated impact scoring requires algorithmic transparency. Stakeholders must monitor how fragmented national ESG standards converge or diverge to determine platform localization investments.
Market Dynamics
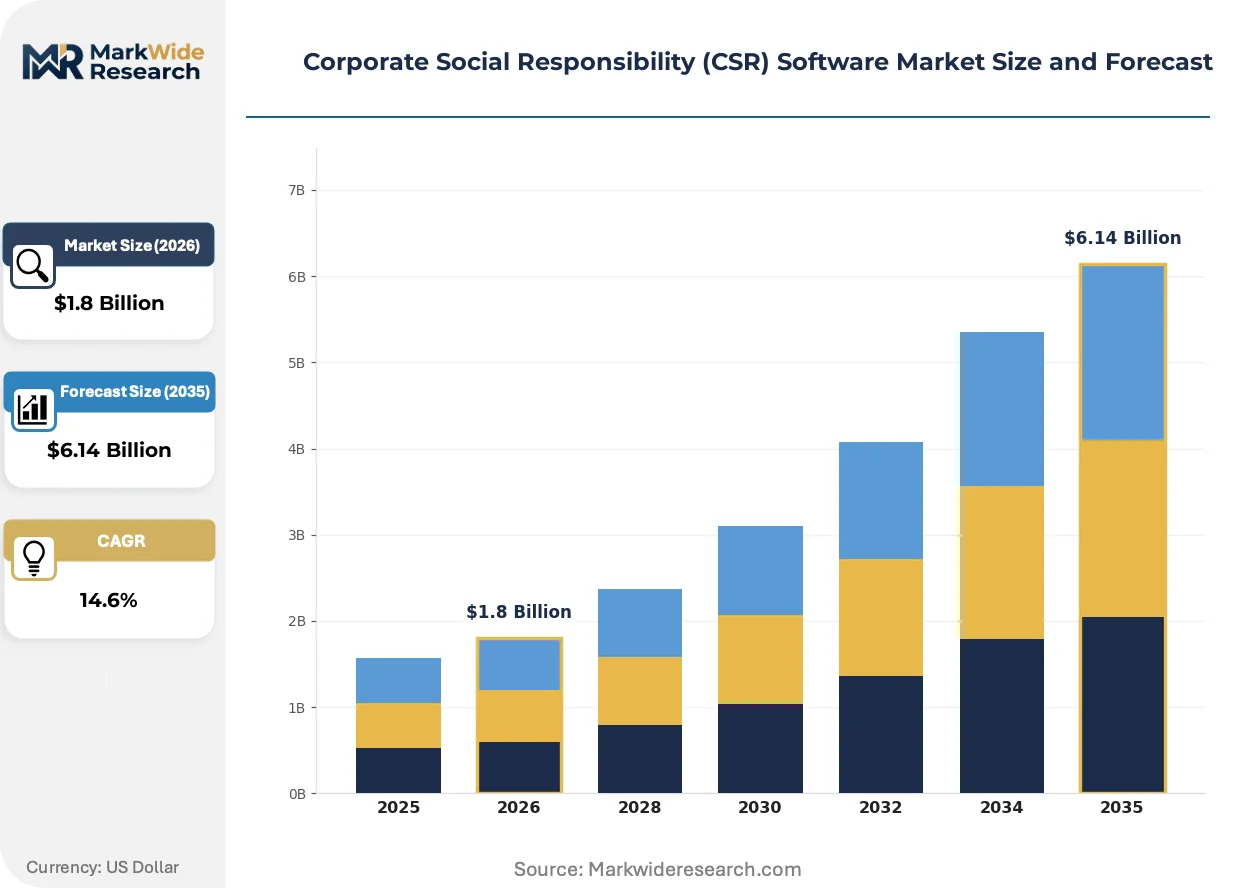
The Corporate Social Responsibility (CSR) Software Market is being fundamentally restructured by mandatory ESG disclosure regimes that demand machine-readable sustainability data and third-party assurance, forcing platform vendors to rebuild architectures around audit-grade data lineage and regulatory interoperability.
Growth Catalysts
- EU CSRD Mandate:The Corporate Sustainability Reporting Directive requires nearly 50,000 companies to produce assured sustainability reports, creating immediate procurement demand for integrated disclosure platforms.
- Financial Services ESG Workflows:Asset managers and insurers face SEC climate disclosure rules and EU Taxonomy alignment pressures, driving adoption of automated carbon accounting and portfolio-level impact scoring tools.
- Germany's Industrial Digitization:German industrial conglomerates are consolidating compliance processes onto cloud-native platforms to satisfy supply chain due diligence requirements under the Supply Chain Due Diligence Act.
Market Restraints
- Data Integration Complexity:Legacy ERP systems and disparate sustainability data sources require expensive middleware development, elevating total cost of ownership for mid-market buyers.
- Fragmented Standard Landscape:Competing frameworks including GRI, SASB, TCFD, and ISSB create regulatory friction as platforms must maintain parallel reporting templates for multinational clients.
- Assurance Provider Bottleneck:
Strategic Opportunities
- CSRD-Aligned SME Tier:Small and medium enterprises in Spain and Italy face phased CSRD applicability, creating whitespace for scaled-down disclosure platforms with pre-configured sector templates.
- AI-Act Intersection:Automated impact scoring modules that satisfy EU AI Act algorithmic transparency requirements represent a technology convergence opening for ESG-native vendors.
- Scope 3 Supply Chain Extension:Tier-n supplier engagement tools that cascade reporting requirements downstream unlock new revenue pools in manufacturing supply chains.
Industry Challenges
- Sustainability Data Engineering Talent:The scarcity of professionals combining domain expertise in carbon accounting with software engineering capabilities constrains platform development velocity.
- Multi-Framework Certification Timelines:Achieving recognized assurance readiness against both ISSB and CSRD technical standards extends product certification cycles and diverts R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Social Responsibility (CSR) Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Measurement Tools, Reporting Platforms, Stakeholder Engagement Solutions, Compliance Management Software End User: Corporations, Nonprofits, Educational Institutions, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Mobile Applications Application: Environmental Sustainability, Social Impact Assessment, Community Engagement, Corporate Governance |
| Companies Covered | iPoint, Selflessly, Benevity, Workiva, CSRconnect, EcoVadis, onHand, Sweep, WeSpire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Social Responsibility (CSR) Software Market Emerging Trajectories
Artificial intelligence and blockchain architectures are actively rewiring how CSR platforms validate and transmit sustainability claims, compressing the gap between data collection and audit-ready disclosure.
Embedded carbon accounting engines are converging with enterprise resource planning systems to enable real-time emissions tracking at the transaction level. Manufacturing firms with complex Scope 3 exposure are adopting these modules fastest, replacing annual spreadsheet-based inventories with continuous monitoring. This convergence is collapsing the traditional separation between operational and sustainability data systems.
The EU AI Act's risk classification framework is reshaping how automated ESG scoring algorithms are designed and documented. Platform vendors must now maintain technical documentation and human oversight protocols for high-risk AI applications in credit and insurance underwriting. Financial services procurement teams in France and Germany are prioritizing vendors with pre-certified algorithmic transparency controls.
Buy-side consolidation among institutional investors is compressing vendor selection cycles and elevating platform interoperability demands. Asset managers are unbundling point solutions in favor of integrated suites that feed directly into portfolio analytics systems. This behavioral shift is most visible in the Netherlands and Scandinavia, where pension funds have centralized ESG data procurement at the fund-of-funds level.
Corporate Social Responsibility (CSR) Software Market Segmentation
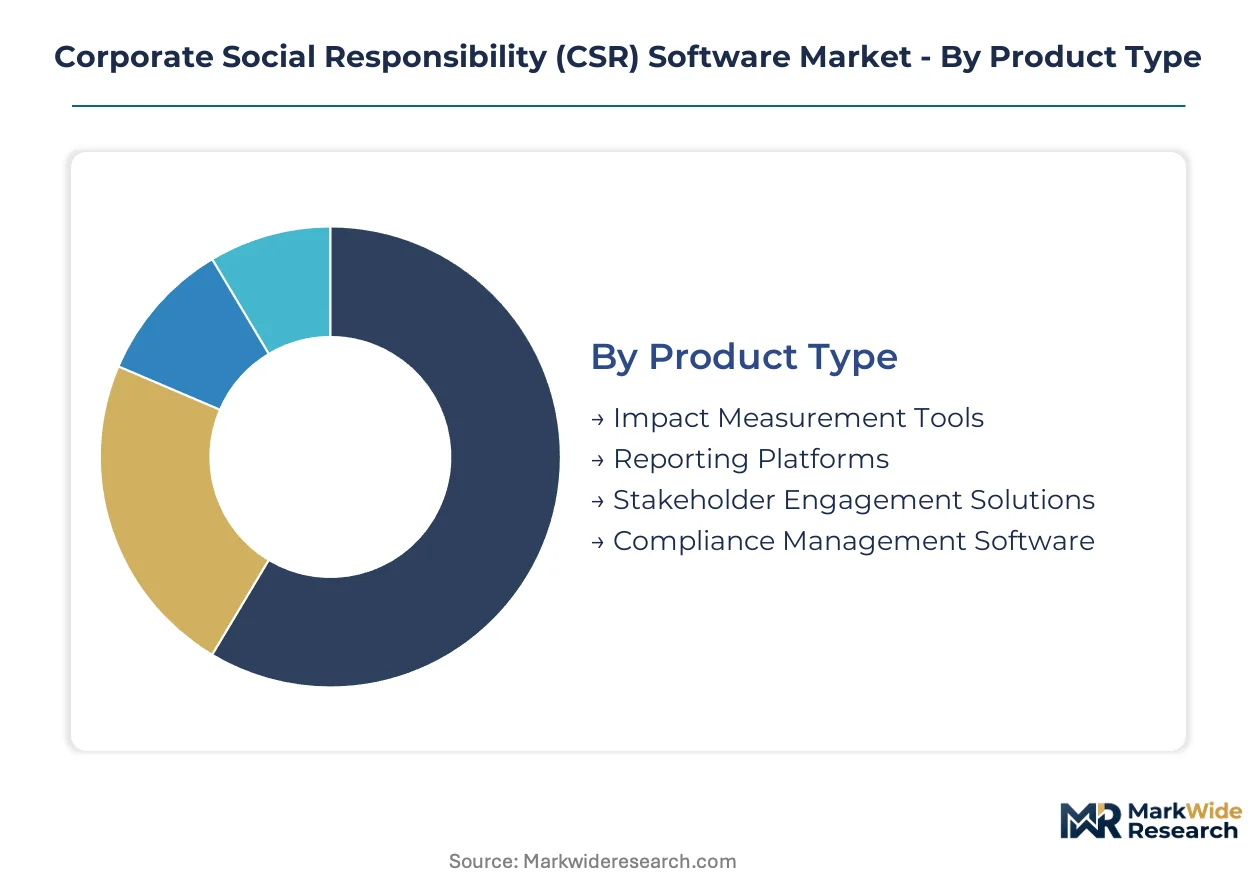
CSR software segmentation reveals how vendor specialization aligns with divergent compliance pressures and data maturity levels across buyer organizations. Procurement patterns concentrate where regulatory mandates intersect with internal reporting sophistication.
Product Type:
Supply concentration in this category tilts toward audit-grade infrastructure as disclosure mandates harden data lineage requirements.
- Impact Measurement Tools:These modules quantify carbon emissions, diversity metrics, and community outcomes through automated data ingestion from ERP and HR systems. Manufacturing conglomerates in Germany deploy these tools to satisfy Supply Chain Due Diligence Act calculations for Scope 3 liability.
- Reporting Platforms:Integrated disclosure engines generate machine-readable sustainability reports aligned with CSRD, GRI, and ISSB technical standards. Asset managers in the Netherlands prioritize these platforms to feed portfolio analytics systems with assured ESG data.
- Stakeholder Engagement Solutions:Survey and communication portals capture employee sentiment, community feedback, and investor queries for integrated materiality assessments.
- Compliance Management Software:Workflow engines track regulatory deadlines, evidence repositories, and assurance provider coordination across jurisdictions.
Reporting Platforms absorb the bulk of installed capacity; Compliance Management Software is expanding most quickly.
End User:
Cost tier stratification separates enterprise-grade deployments from scaled configurations serving resource-constrained organizations.
- Corporations:Multinational enterprises operate integrated CSR suites connecting subsidiary data to consolidated disclosure. Industrial conglomerates digitize compliance processes under CSRD and SEC climate rules, driving premium platform procurement.
- Nonprofits:Grant-dependent organizations leverage modular tools for donor reporting and outcome verification. Benevity's partnership workflows dominate this tier through specialized nonprofit-corporate collaboration features.
- Educational Institutions:Universities track campus emissions, research ethics compliance, and endowment ESG alignment through lightweight cloud deployments.
- Government Agencies:Public sector buyers emphasize procurement transparency and supplier sustainability scoring under national green public procurement policies.
Corporations command the dominant share of vendor revenue; Educational Institutions are climbing the fastest as endowment ESG mandates proliferate.
Deployment:
Volume concentration favors architectures that balance scalability with data sovereignty constraints across multinational footprints.
- Cloud-Based:SaaS architectures dominate enterprise procurement due to distributed operations requiring real-time collaboration across facilities. European manufacturing supply chains rely on these deployments for EcoVadis supplier rating integration.
- On-Premises:Air-gapped installations persist in defense contractors and critical infrastructure operators facing national security data localization requirements.
- Hybrid Solutions:Split configurations process sensitive personnel data locally while pushing anonymized metrics to cloud analytics engines.
- Mobile Applications:Field audit and stakeholder survey tools extend platform reach to supply chain auditors and community liaisons without desktop access.
Cloud-Based deployments carry the majority of new installations; Hybrid Solutions are gaining share fastest among regulated financial services firms.
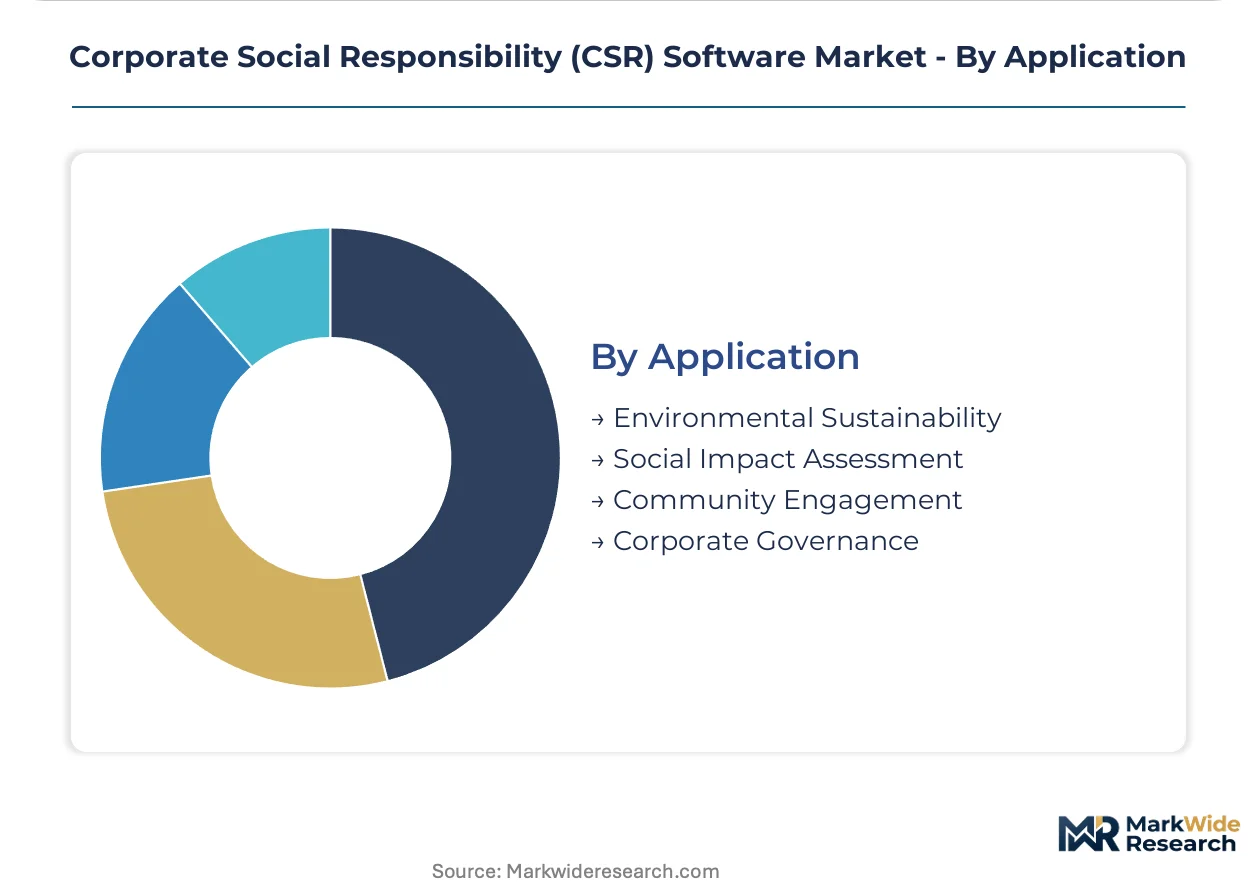
Application:
Customer type differentiation separates buyers prioritizing operational carbon reduction from those emphasizing governance and social license.
- Environmental Sustainability:Carbon accounting, energy management, and circular economy tracking modules attract industrial buyers facing EU Taxonomy alignment pressure. Embedded engines converging with ERP systems enable transaction-level emissions monitoring.
- Corporate Governance:Board oversight tools, ethics hotlines, and anti-corruption monitoring satisfy audit committee requirements under SEC and CSRD governance disclosures.
- Social Impact Assessment:Human rights due diligence and diversity analytics serve apparel and electronics manufacturers exposed to supply chain labor scrutiny.
- Community Engagement:Volunteer management, local procurement tracking, and philanthropy administration support reputation-sensitive consumer brands.
Environmental Sustainability holds the largest functional deployment base; Corporate Governance is expanding most rapidly as governance disclosures harden across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center capacity in Northern Virginia anchors SaaS infrastructure for CSR platform delivery across North American financial services clusters.
United States
Asset managers in New York and Boston face SEC climate disclosure rules requiring machine-readable sustainability data. The SEC mandates third-party assurance for Scope 1 and 2 emissions disclosures. Chicago-based industrial conglomerates deploy carbon accounting modules to satisfy emerging state-level climate accountability statutes.
Germany
Industrial manufacturers in Stuttgart and Munich digitize compliance processes under the Supply Chain Due Diligence Act. The EU CSRD directive requires nearly 50,000 companies to produce assured sustainability reports. Frankfurt's financial services sector drives demand for integrated ESG disclosure platforms aligned with EU Taxonomy technical screening criteria.
United Kingdom
London-based insurers and pension funds procure automated portfolio impact scoring tools. The Financial Conduct Authority's sustainability disclosure requirements intersect with TCFD-aligned reporting obligations. Edinburgh's asset management cluster concentrates procurement of stakeholder engagement solutions for materiality assessments.
Netherlands
Pension funds in Amsterdam and Rotterdam centralize ESG data procurement at the fund-of-funds level. The Dutch Authority for Financial Markets enforces strict sustainability labeling requirements for investment products. Eindhoven's technology manufacturing base adopts supplier sustainability rating systems for EU Taxonomy alignment.
France
Paris-based asset managers prioritize vendors with pre-certified algorithmic transparency controls under the EU AI Act. The Autorité des Marchés Financiers mandates climate risk disclosures for institutional investors. Lyon's chemical and pharmaceutical clusters deploy environmental sustainability modules for circular economy tracking.
Corporate Social Responsibility (CSR) Software Market Vendor Landscape
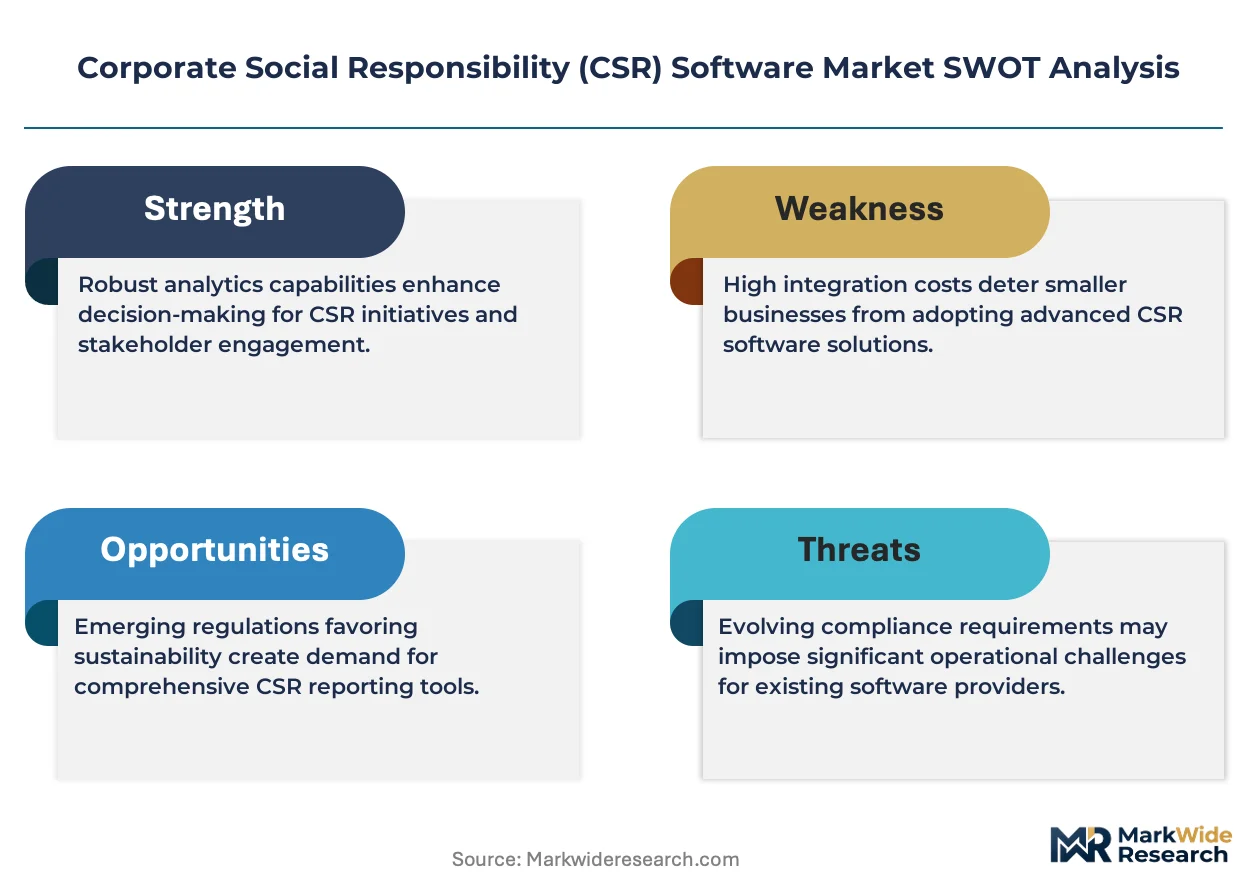
Global majors compete with regional champions across disclosure automation capabilities, with market structure tiering between integrated platform vendors and specialized point-solution providers. The vendor landscape segments into three strategic archetypes: ESG-native SaaS developers, legacy compliance software extenders, and nonprofit-corporate partnership specialists. M&A activity concentrates on carbon accounting engine acquisitions, while strategic partnerships dominate distribution channel expansion into mid-market segments.
Within the ESG-native tier, EcoVadis exemplifies supplier sustainability rating dominance across European manufacturing supply chains, while Workiva occupies a position anchoring integrated financial and non-financial reporting workflows. Benevity represents the nonprofit-corporate partnership specialization through grant management and volunteer coordination features. These three vendors collectively illustrate how geographic origin and functional focus determine competitive positioning in procurement cycles.
| Leading Market Players |
|---|
| iPoint |
| Selflessly |
| Benevity |
| Workiva |
| CSRconnect |
| EcoVadis |
| onHand |
| Sweep |
| WeSpire |
| Others |
Supply Flow & Price Mechanics
Asset manager consolidation in the Netherlands and Scandinavia is compressing vendor selection cycles and forcing platform vendors to unbundle implementation services from core SaaS subscriptions, compressing margins in the mid-market tier while elevating premium pricing for audit-grade configurations.
Pricing Analysis
Assurance-bundling separates premium-tier deployments from standard configurations in CSR software procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification readiness against CSRD and ISSB technical standards. Price differentiation rests on audit-grade data lineage capabilities and third-party assurance coordination workflows. Cost compression in the standard tier is intensifying because mid-market buyers resist implementation fees for middleware development. Educational institutions exhibit highest price sensitivity; asset managers in Frankfurt and Amsterdam demonstrate lowest sensitivity due to regulatory penalty exposure.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers in Ireland and Germany hosting EU data residency-compliant deployments. Software development capacity draws from India, Poland, and Portugal for engineering talent. Raw material dependencies center on proprietary carbon accounting engines, pre-certified algorithmic transparency modules, and API integration libraries. Supply chain risk stems from accreditation bottlenecks among sustainability assurance providers delaying audit timelines. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships in financial services clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSR software vendors are racing to deepen upstream control over carbon accounting engine development and downstream integration with portfolio analytics systems to capture margin pools that point-solution providers cannot access.
For Market Incumbents: Hedge against open-source carbon accounting frameworks by acquiring specialized Scope 3 calculation engine developers. Lock in assurance provider partnerships to preempt audit timeline compression that delays customer deployments. Expand certification investment against both ISSB and CSRD technical standards to maintain pricing power in procurement cycles. For New Entrants and Emerging Players: The price-point gap between premium audit-grade platforms and lightweight survey tools creates whitespace for mid-tier disclosure automation. Target phased CSRD applicability in Spanish and Italian SME manufacturing segments. Pursue white-label partnerships with regional systems integrators lacking native ESG capabilities. For Investors and Strategic Acquirers: The window for entry favors carbon accounting engine specialists with pre-built ERP connectors. Long-term viability hinges on regulatory interoperability rather than feature depth. Watch for convergence between EU AI Act algorithmic transparency requirements and automated ESG scoring modules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Carbon Accounting Engine | Captures Scope 3 calculation capabilities critical for German industrial compliance workflows. |
| Assurance Provider Partnership | Preempts audit timeline bottlenecks that compress software deployment schedules in EU markets. |
| CSRD-Aligned Certification Investment | Unlocks procurement eligibility among Frankfurt financial services firms facing EU Taxonomy alignment pressure. |
| API Integration with Portfolio Analytics | Feeds directly into Amsterdam pension fund centralized ESG data procurement systems. |
| AI Act Algorithmic Transparency Pre-Certification | Addresses Paris asset manager procurement priorities under EU AI Act risk classification framework. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with sustainability officers, ESG data managers, audit firm assurance leads, and IT procurement directors at asset management firms were combined with secondary validation from SEC climate disclosure filings, EU CSRD technical standard drafts, and EFRAG implementation guidance. Bottom-up deployment estimates and top-down market sizing were triangulated to constrain variance.
Reconciliation of vendor-reported bookings, customer procurement patterns, and regulatory mandate timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory adoption pattern. CAGRs were derived from slope analysis of disclosed platform revenue trajectories and procurement cycle compression indicators in financial services clusters.
Inputs from ESG software vendors and assurance providers were available through the study window; gaps in mid-market SME procurement intention data introduce uncertainty bands around penetration assumptions. Forecasts reflect documented assumptions regarding CSRD phase-in schedules and SEC rule durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Water Pipeline Leak Detection System Market
Environment & Sustainability
Industrial Waste Management Market
Environment & Sustainability
Recyclate PET Market
Environment & Sustainability
APAC Bio-Medical Waste Management Market
Environment & Sustainability
Global Water and Wastewater Treatment Equipment Market
Environment & Sustainability
Asia Pacific Air Quality Monitoring Market
Environment & Sustainability
Recycled Ocean Plastics Market
Environment & Sustainability
Construction and Demolition Waste Management Market
Environment & Sustainability
Green Roof Market
Environment & Sustainability
Automated Waste Collection System (AWCS) Market
Environment & Sustainability
Environment Testing Services Market
Environment & Sustainability
North America Green Buildings Market
Environment & Sustainability
Environmental Technology Market
Environment & Sustainability
Indoor Air Quality Service Market
Environment & Sustainability
Brazil Organic Dinnerware Market
Environment & Sustainability
China Cloud Seeding Market