
 Saudi Arabia Quick Service Restaurants Market | 2026-2036
Saudi Arabia Quick Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Quick Service Restaurants Market Insights
Plant-based protein alternatives are broadening menu economics beyond traditional chicken and beef formulations. ALBAIK Food Systems Company anchors its competitive position through proprietary spice blends and vertically controlled supply chains across the western province. McDonald's Corporation leverages standardized kitchen automation to sustain throughput during peak pilgrimage seasons. Yum! Brands differentiates via localized menu engineering that adapts global recipes to Saudi palates.
Quick service restaurants are foodservice establishments characterized by limited menus, standardized preparation protocols, and service completion times under five minutes, typically operating through centralized commissary kitchens that pre-portion ingredients to ensure consistency. Their primary commercial purpose is delivering convenient, repeatable meal experiences at price points accessible to mass-market consumers. Burgers and pizza categories dominate transaction volume due to family-oriented promotional bundling, while the drive-thru service model captures disproportionate morning and late-evening traffic from commuters and shift workers. Delivery segments are expanding fastest as third-party platform commissions reshape franchisee margin structures.
SFDA enforces Hazard Analysis Critical Control Point standards across all food preparation facilities, while municipal authorities in Riyadh, Jeddah, and Dammam operate separate licensing regimes that govern operating hours and location zoning. The Saudi Food and Drug Authority's escalating traceability requirements are forcing upstream supplier documentation upgrades. Franchise operators must monitor how forthcoming municipal sustainability mandates affect packaging specifications and waste disposal costs.
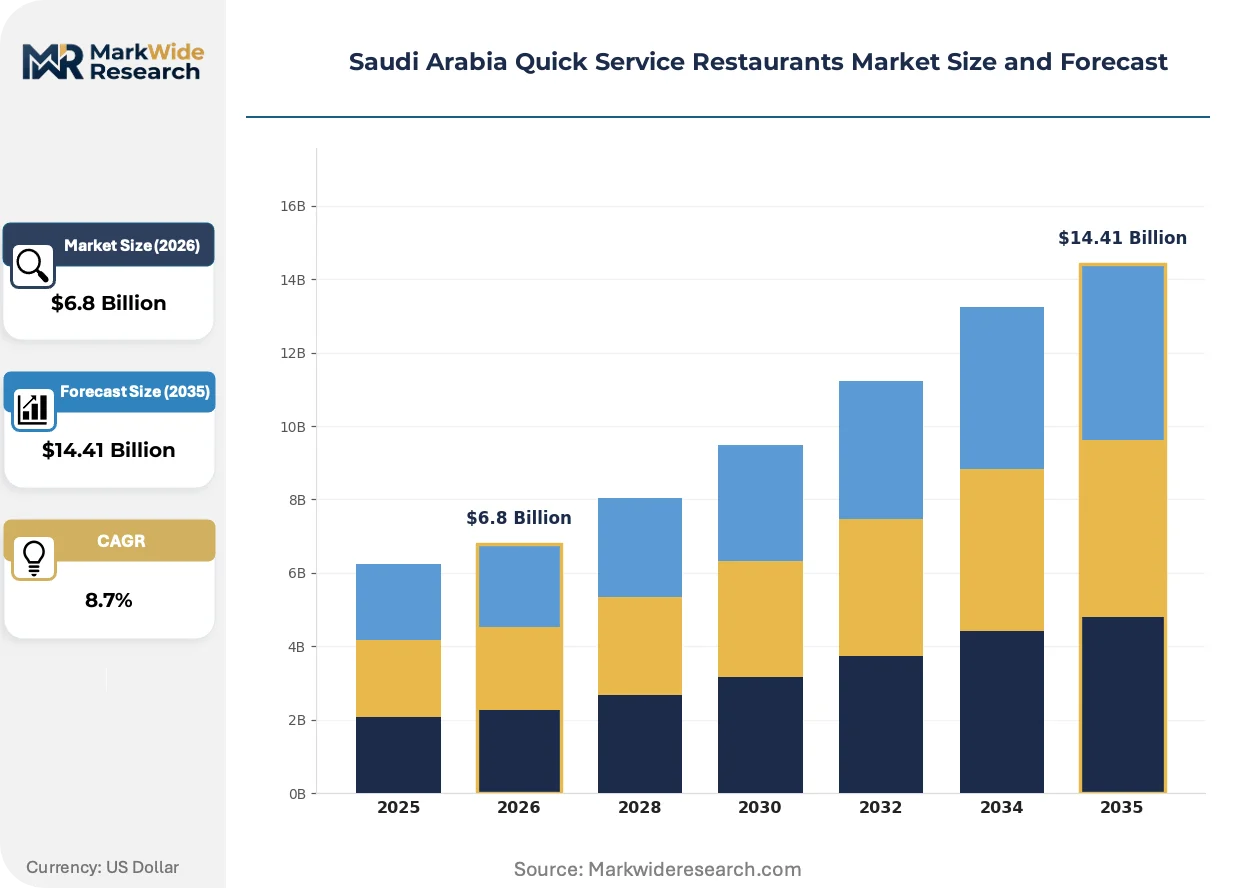
Market Dynamics
Digital ordering platforms are compressing customer acquisition timelines while SFDA traceability mandates force upstream documentation upgrades across Saudi Arabia's quick service restaurant supply chains.
Growth Catalysts
- SFDA HACCP enforcement:Standardized food safety protocols reduce contamination incidents and build consumer trust in chain establishments.
- Young adult demographic expansion:Smartphone-native consumers drive app-based ordering penetration in Riyadh and Jeddah metropolitan corridors.
- Highway drive-thru clustering:Strategic positioning along major intercity routes captures commuter traffic and pilgrimage-season volume spikes.
Market Restraints
- Third-party platform commissions:Delivery aggregator fees compress franchisee margins and erode unit-level profitability.
- Western province supply concentration:Vertically controlled spice and poultry supply chains limit new entrant access to signature flavor profiles.
- Municipal licensing fragmentation:Separate operating-hour regimes across Riyadh, Jeddah, and Dammam create compliance complexity for multi-location operators.
Strategic Opportunities
- Plant-based menu expansion:Protein alternative formulations attract health-conscious segments beyond traditional chicken and beef loyalists.
- Mall food court premiumization:Entertainment-destination dining complexes in secondary cities offer underexploited real estate.
- Municipal sustainability mandates:Forthcoming packaging specifications and waste disposal rules favor early adopters of compostable materials.
Industry Challenges
- Kitchen automation integration:Standardized equipment retrofitting demands capital outlay and staff retraining during operational hours.
- Commissary kitchen talent pipeline:Shortage of HACCP-certified supervisors constrains multi-unit expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Quick Service Restaurants Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Pizza, Sandwiches, Salads Customer Type: Families, Young Adults, Professionals, Students Service Model: Dine-in, Takeaway, Drive-thru, Delivery Franchise Model: Single Unit, Multi-Unit, Master Franchise, Area Development |
| Companies Covered | Yum! Brands, Herfy, ALBAIK Food Systems Company, Dunkin', Kudu, McDonald's Corporation, Restaurant Brands International, Starbucks, Americana Restaurants International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Quick Service Restaurants Market Trends and Innovations
Automation and regulatory digitization are restructuring how Saudi quick service restaurants manage throughput, compliance documentation, and customer interface design.
Kitchen display systems with predictive prep algorithms are expanding into high-volume pilgrimage-season operations. Franchise operators in Makkah and Madinah corridors deploy these platforms to synchronize fryer cycles with prayer-time demand surges. Real-time inventory tracking is expanding into supplier coordination, reducing waste from perishable protein stocks.
SFDA's escalating traceability requirements mandate lot-level documentation from farm to fryer. Municipal health authorities in Riyadh now require digital submission of temperature logs and supplier certificates. Smaller independent operators face compliance cost burdens that favor consolidated chain networks with dedicated quality assurance staff.
Family-oriented promotional bundling is shifting toward subscription-based meal plans accessed through proprietary apps. Quick service chains in Jeddah's coastal districts pilot monthly burger-and-beverage packages to lock in recurring revenue. This model displaces transaction-by-transaction discounting that trained consumers to wait for periodic promotions.
Saudi Arabia Quick Service Restaurants Market Segmentation
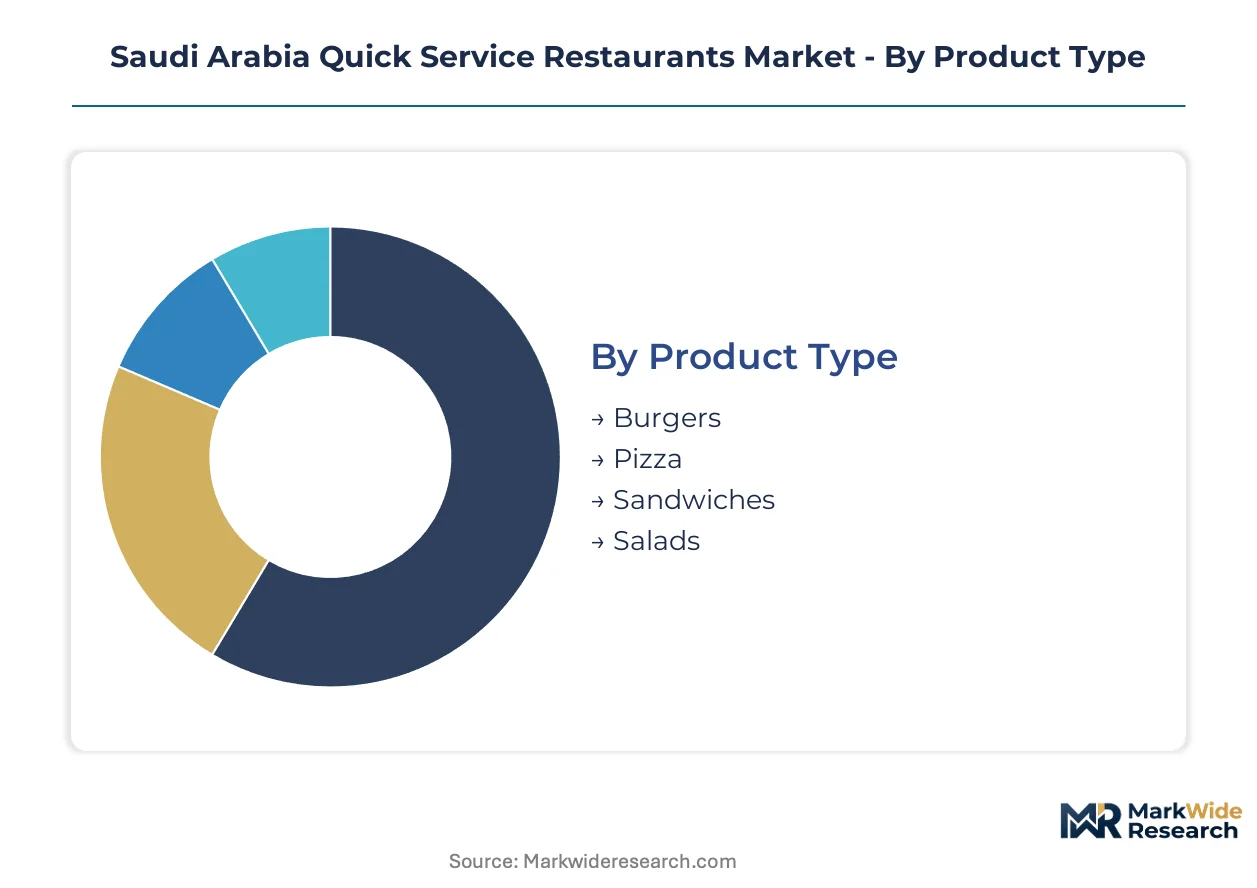
Segmentation in Saudi Arabia's quick service restaurant market reveals how consumption patterns split across protein formats, demographic cohorts, and service modalities. These divisions determine real estate selection, kitchen equipment specifications, and digital platform investments for operators targeting Riyadh and Jeddah corridors.
Product Type:
Standardization dominates burgers and pizza through frozen patty and dough supply chains, while salads retain higher customization variance in ingredient sourcing.
- Burgers:Frozen beef and chicken patty supply chains enable consistent portioning across highway drive-thru locations. Demand concentrates in family-oriented mall food courts where promotional bundling drives transaction volume during weekend peak periods.
- Pizza:Centralized dough production and standardized topping protocols support rapid throughput in pilgrimage-season operations. Riyadh's northern districts absorb disproportionate delivery volume from third-party platform users seeking late-evening convenience.
- Sandwiches:Wrap and flatbread formats adapt to localized spice preferences through regional commissary variations.
- Salads:Perishable supply chains and SFDA temperature logging requirements constrain menu breadth outside premium mall locations.
Leading the category by volume: Burgers. Growing fastest: Salads.
Customer Type:
Family units generate highest per-check averages through bundled meal purchases, while young adults drive frequency through app-based ordering platforms.
- Families:Multi-person meal combinations anchor promotional calendars during school holiday periods and religious observances. Jeddah's coastal entertainment districts capture concentrated weekend traffic from extended household dining occasions.
- Young Adults:Smartphone-native consumers exhibit highest delivery platform penetration and subscription plan adoption rates. Riyadh's university corridors and corporate zones generate recurring weekday lunch demand through proprietary app ordering.
- Professionals:Time-constrained weekday lunch occasions favor drive-thru speed and pre-order pickup functionality.
- Students:Price-sensitive demand clusters near educational institutions with heavy reliance on value-menu positioning and promotional discounting cycles.
Highest revenue per transaction: Families. Steepest expansion trajectory: Young Adults.
Service Model:
Capital intensity escalates from delivery-only ghost kitchens through full-service dine-in with dedicated parking infrastructure.
- Dine-in:Mall food court locations require premium rent structures and extended operating hour compliance with municipal licensing regimes. Makkah corridor operators synchronize seating capacity with prayer-time demand surges through kitchen display system coordination.
- Drive-thru:Highway-adjacent real estate commands highest development costs but captures commuter traffic and Umrah season volume spikes. Jeddah's ring road clusters demonstrate strongest throughput metrics during morning and late-evening dayparts.
- Takeaway:Counter-service formats minimize labor overhead in secondary city markets with lower real estate costs.
- Delivery:Third-party platform dependence erodes unit economics through commission structures, driving proprietary app development investments.
Widest geographic penetration: Takeaway. Fastest infrastructure expansion: Delivery.
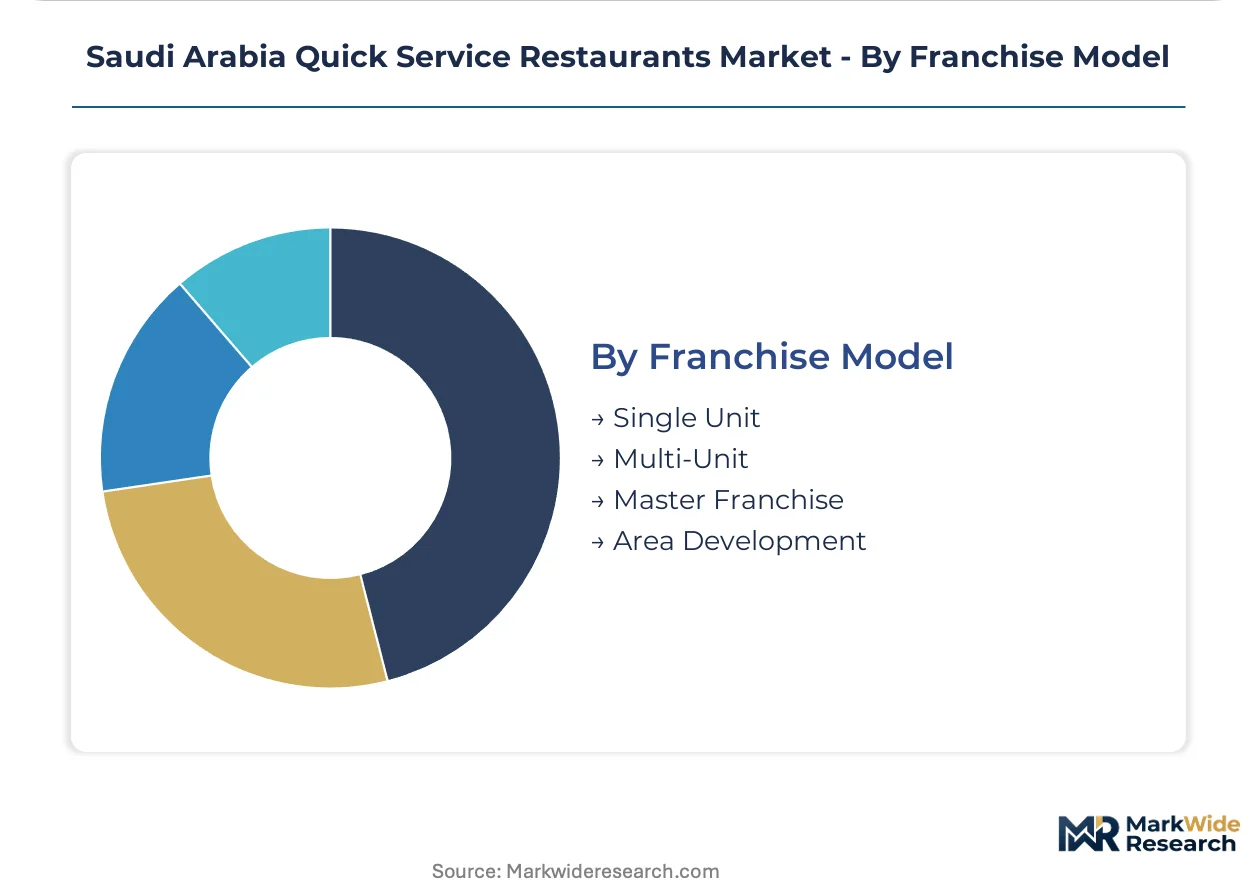
Franchise Model:
Capital commitment and operational control intensity vary from single-unit owner-operators through territory-exclusive master franchise arrangements.
- Multi-Unit:Portfolio operators achieve supply chain leverage and shared commissary infrastructure across Riyadh and Jeddah metro zones. SFDA HACCP certification investments amortize across location networks, accelerating expansion timelines relative to single-unit competitors.
- Master Franchise:Territory-exclusive agreements concentrate development risk with capitalized partners responsible for sub-franchise recruitment and training pipeline construction. Western province operators leverage existing poultry and spice supply relationships to secure favorable territory terms.
- Single Unit:Owner-operator models dominate secondary city entry strategies with localized menu adaptation flexibility.
- Area Development:Phased rollout commitments match capital deployment to demographic growth corridors in emerging urban zones.
Dominant transaction volume: Multi-Unit. Gaining share fastest: Master Franchise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters along three metropolitan corridors where mall food courts and highway drive-thru infrastructure absorb the majority of transaction volume. SFDA traceability mandates and municipal licensing fragmentation create divergent compliance burdens across these zones.
Riyadh
Corporate lunch demand and university corridor traffic drive proprietary app adoption among smartphone-native consumers. Municipal health authorities require digital submission of temperature logs and supplier certificates. Northern district delivery volume concentrates through third-party platforms serving late-evening convenience seekers.
Jeddah
Coastal entertainment districts capture concentrated weekend traffic from extended household dining occasions. Western province vertically controlled poultry and spice supply chains limit new entrant access to signature flavor profiles. Ring road drive-thru clusters demonstrate strongest throughput metrics during morning and late-evening dayparts.
Eastern Province
Industrial zone shift-worker populations generate recurring demand for drive-thru speed and pre-order pickup functionality. Dammam operates separate licensing regimes governing operating hours and location zoning relative to Riyadh and Jeddah. Dhahran corridor commissary kitchens serve as distribution nodes for multi-unit portfolio operators.
Makkah and Madinah Corridors
Pilgrimage-season volume spikes demand kitchen display systems that synchronize fryer cycles with prayer-time surges. SFDA HACCP enforcement standardizes food safety protocols across high-throughput operations. Mall food court locations in these corridors require extended operating hour compliance with municipal licensing regimes.
NEOM Northwest
Emerging urban zone development matches capital deployment to demographic growth corridors in secondary markets. Forthcoming municipal sustainability mandates affect packaging specifications and waste disposal costs for early entrants. Entertainment-destination dining complexes offer underexploited real estate for premium positioning.
Saudi Arabia Quick Service Restaurants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international franchise networks and domestic vertically integrated operators commanding distinct territorial advantages. The market structure consolidates around multi-unit portfolio operators that amortize SFDA certification investments across location networks. Three archetypes dominate: Western province supply-chain-integrated incumbents, global brand licensors with standardized automation protocols, and regional multi-unit aggregators. Competitive moves concentrate on proprietary app development to displace third-party platform dependence, and backward integration into commissary kitchen infrastructure to control perishable protein stocks.
Within the Western province supply-chain tier, ALBAIK Food Systems Company and Herfy exemplify vertically integrated positioning through captive poultry and spice procurement relationships. McDonald's Corporation anchors the global licensor archetype with standardized kitchen automation deployment. Yum! Brands occupies a position bridging international scale with localized menu engineering adaptation.
| Leading Market Players |
|---|
| Yum! Brands |
| Herfy |
| ALBAIK Food Systems Company |
| Dunkin' |
| Kudu |
| McDonald's Corporation |
| Restaurant Brands International |
| Starbucks |
| Americana Restaurants International |
| Others |
Pricing and Supply Chain Analysis
HACCP-certified kitchen supervisors concentrated in Riyadh and Jeddah corridors widen labor-cost differentials between premium mall locations and highway drive-thru clusters. SFDA compliance investments at the unit level feed into pricing-tier spreads that separate family-oriented bundled meals from value-menu positioning near educational institutions.
Pricing Analysis
Volume-driven highway drive-thru operations trade margin for throughput during pilgrimage-season spikes, while mall food court premiums capture family check averages through entertainment-destination positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by real estate cost absorption and after-sales service bundling through proprietary apps. Pricing pressure stems from third-party delivery platform commissions that compress franchisee unit economics. Students exhibit highest price sensitivity through value-menu dependence, whereas family segments show lowest sensitivity to bundled meal premiums.
Supply Chain Analysis
Regional distribution centers in Riyadh and Jeddah operate hub-and-spoke patterns feeding commissary kitchens across metropolitan corridors and secondary city markets. Saudi Arabia's poultry and spice procurement draws from domestic Western province vertical integration and imported protein stocks from Brazil and India. Frozen patty and dough supply chains hinge on cold-chain integrity risks from temperature excursion during desert transit. Distribution runs through centralized commissary networks that pre-portion ingredients for standardized preparation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
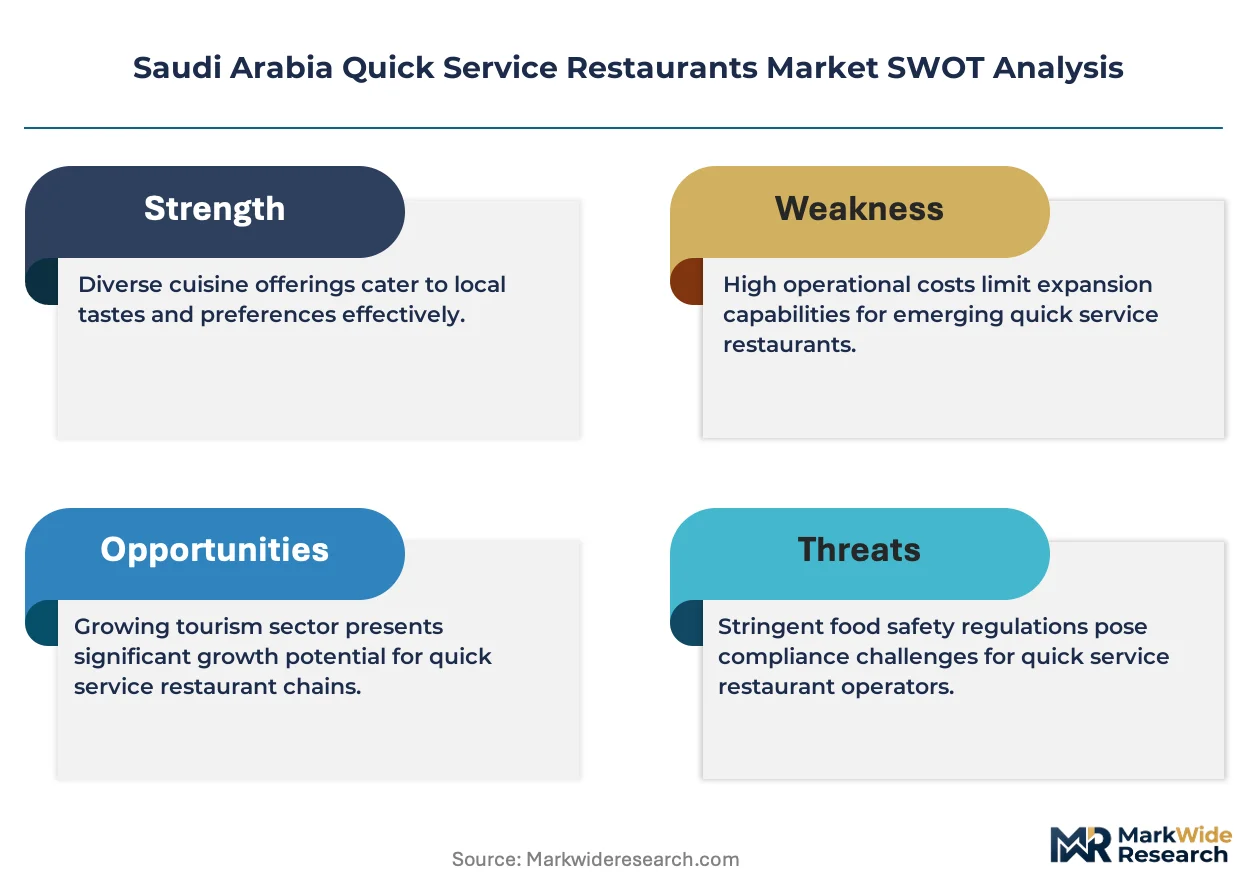
SFDA escalating traceability requirements function as a cost-of-compliance moat that favors multi-unit operators with dedicated quality assurance staff over independent entrants lacking documentation infrastructure.
For Market Incumbents: To counter third-party platform margin compression, deploy proprietary app subscription models that lock recurring revenue and displace transaction-by-transaction discounting. Backward integration into commissary kitchen infrastructure controls perishable protein stocks and reduces supplier coordination waste. For New Entrants and Emerging Players: Begin with secondary city mall food court premiumization in entertainment-destination dining complexes where real estate remains underexploited. Target young adult subscription plan adoption through smartphone-native app interfaces in Riyadh university corridors. For Investors and Strategic Acquirers: The window for entry favors multi-unit portfolio operators with existing SFDA HACCP certification investments that amortize across location networks. Monitor municipal sustainability mandate timing as inflection signal for packaging specification shifts favoring early compostable material adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary App Development | Reduces third-party platform dependence and protects franchisee margins from aggregator commission structures. |
| Commissary Kitchen Expansion | Enables HACCP-certified centralized production that satisfies SFDA traceability mandates across multi-unit networks. |
| Plant-Based Menu Engineering | Captures health-conscious young adult segments beyond traditional chicken and beef protein loyalists. |
| Highway Drive-Thru Clustering | Positions operations to capture commuter traffic and Umrah season volume spikes along major intercity routes. |
| Sustainability Certification Program | Anticipates forthcoming municipal packaging mandates and waste disposal rules favoring compostable material adopters. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with franchise operations directors, SFDA compliance officers, mall property managers, and third-party delivery platform executives. Saudi Food and Drug Authority guidance documents, municipal health licensing registries, and restaurant industry association membership databases provided validation layers. Bottom-up location-level transaction modeling and top-down metropolitan corridor demand aggregation were reconciled through iterative triangulation.
Data-stream reconciliation across proprietary app transaction logs, third-party platform commission disclosures, and commissary kitchen throughput metrics informed the analytical framework. Segmentation dimensions spanned protein format, customer demographic cohort, service modality, and franchise capital structure across the projection horizon. CAGRs were derived from demographic growth trajectories, digital ordering platform penetration curves, and pilgrimage-season volume elasticity estimates. Forecast inputs incorporated SFDA regulatory implementation timelines and municipal licensing regime fragmentation patterns.
Underlying measurement precision varies by segment; Riyadh and Jeddah metropolitan corridors carry tighter precision than emerging NEOM Northwest development zones due to data availability differentials. Forecasts reflect documented assumptions regarding young adult smartphone adoption rates and pilgrimage-season traffic elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Beverage Vending Machine Market
Food Service
Food Service Utensils Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Virtual Kitchen Market
Food Service
Europe Vending Machine Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Thailand Food Service Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Kuwait Food Service Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Personal Chef Services Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
West Africa Food Services Market
Food Service
United States Online Food Delivery Market
Food Service
Portable Buffet and Drop-In Ranges Market