
 Online Grocery Market | 2026-2036
Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
Online Grocery Market Analysis
Urban household penetration is hardening as dual-income families replace weekly supermarket trips with scheduled replenishment cycles. Walmart leverages its supercenter footprint to anchor same-day fulfillment density in suburban corridors. Amazon competes through vertically integrated logistics networks that compress last-mile delivery windows. Kroger differentiates via proprietary fulfillment centers optimized for fresh produce picking accuracy.
Online grocery denotes the digital procurement of food and household consumables through web-based platforms or mobile applications, typically involving refrigerated warehousing, batch-picking algorithms, and temperature-controlled last-mile transport to preserve perishable integrity. The category serves commercial and residential buyers seeking to eliminate physical store visits while maintaining product freshness standards. Direct delivery occupies the largest volume share among distribution channels, though click and collect commands superior unit economics by eliminating last-mile transport costs. Subscription box models sustain higher retention rates among busy professionals through algorithmic replenishment of recurring staples. Online marketplace penetration is accelerating fastest among students and seniors attracted to price transparency and promotional aggregation.
FDA food safety protocols govern cold-chain integrity requirements for perishable shipments within the United States, while the EU Green Deal packaging waste directives are reshaping last-mile container specifications across European operations. India's FSSAI guidelines mandate hygiene certifications for dark store operations handling unpacked fresh produce. Stakeholders must monitor evolving refrigerant regulations under the EU F-Gas framework and assess captive fulfillment investments against third-party platform economics.
Market Dynamics
Dual-income households are hardening their reliance on scheduled replenishment cycles, compressing traditional supermarket foot traffic into algorithmically optimized dark-store fulfillment networks that prioritize perishable integrity over browsing experience.
Growth Catalysts
- EU Green Deal packaging directives:Mandates for reusable last-mile containers are accelerating investment in return-loop logistics infrastructure across European operations.
- Dark-store automation:Batch-picking algorithms integrated with computer vision are reducing fresh-produce handling errors below human baseline rates.
- India smartphone penetration:Urban density above 4,000 persons per square kilometer enables 15-minute delivery economics previously unviable in dispersed markets.
Market Restraints
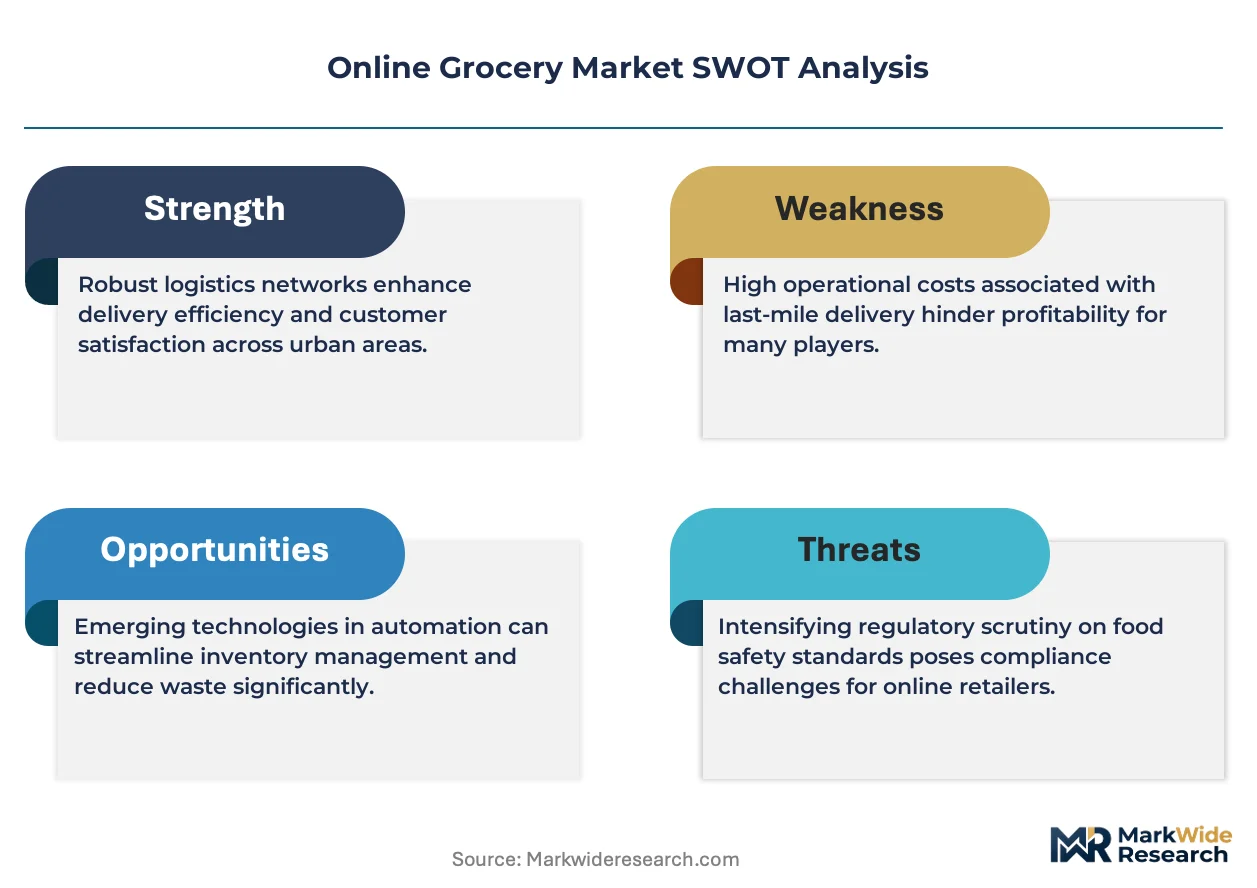
- Refrigerant cost volatility:EU F-Gas phase-down schedules are compressing hydrofluorocarbon supply and elevating cold-chain equipment capex.
- Last-mile labor concentration:Gig-platform dependency in dense urban corridors creates wage-spike vulnerability during demand surges.
- Perishable shrinkage ceiling:Temperature excursions above 4°C for more than 30 minutes render produce unsaleable regardless of packaging innovation.
Strategic Opportunities
- Subscription algorithm refinement:Machine learning on household consumption patterns enables predictive replenishment before stockout triggers manual reordering.
- India tier-2 urban expansion:Cities with 500,000 to 2 million residents show smartphone penetration above 65 percent but platform penetration below 12 percent.
- Click-and-collect unit economics:Eliminating last-mile transport costs produces margin structures competitive with in-store shopping.
Industry Challenges
- Fresh-produce picking accuracy:Variability in ripeness and cosmetic standards requires human-in-the-loop quality control that automation has not replicated.
- Legacy ERP integration:Inventory synchronization between dark-store WMS and retailer central systems introduces stock-visibility latency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Grocery Market |
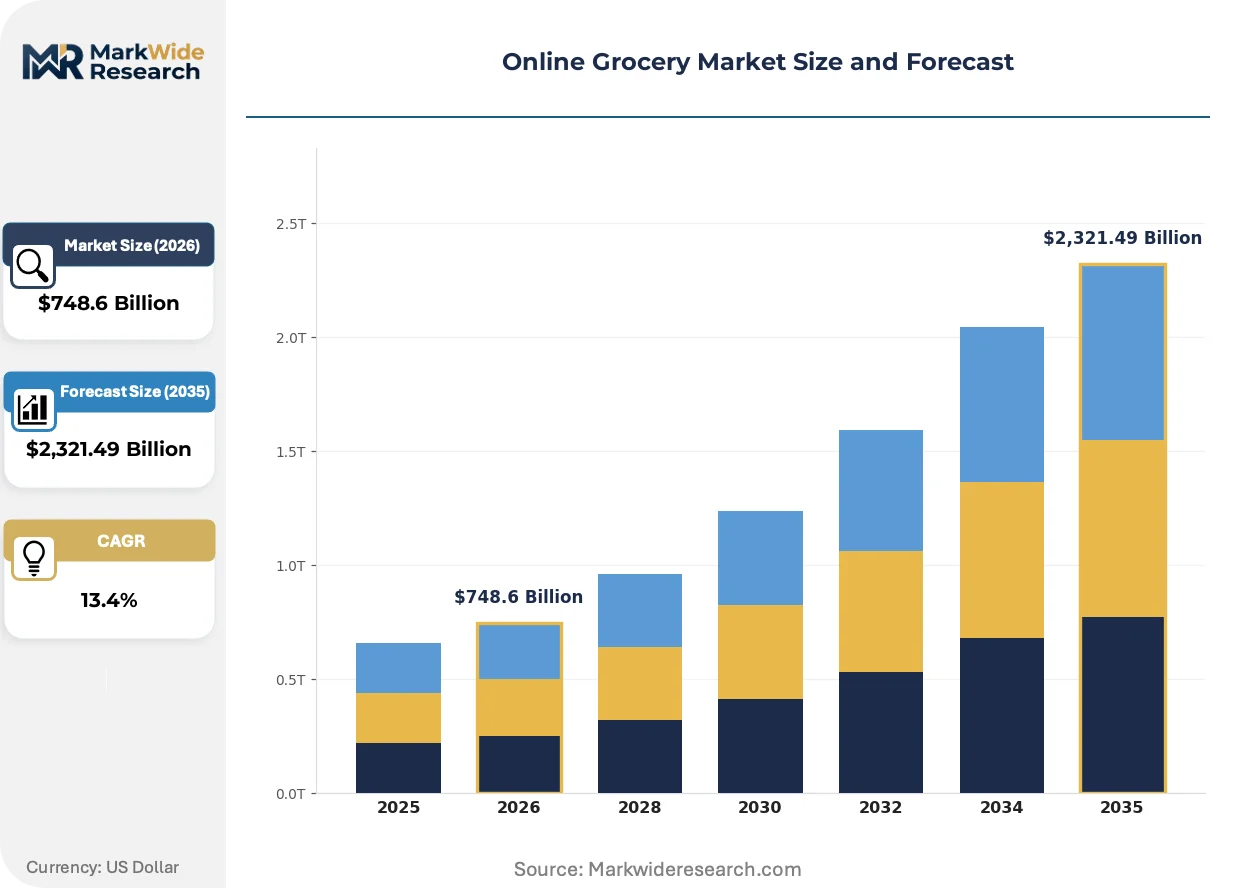
| Market Size in 2026 | $748.6 Billion |
| Market Size in 2035 | $2,321.49 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Beverages Customer Type: Busy Professionals, Families, Students, Seniors Distribution Channel: Direct Delivery, Click & Collect, Subscription Box, Online Marketplace Payment Method: Credit Card, Debit Card, Digital Wallet, Cash on Delivery |
| Companies Covered | Albertsons Companies, Costco Wholesale Corporation, Amazon, Carrefour, Tesco PLC, Walmart, Target Corporation, Instacart, Kroger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Grocery Market Emerging Trajectories
Automation is absorbing labor-intensive picking and packing functions while regulatory pressure on packaging waste forces redesign of temperature-controlled logistics. Demand patterns are fragmenting across generational cohorts with divergent willingness to trade convenience for price transparency.
Computer vision systems paired with robotic grasping hardware are absorbing fresh-produce selection tasks previously requiring human judgment. Grocery platforms in South Korea and Japan are deploying these systems at scale in temperature-controlled fulfillment centers. The technology is absorbing quality-control labor costs while compressing order-to-dispatch intervals below 12 minutes for standard basket sizes.
The EU F-Gas Regulation is mandating refrigerant phase-downs that force cold-chain equipment replacement before natural depreciation cycles complete. Operators face stranded asset risk in refrigerated vehicles and warehouse cooling systems. Indian dark-store networks are responding by leapfrogging to transcritical CO2 systems that bypass synthetic refrigerant dependency entirely.
Scheduled replenishment is displacing impulse-driven weekly shops among households with children under 12. Parents are abandoning supermarket browsing for algorithmic staple prediction that eliminates decision fatigue. This pattern concentrates in United Kingdom and Australian suburbs where dual-income prevalence exceeds 70 percent and parking friction at physical stores is acute.
Online Grocery Market Segmentation
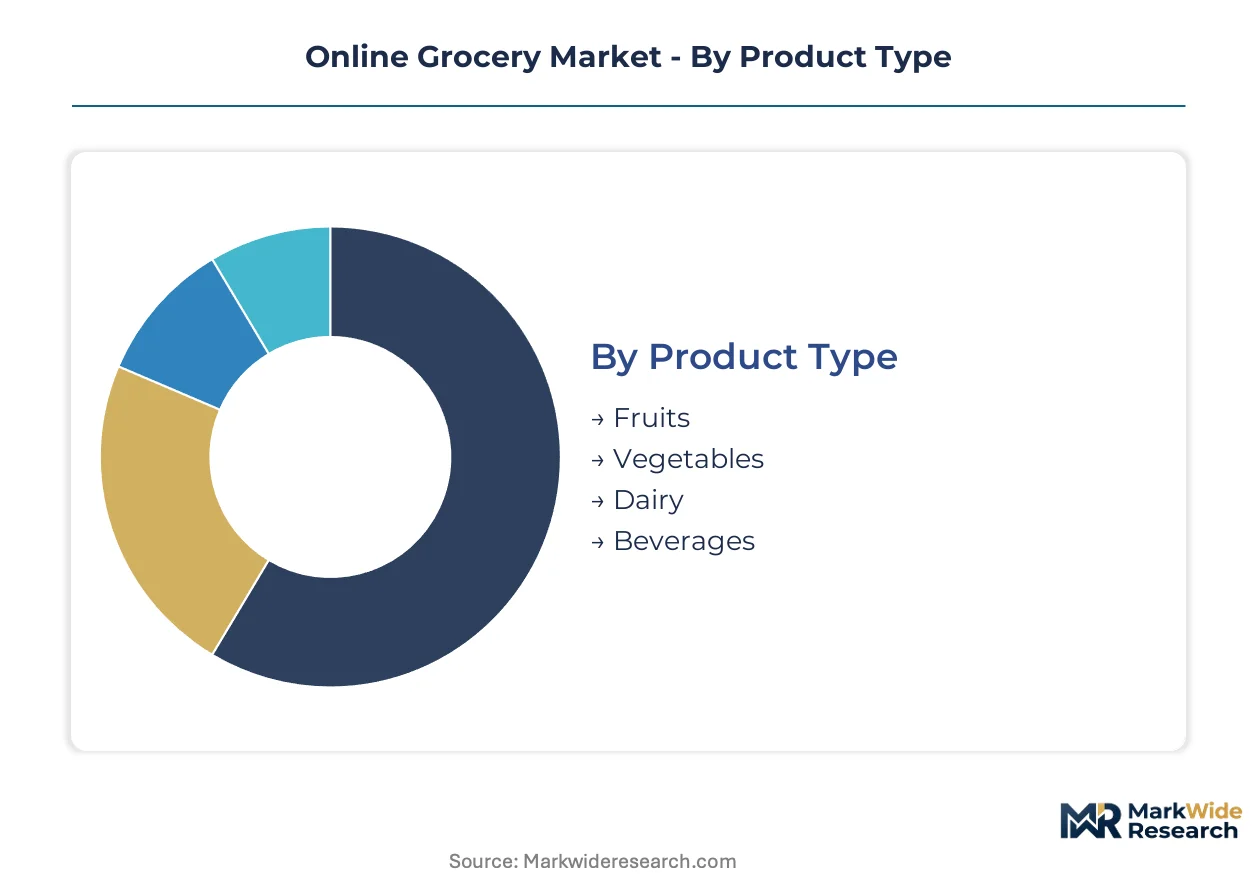
Segmentation in online grocery reveals divergent logistics requirements and margin profiles across product freshness tiers and customer life stages. Understanding these divisions exposes where automation investments yield highest returns and which payment infrastructures require regional customization.
Product Type:
Temperature sensitivity and spoilage risk separate procurement workflows and fulfillment economics across edible categories.
- Fruits:Ripeness variability demands computer vision grading systems in dark-store picking operations. Demand concentrates in Indian metropolitan corridors where FSSAI hygiene mandates for unpacked handling drive certification investments by platform operators.
- Vegetables:Leafy greens require 0-4°C chain integrity with maximum 20-minute ambient exposure windows. UK suburban households with children under 12 show highest replenishment frequency for this segment, compressing order-to-dispatch targets below 15 minutes.
- Dairy:Refrigerated transport compliance with FDA pasteurization protocols governs interstate distribution in the United States.
- Beverages:Shelf-stable liquids enable batch consolidation and lower last-mile cost per unit versus temperature-controlled categories.
Fruits lead volumes today; vegetables are gaining share fastest.
Customer Type:
Time scarcity and digital literacy determine platform interface design and subscription algorithm sophistication.
- Busy Professionals:Scheduled replenishment algorithms eliminate decision fatigue through predictive staple reordering. This cohort in Australian suburbs with dual-income prevalence above 70 percent shows highest subscription retention rates for automated basket generation.
- Families:Multi-person household consumption patterns require larger basket sizes that improve per-order economics for direct delivery. Indian tier-2 cities with 500,000 to 2 million residents show this segment expanding most quickly as smartphone penetration crosses 65 percent.
- Students:Price transparency sensitivity drives marketplace aggregation behavior over direct platform loyalty.
- Seniors:Interface simplicity requirements favor click-and-collect with assisted pickup protocols.
Families dominate current transaction volumes; busy professionals show steepest expansion trajectory.
Distribution Channel:
Fulfillment infrastructure ownership and last-mile cost absorption define competitive positioning.
- Direct Delivery:Vertically integrated logistics networks compress delivery windows through captive driver fleets. South Korean platforms deploy this model with sub-12-minute dispatch intervals for standard basket sizes.
- Click & Collect:Elimination of last-mile transport produces margin structures competitive with in-store economics. EU Green Deal packaging directives accelerate reusable container return-loop investments for this channel.
- Subscription Box:Algorithmic replenishment sustains retention through predictive consumption modeling.
- Online Marketplace:Third-party seller aggregation sacrifices margin for assortment breadth and price transparency.
Direct delivery leads volumes today; click and collect is climbing the fastest.
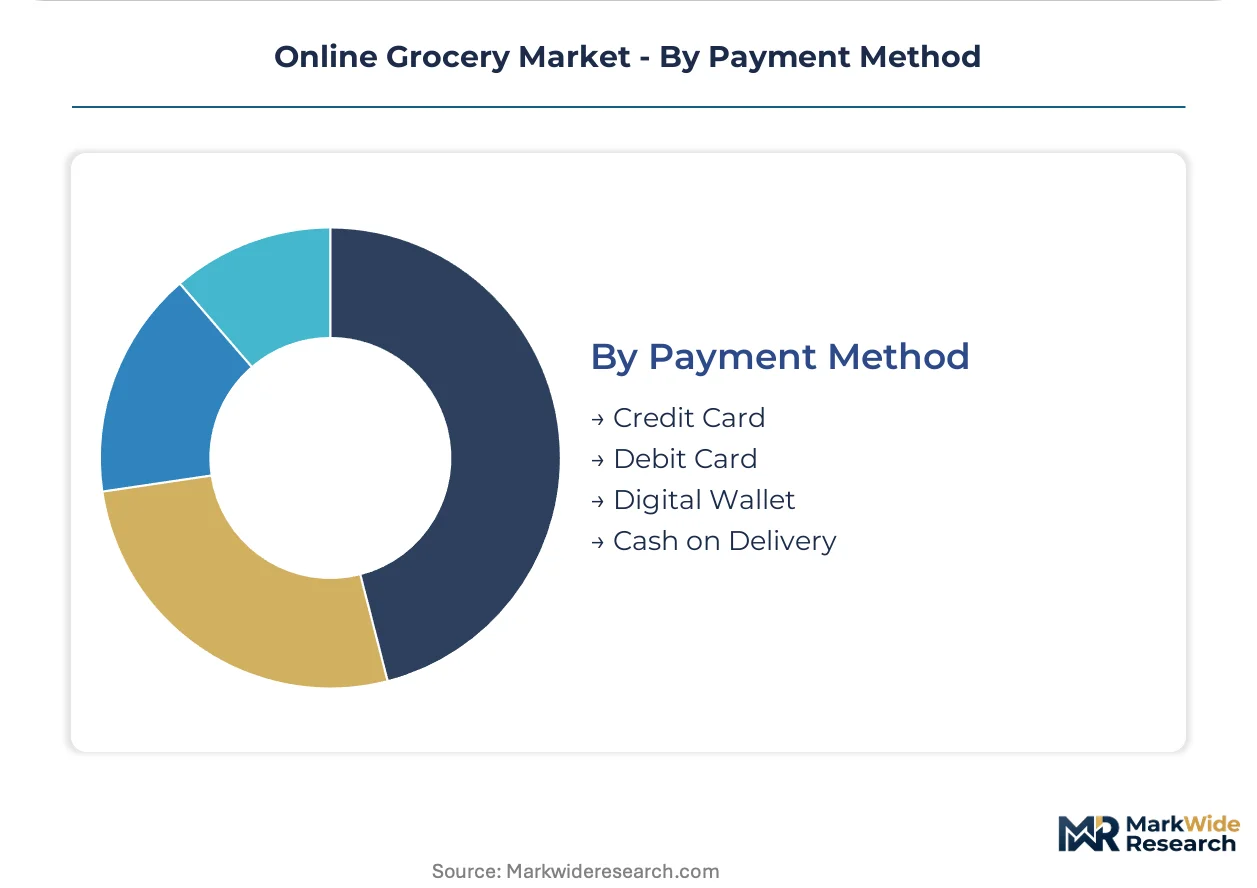
Payment Method:
Financial infrastructure maturity and regulatory compliance shape checkout conversion rates.
- Credit Card:Chargeback protection and rewards integration drive preference among high-frequency purchasers in developed markets.
- Debit Card:Real-time settlement reduces platform working capital requirements versus credit float.
- Digital Wallet:UPI integration in India enables sub-30-second checkout completion that reduces cart abandonment.
- Cash on Delivery:Trust bridging for first-time adopters in cash-dominant economies imposes reverse logistics costs for uncollected orders.
Digital wallet leads volumes today; cash on delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in cold-chain compliance costs is redirecting dark-store investment toward jurisdictions with flexible FSSAI-equivalent hygiene frameworks and subsidized refrigerant transitions. Operators migrate fulfillment infrastructure where EU F-Gas phase-down penalties remain absent and last-mile labor regulations permit gig-platform elasticity.
United States
Dual-income suburban households in Texas and Florida are hardening scheduled replenishment patterns around algorithmic staple prediction. FDA pasteurization protocols govern interstate dairy distribution, forcing refrigerated fleet compliance investments. Walmart anchors same-day fulfillment density across Dallas-Fort Worth and Houston corridors using supercenter backrooms as micro-fulfillment nodes.
India
Urban density above 4,000 persons per square kilometer in Mumbai and Bangalore enables 15-minute delivery economics previously unviable in dispersed markets. FSSAI hygiene certifications mandate dark-store operator investments for unpacked fresh produce handling. Platform penetration accelerates fastest in tier-2 cities including Pune and Ahmedabad where smartphone penetration crosses 65 percent.
South Korea
Computer vision systems paired with robotic grasping hardware absorb fresh-produce selection tasks at scale in Seoul metropolitan fulfillment centers. National refrigerant regulations under K-REACH parallel EU F-Gas constraints but with extended compliance timelines. Coupang and local platforms deploy sub-12-minute dispatch intervals for standard basket sizes through vertically integrated logistics networks.
Germany
EU Green Deal packaging directives mandate reusable last-mile containers, accelerating return-loop logistics infrastructure investments in Berlin and Munich corridors. ECHA chemical safety frameworks govern disinfectant protocols for dark-store sanitation. REWE and Edeka operate automated fulfillment centers in North Rhine-Westphalia optimized for fresh-produce picking accuracy.
United Kingdom
Parents in Greater London and Manchester suburbs abandon supermarket browsing for algorithmic staple prediction, compressing traditional foot traffic into dark-store networks. FSA hygiene ratings govern unpacked produce handling certifications. Ocado and Tesco deploy proprietary fulfillment centers with batch-picking algorithms that prioritize perishable integrity over browsing experience.
Online Grocery Market Vendor Landscape
Capacity expansion dominates the current landscape as operators build captive fulfillment networks to compress delivery windows. The vendor base stratifies across three tiers: mass-market retailers with supercenter footprints, pure-play logistics integrators, and subscription algorithm specialists. Consolidation pressure concentrates among mid-scale regional grocers lacking dark-store automation. M&A activity and geographic expansion represent the dominant competitive moves as players seek density in underpenetrated urban corridors.
Among US-based mass-market retailers, Walmart and Target exemplify the supercenter-anchored fulfillment archetype, leveraging existing real estate for same-day delivery density. Amazon occupies a distinct position as a vertically integrated logistics operator with proprietary cold-chain networks. European operators including Carrefour and Tesco sit within the hybrid model tier, combining physical store networks with dedicated dark-store investments to balance coverage and unit economics.
| Leading Market Players |
|---|
| Albertsons Companies |
| Costco Wholesale Corporation |
| Amazon |
| Carrefour |
| Tesco PLC |
| Walmart |
| Target Corporation |
| Instacart |
| Kroger |
| Others |
Supply Flow & Price Mechanics
Dark-store automation compressing order-to-dispatch intervals below 12 minutes is simultaneously lowering per-unit fulfillment costs and concentrating operational control among platforms with captive logistics networks, reshaping competitive economics across temperature-controlled grocery categories.
Pricing Analysis
Direct delivery channel margins absorb last-mile transport costs that click-and-collect operations bypass entirely, creating a two-tier margin structure. Price differentiation rests on delivery speed premiums versus pickup convenience discounts, with busy professionals in Australian suburbs showing lowest price sensitivity and students in Indian tier-2 cities exhibiting highest. Pricing pressure stems from gig-platform wage spikes in dense urban corridors during demand surges. Families with multi-person households generate larger basket sizes that improve per-order economics and reduce effective price sensitivity.
Supply Chain Analysis
Regional distribution centers in Germany, South Korea, and India anchor hub-and-spoke patterns for temperature-controlled fulfillment. Cold-chain equipment draws from hydrofluorocarbon suppliers facing EU F-Gas phase-down constraints, while fresh produce sourcing rests on FSSAI-certified dark stores in Mumbai and Bangalore. Single-source vulnerability concentrates in synthetic refrigerant supply chains subject to regulatory restriction. Distribution runs through vertically integrated captive fleets for direct delivery and third-party logistics partnerships for click-and-collect.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operators can exploit arbitrage between India's flexible FSSAI-equivalent hygiene frameworks and the EU's rigid F-Gas compliance costs, redirecting dark-store investment toward jurisdictions with subsidized refrigerant transitions and elastic gig-platform labor regulations.
For Market Incumbents: Deploy subscription algorithm refinement as the primary retention lever against pure-play logistics integrators. Incumbents should consolidate regional grocer networks lacking dark-store automation in Indian tier-2 cities and UK suburban corridors. Capacity addition in Pune and Ahmedabad captures smartphone penetration above 65 percent before platform saturation hardens. For New Entrants and Emerging Players: Enter via click-and-collect infrastructure in EU Green Deal jurisdictions where reusable container return-loop investments create barrier gaps. White-space targets include Indian tier-2 cities with 500,000 to 2 million residents and UK Greater Manchester suburbs with acute parking friction. Go-to-market positioning emphasizes margin structures competitive with in-store shopping through last-mile cost elimination. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional grocers lacking proprietary fulfillment center technology. Long-term viability across the analysis window favors platforms with backward integration into cold-chain logistics and predictive replenishment algorithms. The signal to watch is FSSAI certification density in Indian dark-store networks as a proxy for operational moat formation.| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Automation Deployment | Computer vision systems in Seoul fulfillment centers absorb quality-control labor costs while compressing dispatch intervals. |
| Refrigerant Infrastructure Transition | Transcritical CO2 systems in Indian dark stores bypass synthetic refrigerant dependency under EU F-Gas constraints. |
| Subscription Algorithm Investment | Predictive replenishment for UK dual-income households eliminates decision fatigue and sustains retention rates. |
| Tier-2 Geographic Expansion | Platform penetration below 12 percent in Pune and Ahmedabad offers first-mover density advantages. |
| Reusable Container Return-Loop | EU Green Deal mandates in Berlin and Munich corridors accelerate infrastructure investments with regulatory tailwinds. |
Methodological Framework
Bottom-up household consumption modeling reconciled against top-down fulfillment capacity tracking forms the analytical core. Primary interviews with dark-store operations managers, grocery platform supply chain directors, cold-chain logistics providers, and FSSAI compliance officers combined with secondary validation from customs trade records, SEC retail filings, EU ECHA chemical safety frameworks, and Indian smartphone penetration databases. Triangulation between demand-side replenishment pattern analysis and supply-side refrigerated fleet deployment data ensures cross-verification.
Input-output matrices map segmentation dimensions including product temperature sensitivity tier, customer life stage archetype, fulfillment channel ownership structure, and payment infrastructure maturity across the projection horizon. CAGRs derive from algorithmic staple adoption curves and dark-store automation diffusion rates. Industry-specific forecast inputs incorporate EU F-Gas phase-down schedules and Indian urban density thresholds for 15-minute delivery viability.
Inputs from regulatory filing databases and platform operator disclosures were available through the study window; gaps in real-time gig-platform wage data introduce uncertainty bands around last-mile cost projections. Forecasts reflect documented assumptions around smartphone penetration trajectories and refrigerant substitution timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Wok Market
Food Service
Personal Chef Services Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Global Meal Kit Market
Food Service
Europe Cloud Kitchen Market
Food Service
Commercial Tandoor Oven Market
Food Service
Gas Fryers Market
Food Service
Food Truck Services Market
Food Service
Countertop Pressure Fryer Market
Food Service
Commercial Kitchen Appliances Market
Food Service
West Africa Food Services Market
Food Service
India Online Grocery Market
Food Service
Vacuum Flask Market
Food Service
Online Catering Market
Food Service
UAE Food Service Market