
 South America Gear Market | 2026-2036
South America Gear Market Size, Share, and Industry Trends Forecast 2026-2036
South America Gear Market Insights
Modular gear-train packaging is recalibrating buyer choice across South America's capital-equipment sectors. Carraro Group leverages integrated axle-transmission modules to dominate agricultural and construction machinery supply chains. Zanini Renk anchors high-torque wind turbine gearbox production for the region's expanding renewable energy base. Sumitomo Drive Technologies competes through localized assembly networks that reduce import dependency for Brazilian industrial customers.
Gears are toothed mechanical components that transmit torque and motion between rotating shafts through precise meshing engagement, typically manufactured via hobbing, shaping, or grinding processes to achieve AGMA or DIN tolerance classes. Helical gears occupy the largest product category due to superior load distribution and quieter operation in heavy machinery applications across Brazilian automotive and mining sectors. Planetary gear configurations represent the fastest-expanding segment, driven by robotics and renewable energy installations requiring high power density in compact footprints. Steel remains the dominant material selection, though alloy variants command premium positioning in aerospace and precision industrial machinery end uses.
Brazil's PROCONVE standards and Argentina's equivalent emissions frameworks shape transmission-system design requirements for automotive manufacturers throughout Mercosur trade zones. ANVISA certification protocols and local content regulations under Brazil's BNDES financing rules further condition market access for imported gear assemblies. Stakeholders must monitor evolving Mercosur technical barriers to trade and localize testing capabilities to sustain contract eligibility with state-backed infrastructure projects.
Market Dynamics
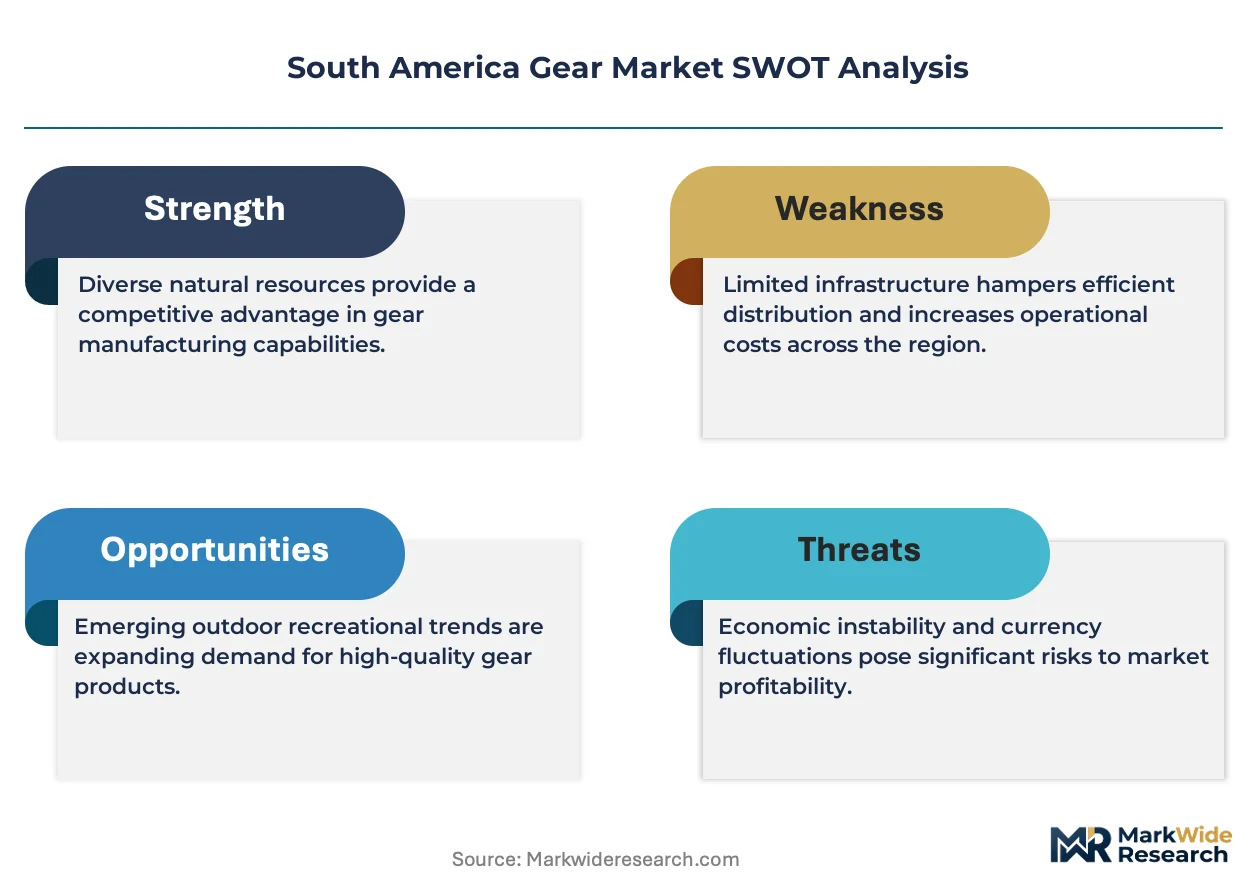
Brazil's PROCONVE vehicle emissions standards and Argentina's equivalent frameworks are forcing transmission redesigns across Mercosur automotive supply chains, while mining equipment procurement in Chile and Peru drives precision gear demand for stricter environmental compliance.
Growth Catalysts
- Renewable energy installations:Wind turbine gearbox demand accelerates as Brazil and Chile expand onshore capacity. Planetary configurations dominate new nacelle designs for high power density.
- ANVISA certification pathways:Streamlined medical device approvals enable precision gear integration into Brazilian surgical robotics and diagnostic equipment manufacturing.
- Mining sector modernization:Chilean and Peruvian copper producers upgrade fleet transmissions to meet emissions thresholds, pulling helical and bevel gear orders from southeastern Brazilian suppliers.
Market Restraints
- Alloy steel import dependency:Specialty bearing-grade steels for aerospace and precision industrial applications concentrate sourcing from European and Asian mills, exposing Brazilian fabricators to currency volatility and lead time extension.
- BNDES local content floors:Brazil's development bank mandates minimum domestic value-add percentages for infrastructure financing eligibility, complicating gear assembly sourcing for multinational OEMs.
- Electrification substitution:Direct-drive motor architectures in light electric vehicles eliminate multi-speed transmissions, compressing automotive gear demand in passenger car segments.
Strategic Opportunities
- Colombian infrastructure buildout:Road and tunnel construction projects create first-mover positioning for construction machinery gear-train suppliers establishing Andean distribution.
- Additive manufacturing convergence:Hybrid production combining conventional hobbing with selective laser melting enables rapid prototyping of custom gear profiles for maintenance-repair-overhaul channels.
- Uruguayan free trade zone utilization:Port of Montevideo logistics infrastructure supports duty-efficient re-export of Brazilian-manufactured gear assemblies to Argentine and Paraguayan markets.
Industry Challenges
- AGMA/DIN metrology capability gaps:Fewer than twelve certified testing laboratories operate across the entire continent, creating bottlenecks for precision gear validation and export certification.
- Legacy equipment integration friction:Mining and agricultural machinery fleets average eighteen years of service life, requiring backward-compatible gear designs that constrain modular platform adoption.
- Specialized heat treatment capacity:Carburizing and nitriding furnace availability concentrates in São Paulo state, forcing long-haul logistics for finished components from Minas Gerais machining clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Gear Market |
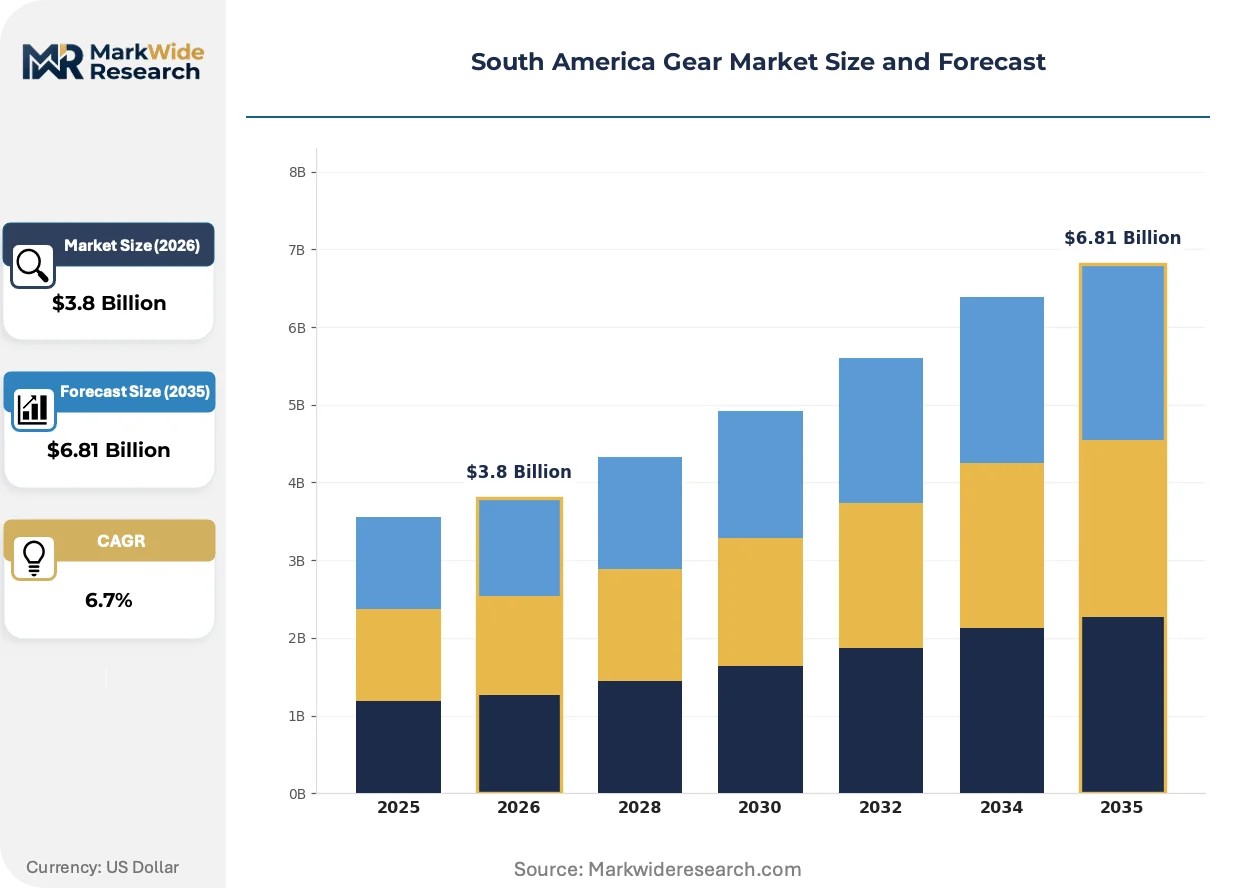
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical Gears, Bevel Gears, Spur Gears, Planetary Gears End User: Aerospace, Automotive Manufacturers, Industrial Machinery, Energy Sector Material: Steel, Brass, Plastic, Alloy Application: Transmission Systems, Robotics, Renewable Energy, Construction Equipment |
| Companies Covered | Carraro Group, Zanini Renk, Companhia Industrial de Peças (CIP), Sumitomo Drive Technologies, GNA Gears, Renk Group, Elecon Engineering, Shanthi Gears, Precimaq, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Gear Market Trends and Innovations
Digital thread integration across design-manufacturing-test workflows is compressing product development cycles for precision gear producers serving South American capital equipment markets.
Hybrid additive-subtractive manufacturing is converging with conventional gear production lines. Brazilian job shops serving agricultural OEMs adopt laser cladding for worn tooth restoration and near-net-shape preforms. Equipment suppliers in Minas Gerais report forty percent lead time reduction for custom spiral bevel prototypes. This convergence is compressing minimum viable order quantities and enabling economically viable single-piece production runs.
PROCONVE P-8 emission standards enforce real-time powertrain monitoring and predictive maintenance integration. Automotive transmission suppliers must embed torque sensors and telemetry modules within gear housings. The regulation most affects São Paulo-based commercial vehicle manufacturers, which are redesigning axle differentials to accommodate sensor arrays and data transmission hardware.
Aftermarket service unbundling accelerates as mining operators in Chile's Atacama Desert demand component-level gear replacement rather than complete transmission exchanges. Independent distributors in Antofagasta and Calama stock planetary gear sets and sun gears separately, displacing traditional OEM captive parts programs. This behavioral shift concentrates procurement authority with site maintenance engineers rather than centralized fleet purchasing departments.
South America Gear Market Segmentation
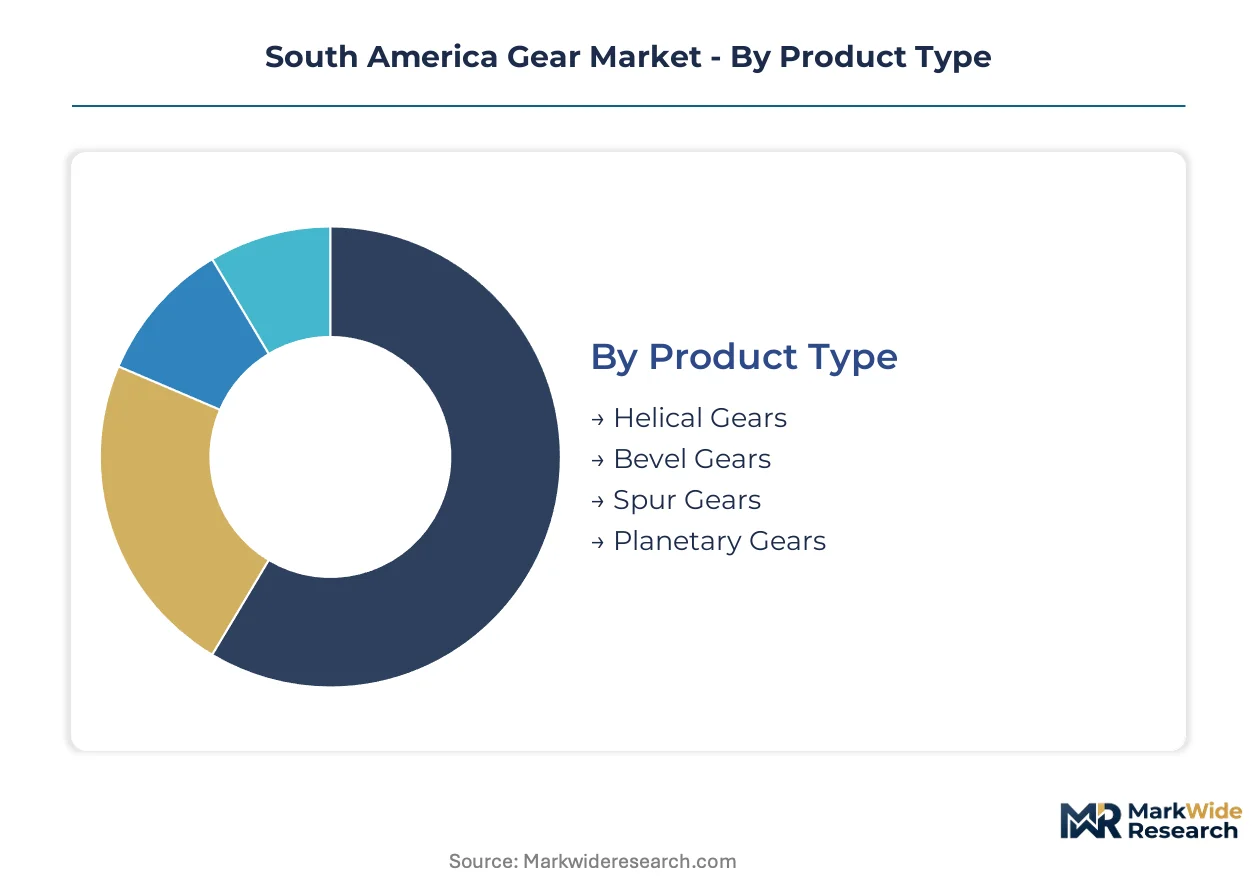
Gear specification choices in South America trace directly to end-use severity and local supply capabilities. Procurement patterns split between heavy-industry durability requirements and precision applications where imported alloys dominate cost structures.
Product Type:
Buyer differentiation centers on load distribution needs and noise constraints across Brazilian mining corridors and Argentine agricultural zones.
- Helical Gears:Angled tooth engagement spreads loads across multiple contact points, reducing vibration in high-torque conveyor systems. Brazilian iron ore processors in Minas Gerais specify these for continuous-duty material handling lines where downtime costs exceed replacement part premiums.
- Planetary Gears:Epicyclic arrangements deliver torque multiplication in compact radial envelopes. Wind turbine nacelle assemblers in Rio Grande do Sul and Ceará deploy these configurations for drivetrain density where tower-top weight limits constrain design freedom.
- Bevel Gears:Conical tooth profiles transmit power between intersecting shafts in mining truck differentials and agricultural tractor PTO systems.
- Spur Gears:Parallel-axis simplicity suits low-speed auxiliary drives where cost minimization outweighs noise considerations.
Helical configurations lead volumes today; planetary systems are gaining share fastest.
End User:
Volume concentration varies by capital investment cycles and regulatory compliance intensity across Mercosur industrial zones.
- Automotive Manufacturers:PROCONVE emission tiers force transmission redesigns integrating real-time torque monitoring. São Paulo-based commercial vehicle plants now specify gear housings with embedded sensor mounting bosses and telemetry conduit channels.
- Energy Sector:Onshore wind expansion in Brazil's Northeast and Chile's Biobío region pulls precision planetary assemblies for megawatt-scale turbine drivetrains.
- Industrial Machinery:Food processing and packaging lines in Argentina's Buenos Aires province demand stainless-compatible gearing for washdown compliance.
- Aerospace:Maintenance-repair-overhaul facilities in São José dos Campos source superalloy precision gears for regional jet engine accessory drives.
Automotive procurement anchors current demand; energy sector orders are climbing the fastest.
Material:
Selection tradeoffs pivot on strength-to-weight requirements versus domestic mill availability and heat treatment infrastructure reach.
- Steel:Carbon and alloy grades dominate mining and construction applications where fatigue resistance governs service life. Carburizing capacity concentrates in São Paulo state, forcing Minas Gais fabricators into long-haul logistics for case-hardened finished components.
- Alloy:Nickel-chromium-molybdenum formulations serve aerospace and precision industrial specifications where AGMA Q12 tolerances apply. Brazilian fabricators import bearing-grade specialty steels from European and Asian mills, exposing procurement to currency volatility.
- Brass:Corrosion resistance and machinability suit marine hardware and decorative architectural applications with modest load requirements.
- Plastic:Acetal and nylon formulations reduce noise and eliminate lubrication in consumer appliance and medical device gear trains.
Steel grades command the largest volume position; alloy specifications show the steepest expansion trajectory.
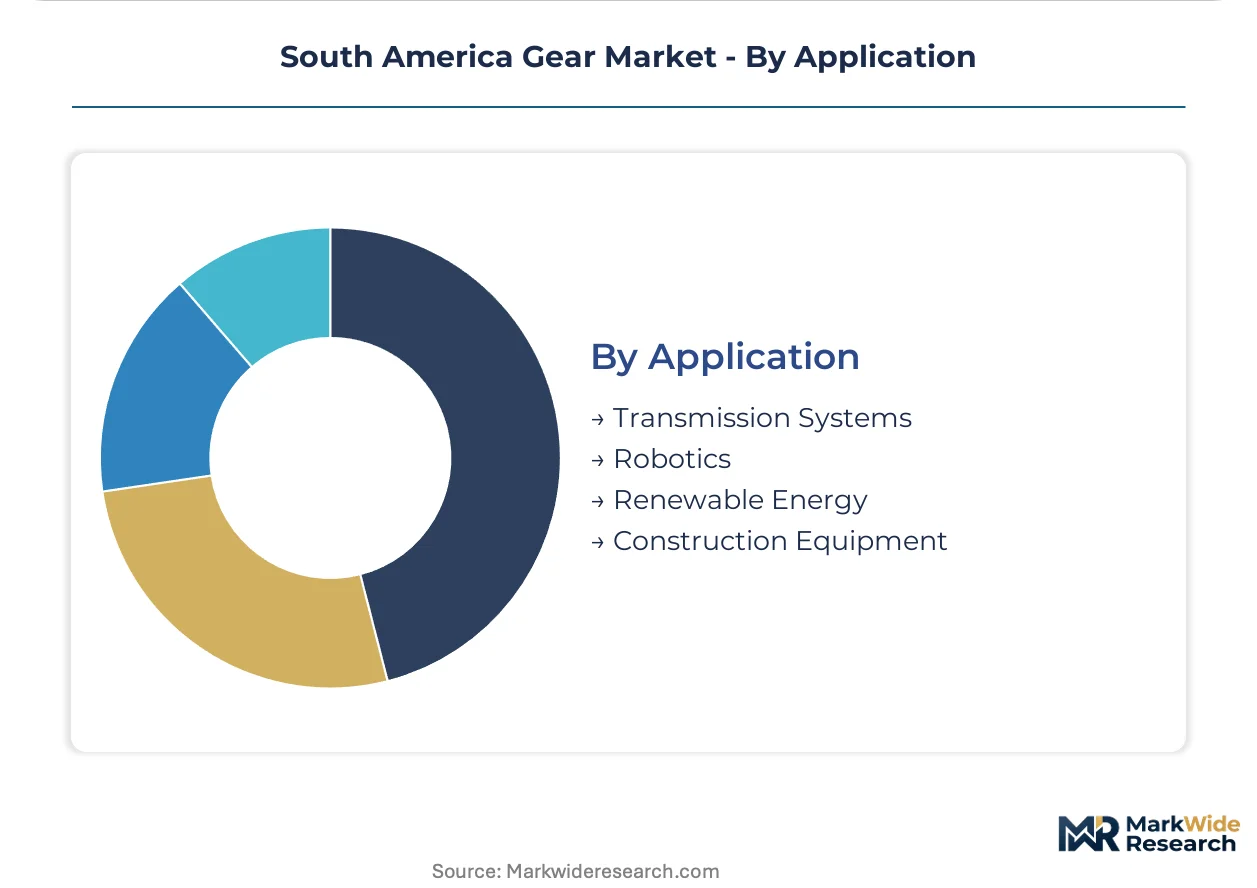
Application:
Functional requirements diverge between stationary power transmission and mobile equipment where weight and packaging density constrain design.
- Transmission Systems:Multi-speed gearboxes for commercial vehicles and mining haulers must reconcile PROCONVE monitoring mandates with mechanical durability. Differential redesigns in São Paulo manufacturing plants now accommodate sensor arrays and data transmission hardware.
- Renewable Energy:Wind turbine main bearings and yaw drives require twenty-year service life predictions with minimal maintenance access. Gear producers serving Brazilian and Chilean wind farm developers emphasize planetary stage efficiency and sealed lubrication systems.
- Construction Equipment:Excavator swing drives and crawler final drives demand shock-load capacity for irregular terrain operations.
- Robotics:Harmonic and cycloidal drives for surgical and industrial automation require positioning repeatability within arc-minute tolerances.
Transmission applications hold the volume lead today; renewable energy deployments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision gear manufacturing took root in South America through European immigrant-founded machine shops in São Paulo during the mid-twentieth century. These operations supplied Brazil's import-substitution industrialization programs before expanding into agricultural and mining equipment sectors. Today, the industry clusters around southeastern Brazilian states while serving demand across the continent's extractive and energy infrastructure.
Brazil
PROCONVE vehicle emission standards and BNDES local content mandates drive transmission redesigns for commercial vehicle manufacturers. ANVISA certification protocols shape medical device gear integration into surgical robotics. São Paulo and Minas Gerais states host the continent's densest concentration of carburizing furnaces and precision machining capacity.
Chile
Copper mining fleet modernization pulls high-torque helical and bevel gear orders from Brazilian suppliers. Stricter environmental compliance thresholds for open-pit operations accelerate precision drivetrain procurement. Antofagasta and Calama maintenance hubs stock planetary gear sets independently, displacing traditional OEM captive parts programs.
Argentina
Mercosur-aligned emission frameworks force agricultural machinery transmission redesigns for export eligibility to Brazilian markets. Buenos Aires province food processing lines demand stainless-compatible gearing for washdown compliance. Córdoba's automotive component cluster sources precision gears through cross-border supply arrangements with São Paulo fabricators.
Peru
Copper and gold mining expansion drives demand for heavy-duty haul truck differentials and conveyor drive systems. The Ministry of Energy and Mines enforces progressive closure regulations that extend equipment service life requirements. Lima-based distributors maintain inventory partnerships with southeastern Brazilian gear producers to reduce Andean lead times.
Colombia
Road and tunnel construction projects under the 4G infrastructure program create demand for excavator swing drives and crawler final drives. The National Infrastructure Agency's concession frameworks favor equipment suppliers with regional service networks. Bogotá machinery distributors increasingly source gear-train assemblies through Brazilian manufacturing channels.
South America Gear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and heat-treatment capability tiers. The vendor base organizes into three discernible strata: integrated axle-transmission module suppliers, precision planetary gearbox specialists, and regional job-shop fabricators serving maintenance channels. Consolidation pressures concentrate among mid-scale operators lacking captive heat treatment or metrology capabilities. Dominant competitive moves include backward integration into specialty steel sourcing and geographic expansion through Uruguayan free trade zone logistics.
Among European-origin industrial conglomerates, Carraro Group and Renk Group exemplify the integrated-systems archetype through axle-transmission module positioning. Zanini Renk occupies a specialist tier in high-torque renewable energy applications. Sumitomo Drive Technologies represents the localized-assembly competitive vector with Brazilian manufacturing presence. Precimaq and GNA Gears sit within the regional-fabricator tier serving aftermarket and maintenance-repair-overhaul channels. Companhia Industrial de Peças anchors the domestic Brazilian supplier base with long-standing agricultural OEM relationships.
| Leading Market Players |
|---|
| Carraro Group |
| Zanini Renk |
| Companhia Industrial de Peças (CIP) |
| Sumitomo Drive Technologies |
| GNA Gears |
| Renk Group |
| Elecon Engineering |
| Shanthi Gears |
| Precimaq |
| Others |
Pricing and Supply Chain Analysis
Backward integration into captive heat treatment anchors pricing power for Brazilian gear fabricators serving PROCONVE-mandated transmission redesigns. São Paulo state's concentration of carburizing furnaces creates geographic rent extraction for case-hardened components, while Minas Gais machining clusters absorb logistics premiums to access thermal processing capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AGMA Q12-certified aerospace gears from commercial vehicle transmission components and aftermarket replacement sets. Price differentiation hinges on certification grade and volume scale, with alloy steel import dependency compressing margins for precision specifications. Pricing pressure stems from electrification substitution in light passenger vehicles, where direct-drive architectures eliminate multi-speed gearboxes. Aftermarket distributors in Chile's mining corridors demonstrate highest price sensitivity due to unbundled procurement authority shifting to site maintenance engineers.
Supply Chain Analysis
Freight costs from European and Asian specialty steel mills compound currency volatility exposure for Brazilian precision gear producers. Manufacturing gravity centers on São Paulo and Minas Gerais states, with raw material dependencies spanning bearing-grade alloy steels, nodular iron castings, and cutting tool inserts. Single-source vulnerability concentrates in carburizing furnace capacity tethered to southeastern Brazil, forcing long-haul logistics for heat-treated finished components. Distribution runs through authorized OEM channels, independent aftermarket distributors, and Uruguayan free trade zone re-export hubs serving Argentine and Paraguayan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Gear Market functions as a regulatory compounder where PROCONVE P-8 emission standards force continuous transmission redesign cycles across Mercosur automotive supply chains.
For Market Incumbents: Deploy captive metrology certification to defend against AGMA/DIN testing laboratory bottlenecks that constrain export eligibility. Consolidate heat treatment capacity through acquisition of São Paulo-state furnace operators to capture margin currently lost to third-party thermal processing. Electrification substitution in passenger vehicles threatens volume; offset through expansion into wind turbine planetary gearbox production for Brazil's Northeast renewable energy corridor. For New Entrants and Emerging Players: Independent distributors in Chile's Atacama Desert represent the most penetrable channel, where unbundled aftermarket procurement displaces OEM captive parts programs. Target Colombian construction machinery gear-train demand under the 4G infrastructure program before established Brazilian suppliers establish Andean distribution networks. Partner with Montevideo free trade zone logistics operators to achieve duty-efficient re-export positioning into Mercosur markets without BNDES local content floor complications. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale regional fabricators because heat treatment and metrology capability scarcity concentrates value in certified operators. Five-to-ten year viability hinges on positioning for renewable energy drivetrain demand rather than automotive transmission exposure. Watch electrification penetration rates in Brazilian commercial vehicle segments as the critical inflection signal for transmission gear volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Treatment | Captive carburizing capacity in São Paulo state eliminates third-party thermal processing margins and logistics premiums. |
| Uruguayan Free Trade Zone Utilization | Montevideo logistics infrastructure enables duty-efficient re-export of Brazilian-manufactured gear assemblies to Argentine markets. |
| Additive Manufacturing Convergence | Hybrid laser cladding with conventional hobbing compresses lead times for custom spiral bevel prototypes in Minas Gerais job shops. |
| Planetary Gearbox Specialization | Wind turbine nacelle density requirements in Rio Grande do Sul and Ceará favor epicyclic configurations for tower-top weight constraints. |
| ANVISA Certification Pathway Investment | Streamlined medical device approvals enable precision gear integration into Brazilian surgical robotics manufacturing. |
Research Methodology
Multiple input streams — primary interviews with transmission design engineers, aftermarket procurement managers, and heat treatment facility operators; secondary validation through ANVISA regulatory filings, BNDES financing disclosure records, and Mercosur technical barrier notifications; plus customs trade data on alloy steel imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, material grade, end-use sector, and regional regulatory cluster dimensions produced volume and value estimates over the projection horizon. CAGRs were derived from segmented growth trajectory modeling. Forecast inputs incorporated PROCONVE implementation timelines, wind farm development pipeline tracking, and mining fleet modernization cycles in Chile and Peru.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrification substitution rates in commercial vehicles and alloy steel import tariff adjustments. Forecasts reflect documented assumptions about regulatory implementation pacing and capital equipment replacement cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Brake Pad Market
Automotive Parts
Automotive Screenwash Products Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Diesel Common Rail Injection System Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
Australia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Japan Passenger Vehicles Lubricants Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Common Rail System Market