
 AI-Ready Enterprise Knowledge Graph Market | 2026-2036
AI-Ready Enterprise Knowledge Graph Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Ready Enterprise Knowledge Graph Market Insights
Enterprise-grade graph query performance is collapsing the gap between pilot deployments and production-scale AI systems. Neo4j leverages native graph storage to dominate property graph deployments across financial services and telecommunications. Stardog anchors its position through knowledge graph virtualization that sustains federated queries without full data migration. Ontotext specializes in semantic technology stacks that extend RDF-based reasoning into manufacturing and government intelligence workflows.
An AI-ready enterprise knowledge graph is a structured data architecture that encodes entities, relationships, and semantic meaning using graph database engines, typically supporting ACID-compliant transactions and SPARQL or Cypher query languages, designed to power inference, recommendation, and generative AI retrieval-augmented generation pipelines. Cloud deployment configurations are capturing the fastest expansion as hybrid architectures mature, while on-premises installations retain strongholds in defense and classified government environments. Solution-layer spending concentrates in semantic search and entity resolution where margin pools deepen from recurring ontology engineering services.
The EU AI Act, FDA guidance on AI-enabled clinical decision support, and China's GB standards for algorithmic recommendation services are each tightening auditability requirements that favor knowledge graph provenance tracking. NIST's AI Risk Management Framework in the United States further elevates structured relationship mapping as a compliance enabler for high-stakes automated decisions. Stakeholders must weigh build-versus-buy commitments for ontology management as foundation model providers integrate native graph retrieval that could commoditize standalone tooling layers.
Market Dynamics
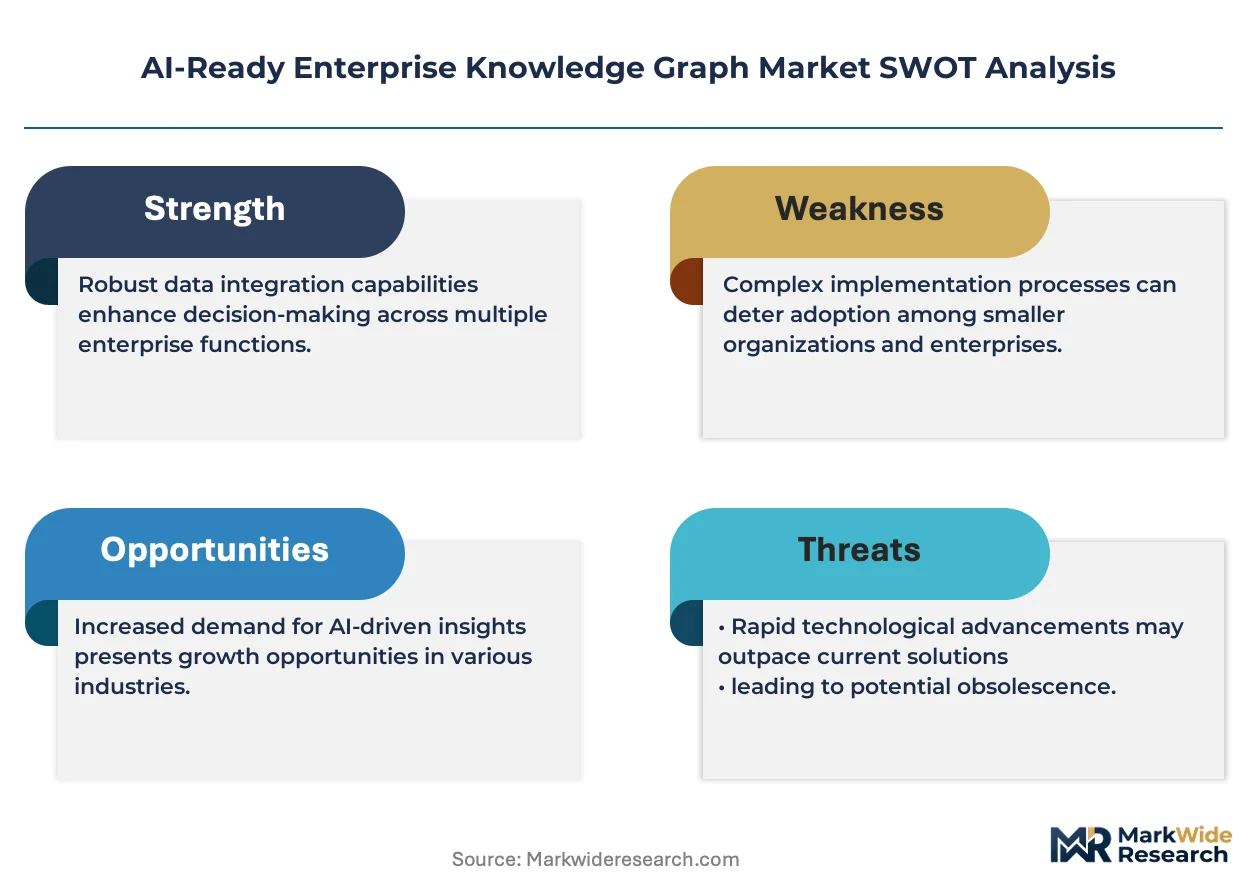
Foundation model providers are integrating native graph retrieval capabilities that threaten to commoditize standalone ontology management tooling, forcing incumbent vendors to defend their position through vertical specialization in regulated industries.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions in Frankfurt and Paris are deploying knowledge graphs to satisfy explainability requirements for automated credit decisions, creating immediate procurement pull.
- Entity resolution in telecommunications:Carrier networks use graph databases to unify subscriber identity across fragmented billing and service systems, reducing churn prediction latency.
- China:State-owned banks in Shanghai and Beijing are accelerating semantic search deployments to meet GB standards for algorithmic transparency in consumer lending.
Market Restraints
- Ontology engineering talent scarcity:The specialized skill set combining formal logic and domain expertise commands premium compensation, inflating implementation costs.
- SPARQL query performance limitations:RDF stores struggle with sub-second response times on billion-edge graphs, constraining real-time fraud detection applications.
- Data residency requirements:Germany's Bundesdatenschutzgesetz and similar national frameworks fragment cloud deployment architectures, complicating multi-national rollouts.
Strategic Opportunities
- India's BFSI modernization:RBI's push for digital lending infrastructure creates greenfield demand for knowledge graph-based credit risk engines in Mumbai and Bangalore.
- Retrieval-augmented generation convergence:Combining vector embeddings with graph traversal is opening new product categories in legal research and pharmaceutical competitive intelligence.
- Defense and intelligence:Classified environments in the United States and United Kingdom require air-gapped deployments, sustaining premium on-premises solution margins.
Industry Challenges
- Legacy data warehouse integration:ETL pipelines from relational schemas to property graphs require extensive custom mapping, extending deployment timelines.
- Model drift in dynamic ontologies:Domain concept evolution in rapidly changing industries like cryptocurrency compliance demands continuous engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Ready Enterprise Knowledge Graph Market |
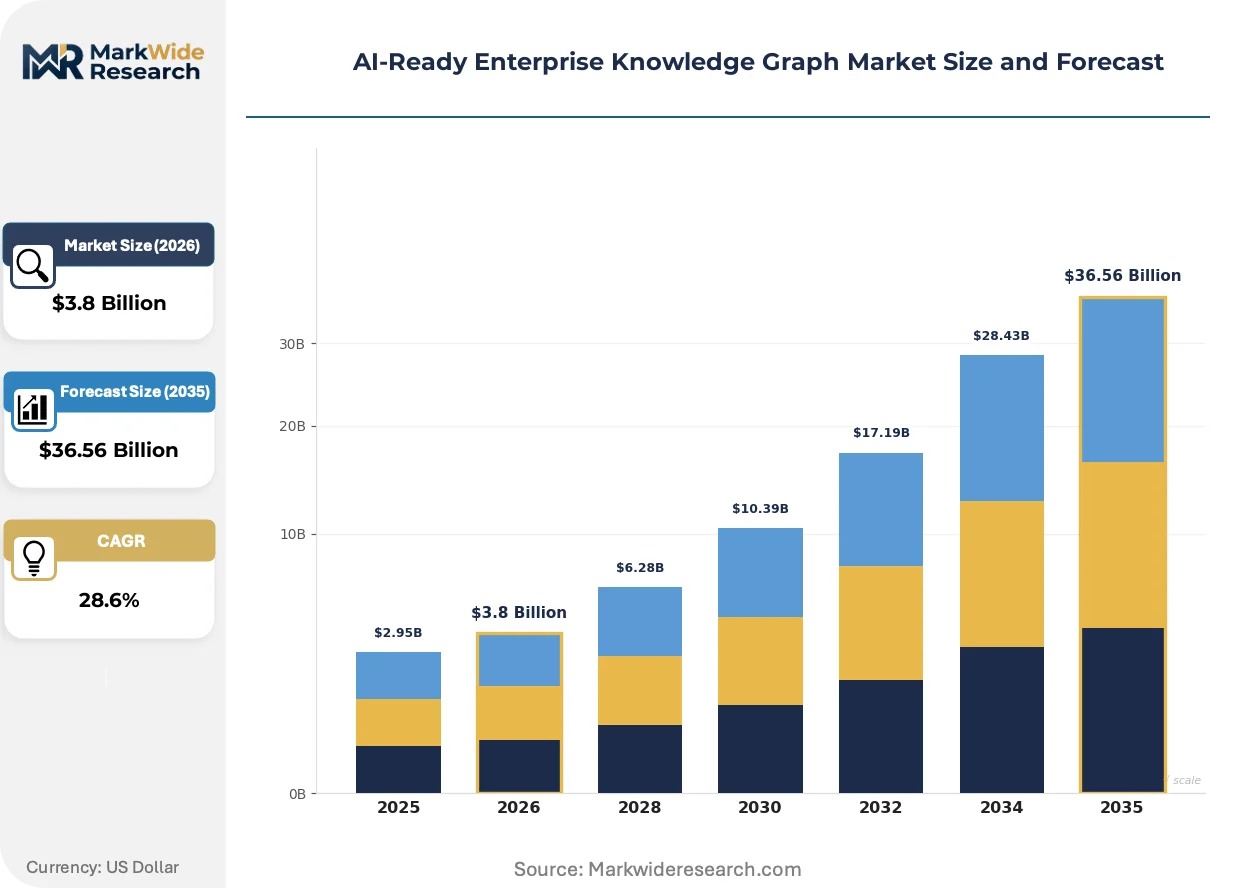
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid Cloud, Edge Computing Solution: Data Integration, Semantic Search, Relationship Mapping, Entity Resolution, Metadata Management Use Case: Customer 360, Fraud Detection, Predictive Maintenance, Risk Management, Compliance Monitoring End User: Financial Institutions, Telecommunications, Manufacturing Units, Retail Chains, Government Agencies |
| Companies Covered | Neo4j, Stardog, Ontotext, Oracle, Amazon Web Services, Microsoft, IBM, Altair, Progress Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Ready Enterprise Knowledge Graph Market Trends and Innovations
Graph-native vector search is collapsing the architectural boundary between structured relationship queries and semantic similarity retrieval, enabling unified platforms that previously required separate systems.
Hybrid graph-vector databases are fragmenting the traditional separation between knowledge graphs and embedding stores. Financial services firms in London and Singapore are piloting unified query interfaces that traverse both entity relationships and semantic neighborhoods. This convergence is compressing vendor margins in the standalone vector database segment.
The EU AI Act's risk classification system is mandating provenance documentation for high-stakes automated decisions. Pharmaceutical manufacturers preparing EMA submissions must now maintain auditable knowledge graph trails linking training data to model outputs. German medical device companies are rebuilding their clinical decision support architectures to satisfy these traceability requirements.
Buyer procurement patterns are consolidating around outcome-based ontology engineering contracts. Large enterprises in the United States are shifting from perpetual software licenses to recurring professional services engagements that guarantee query performance SLAs. This transition is visible most acutely in healthcare systems replacing legacy master data management with managed knowledge graph subscriptions.
AI-Ready Enterprise Knowledge Graph Market Segmentation
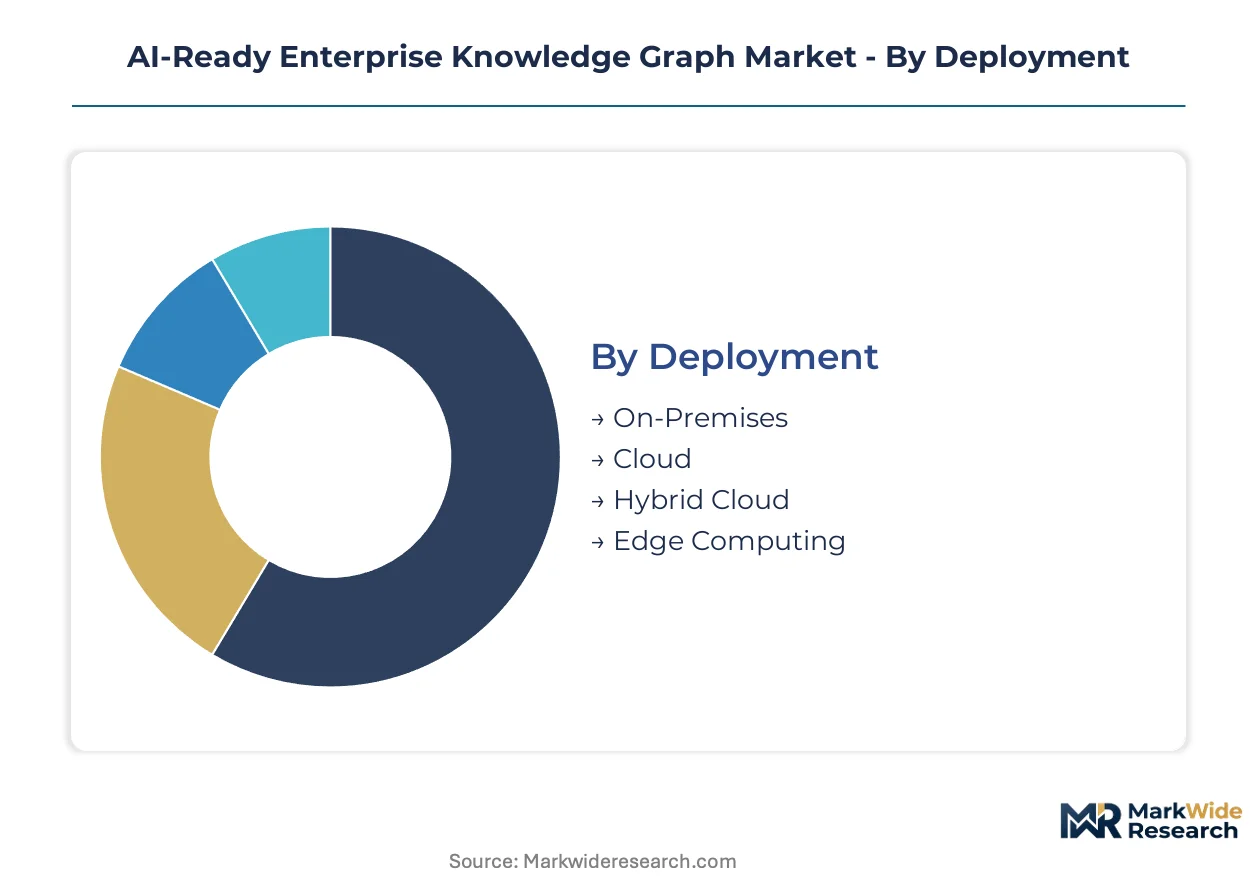
Knowledge graph architectures fragment across deployment topologies, solution layers, and regulatory use cases. Each segmentation dimension carries distinct margin profiles and compliance obligations that reshape procurement patterns.
Deployment:
Regulatory differentiation separates sovereign data requirements from elastic compute economics. Air-gapped installations dominate defense and classified intelligence workflows. Cloud configurations accelerate where GDPR adequacy decisions and cross-border data frameworks permit.
- On-Premises:Hardware-resident deployments maintain complete data sovereignty with dedicated GPU clusters for graph neural network inference. Bundesdatenschutzgesetz enforcement in Frankfurt and Munich sustains procurement pull from German automotive manufacturers and state banks.
- Cloud:Elastic provisioning through hyperscale providers collapses capital requirements for pilot programs. Singaporean fintechs and Bangalore digital lenders favor consumption-based pricing that scales with entity resolution throughput.
- Hybrid Cloud:Federated architectures partition sensitive relationship data on-premises while pushing compute-intensive traversal to public infrastructure. Swiss pharmaceutical manufacturers deploy this model to satisfy Swissmedic audit requirements without sacrificing query performance.
- Edge Computing:Embedded graph engines on manufacturing equipment enable real-time anomaly detection without cloud latency. Industrial deployments in Stuttgart and Toyota City cluster around predictive maintenance pipelines.
On-Premises handles the majority of throughput; Cloud is the fastest mover on share.
Solution:
Cost tier differentiation separates commodity data plumbing from high-margin reasoning layers. Enterprise buyers consolidate spending around outcome-guaranteed professional services.
- Semantic Search:Natural language interfaces traverse billions of entities to surface precise relationship paths. Legal research platforms in London and New York command premium subscriptions for case law precedent mapping.
- Entity Resolution:Probabilistic matching algorithms unify fragmented identity records across acquisition boundaries. Telecommunications carriers in Paris and Madrid deploy this layer to reduce subscriber churn prediction latency.
- Data Integration:ETL pipelines from relational warehouses to property graph schemas require extensive custom ontology mapping. Implementation timelines extend 8-14 months for complex financial services migrations.
- Relationship Mapping:Visual exploration tools expose hidden connection patterns in anti-money laundering investigations. Compliance teams at Singaporean private banks prioritize this capability for suspicious transaction network analysis.
- Metadata Management:Automated lineage tracking satisfies EU AI Act provenance mandates for high-risk automated decisions. German medical device manufacturers rebuild clinical decision support architectures around this foundation.
Semantic Search captures the deepest recurring revenue pools; Entity Resolution is climbing the fastest on enterprise deployment velocity.
Use Case:
Application maturity separates proven ROI categories from emerging experimental deployments. Regulated industries anchor procurement in audit-ready workflows.
- Fraud Detection:Real-time graph traversal flags anomalous transaction patterns across multi-hop relationship networks. State-owned banks in Shanghai and Beijing accelerate procurement to satisfy GB standards for algorithmic transparency.
- Compliance Monitoring:Automated ontology enforcement tracks regulatory rule changes against enterprise data models. EMA submission requirements drive pharmaceutical manufacturers toward auditable knowledge graph trails.
- Customer 360:Unified entity profiles consolidate interaction history across product silos. Retail banking divisions in Mumbai deploy this layer for RBI-mandated digital lending infrastructure.
- Predictive Maintenance:Equipment sensor data feeds graph models that predict failure cascades before they propagate. Industrial deployments cluster around Stuttgart automotive suppliers and Japanese precision manufacturers.
- Risk Management:Counterparty exposure calculations traverse complex ownership networks for concentration limit enforcement. Basel III compliance sustains demand from London and Zurich headquarters.
Fraud Detection handles the majority of throughput; Compliance Monitoring is expanding most quickly on regulatory mandate density.
End User:
Customer type concentration separates high-volume standardized deployments from bespoke engineered solutions. Procurement authority varies sharply across organizational maturity.
- Financial Institutions:Universal banks and insurers deploy knowledge graphs for credit risk, AML, and Solvency II reporting. Frankfurt and Paris institutions prioritize EU AI Act explainability infrastructure.
- Government Agencies:Defense and intelligence services require air-gapped deployments with classified security clearances. Pentagon and GCHQ procurement sustains premium on-premises margins.
- Telecommunications:Carrier networks unify subscriber identity across fragmented billing and service systems. Churn prediction latency reductions drive Singapore and Madrid deployment decisions.
- Manufacturing Units:Industrial equipment producers embed graph reasoning in quality control and supply chain traceability. Stuttgart and Toyota City clusters concentrate around automotive and precision engineering.
- Retail Chains:Customer journey mapping and inventory optimization leverage relationship data across channel boundaries. Deployment velocity lags financial services by 18-24 months.
Financial Institutions handle the majority of throughput; Government Agencies are gaining share fastest on classified environment premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net knowledge graph service exports flow toward the United States, Germany, and China as these markets import specialized ontology engineering talent while exporting platform technology licenses. Import dependency concentrates in smaller European markets and Southeast Asian financial hubs lacking domestic graph database vendors.
United States
Defense and intelligence procurement sustains premium on-premises deployments at Pentagon and CIA-adjacent facilities. FDA guidance on AI-enabled clinical decision support tightens auditability requirements for pharmaceutical manufacturers rebuilding clinical data architectures. Boston and Seattle clusters concentrate around healthcare knowledge graph startups serving NIH-funded research consortia.
Germany
Automotive manufacturers in Stuttgart and Munich deploy graph-native systems for supply chain traceability and predictive maintenance pipelines. Bundesdatenschutzgesetz enforcement fragments cloud deployment architectures, sustaining demand for sovereign data infrastructure at Commerzbank and Deutsche Börse. Frankfurt's financial district anchors EU AI Act compliance spending for explainable credit decision systems.
China
State-owned banks in Shanghai and Beijing accelerate semantic search procurement to satisfy GB standards for algorithmic transparency in consumer lending. MIIT industrial internet initiatives embed knowledge graphs in smart manufacturing pilots at Sinopec and Baowu Steel. Shenzhen's technology corridor concentrates vector-graph hybrid development for intelligent customer service platforms.
United Kingdom
GCHQ and Ministry of Defence procurement sustains air-gapped deployment specialists with classified security clearances. FCA regulatory sandboxes test knowledge graph-based anti-money laundering systems at London-based fintechs. The Cambridge-Oxford arc concentrates academic research commercialization around biomedical knowledge graphs for drug repurposing.
India
RBI-mandated digital lending infrastructure creates greenfield demand for credit risk engines at HDFC Bank and ICICI in Mumbai. CDSCO's tightening data integrity requirements push pharmaceutical manufacturers in Hyderabad toward auditable knowledge graph trails for export compliance. Bangalore's technology parks host offshore ontology engineering centers serving North American and European financial institutions.
AI-Ready Enterprise Knowledge Graph Market Competitive Landscape
Listed leaders compete with private specialists across graph database engines and ontology management tooling. The vendor landscape organizes into three tiers: hyperscale cloud providers with native graph services, dedicated graph database vendors with vertical specializations, and boutique ontology engineering consultancies. Strategic archetypes include property graph specialists dominating financial services, RDF-native vendors anchoring government intelligence workflows, and cloud-agnostic virtualization platforms. Competitive moves concentrate on M&A for talent acquisition and strategic partnerships with foundation model providers.
Within the dedicated graph database tier, Neo4j exemplifies the property graph archetype through native storage architectures, while Stardog occupies a position in knowledge graph virtualization for federated enterprise queries. Ontotext anchors the semantic technology segment with RDF-based reasoning stacks. These three vendors represent distinct technical philosophies—native graph storage, query federation without migration, and formal semantic reasoning—that collectively shape procurement patterns across regulated industries.
| Leading Market Players |
|---|
| Neo4j |
| Stardog |
| Ontotext |
| Oracle |
| Amazon Web Services |
| Microsoft |
| IBM |
| Altair |
| Progress Software |
| Others |
Pricing and Supply Chain Analysis
Outcome-based ontology engineering contracts lock in multi-year supply access for enterprise buyers while anchoring price visibility through guaranteed query performance SLAs. This structure concentrates procurement power among Frankfurt financial institutions and Pentagon-adjacent defense contractors who bundle software licenses with recurring professional services.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structures across premium, standard, and economy levels in Stuttgart and Toyota City manufacturing clusters. Price differentiation hinges on ACID compliance certification and GPU cluster provisioning for graph neural network inference. Cost compression in cloud-native tiers is intensifying because hyperscale providers bundle native graph services with compute commitments. Mid-market digital lenders in Bangalore exhibit highest price sensitivity; classified government agencies in Washington and London show least.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for GPU hardware destined to Singaporean and Bangalore data centers. Graph database engine development concentrates in the United States, Germany, and China; ontology engineering talent feeds from India and Eastern Europe. Supply chains draw from specialized semiconductor foundries, enterprise storage arrays, and formal logic training pipelines. Single-source vulnerability concentrates in NVIDIA GPU allocations for graph neural network training. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales forces with classified security clearances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI-Ready Enterprise Knowledge Graph Market represents a high-growth disruption as foundation model providers integrate native graph retrieval capabilities that threaten to commoditize standalone tooling layers. EU AI Act compliance mandates and FDA auditability guidance create irreversible procurement pull for explainable data architectures.
For Market Incumbents: Secure vertical specialization in regulated industries through EU AI Act certification investments and air-gapped deployment capabilities for Pentagon and GCHQ procurement. Deepen upstream control over ontology engineering talent pipelines in Bangalore and Hyderabad to defend margin position against foundation model encroachment. Anchor channel control through outcome-guaranteed professional services contracts that lock in recurring revenue.
For New Entrants and Emerging Players: Managed ontology engineering services for mid-market BFSI in Mumbai represent the most penetrable white-space where incumbents under-serve. Target RBI-mandated digital lending infrastructure with consumption-based pricing that scales with entity resolution throughput. Pursue hybrid cloud federated architectures for Swiss pharmaceutical manufacturers seeking Swissmedic compliance without query performance sacrifice.
For Investors and Strategic Acquirers: Boutique ontology engineering consultancies with formal logic expertise and domain specialization in financial services or government intelligence offer prime acquisition targets. Long-term viability over the coming decade rests on differentiation from foundation model providers' native graph capabilities. Watch for FDA enforcement patterns on AI-enabled clinical decision support as inflection indicator for healthcare knowledge graph demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Specialization in Regulated Industries | EU AI Act compliance mandates in Frankfurt and Paris create immediate procurement pull for certified vendors. |
| Hybrid Cloud Federated Architecture Development | Swiss pharmaceutical manufacturers satisfy Swissmedic audit requirements without sacrificing query performance. |
| Outcome-Based Ontology Engineering Contracts | US healthcare systems replace legacy master data management with managed knowledge graph subscriptions. |
| Native Graph-Vector Database Convergence | London and Singapore financial services firms pilot unified query interfaces collapsing architectural boundaries. |
| Air-Gapped Deployment Capability Investment | Pentagon and GCHQ procurement sustains premium margins in classified intelligence environments. |
Research Methodology
A spread of perspectives from chief data officers, ontology engineers, regulatory compliance leads, and hyperscale cloud procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU AI Act implementation guidance, FDA enforcement letters, and hyperscaler capex disclosures. Bottom-up deployment counts triangulated against top-down enterprise IT spending estimates.
Segmentation dimensions modeled span deployment topology, solution layer, regulatory use case, and end-user vertical across the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves and compliance-mandate timing. Forecast inputs incorporated ontology engineering talent supply constraints, SPARQL query performance benchmarks, and data residency requirement fragmentation.
Forecasts assume regulatory continuity in EU AI Act implementation, FDA AI-enabled clinical decision support guidance, and China's GB standards for algorithmic transparency; material policy shifts would require re-modeling. Technology disruption risk from foundation model providers' native graph capabilities represents primary forecast sensitivity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Conversational AI Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Voice User Interface Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Neural Network Market