
 Voice User Interface Market | 2026-2036
Voice User Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Voice User Interface Market Analysis
Automotive infotainment is rebalancing the Voice User Interface Market as OEMs embed conversational AI deeper into vehicle cabins. Google Cloud Speech-to-Text leverages its multilingual model pipeline to anchor automotive contracts across European and Asian manufacturing hubs. Nuance Communications sustains its clinical documentation dominance in healthcare through specialized medical vocabularies and ambient clinical intelligence. Amazon Web Services Transcribe competes aggressively on cloud scale, extending transcription APIs into call-center voice analytics at enterprise volume tiers.
A voice user interface constitutes a human-computer interaction modality that converts spoken audio input into machine-executable commands through acoustic modeling, language modeling, and dialog management pipelines operating at sub-200-millisecond latency thresholds for real-time responsiveness. Its primary commercial purpose is to eliminate manual input friction in hands-busy or eyes-busy environments across vehicles, medical suites, and connected home devices. Natural language processing segments are capturing disproportionate R&D investment as transformer architectures improve intent disambiguation accuracy. Cloud-based deployment leads current revenue volumes, though edge computing configurations are expanding fastest in automotive and smart home applications where latency constraints and data sovereignty requirements intensify. Machine learning subsystems within voice synthesis are maturing toward indistinguishable human voice replication, concentrating margin pools in enterprise customer service and accessibility tools.
The Federal Communications Commission governs spectrum allocation for voice-enabled IoT devices in the United States, while the EU AI Act imposes conformity obligations on biometric voiceprint systems entering European markets. The International Organization for Standardization publishes IEC 63000 and related frameworks that shape interoperability testing for speech recognition hardware-software stacks. Stakeholders must monitor whether national implementations of AI risk frameworks fragment certification pathways or converge toward mutual recognition, as this divergence will determine which voice AI architectures achieve cross-border deployment economics.
Market Dynamics
Automotive OEMs are embedding conversational AI into cabin systems at scale, pulling developer resources from smartphone and smart home applications toward vehicle-grade acoustic environments with stricter latency and safety requirements.
Growth Catalysts
- EU AI Act compliance deadlines:Biometric voiceprint systems face mandatory conformity obligations, redirecting vendor R&D toward auditable architectures and creating first-mover advantages for certified suppliers.
- Edge computing maturation:Automotive and smart home applications demand sub-200-millisecond response times, driving silicon investment into dedicated neural processing units for on-device inference.
- Stuttgart-Munich corridor concentration:Germany's overlapping automotive headquarters and voice AI research clusters generate talent density and pilot-to-production pipelines unmatched elsewhere.
Market Restraints
- GPU and NPU supply concentration:Taiwan-based foundries control advanced node production for voice AI accelerators, exposing automotive programs to allocation risk during semiconductor demand spikes.
- Training data licensing friction:Proprietary speech corpora for medical and legal domains carry per-hour licensing costs that compress margins for specialized vocabulary models.
- Acoustic environment variability:Cabin noise profiles differ across vehicle platforms, forcing redundant engineering cycles rather than transferable model architectures.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives attract voice hardware assembly, creating export capacity for cost-sensitive smart speaker and wearable segments.
- Healthcare ambient intelligence:Clinical documentation workflows remain underpenetrated by hands-free interfaces, offering expansion paths beyond automotive saturation.
- Transformer-quantum hybrid architectures:Convergence of large language models with on-device compression techniques enables premium features without cloud dependency.
Industry Challenges
- Conversational AI talent scarcity:Dialog management and intent disambiguation specialists command compensation premiums that strain mid-tier vendor hiring.
- ISO/IEC 27001 certification timelines:Enterprise buyers mandate information security management system audits, extending sales cycles by six to nine months.
- Legacy infotainment integration:Middleware compatibility with decade-old vehicle bus protocols consumes engineering bandwidth without differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice User Interface Market |
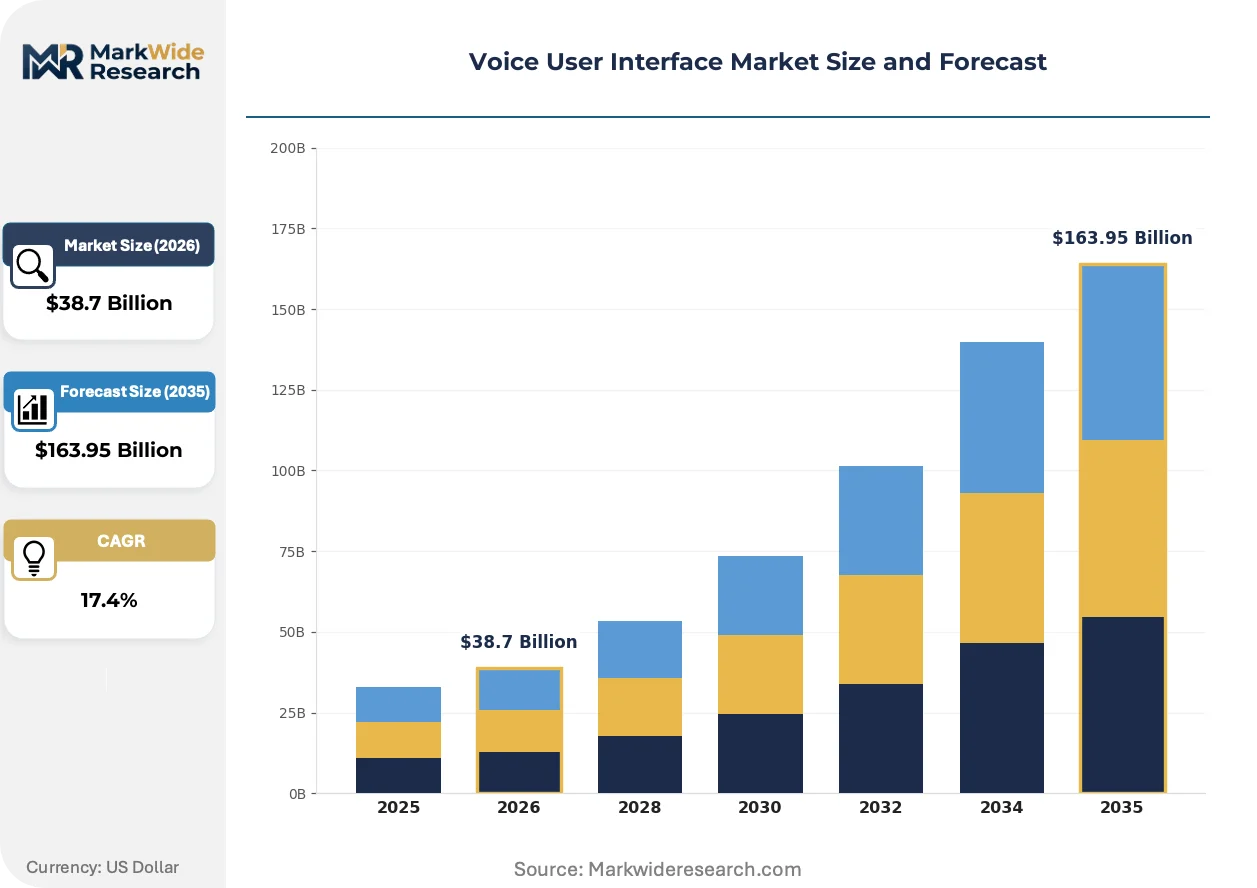
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $163.95 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Recognition, Natural Language Processing, Machine Learning, Voice Synthesis End User: Consumer Electronics, Automotive, Healthcare, Smart Home Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Virtual Assistants, Interactive Voice Response, Voice Search, Voice Command |
| Companies Covered | IBM Watson Speech, Speechmatics, Google Cloud Speech-to-Text, Vapi, Parloa, Amazon Web Services Transcribe, Nuance Communications, Retell AI, Microsoft Azure Speech Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice User Interface Market Emerging Trajectories
Transformer-based natural language processing architectures are compressing intent recognition latency while expanding multilingual coverage, forcing incumbent vendors to retrain or replace legacy acoustic models.
On-device neural processing is overtaking cloud-dependent inference in automotive cabins. OEMs in Germany and Japan deploy edge-first voice stacks to satisfy data sovereignty requirements and eliminate connectivity dead zones. This shift compresses infrastructure spend for tier-one suppliers while raising the bar for silicon thermal design in sealed dashboard enclosures.
The EU AI Act's risk classification framework imposes documentation burdens on biometric identification systems entering European markets. Vendors must maintain technical files and quality management systems subject to third-party assessment. Healthcare and automotive applications face the strictest conformity routes, with some suppliers bifurcating product lines to isolate high-risk from limited-risk feature sets.
Enterprise procurement of voice analytics has pivoted toward usage-based API metering rather than perpetual licensing. Call-center operators in the United States and United Kingdom now negotiate transcription volumes against committed spend tiers, unbundling storage and analytics modules previously sold as suites. This pricing transparency favors cloud-scale providers with marginal cost advantages on inference compute.
Voice User Interface Market Segmentation
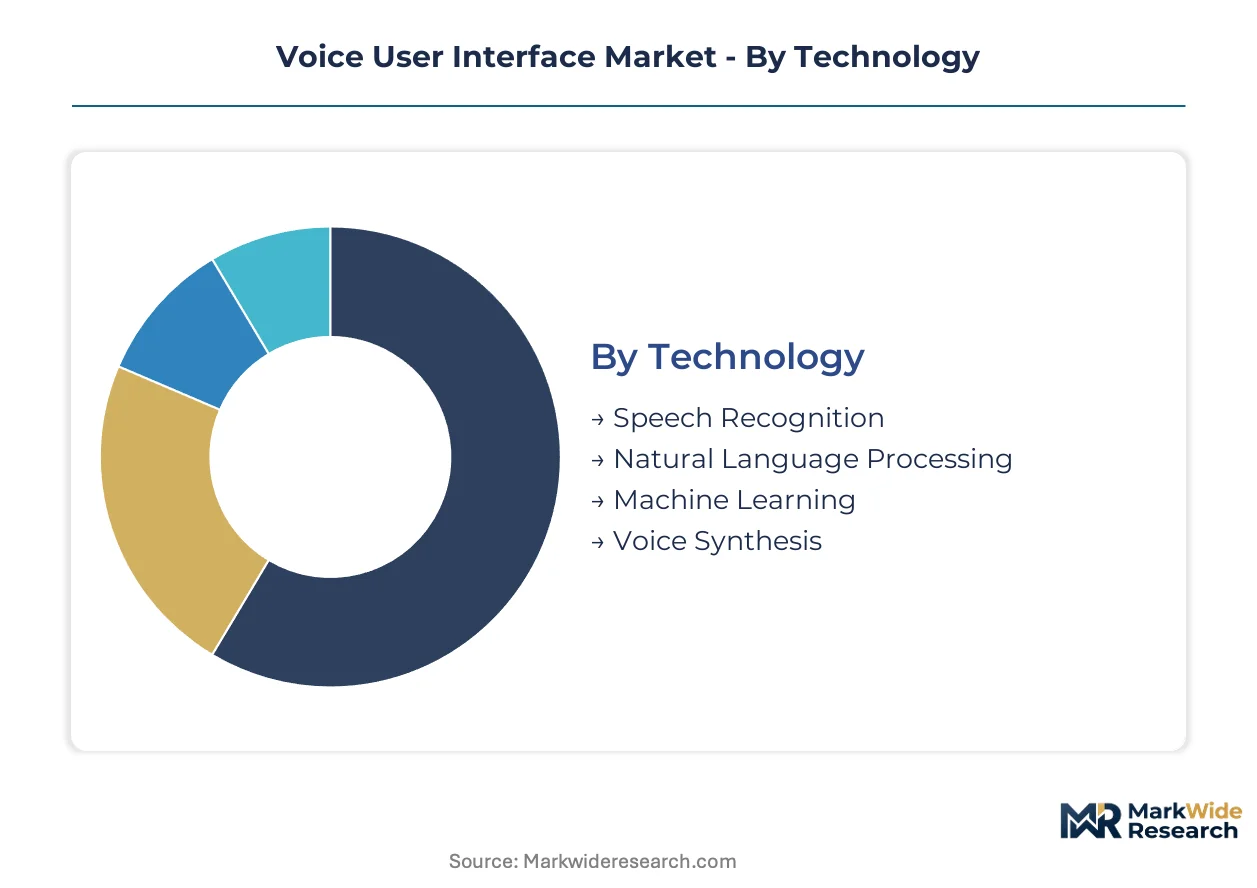
Technology differentiation in voice interfaces determines latency budgets, privacy architectures, and deployment economics. Buyers prioritize acoustic robustness in automotive cabins, medical accuracy in clinical settings, and cost efficiency in consumer electronics. Segmentation reveals where engineering investment concentrates versus where margin compression threatens.
Technology:
Technical sophistication separates premium deployments from commodity implementations across automotive, healthcare, and consumer verticals.
- Speech Recognition:Acoustic modeling pipelines convert audio waveforms into phonetic sequences through deep neural networks trained on multilingual corpora. Automotive OEMs in Germany demand sub-200-millisecond latency for cabin commands, forcing edge-optimized architectures over cloud-dependent alternatives.
- Natural Language Processing:Transformer architectures disambiguate user intent through contextual embedding layers that capture semantic relationships beyond keyword matching. Healthcare documentation workflows in the United States drive specialized medical vocabulary training to reduce clinical transcription error rates.
- Machine Learning:Continuous model refinement through federated learning enables personalization without centralizing sensitive voiceprints. Smart home device manufacturers leverage on-device training to adapt to household-specific speech patterns.
- Voice Synthesis:Neural vocoders generate prosodically natural output through adversarial training against human speech samples. Enterprise customer service platforms deploy indistinguishable synthetic voices to reduce live agent costs.
Volume sits with speech recognition; growth tilts toward natural language processing.
End User:
Application environments dictate acoustic constraints, safety requirements, and integration complexity.
- Consumer Electronics:Smartphone and wearable manufacturers prioritize battery-efficient inference through quantized neural networks. Cost pressure from Asian assembly hubs compresses BOM allowances for dedicated voice silicon.
- Automotive:Cabin noise cancellation and multi-zone microphone arrays enable hands-free control during highway operation. Stuttgart and Munich engineering centers concentrate R&D for EU AI Act-compliant biometric systems.
- Healthcare:Ambient clinical intelligence captures physician-patient dialogue without keyboard interruption. HIPAA obligations in the United States mandate encrypted local processing for protected health information.
- Smart Home:Hub-and-spoke architectures coordinate distributed microphones across residential floor plans. Privacy-conscious buyers in Germany favor edge-only processing that eliminates cloud voiceprint storage.
Consumer electronics dominates shipment volumes; healthcare claims the steepest expansion trajectory.
Deployment:
Infrastructure location determines data sovereignty compliance, connectivity dependency, and operating cost structure.
- Cloud-Based:Centralized GPU clusters enable large-model inference for multilingual virtual assistants. AWS, Google Cloud, and Azure compete on transcription API pricing tiers.
- On-Premises:Air-gapped installations satisfy financial services and defense sector security mandates. Capital expenditure requirements limit adoption to enterprise-scale buyers.
- Hybrid:Sensitive preprocessing occurs locally while complex intent resolution routes to cloud infrastructure. Automotive programs use this architecture to balance latency with computational depth.
- Edge Computing:Dedicated neural processing units within sealed dashboard enclosures eliminate connectivity dead zones. Japanese OEMs lead thermal design innovation for high-temperature automotive environments.
Cloud-based deployment holds current revenue concentration; edge computing gains share fastest.
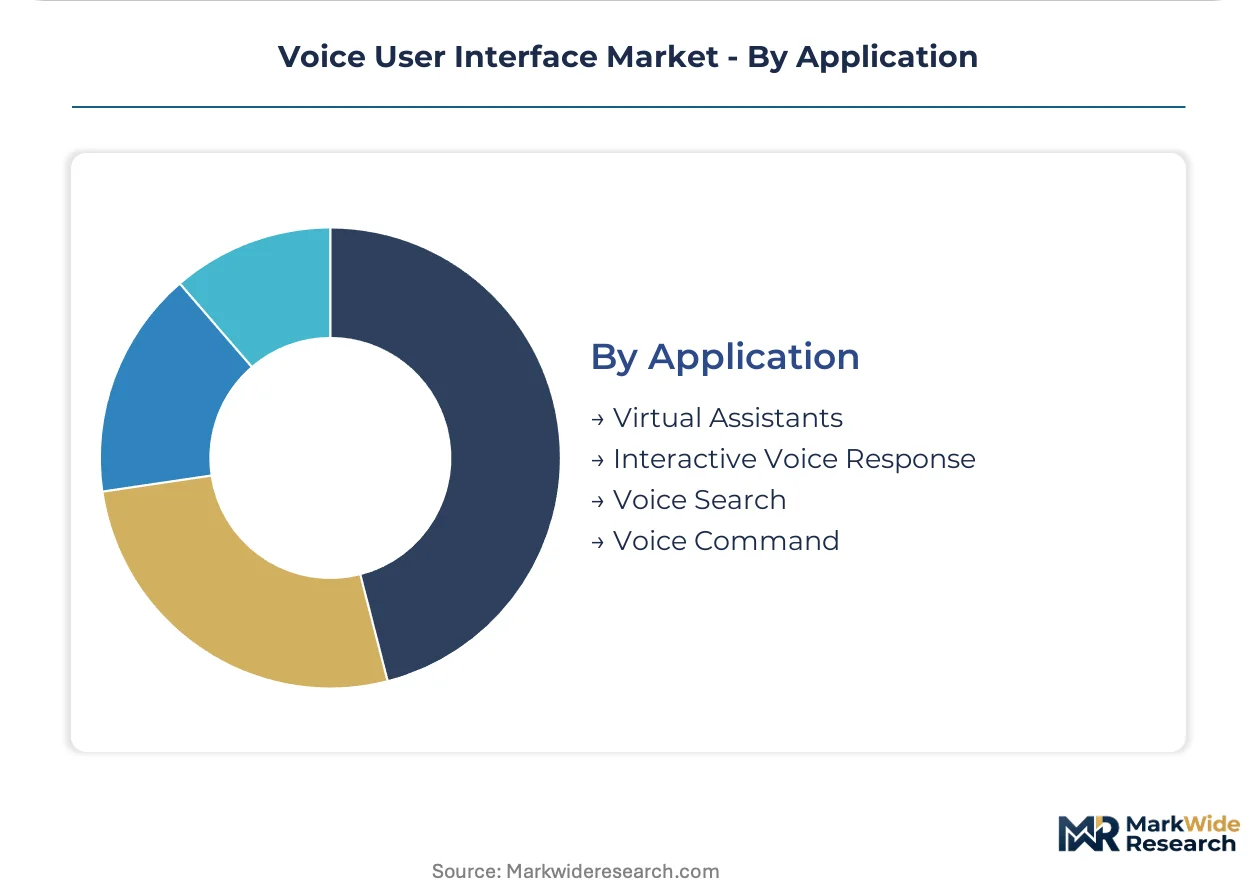
Application:
Use case specificity shapes dialog management complexity and integration touchpoints.
- Virtual Assistants:General-purpose conversational agents handle open-domain queries through retrieval-augmented generation. Smart speaker saturation in the United States and United Kingdom shifts growth toward automotive and industrial variants.
- Interactive Voice Response:Structured menu navigation reduces live agent utilization in banking and telecommunications call centers. Usage-based API metering has displaced perpetual licensing in enterprise procurement.
- Voice Search:Hands-free information retrieval competes with visual interfaces for mobile query share. Local business discovery drives monetization through sponsored placement.
- Voice Command:Constrained vocabulary control enables deterministic execution in safety-critical vehicle and manufacturing environments. ISO 26262 functional safety requirements govern automotive implementations.
Interactive voice response captures enterprise spend; virtual assistants expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Munich anchor Europe's densest voice AI corridor, where automotive OEM headquarters overlap with specialized research clusters. Germany's concentration of engineering talent and manufacturing integration creates pilot-to-production pipelines unmatched elsewhere.
Germany
Automotive infotainment systems pull significant developer investment as Mercedes-Benz, BMW, and Volkswagen embed conversational AI into vehicle cabins. The EU AI Act imposes conformity obligations on biometric voiceprint systems, redirecting vendor compliance roadmaps toward auditable architectures. Stuttgart and Munich engineering centers concentrate R&D for EU AI Act-compliant biometric systems.
United States
Enterprise call-center voice analytics and healthcare clinical documentation drive cloud-scale transcription demand. The Federal Communications Commission governs spectrum allocation for voice-enabled IoT devices, shaping deployment parameters for connected home and wearable segments. Seattle and San Francisco Bay Area clusters host hyperscaler speech API development and ambient clinical intelligence platforms.
Japan
Automotive OEMs deploy edge-first voice stacks to satisfy data sovereignty requirements and eliminate connectivity dead zones. METI standards coordination shapes interoperability testing for speech recognition hardware-software stacks. Toyota City and Nagoya engineering centers lead thermal design innovation for high-temperature automotive environments.
India
Cost-sensitive smart speaker and wearable manufacturing attracts assembly investment under the PLI scheme for electronics. TRAI regulations on data localization influence cloud-vs-edge deployment decisions for domestic voice service providers. Bangalore and Hyderabad clusters generate software engineering talent for multilingual model development.
China
Smart home hub-and-spoke architectures coordinate distributed microphones across residential floor plans at manufacturing scale. MIIT standards and GB certification requirements govern speech recognition hardware-software stack interoperability. Shenzhen and Beijing clusters concentrate consumer electronics voice silicon integration and virtual assistant platform development.
Voice User Interface Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscaler cloud platforms capturing enterprise transcription volumes while vertical-focused vendors defend healthcare and automotive niches. The vendor landscape organizes into three strategic archetypes: cloud-scale API providers with marginal cost advantages, specialized medical and automotive application vendors with domain-specific vocabularies, and emerging conversational AI platforms targeting call-center automation. Competitive moves concentrate on M&A for talent acquisition in dialog management and federated learning capabilities, plus strategic partnerships between tier-one automotive suppliers and edge silicon vendors.
Within the cloud-scale tier, Google Cloud Speech-to-Text and Amazon Web Services Transcribe exemplify the infrastructure-heavy positioning that dominates enterprise procurement through usage-based API metering. Nuance Communications occupies a specialized position representing vertical integration into clinical documentation workflows through ambient intelligence architectures. Microsoft Azure Speech Services anchors the platform-agnostic alternative for hybrid cloud-edge deployments across regulated industries.
| Leading Market Players |
|---|
| IBM Watson Speech |
| Speechmatics |
| Google Cloud Speech-to-Text |
| Vapi |
| Parloa |
| Amazon Web Services Transcribe |
| Nuance Communications |
| Retell AI |
| Microsoft Azure Speech Services |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up voice AI specialists have consolidated fragmented speech recognition vendors across Europe and North America, concentrating ownership patterns that tighten supply discipline while enabling coordinated pricing power against automotive OEM procurement teams. This ownership concentration interacts with Taiwan-based foundry allocation constraints to sustain premium pricing for edge-optimized neural processing units despite commoditization pressure in cloud transcription APIs.
Pricing Analysis
Short lead-time premiums command substantial markups in automotive voice stack procurement, with Stuttgart-based OEMs paying significant uplifts for guaranteed NPU allocation during semiconductor demand spikes. The dominant pricing structure stratifies across premium, standard, and economy tiers tied to ISO 26262 functional safety certification levels and acoustic robustness guarantees. Price differentiation rests on medical vocabulary licensing costs and edge inference thermal performance specifications. Margins are tightening due to GPU allocation friction from Taiwan foundry concentration. Healthcare documentation buyers exhibit highest price sensitivity, while German automotive OEMs prioritize latency guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundries controlling advanced node production for voice AI accelerators, exposing automotive programs to allocation risk during semiconductor demand spikes. Manufacturing concentrates in Taiwan, South Korea, and China for neural processing units, with assembly shifting toward India under PLI scheme incentives. Raw material dependencies include silicon wafers, high-bandwidth memory modules, and specialized microphone MEMS sensors. Tariff exposure on Chinese-manufactured smart speaker components threatens cost structures for consumer electronics tiers. Distribution runs through tier-one automotive suppliers and hyperscaler cloud marketplaces for enterprise API access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neural processing unit foundry capacity constraints prop pricing power for certified automotive voice stacks, creating supply-constrained conditions that favor incumbent margin defense over volume expansion.
For Market Incumbents: Acquire federated learning and dialog management specialist teams to consolidate scarce conversational AI talent pools before compensation premiums erode R&D budgets. Defend automotive positions through backward integration into edge silicon thermal design partnerships with Japanese OEM engineering centers. Counter AWS and Google Cloud API pricing aggression by embedding specialized medical vocabularies and ambient clinical intelligence workflows that resist commoditization. For New Entrants and Emerging Players: Capture healthcare ambient intelligence documentation workflows in the United States, where HIPAA-encrypted local processing requirements create compliance moats against hyperscaler cloud-only offerings. Penetrate India's cost-sensitive smart speaker assembly segment through PLI scheme manufacturing partnerships that generate export capacity for wearable voice interfaces. Lead with multilingual model development targeting Indic language coverage gaps in incumbent portfolios. For Investors and Strategic Acquirers: First EU AI Act conformity certifications for biometric voiceprint systems are the leading indicator that vendor compliance roadmaps have achieved auditable architectures with sustained pricing power. Frame long-term viability around 5-10 year regulatory fragmentation windows where certified suppliers command procurement preference. Target acquisition profiles emphasizing dialog management IP and automotive thermal design capabilities rather than generic transcription scale.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-First Voice Stack Development | Automotive OEMs in Germany deploy on-device inference to satisfy EU AI Act data sovereignty requirements. |
| Specialized Medical Vocabulary Licensing | Nuance Communications defends clinical documentation margins through proprietary ambient intelligence training corpora. |
| Neural Processing Unit Thermal Design Partnership | Toyota City engineering centers lead innovation for high-temperature automotive dashboard enclosures. |
| Multilingual Model Pipeline Expansion | Google Cloud Speech-to-Text anchors European and Asian manufacturing contracts through language coverage depth. |
| Federated Learning Capability Acquisition | Smart home manufacturers adapt to household-specific speech patterns without centralizing sensitive voiceprints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across automotive platform engineers, healthcare biomedical informaticists, cloud procurement officers, tier-one supplier executives, and smart home device manufacturers. Secondary validation drew from EU AI Act implementation documents, FCC spectrum allocation records, ISO/IEC 27001 certification databases, and hyperscaler capex disclosures. Bottom-up shipment modeling and top-down spending pattern triangulation converged on segment-level estimates.
Granularity-level modeling deployed technology-by-deployment matrix analysis across speech recognition, natural language processing, and voice synthesis segments, with end-user splits for automotive, healthcare, consumer electronics, and smart home verticals. Geographic clustering captured Germany's Stuttgart-Munich corridor concentration, US enterprise call-center demand, and Japan's edge-first automotive adoption. CAGRs were derived from fitted growth curves against historical penetration rates and regulatory deadline impacts. Forecast inputs included EU AI Act compliance timeline assumptions and semiconductor foundry capacity expansion announcements.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement variance, Taiwan foundry allocation disruptions, and conversational AI talent scarcity dynamics. Forecasts reflect documented assumptions regarding regulatory implementation pacing and technology substitution thresholds. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
AI Mirror Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Cognitive Computing Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
Saudi Arabia Big Data and Artificial Intelligence Market