
 Emotion Detection and Recognition (EDR) Market | 2026-2036
Emotion Detection and Recognition (EDR) Market Size, Share, and Industry Trends Forecast 2026-2036
Emotion Detection and Recognition (EDR) Market Foresight
The EU AI Act is restructuring procurement criteria for emotion recognition systems across European healthcare and public sectors, forcing vendors to demonstrate algorithmic transparency and human-in-the-loop safeguards. Microsoft Corporation leverages its Azure cloud infrastructure to anchor enterprise deployments of facial and voice analysis tools. Google LLC competes through specialized machine learning APIs that differentiate on multimodal emotion parsing. IBM Corporation sustains R&D intensity in neurological measurement protocols for clinical applications.
Emotion Detection and Recognition (EDR) encompasses biometric technologies that capture, process, and classify human affective states through facial micro-expressions, vocal prosody, gestural kinematics, and neurophysiological signals such as electroencephalography and galvanic skin response, serving industrial purposes from real-time customer experience optimization to clinical mood disorder screening. Facial recognition technology dominates current revenue pools due to mature computer vision architectures and low hardware barriers, while voice analysis grows fastest as natural language processing architectures improve paralinguistic feature extraction. Gesture recognition occupies narrower margin pools constrained by sensor cost and calibration complexity, though immersive gaming and virtual reality applications expand its addressable base.
The U.S. Food and Drug Administration scrutinizes EDR tools marketed for diagnostic purposes, requiring clinical validation pathways that extend time-to-market for healthcare applications. China's SAMR and MIIT enforce algorithmic recommendation and data security provisions that shape how emotion data may be collected, stored, and transmitted across consumer platforms. ISO/IEC standards for biometric performance testing provide baseline interoperability benchmarks that regulators in Japan and South Korea reference in procurement specifications. Stakeholders must monitor divergence between risk-based regulatory frameworks in the European Union and sector-specific enforcement patterns in Asia-Pacific jurisdictions to align compliance investments with revenue exposure.
Market Dynamics
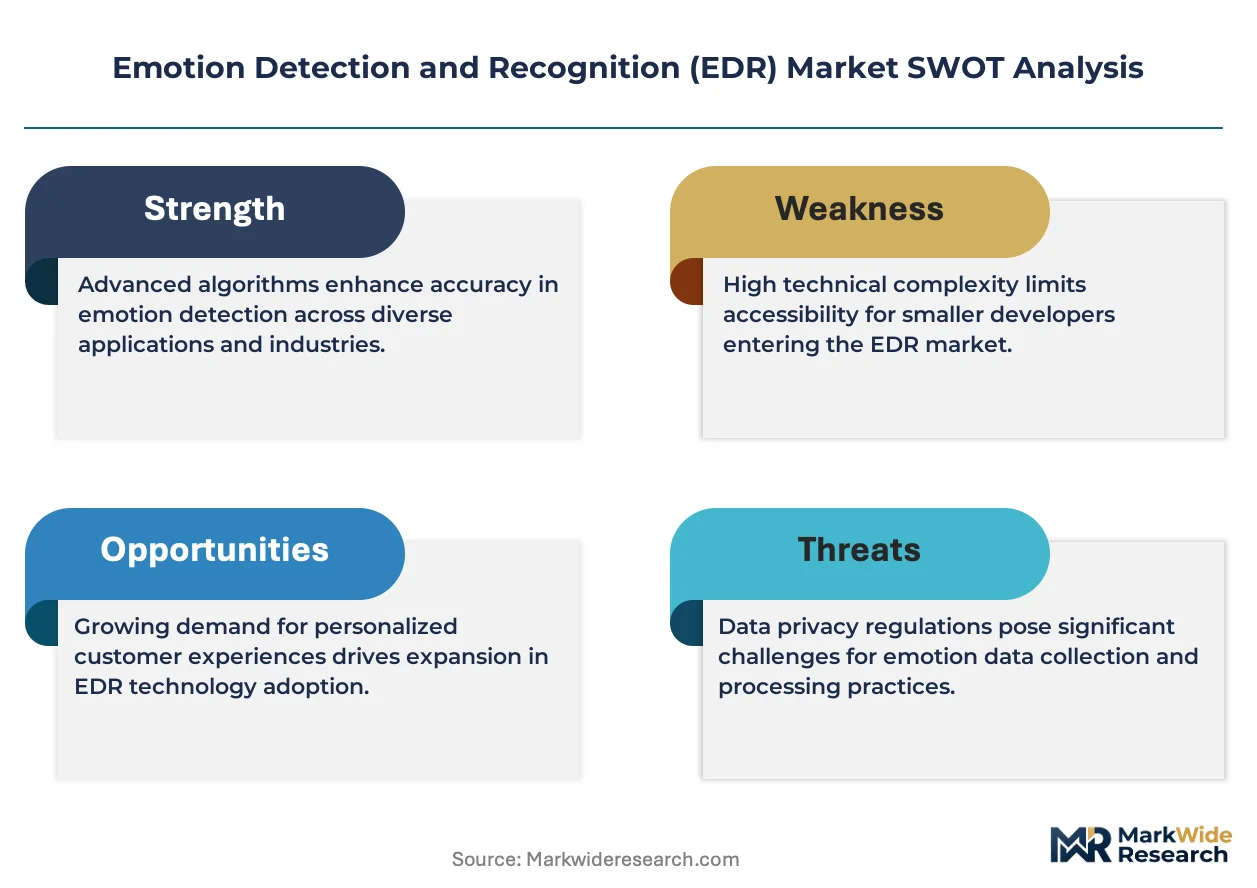
The EU AI Act's risk-classification framework is forcing algorithmic redesign across emotion recognition vendors, compelling transparency disclosures and human-in-the-loop architectures that reshape development costs and competitive positioning.
Growth Catalysts
- Healthcare digitization mandates:Patient monitoring systems in clinical settings drive institutional procurement of EDR platforms for mood disorder screening and real-time affective state tracking.
- Natural language processing advances:Paralinguistic feature extraction from vocal prosody enables voice-based emotion detection to capture expanding share of enterprise workforce analytics deployments.
- ISO/IEC biometric standards:Interoperability benchmarks referenced by Japanese and South Korean procurement specifications accelerate cross-border vendor certification and market access.
Market Restraints
- Clinical validation pathways:FDA scrutiny of diagnostic-purpose EDR tools extends time-to-market for healthcare applications, compressing returns on R&D investment cycles.
- Sensor cost concentration:Galvanic skin response and electroencephalography hardware dependencies create margin pressure for gesture and neurophysiological signal capture systems.
- Algorithmic transparency requirements:EU AI Act conformity obligations force proprietary model disclosure that erodes vendor differentiation and increases compliance overhead.
Strategic Opportunities
- Immersive gaming expansion:Virtual reality headset integration of kinematic gesture recognition opens addressable base beyond traditional enterprise and clinical verticals.
- Consumer platform regulation:China's SAMR algorithmic recommendation provisions create compliant-first vendor advantage for emotion data collection architectures meeting data security mandates.
- Multimodal parsing convergence:Fusion of facial micro-expression analysis with vocal prosody extraction enables higher-fidelity affective classification for premium-tier enterprise deployments.
Industry Challenges
- Neurophysiological signal calibration:Electroencephalography and galvanic skin response systems require specialized technical talent for sensor placement and baseline establishment, constraining deployment velocity.
- Legacy system integration:Enterprise workforce analytics platforms face friction embedding EDR modules into existing human capital management software architectures without API standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emotion Detection and Recognition (EDR) Market |
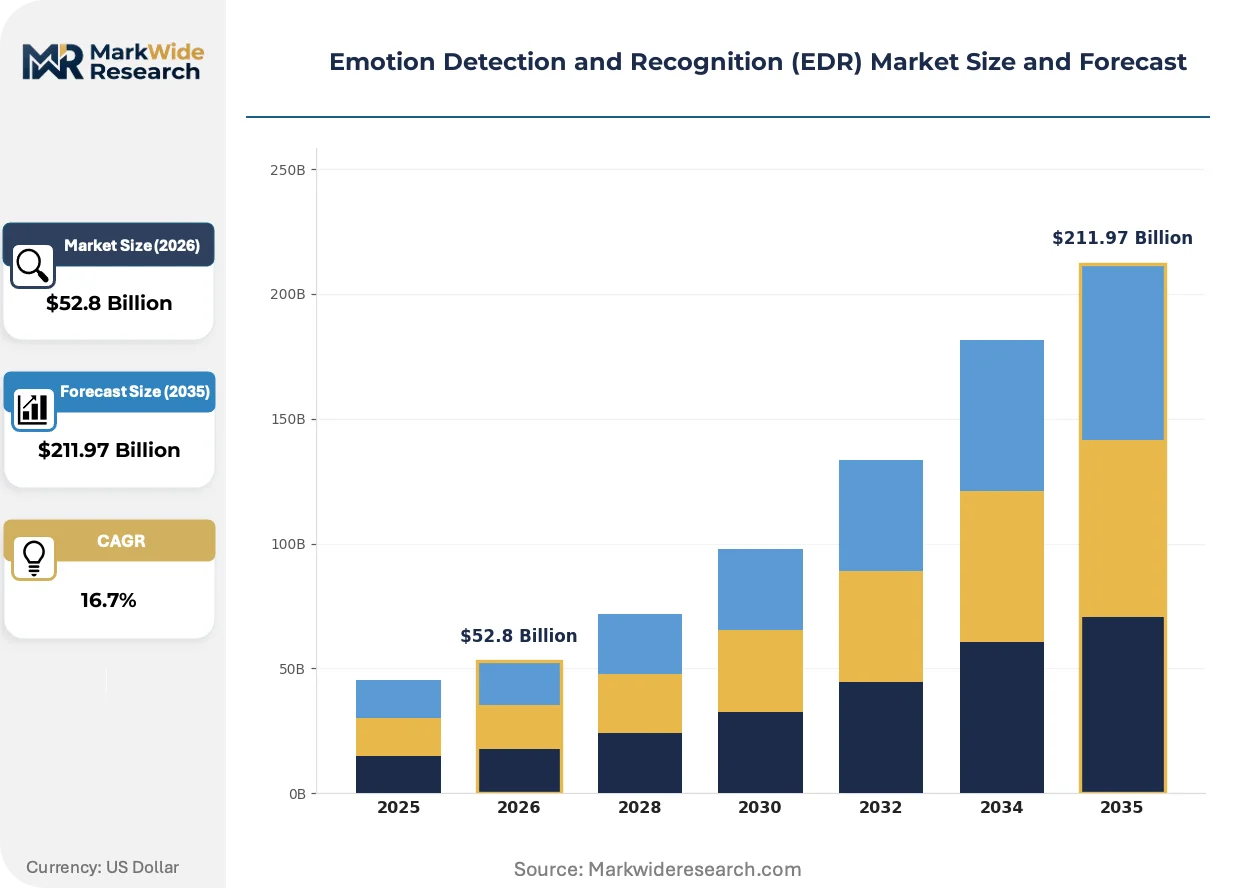
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $211.97 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Facial Recognition, Voice Analysis, Gesture Recognition, Neurological Measurement Application: Healthcare, Gaming, Marketing, Education End User: Enterprises, Consumers, Research Institutions, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Affectiva (Smart Eye), IBM Corporation, Microsoft Corporation, Google LLC, Apple Inc., Tobii AB, Realeyes, NEC Corporation, Noldus Information Technology BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emotion Detection and Recognition (EDR) Market Shifts & Advancements
Multimodal emotion parsing architectures are displacing single-signal systems across enterprise and clinical deployments, while regulatory fragmentation between risk-based and sector-specific frameworks forces vendors to maintain parallel compliance roadmaps.
Facial micro-expression analysis is converging with voice-based paralinguistic feature extraction to enable synchronous multimodal affective classification. Enterprise workforce analytics buyers in the United States are adopting these fused systems at accelerated pace. This convergence is compressing addressable margin for single-modality vendors while rewarding integrated platform providers with premium positioning.
The EU AI Act's high-risk system classification for emotion recognition in education and workplace settings imposes mandatory conformity assessments and human oversight requirements. Vendors must redesign algorithms for explainability and maintain technical documentation for market surveillance authorities. Healthcare and public sector procurement across Germany, France, and Italy now predicates vendor selection on demonstrated compliance with these transparency obligations.
Buyers are consolidating vendor relationships around full-stack EDR platforms rather than point-solution APIs, compressing switching flexibility. System integrators and value-added resellers are displacing direct sales channels for mid-market enterprise deployments. This concentration is most visible in United States workforce analytics, where human capital management suite vendors are embedding native emotion detection capabilities rather than licensing third-party tools.
Emotion Detection and Recognition (EDR) Market Segmentation
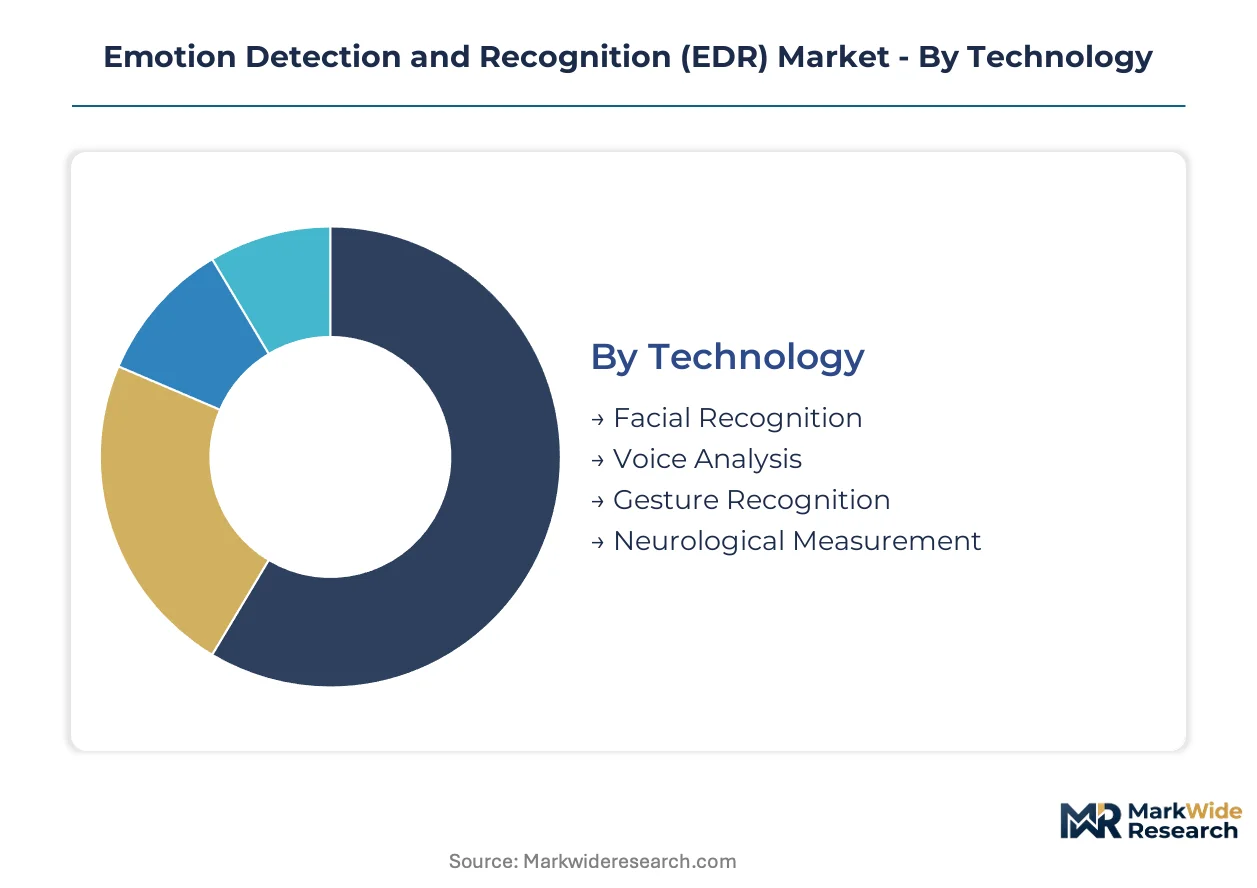
EDR vendors architect product portfolios around four intersecting dimensions. Technology choices determine hardware dependencies and margin structures. Application focus shapes regulatory exposure and customer acquisition costs.
Technology:
Supply concentration in computer vision components has concentrated vendor R&D spending on two modalities while constraining development velocity for sensor-heavy alternatives.
- Facial Recognition:Mature convolutional neural networks process micro-expressions and gaze vectors through standard RGB or depth cameras. Healthcare providers in the United States deploy these systems for patient mood screening, though FDA validation pathways extend commercialization timelines.
- Voice Analysis:Transformer architectures extract paralinguistic features—pitch variation, speech rate, jitter, shimmer—from audio streams without specialized hardware. Enterprise workforce analytics platforms in the United States integrate voice-based emotion detection for call center quality assurance, climbing the fastest as natural language processing capabilities advance.
- Gesture Recognition:Kinematic tracking via accelerometers, gyroscopes, and depth sensors captures body posture and hand movements for immersive applications.
- Neurological Measurement:Electroencephalography and galvanic skin response systems require medical-grade sensors and specialized calibration protocols.
Today's leader: Facial Recognition. Tomorrow's challenger: Voice Analysis.
Application:
End-use diversification determines pricing power and contract duration, with clinical deployments commanding premium terms despite longer sales cycles.
- Healthcare:Clinical mood disorder screening and real-time patient monitoring systems leverage multimodal fusion of facial, vocal, and neurophysiological signals. German hospitals and French mental health clinics now predicate procurement on EU AI Act conformity assessments, compressing addressable vendor pools.
- Gaming:Virtual reality headset integration of gesture and facial tracking enables adaptive gameplay mechanics based on player affective state. Japanese and South Korean studios drive hardware partnerships for immersive emotion-responsive environments.
- Marketing:Real-time customer experience optimization through sentiment analysis of facial reactions and vocal feedback.
- Education:Student engagement monitoring systems face heightened regulatory scrutiny under EU AI Act high-risk classifications for emotion recognition in learning environments.
Healthcare commands premium pricing. Gaming shows steepest expansion trajectory.
End User:
Customer type segmentation reveals divergent procurement patterns, with institutional buyers emphasizing compliance documentation and consumer platforms prioritizing latency and cost.
- Enterprises:Workforce analytics deployments in the United States integrate EDR modules into human capital management suites for employee sentiment tracking and stress detection. Procurement concentrates around full-stack platform vendors rather than point-solution APIs.
- Consumers:Mobile applications and smart home devices deploy lightweight on-device emotion recognition for personalized content recommendation and wellness coaching.
- Research Institutions:Academic and clinical research programs require calibrated neurophysiological measurement systems with published validation studies.
- Government Agencies:Public sector procurement across Germany, France, and Italy mandates algorithmic transparency and human-in-the-loop safeguards under EU AI Act requirements.
Enterprise segment anchors current revenue. Consumer platforms represent volume expansion opportunity.
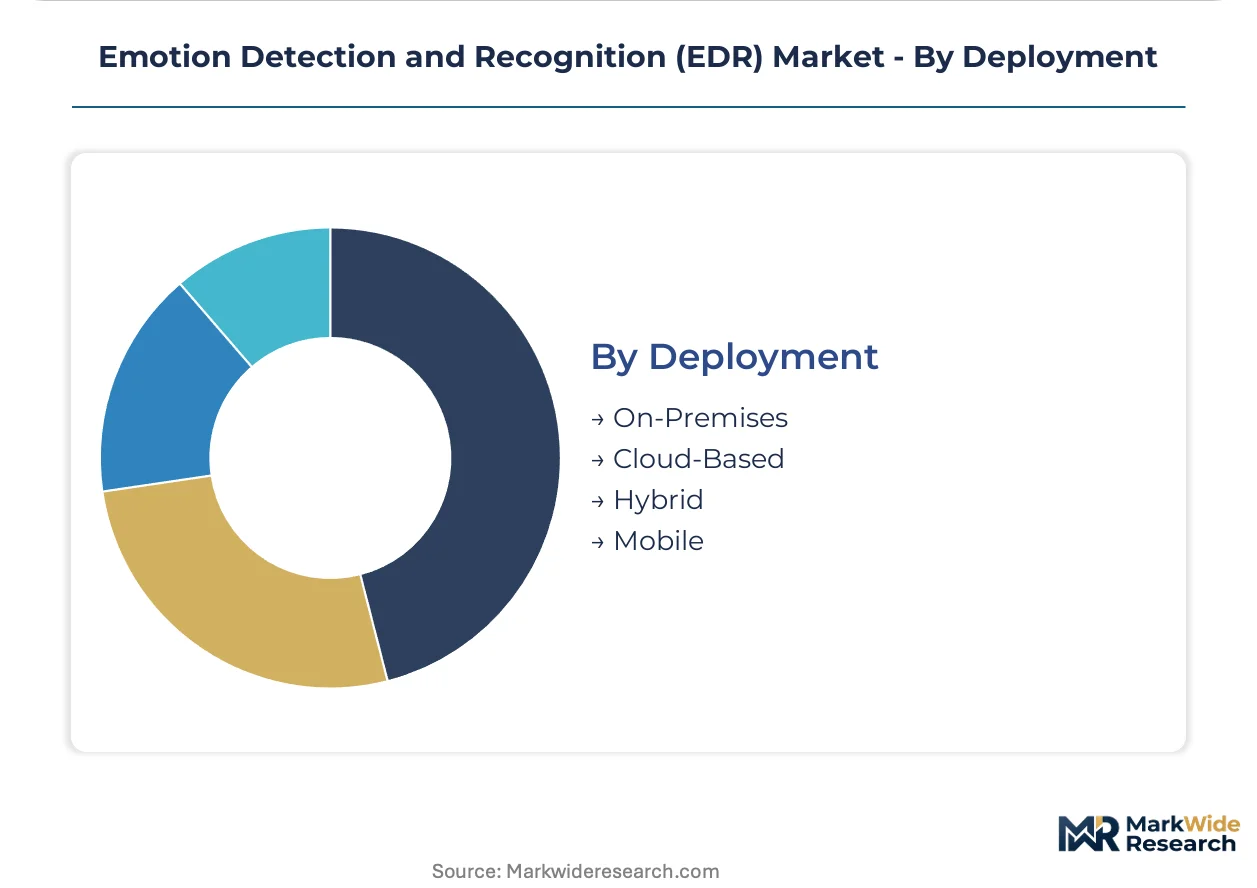
Deployment:
Infrastructure architecture choices reflect trade-offs between data sovereignty, latency requirements, and computational cost structures.
- On-Premises:Healthcare and government deployments in Germany and France require local data processing to satisfy GDPR and EU AI Act data residency provisions. Hardware and maintenance costs elevate total cost of ownership.
- Cloud-Based:Microsoft Azure and Google Cloud anchor enterprise emotion recognition workloads, offering scalable inference for facial and voice analysis pipelines. United States workforce analytics buyers favor cloud deployment for rapid integration with existing SaaS architectures.
- Hybrid:Edge preprocessing with cloud aggregation balances latency and analytical depth for real-time applications.
- Mobile:On-device inference via neural processing units enables consumer-facing emotion recognition without network dependency.
Cloud-Based deployment dominates enterprise adoption. Mobile edge inference gains share in consumer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered commercial emotion recognition through early academic research at MIT Media Lab and subsequent venture-backed startups. This foundation established North American dominance in facial analysis patents and enterprise workforce analytics deployment.
United States
Enterprise workforce analytics and consumer-facing sentiment tools drive procurement velocity. The FDA scrutinizes diagnostic-purpose EDR tools, requiring clinical validation pathways that extend commercialization timelines. Boston and San Francisco anchor development clusters where healthcare providers pilot mood disorder screening systems.
Germany
Industrial automation and automotive human-machine interface applications generate institutional demand. The EU AI Act mandates algorithmic transparency and human-in-the-loop safeguards for workplace emotion recognition. Munich and Stuttgart concentrate vendor engineering centers serving continental procurement specifications.
China
Consumer platform integration and smart city surveillance deployments scale hardware volumes. SAMR and MIIT enforce algorithmic recommendation and data security provisions governing emotion data collection and transmission. Beijing and Shenzhen host development clusters where domestic vendors optimize for latency-sensitive mobile inference.
Japan
Gaming and immersive entertainment applications drive gesture recognition hardware partnerships. METI references ISO/IEC biometric standards in procurement specifications for public sector deployments. Tokyo and Osaka studios pioneer virtual reality emotion-responsive environment design.
United Kingdom
Financial services customer experience optimization and call center quality assurance sustain enterprise demand. The Information Commissioner's Office interprets GDPR provisions for biometric data processing in commercial settings. London anchors fintech adoption of voice-based paralinguistic analysis for sentiment detection.
Emotion Detection and Recognition (EDR) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the EDR value chain. Cloud infrastructure providers anchor enterprise deployments while specialized machine learning shops differentiate on multimodal parsing architectures. Three archetypes dominate: hyperscale platform operators with captive inference infrastructure, vertical specialists concentrating on single-modality clinical validation, and system integrators embedding third-party APIs into human capital management suites. Competitive dynamics center on M&A activity consolidating point-solution vendors and strategic partnerships securing exclusive healthcare provider relationships.
Within the hyperscale platform tier, Microsoft Corporation and Google LLC exemplify divergent approaches to enterprise market development. IBM Corporation occupies a position emphasizing clinical application depth and neurological measurement protocols. These three entities represent the spectrum from infrastructure-anchored broad deployment to research-intensive vertical specialization.
| Leading Market Players |
|---|
| Affectiva (Smart Eye) |
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Apple Inc. |
| Tobii AB |
| Realeyes |
| NEC Corporation |
| Noldus Information Technology BV |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists in computer vision components have consolidated sensor manufacturing capacity across Taiwan and South Korea, compressing input costs for facial recognition modules while simultaneously extracting pricing premiums from healthcare buyers facing FDA validation timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with premium tiers commanding certification-grade positioning for clinical deployments under FDA and EU AI Act requirements. Price differentiation hinges on algorithmic transparency documentation and human-in-the-loop architecture depth. Cost compression in standard tiers is intensifying because cloud infrastructure providers are bundling emotion detection APIs at marginal cost. Healthcare providers exhibit lowest price sensitivity due to regulatory compliance mandates, while gaming studios and consumer platform developers drive hardest bargain negotiations.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and healthcare buyers mandate multi-supplier qualification for depth cameras and neural processing units, dispersing procurement across Taiwan, South Korea, and Japan. Hardware dependencies draw from specialized CMOS image sensors, edge AI accelerators, and medical-grade electroencephalography electrodes. Single-source vulnerability concentrates in advanced neural processing unit fabrication. Distribution runs through system integrators embedding EDR modules into human capital management suites rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in emotion detection and recognition rests on voice analysis API commoditization compressing delivery costs, while multimodal fusion platforms capture premium positioning through EU AI Act compliance bundling.
For Market Incumbents: Cement platform stickiness by embedding native emotion detection into existing Azure and Google Cloud enterprise workflows before point-solution APIs gain traction. Acquire specialized voice analysis shops to defend against natural language processing commoditization. Prioritize EU AI Act conformity documentation to lock out non-compliant challengers from German and French public sector procurement. For New Entrants and Emerging Players: Value-added resellers serving mid-market United States workforce analytics represent the most penetrable channel for voice-based emotion detection modules. Target immersive gaming studios in Japan and South Korea seeking kinematic gesture partnerships for virtual reality headset integration. Lead with lightweight mobile edge inference to bypass hyperscale cloud dependency. For Investors and Strategic Acquirers: Valuations sit cheapest among single-modality clinical validation specialists lacking multimodal fusion capabilities. Long-term viability favors full-stack platforms with healthcare provider exclusives and published neurological measurement protocols. Watch FDA breakthrough device designations as inflection signals for clinical-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Multimodal Fusion Platform Launch | Integrates facial micro-expression analysis with vocal prosody extraction for premium enterprise positioning. |
| EU AI Act Conformity Certification | Unlocks German, French, and Italian healthcare and public sector procurement specifications. |
| Healthcare Provider Exclusive Partnership | Secures pilot deployments for mood disorder screening systems under FDA validation pathways. |
| Voice Analysis API Integration | Captures fastest-growing segment in United States workforce analytics call center deployments. |
| Virtual Reality Hardware Partnership | Opens Japanese and South Korean gaming studio demand for kinematic gesture recognition. |
Research Methodology
Multiple input streams — primary interviews with EDR platform engineers, healthcare IT procurement officers, and regulatory affairs specialists; secondary validation against FDA 510(k) filings, EU AI Act technical documentation, and hyperscaler cloud service disclosures; plus customs records for depth camera and neural processing unit trade flows — were reconciled through bottom-up vendor revenue aggregation and top-down market sizing triangulation.
Cross-referencing historical deployment velocity against panel input from enterprise software buyers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include technology modality, application vertical, deployment architecture, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating natural language processing capability advancement rates and healthcare digitization mandate implementation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement stringency and FDA diagnostic-purpose classification rulings. Deviation in clinical validation pathway duration or algorithmic transparency requirement scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Sports Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
AI Datasets Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market