
 Agentic AI Market | 2026-2036
Agentic AI Market Size, Share, and Industry Trends Forecast 2026-2036
Agentic AI Market Insights
Platform licensing revenue is reconfiguring the economics of enterprise software procurement. Microsoft Corporation leverages its Azure cloud infrastructure to embed agentic capabilities across productivity suites. Google LLC anchors its position through deep integration of autonomous reasoning into search and enterprise workflows. Amazon.com, Inc. competes by extending AWS compute services toward autonomous operational agents for logistics and fulfillment.
Agentic AI denotes systems capable of autonomous goal-directed behavior, environmental perception, and iterative action selection without continuous human oversight, typically employing reinforcement learning architectures with context windows exceeding 100,000 tokens for sustained task execution. Its primary purpose is automating complex multi-step business processes that previously required human judgment and intervention. Natural language processing segments dominate current deployment as conversational interfaces mediate most human-agent interactions. Cloud-based deployment absorbs the majority of new capacity as organizations prioritize scalable inference over fixed infrastructure. Healthcare applications represent the fastest-growing demand concentration as autonomous diagnostic and treatment recommendation systems advance through clinical validation.
The EU AI Act imposes conformity assessment obligations on providers of autonomous systems deployed in high-risk domains, directly shaping product development roadmaps for vendors targeting European enterprises. The US FDA maintains evolving guidance frameworks for AI-enabled medical devices, creating a dual-track compliance environment for healthcare-focused agentic platforms. ISO and IEC standards for AI risk management provide baseline governance structures that multinational adopters increasingly mandate in procurement specifications. Stakeholders must evaluate whether their agentic architectures can satisfy divergent jurisdictional requirements without fragmenting into region-specific product variants.
Market Dynamics
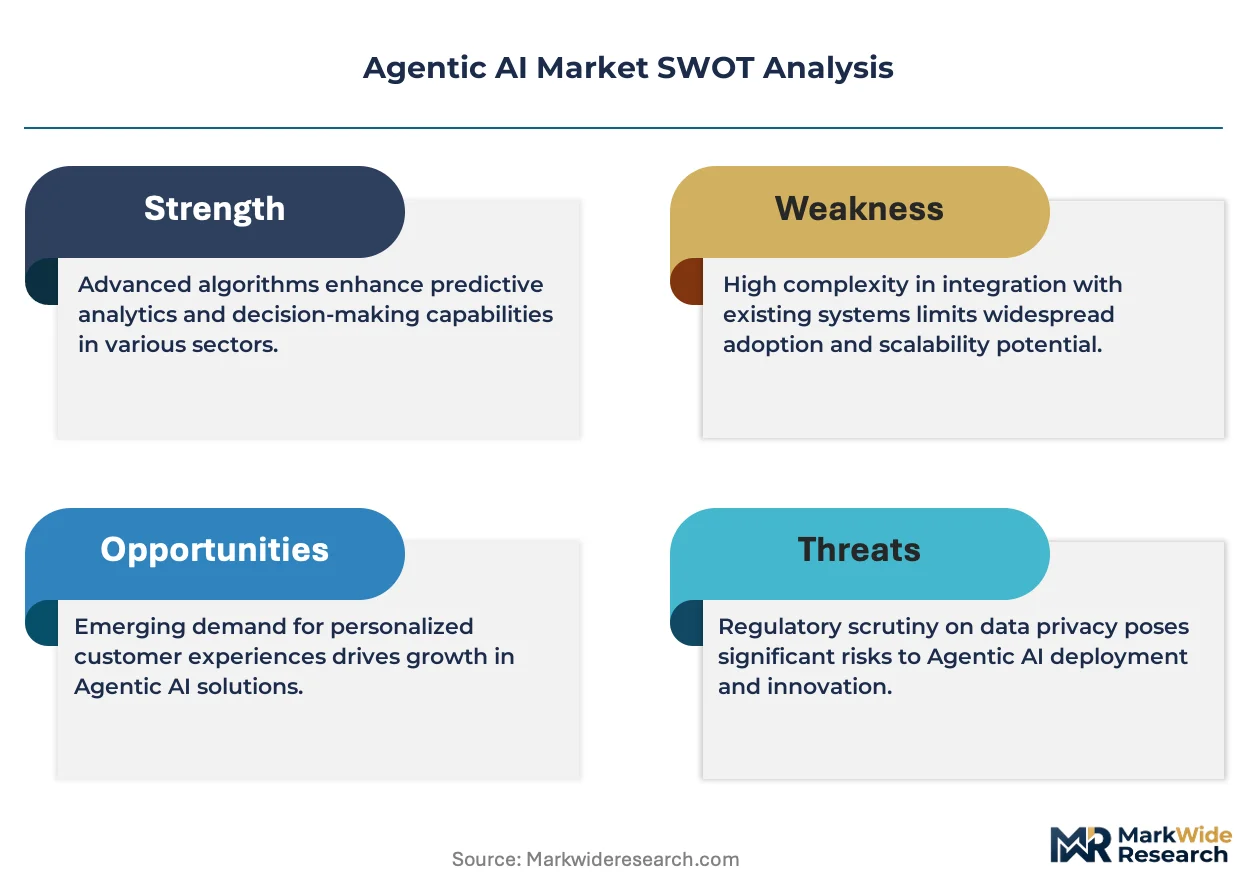
Enterprise procurement specifications are rewriting vendor roadmaps as buyers demand autonomous systems with verifiable reasoning traces. The EU AI Act's conformity assessment obligations force architecture redesigns for any platform targeting European financial or healthcare institutions.
Growth Catalysts
- EU AI Act transparency mandates:High-risk system documentation requirements create procurement urgency among European banks and insurers seeking compliant autonomous platforms before enforcement deadlines.
- Reinforcement learning from human feedback:RLHF architectures enable sustained task execution across multi-step workflows, compressing deployment timelines for complex operational automation.
- California enterprise density:Concentrated venture deployment and Fortune 500 headquarters generate disproportionate pilot-to-production conversion for agentic platforms.
Market Restraints
- GPU cluster cost volatility:Training and inference for 100,000+ token context windows requires NVIDIA H100 or equivalent compute, with spot pricing swings exceeding 40% quarterly.
- Foundation model supplier concentration:Three US-based providers control over 80% of frontier model access, creating single-source vulnerability for downstream agentic vendors.
- Interpretability technical limitations:Attention mechanism opacity prevents full audit trails for autonomous decisions, conflicting with emerging regulatory explainability requirements.
Strategic Opportunities
- India BIS certification pathway:Emerging standardization for autonomous systems creates first-mover advantage for vendors achieving early compliance with national AI governance frameworks.
- Convergence of agentic AI and robotic process automation:Hybrid architectures blending conversational reasoning with legacy RPA infrastructure unlock brownfield enterprise deployments.
- US FDA breakthrough device designation:Expedited review pathways for autonomous diagnostic agents accelerate clinical validation timelines and reimbursement negotiations.
Industry Challenges
- Reinforcement learning engineering scarcity:Practitioners capable of tuning reward functions for multi-step autonomous workflows command compensation premiums exceeding 200% versus conventional ML engineering roles.
- ISO/IEC 42001 alignment complexity:AI management system certification requires 12-18 month implementation cycles, delaying enterprise sales cycles for vendors without pre-certified architectures.
- Legacy ERP integration friction:SAP and Oracle system APIs lack native support for autonomous agent orchestration, forcing custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agentic AI Market |
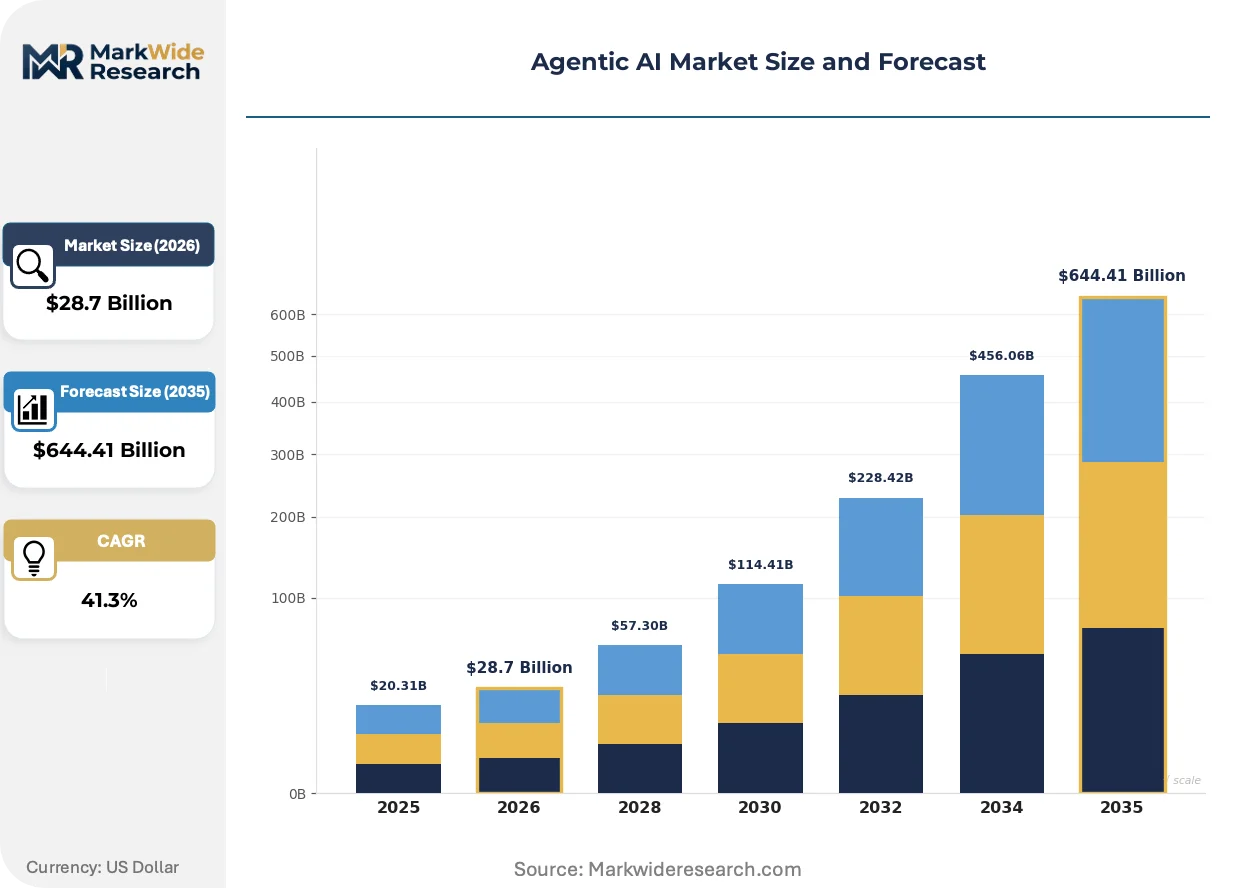
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $644.41 Billion |
| CAGR (2026 – 2036) | 41.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Application: Healthcare, Finance, Customer Service, Autonomous Vehicles End User: Small Enterprises, Large Corporations, Government Agencies, Educational Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Microsoft Corporation, Google LLC, Amazon.com, Inc., OpenAI, Anthropic, UiPath, Aisera, Adept AI, Cognition Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agentic AI Market Trends and Innovations
Foundation model architectures are compressing the boundary between reasoning and action execution. Autonomous systems now generate their own tool-use sequences rather than relying on pre-programmed workflow graphs.
Multi-modal foundation models are virtualizing environmental perception for agentic systems. Manufacturing quality control and warehouse robotics vendors adopt these architectures to reduce sensor fusion engineering. This capability is virtualizing the traditional machine vision middleware layer, collapsing supplier counts in industrial automation stacks.
The EU AI Act's high-risk system classification is redrawing product liability boundaries. Providers of autonomous credit scoring and medical triage agents face mandatory conformity assessments and post-market monitoring obligations. Healthcare platforms targeting German and French enterprises are restructuring their evidence-generation protocols to satisfy notified body requirements.
Enterprise buyers are unbundling implementation services from platform licensing. Large financial institutions in New York and London now procure raw agentic capabilities through direct API contracts, engaging systems integrators separately for domain-specific tuning. This disintermediation pressures vendor professional services margins while accelerating buyer-specific customization cycles.
Agentic AI Market Segmentation
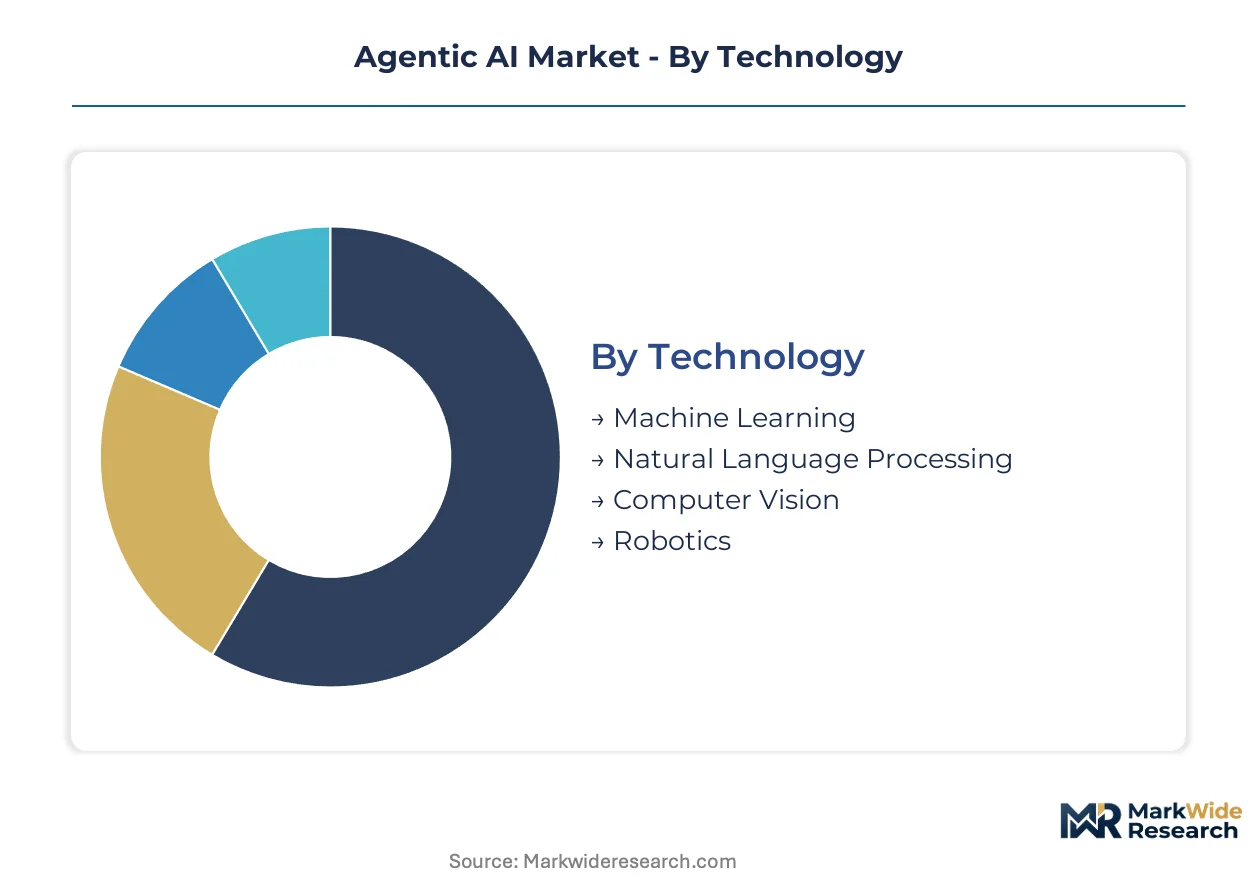
Segmentation reveals divergent investment cycles across agentic AI architectures. Technology categories exhibit 18-36 month refresh intervals while deployment modes show 5-7 year infrastructure commitments. Understanding these temporal patterns enables procurement timing and vendor selection aligned to organizational planning horizons.
Technology:
Natural Language Processing compresses development cycles to 12-18 months as foundation model releases accelerate capability thresholds. Machine Learning and Computer Vision operate on 24-30 month improvement curves. Robotics integration extends to 36-48 months due to hardware validation requirements.
- Machine Learning:Reinforcement learning architectures with extended context windows enable sustained autonomous task execution. Financial institutions in New York and London deploy these systems for portfolio rebalancing and risk model updates, constrained by interpretability audit requirements under the EU AI Act.
- Natural Language Processing:Conversational interfaces mediate human-agent interactions through transformer-based reasoning engines. Enterprise software buyers in California concentrate procurement here, driven by productivity suite integration mandates from Microsoft Azure and Google Cloud deployments.
- Computer Vision:Multi-modal perception systems virtualize environmental sensing for quality control applications.
- Robotics:Physical actuation layers bridge digital reasoning with mechanical execution in warehouse and manufacturing contexts.
Natural Language Processing dominates installed base. Machine Learning is where expansion concentrates.
Application:
Healthcare applications command premium pricing due to FDA validation pathways and clinical evidence generation costs. Finance follows with compliance-driven procurement. Customer Service and Autonomous Vehicles operate at lower margin tiers with higher volume throughput.
- Healthcare:Autonomous diagnostic and treatment recommendation systems advance through FDA breakthrough device pathways. German and French enterprises demand conformity assessments under EU AI Act high-risk classifications, extending sales cycles but locking in multi-year contracts.
- Finance:Credit scoring and portfolio management agents face mandatory transparency documentation. Swiss and UK regulators impose algorithmic accountability frameworks that reshape product architecture for vendors targeting European banking consortia.
- Customer Service:Conversational agents reduce call center operational expenditure through first-contact resolution automation.
- Autonomous Vehicles:Perception-planning-control stacks require NHTSA safety validation and ISO 26262 functional certification.
Finance dominates installed base. Healthcare is climbing the fastest.
End User:
Large Corporations amortize implementation costs across 10,000+ seat deployments. Government Agencies extend procurement cycles through security clearance and budget appropriation processes. Small Enterprises and Educational Institutions access capabilities through API consumption models with minimal upfront commitment.
- Large Corporations:Fortune 500 headquarters in California and New York drive pilot-to-production conversion with dedicated AI centers of excellence. These organizations unbundle implementation services from platform licensing, engaging systems integrators separately for domain-specific tuning.
- Government Agencies:National security and civilian applications require FedRAMP authorization and supply chain attestation. The US Department of Defense and comparable European defense ministries concentrate demand for autonomous systems with verifiable reasoning traces.
- Small Enterprises:Cloud API access reduces capital requirements for autonomous capability adoption.
- Educational Institutions:Research licensing agreements enable experimentation with frontier model capabilities.
Large Corporations dominate installed base. Government Agencies are gaining share fastest.
Deployment:
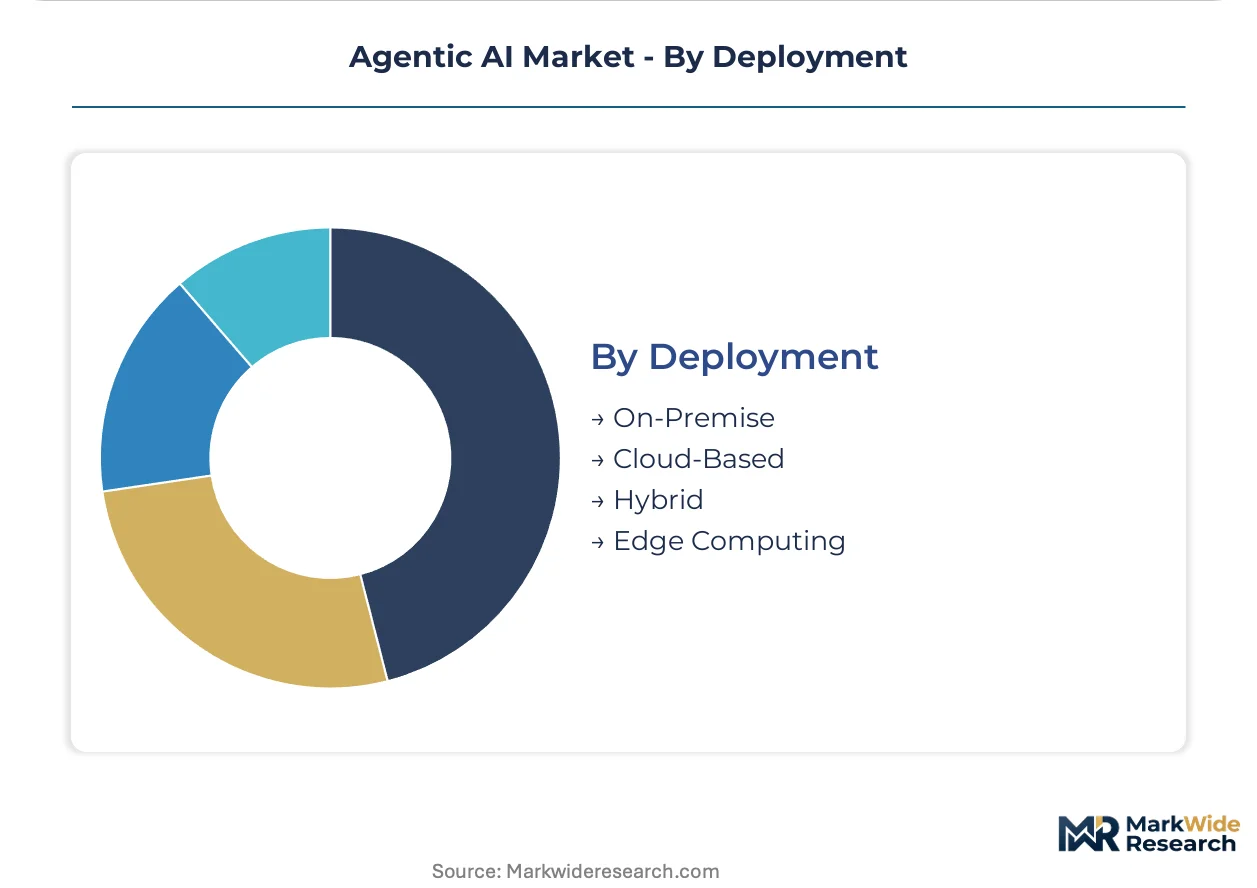
Cloud-Based deployment absorbs majority capacity as organizations prioritize scalable inference. On-Premise installations persist in regulated sectors with data residency mandates. Hybrid and Edge Computing address latency-sensitive and intermittently connected operational contexts.
- Cloud-Based:Scalable inference infrastructure from AWS, Azure, and Google Cloud enables consumption-based pricing for variable workloads. European enterprises face GDPR data transfer restrictions that complicate multi-region deployment architectures.
- On-Premise:Air-gapped installations satisfy financial services and healthcare data sovereignty requirements. German banking regulators and French healthcare authorities mandate local processing for high-risk autonomous decisions.
- Hybrid:Orchestration layers distribute sensitive reasoning on-premise while leveraging cloud burst capacity.
- Edge Computing:Low-latency inference nodes support autonomous vehicle and industrial robotics applications.
Cloud-Based dominates installed base. Hybrid is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States enterprises prioritize autonomous reasoning for productivity software integration. European financial institutions emphasize conformity assessment readiness under the EU AI Act. Asian manufacturers concentrate deployment in physical automation layers.
United States
California and New York host the densest concentration of Fortune 500 AI centers of excellence. The FDA maintains evolving guidance frameworks for AI-enabled medical devices, creating compliance benchmarks for healthcare-focused platforms. Silicon Valley venture deployment generates disproportionate pilot-to-production conversion rates for agentic vendors.
Germany
Automotive and industrial machinery sectors drive demand for autonomous quality control systems. The KBA and BSI impose strict algorithmic accountability requirements for safety-critical applications. Bavarian manufacturing clusters adopt multi-modal perception systems to reduce sensor fusion engineering overhead.
United Kingdom
London-based banking consortia procure autonomous risk assessment platforms with verifiable reasoning traces. The Bank of England and FCA impose algorithmic accountability frameworks that reshape product architecture for credit scoring vendors. The Square Mile concentrates procurement specification unbundling trends.
France
Healthcare platforms target Parisian hospital networks with autonomous diagnostic agents. ANSM and CNIL mandate local processing for high-risk autonomous decisions under GDPR and medical device regulations. Île-de-France enterprises demand conformity assessments extending sales cycles but locking multi-year contracts.
India
Bangalore and Hyderabad software exporters integrate agentic capabilities into business process outsourcing workflows. BIS certification pathways for autonomous systems create first-mover advantages for early compliance achievers. Mumbai financial institutions pilot portfolio management agents through RBI-supervised sandbox programs.
Agentic AI Market Competitive Landscape
Capability concentration sits with frontier model providers; scale advantage sits with cloud infrastructure incumbents. The market structures around three tiers: hyperscale platforms with embedded distribution, specialized autonomous reasoning startups, and legacy automation vendors retrofitting agentic layers. Dominant competitive moves include API ecosystem expansion and vertical integration into enterprise workflow orchestration.
Among hyperscale platforms, Microsoft Corporation and Google LLC exemplify the cloud-anchored archetype, leveraging existing productivity suite penetration to distribute autonomous capabilities. OpenAI occupies a position as the frontier model specialist whose API contracts anchor downstream vendor architectures. UiPath represents the legacy automation tier retrofitting conversational reasoning onto established robotic process automation infrastructure.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Google LLC |
| Amazon.com, Inc. |
| OpenAI |
| Anthropic |
| UiPath |
| Aisera |
| Adept AI |
| Cognition Labs |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific fiber routes from Los Angeles to Singapore carry inference workload traffic that shapes cost-to-serve calculations for foundation model providers, concentrating pricing power among hyperscale cloud operators while forcing tiered API access structures that differentiate enterprise buyers by committed volume scale.
Pricing Analysis
Long-term enterprise offtake contracts dominate procurement for Fortune 500 deployments, with annual commitments securing preferential inference rates against spot-market API pricing that fluctuates with GPU cluster availability. Price differentiation rests on certification tier—ISO/IEC 42001-aligned platforms command 15-25% premiums over uncertified alternatives—and vertical integration depth, with cloud-anchored vendors bundling compute and model access. Cost compression in mid-market SaaS tiers intensifies as open-weight models erode proprietary API margins. Small enterprises exhibit highest price sensitivity, routing workloads through consumption-based serverless endpoints; large financial institutions in New York and London absorb premium pricing for air-gapped, compliance-certified deployments.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries to NVIDIA and AMD compress working capital cycles for downstream server OEMs, amplifying financing risk across the hardware stack. Manufacturing concentrates in Taiwan, South Korea, and China for advanced packaging and memory fabrication, while the United States anchors frontier model development. Raw material dependencies span high-bandwidth memory from SK Hynix and Samsung, CoWoS advanced packaging capacity from TSMC, and rare earth elements for magnetic components in data center power systems. Single-source vulnerability in CoWoS capacity creates bottleneck exposure for training cluster procurement. Distribution runs through direct hyperscaler API contracts and channel partner systems integrators for enterprise on-premise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agentic AI platforms generate disproportionate lifetime value through model fine-tuning and compliance audit services that expand 40% faster than base licensing revenue, making post-deployment attach rates the critical profitability driver across customer segments.
For Market Incumbents: Entrench market position through exclusive compute reservation agreements with NVIDIA and AMD that lock in H100 cluster access before spot price volatility escalates, while accelerating ISO/IEC 42001 pre-certification to capture EU AI Act-driven procurement windows ahead of specialized autonomous reasoning startups. For New Entrants and Emerging Players: India's BIS certification pathway for autonomous systems offers underpenetrated access to Mumbai financial institutions piloting portfolio management agents through RBI-supervised sandboxes, with first-mover compliance positioning enabling multi-year contract capture before hyperscale platforms localize offerings. For Investors and Strategic Acquirers: RLHF engineering specialists with proven multi-step workflow tuning capabilities represent the highest-conviction acquisition archetype, as reinforcement learning talent scarcity commands compensation premiums exceeding 200% versus conventional ML roles; monitor FDA breakthrough device designations for autonomous diagnostic agents as inflection signals for clinical validation platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure embeds agentic capabilities across Office 365 and Teams workflows, capturing productivity suite distribution. |
| Regulatory Pre-Certification | Early ISO/IEC 42001 alignment accelerates EU AI Act conformity assessment completion for German banking consortia. |
| Backward Integration | Captive GPU cluster development reduces inference cost exposure to spot pricing volatility from cloud providers. |
| Geographic Expansion | Paris and Île-de-France hospital networks demand local processing compliance for high-risk autonomous diagnostic decisions. |
| Acquisition of Specialist Firm | RLHF engineering teams with reward function tuning expertise compress deployment timelines for complex operational automation. |
Research Methodology
Cross-validation between primary interviews with CTOs, AI center of excellence directors, regulatory affairs leads at European banks, and hospital procurement committees anchors the qualitative findings against secondary validation from SEC filings, hyperscaler capex disclosures, FDA device guidance documents, and EU AI Act implementation timelines. Bottom-up triangulation across deployment scale estimates and top-down market sizing from cloud infrastructure revenue attribution converge on segment-level demand projections.
Calibration against historical foundation model release cycles and enterprise software procurement patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include technology architecture, deployment mode, application vertical, organization size tier, and regional regulatory cluster. CAGRs derive from slope analysis of adoption curve inflection points and compliance deadline proximity effects, with GPU cluster cost trajectories and RLHF engineering supply constraints as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by frontier model specialists or sudden EU AI Act enforcement acceleration would shift outcomes. Macroeconomic contraction in venture deployment, regulatory fragmentation across jurisdictions, or breakthrough open-weight model capabilities that erode proprietary API pricing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Human-Computer Interaction (HCI) Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Cloud Natural Language Processing (NLP) Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
No-Code AI Platform Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market