
 Enterprise AI Governance and Compliance Market | 2026-2036
Enterprise AI Governance and Compliance Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise AI Governance and Compliance Market Insights
The United States is rewriting competitive dynamics through its surge in cloud-based governance infrastructure investment. IBM leverages deep vertical expertise in policy automation to sustain enterprise relationships across regulated industries. Microsoft anchors its position through integrated Azure AI compliance tooling that extends across hybrid deployment architectures. Google Cloud competes on model monitoring capabilities that specialize in real-time risk detection for financial services clients.
Enterprise AI Governance and Compliance encompasses the technical systems, procedural frameworks, and organizational protocols that ensure artificial intelligence deployments meet legal obligations, ethical standards, and operational risk thresholds through automated policy enforcement, continuous model validation, and auditable decision trails. The discipline serves industrial and commercial purposes by preventing regulatory penalties, reducing algorithmic liability exposure, and maintaining stakeholder trust in automated processes. Cloud-based deployment modes are capturing the fastest expansion as organizations prioritize scalable oversight infrastructure, while ethical AI frameworks command premium pricing due to their complexity and the specialized expertise required for implementation. On-premise solutions retain dominance among pharmaceutical and energy end users where data sovereignty requirements restrict external processing.
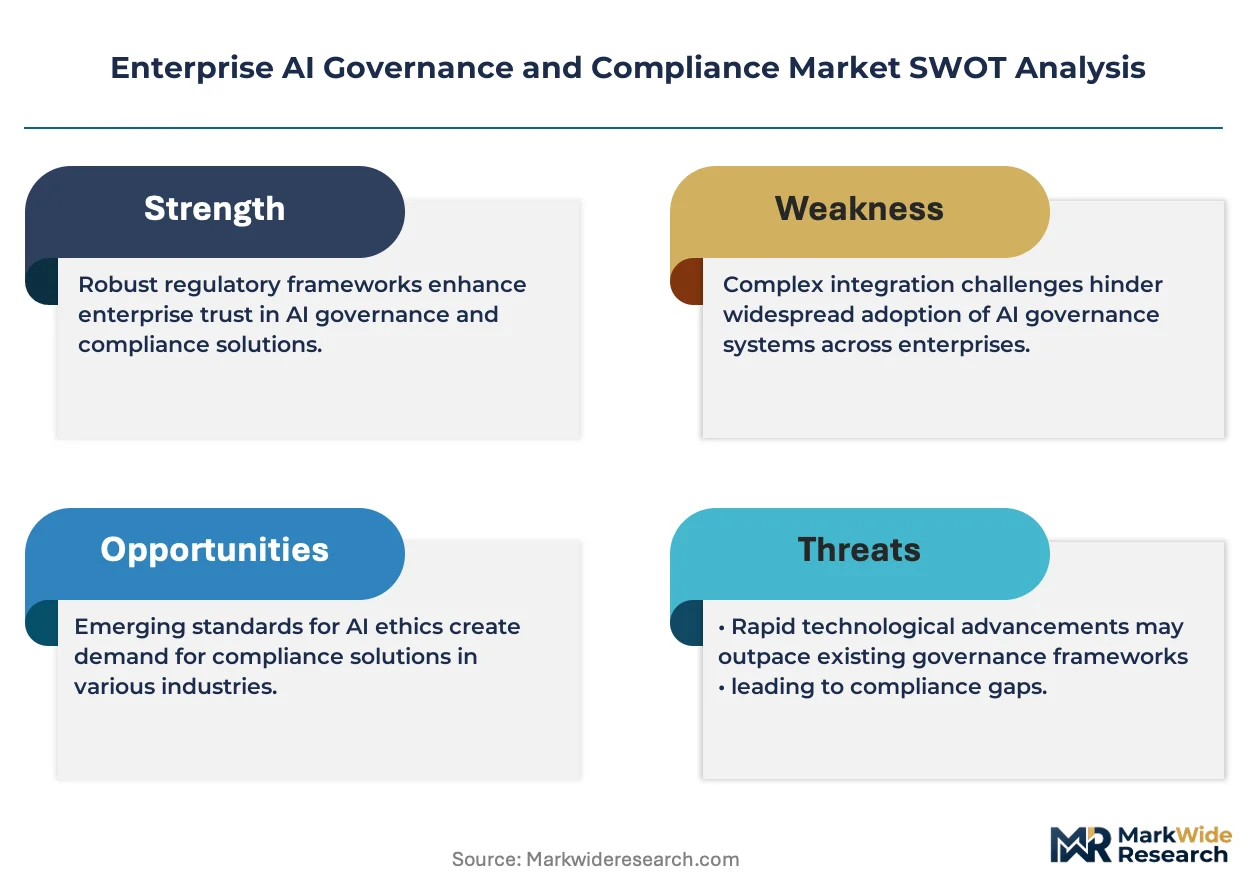
The EU AI Act, alongside FDA guidance on AI-enabled medical devices and the SEC's emerging disclosure expectations for algorithmic trading systems, is creating fragmented but intensifying compliance obligations that directly shape vendor product roadmaps and enterprise procurement criteria. ISO 42001 standards for AI management systems are gaining traction as baseline certification requirements across multinational supply chains. Stakeholders must monitor how divergent national implementation timelines for risk-based AI classification will fragment or consolidate vendor addressable markets.
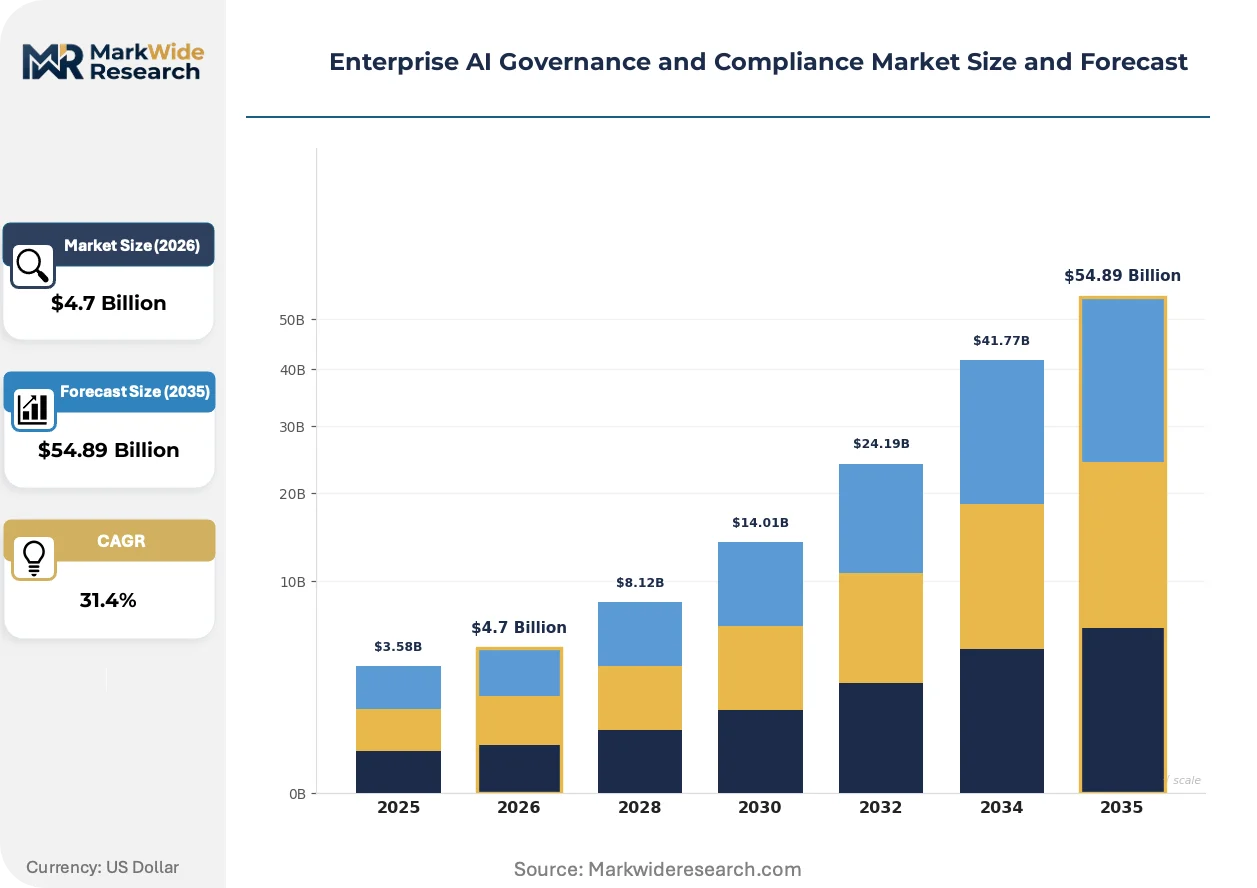
Market Dynamics
The EU AI Act's risk-based classification system is compressing procurement timelines for automated decision-making systems across regulated industries. Enterprises must now embed compliance verification into vendor selection workflows before deployment authorization.
Growth Catalysts
- Algorithmic bias mitigation mandates:Financial services regulators in the United States and European Union now require documented fairness testing for credit and insurance scoring models, forcing institutions to procure governance tooling.
- ISO 42001 certification adoption:Multinational supply chains are embedding AI management system standards into procurement contracts, creating baseline demand across manufacturing and logistics networks.
- Germany's industrial compliance cluster:Munich and Stuttgart have concentrated specialized implementation expertise, accelerating deployment velocity for automotive and precision engineering AI systems.
Market Restraints
- Specialized talent scarcity:The intersection of machine learning engineering and regulatory interpretation requires rare hybrid expertise, inflating implementation costs and extending project timelines.
- Cloud infrastructure concentration:Three hyperscale providers dominate secure enclave availability for sensitive model training, creating vendor lock-in risk and limiting negotiation leverage.
- Fragmented national implementation:Divergent timelines for EU AI Act enforcement across member states are complicating pan-European rollout strategies and inflating compliance architecture costs.
Strategic Opportunities
- Pharmaceutical on-premise penetration:Data sovereignty requirements in drug development create demand for air-gapped governance systems that cloud-native vendors have underaddressed.
- Real-time model monitoring convergence:Integration of continuous validation with MLOps pipelines offers bundled value propositions that standalone governance tools struggle to match.
- SEC disclosure preparation services:Emerging algorithmic trading transparency requirements are creating advisory and tooling demand among hedge funds and quantitative asset managers.
Industry Challenges
- Legacy system integration friction:Mainframe-based financial infrastructure requires custom API development to connect with modern governance platforms, inflating deployment costs.
- Cross-functional coordination gaps:Effective deployment demands alignment between legal, risk, data science, and procurement functions that organizational silos routinely fragment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise AI Governance and Compliance Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $54.89 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Ethical AI Frameworks, Risk Management Tools, Policy Automation, Audit & Reporting, Model Monitoring, Data Privacy Controls Application: Fraud Detection, Regulatory Reporting, Customer Insights, Operational Efficiency, Algorithmic Bias Mitigation, Cybersecurity Deployment Mode: On-Premise, Cloud-Based, Hybrid, Multi-Cloud, Edge Computing End User Industry: Telecommunications, Manufacturing, Insurance, Energy & Utilities, Pharmaceuticals, Education |
| Companies Covered | IBM, Microsoft, Google Cloud, Amazon Web Services, SAS Institute, FICO, PwC, Deloitte, Credo AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise AI Governance and Compliance Market Trends and Innovations
Automated policy enforcement is displacing manual compliance review across enterprise AI deployments. Technical architectures are converging around continuous validation pipelines that embed governance into model lifecycles rather than treating it as a post-hoc audit function.
Continuous model validation infrastructure is collapsing the traditional separation between development and compliance phases. Financial services institutions are deploying real-time monitoring systems that flag drift and bias before regulatory exposure materializes. This compression is eliminating the historical trade-off between deployment velocity and risk coverage, forcing standalone audit-tool vendors to integrate upstream or face displacement.
The EU AI Act's extraterritorial reach is reshaping product roadmaps for governance software vendors worldwide. Any system affecting EU residents triggers compliance obligations regardless of provider headquarters location, compelling non-European vendors to build Act-compatible features. Medical device manufacturers using AI-enabled diagnostics are experiencing the most acute pressure, as MDR and AI Act obligations now overlap in certification requirements.
Buyer preference is rotating toward integrated platform solutions over point tools. Procurement committees are consolidating vendor relationships to reduce integration complexity and establish single accountability for compliance outcomes. This concentration is most visible in United States healthcare networks, where CIOs are bundling governance procurement with broader cloud transformation contracts rather than managing separate AI risk workflows.
Enterprise AI Governance and Compliance Market Segmentation
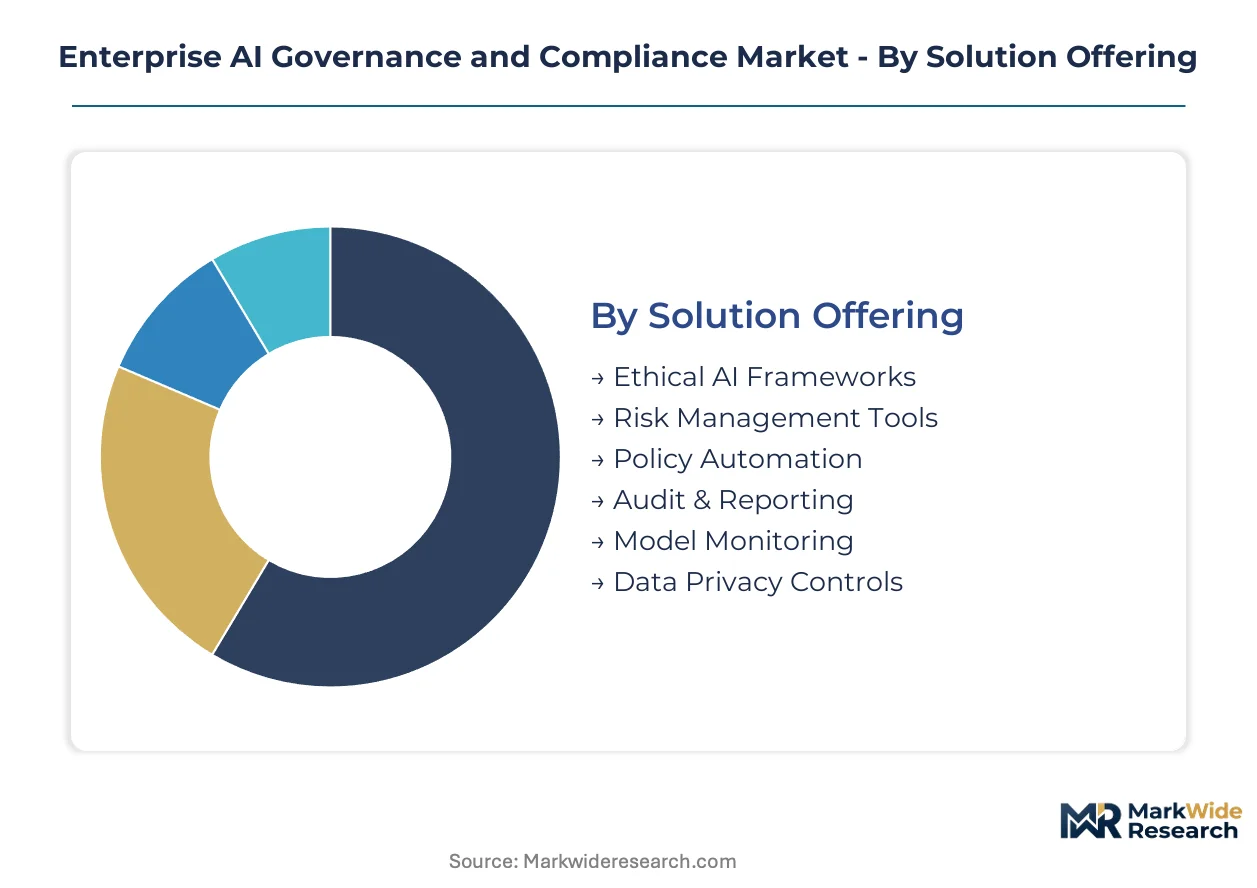
Enterprise AI governance procurement varies sharply by technical architecture and organizational risk profile. Vendors must align solution packaging with deployment constraints and industry-specific regulatory exposure rather than selling uniform platforms.
Solution Offering:
Cost tier stratification separates premium advisory-integrated suites from standalone tooling modules.
- Ethical AI Frameworks:Comprehensive governance architectures embedding fairness principles, stakeholder accountability mechanisms, and human oversight protocols into model development lifecycles. German automotive manufacturers in Munich and Stuttgart procurement clusters prioritize these frameworks for supply chain AI certification under overlapping EU AI Act and ISO 42001 requirements.
- Risk Management Tools:Quantitative assessment platforms measuring model drift, performance degradation, and regulatory exposure probability. United States financial institutions deploy these for SEC algorithmic trading disclosure preparation and automated stress testing of credit scoring systems.
- Policy Automation:Rules engines translating regulatory text into enforceable technical constraints.
- Audit & Reporting:Immutable logging systems generating evidentiary trails for supervisory examination.
- Model Monitoring:Real-time inference tracking with automated alerting on anomalous outputs.
- Data Privacy Controls:Consent management and anonymization verification for training datasets.
Ethical AI Frameworks holds installed capacity. Model Monitoring is rotating up the share rankings.
Application:
Functional use case determines integration depth and pricing architecture across buyer segments.
- Algorithmic Bias Mitigation:Fairness testing infrastructure detecting disparate impact across protected demographic classes in automated decision systems. United States and European Union financial services regulators now mandate documented testing for credit and insurance scoring, concentrating procurement among tier-one banks and carriers.
- Fraud Detection:Real-time anomaly identification for transaction monitoring and claims verification.
- Regulatory Reporting:Automated generation of supervisory submissions with embedded model documentation.
- Customer Insights:Governance overlays for personalization and segmentation models.
- Operational Efficiency:Compliance wrappers for process automation and predictive maintenance.
- Cybersecurity:Adversarial robustness verification and threat detection model validation.
Fraud Detection holds installed capacity. Algorithmic Bias Mitigation is rotating up the share rankings.
Deployment Mode:
Customer data sovereignty requirements and latency constraints fragment infrastructure preferences.
- Cloud-Based:Scalable governance infrastructure hosted on hyperscale platforms with shared security enclaves. United States healthcare networks bundle these deployments with broader Azure transformation contracts, prioritizing integrated compliance tooling over standalone risk workflows.
- On-Premise:Air-gapped systems for environments prohibiting external data transmission.
- Hybrid:Split architectures with sensitive training on-premise and inference monitoring cloud-resident.
- Multi-Cloud:Portability layers avoiding single-provider dependency for critical governance functions.
- Edge Computing:Distributed validation for IoT-embedded models with intermittent connectivity.
On-Premise holds installed capacity. Cloud-Based is rotating up the share rankings.
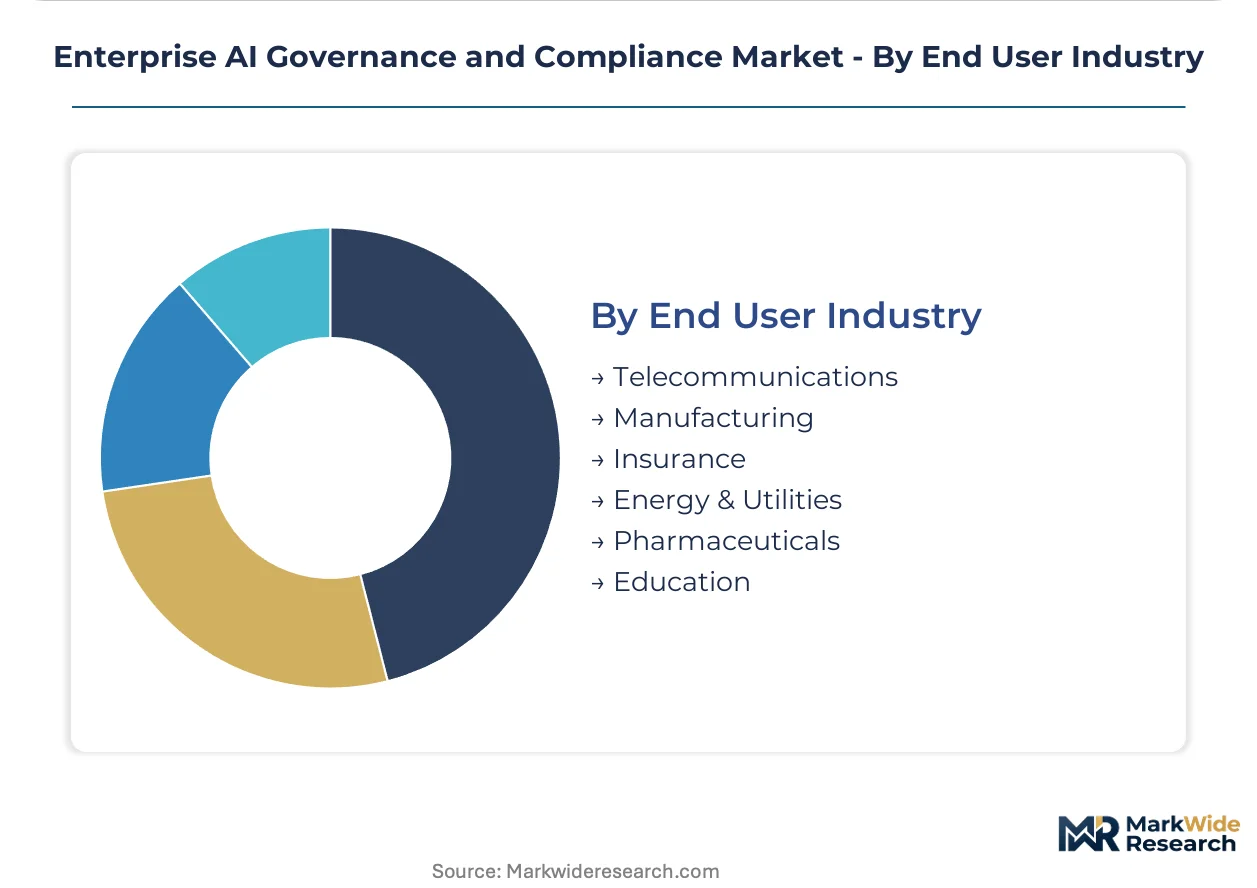
End User Industry:
Sector-specific regulatory density shapes solution customization and sales cycle length.
- Pharmaceuticals:Governance systems for drug discovery AI and diagnostic device algorithms facing overlapping FDA guidance and EU AI Act high-risk system classification. Data sovereignty requirements in clinical development drive demand for air-gapped deployments that cloud-native vendors have underaddressed.
- Insurance:Bias testing and explainability mandates for underwriting and claims automation.
- Energy & Utilities:Critical infrastructure protection standards for predictive grid management.
- Manufacturing:ISO 42001 certification support for supply chain quality control AI.
- Telecommunications:Subscriber data governance for AI-enabled network optimization.
- Education:Emerging procurement for admissions and assessment algorithm oversight.
Manufacturing holds installed capacity. Pharmaceuticals is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SEC anchors North American procurement patterns through emerging algorithmic trading disclosure requirements. EU AI Act enforcement timelines are compressing vendor selection cycles across the Atlantic. Japan's METI guidance on AI risk management is accelerating adoption in precision manufacturing sectors.
United States
Financial services institutions dominate procurement volumes as the SEC finalizes disclosure frameworks for quantitative trading systems. Healthcare networks bundle governance tooling with Azure transformation contracts, prioritizing integrated compliance over standalone risk workflows. The Boston-Cambridge corridor concentrates biotech AI validation expertise for FDA-aligned diagnostic device submissions.
Germany
Automotive manufacturers in Munich and Stuttgart procurement clusters drive demand for ISO 42001 certification support under overlapping EU AI Act obligations. The KBA enforces algorithmic accountability standards for autonomous vehicle decision systems. Industrial AI compliance expertise concentrates in Baden-Württemberg, accelerating deployment velocity for precision engineering applications.
United Kingdom
Financial conduct regulators mandate fairness documentation for credit scoring automation, forcing tier-one banks to procure bias mitigation infrastructure. The Information Commissioner's Office intersects GDPR enforcement with emerging AI governance expectations. London's fintech corridor anchors advisory services for algorithmic accountability implementation.
Japan
METI's AI governance guidelines are reshaping procurement criteria for manufacturing quality control systems. Pharmaceutical multinationals deploy on-premise validation for drug discovery AI facing PMDA inspection protocols. The Nagoya-Toyota industrial zone concentrates MLOps integration expertise for automotive supply chain certification.
France
CNIL enforcement actions against automated decision systems are elevating procurement priority for explainability tooling. Luxury goods manufacturers embed governance frameworks for personalization algorithms under consumer protection scrutiny. The Paris-Saclay research cluster anchors academic-industry partnerships for ethical AI framework development.
Enterprise AI Governance and Compliance Market Competitive Landscape
Hyperscale cloud providers and specialized governance platforms split the market into competing capability layers. Consolidation pressure intensifies as procurement committees favor integrated suites over fragmented point solutions. Three archetypes dominate: infrastructure-anchored ecosystems, vertical-specialized consultancies, and standalone model monitoring specialists. Strategic partnerships and portfolio diversification represent the dominant competitive vectors as vendors race to bundle advisory services with technical tooling.
Within the infrastructure-anchored tier, Microsoft and Google Cloud exemplify platform-centric positioning that extends governance capabilities across hybrid deployment architectures. IBM occupies a position bridging policy automation expertise with deep vertical relationships across regulated industries. Credo AI represents the emerging specialist archetype, anchoring a position focused on ethical AI framework implementation rather than broad infrastructure coverage.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Google Cloud |
| Amazon Web Services |
| SAS Institute |
| FICO |
| PwC |
| Deloitte |
| Credo AI |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure concentration in the United States creates asymmetric margin capture, with compute and secure enclave providers extracting premium rents while governance software vendors compete on implementation velocity and vertical specialization downstream.
Pricing Analysis
United States-based deployments command 15-25% premiums over European equivalents due to integrated Azure bundling and SEC-mandated algorithmic trading disclosure tooling. Three-tier pricing structure across premium advisory-integrated suites, mid-market SaaS modules, and open-source tooling cores dominates procurement patterns. Cost compression in mid-tier subscriptions is intensifying because hyperscalers bundle governance features into broader cloud contracts. Tier-one financial institutions show lowest price sensitivity, accepting premium advisory integration, while mid-market manufacturers prioritize standalone tooling modules.
Supply Chain Analysis
Specialized machine learning engineering talent feeds from concentrated academic pipelines in Germany, the United Kingdom, and the United States, creating bottleneck dependencies for implementation services. Core components include secure enclave hardware from Taiwan and South Korea, open-source model validation libraries, and regulatory interpretation expertise anchored in London and Munich. Single-source vulnerability around hyperscale cloud infrastructure creates vendor lock-in risk for sensitive model training. Distribution runs through direct enterprise sales with advisory-heavy implementation, supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise AI governance functions as a defensive-moat market where regulatory entrenchment creates durable competitive positions. Switching costs compound as embedded policy automation and audit trails deepen organizational dependency.
For Market Incumbents: Build switching-cost moats through deeper integration into MLOps pipelines and continuous validation infrastructure. Incumbents should anchor policy automation within client DevSecOps workflows to raise replacement costs. Threat from standalone model monitoring specialists demands pre-emptive bundling of real-time drift detection. Certification investment in ISO 42001 advisory services reinforces vertical relationships against hyperscaler encroachment. For New Entrants and Emerging Players: Pursue pharmaceutical on-premise deployments where data sovereignty requirements have left cloud-native vendors exposed. Air-gapped governance systems for drug discovery AI represent the most penetrable white space. New entrants should target Baden-Württemberg automotive suppliers seeking ISO 42001 certification support under overlapping EU AI Act obligations. Go-to-market positioning through specialized implementation partnerships with Munich-based consultancies accelerates credibility building. For Investors and Strategic Acquirers: Capital is best deployed toward vertical-specialized governance platforms with embedded advisory capabilities rather than horizontal infrastructure plays. Long-term viability rests on regulatory complexity deepening faster than automation commoditizes compliance interpretation. Acquisition target archetype: mid-tier firms with concentrated expertise in FDA-aligned medical device validation or SEC algorithmic trading disclosure preparation. Signal to watch: divergence in EU AI Act enforcement timelines across member states fragmenting vendor addressable markets.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding governance into Azure and AWS MLOps pipelines captures healthcare network bundling demand. |
| Acquisition of Specialist Firm | Buying ISO 42001 advisory boutiques accelerates automotive certification penetration in Stuttgart clusters. |
| Strategic Partnership | Alliances with systems integrators extend reach into mid-market manufacturing compliance budgets. |
| Product Launch | Air-gapped on-premise suites address pharmaceutical data sovereignty gaps cloud vendors underaddress. |
| Geographic Expansion | Tokyo and Nagoya presence captures METI-guided manufacturing quality control governance demand. |
Research Methodology
The analysis maps ethical AI frameworks, risk management tools, policy automation systems, and audit infrastructure, each validated through chief data officers, compliance leads at tier-one banks, procurement managers at automotive OEMs, and regulatory affairs directors at pharmaceutical multinationals. Primary interview findings were cross-referenced against SEC disclosure filings, EU AI Act implementation guidance, ISO 42001 certification databases, and hyperscaler capex disclosures. Bottom-up deployment estimates and top-down regulatory obligation sizing were triangulated to constrain forecast variance.
Assumptions held fixed include EU AI Act enforcement timelines, FDA guidance stability on AI-enabled medical devices, and hyperscaler cloud infrastructure availability. The projection horizon spans solution offerings, deployment modes, end-user industries, and regional adoption patterns, with particular weighting on financial services algorithmic bias mandates and pharmaceutical data sovereignty requirements. CAGRs were derived from segment-level penetration curves and regulatory obligation intensity scoring, incorporating MLOps pipeline integration velocity as a demand accelerator.
Macroeconomic conditions sit as an overlay; deviation in central bank rate policy affecting enterprise software procurement cycles or cloud infrastructure investment would shift the trajectory. Forecasts reflect assumptions about regulatory fragmentation persistence and talent scarcity duration. Cross-checking against ISO certification issuance rates and hyperscaler AI governance feature release cadence is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Global Artificial Intelligence Chip Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence in Business Market
Artificial Intelligence (AI)
Global Cognitive Computing Technology Market
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
Global Deep Learning Neural Networks (Dnns) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
North America Chatbot Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Computer Vision Market