
 AI Code Assistant Market | 2026-2036
AI Code Assistant Market Size, Share, and Industry Trends Forecast 2026-2036
AI Code Assistant Market Insights
A widening compute infrastructure gap between hyperscalers and challengers is reorganizing competitive dynamics in the AI code assistant space. Microsoft leverages its Azure cloud backbone to embed Copilot across developer workflows, while GitHub sustains repository network effects that anchor distribution. Amazon Web Services competes through Bedrock integration, extending AI code capabilities into enterprise procurement channels that it already controls.
AI code assistants are software tools that apply large language models to predict, generate, debug, and refactor source code through natural language interfaces and context-aware autocomplete, typically processing millions of tokens per second on specialized GPU clusters. Their primary purpose is to compress software development cycles and reduce defect rates in commercial engineering organizations. Cloud-based deployment leads in revenue contribution because enterprises prefer managed infrastructure over on-premise GPU provisioning, while code generation solutions capture expanding margin pools as organizations automate boilerplate and test scaffolding rather than manual completion alone. Embedded systems application growth trails web and mobile development due to stricter safety certification requirements that complicate AI-generated code validation.
The EU AI Act imposes risk classification and documentation obligations on automated code generation tools deployed in regulated industries, while the US Federal Trade Commission scrutinizes competitive bundling of AI services with dominant cloud platforms. ISO and IEC standards for AI system trustworthiness are gaining adoption as procurement prerequisites among European financial institutions. Stakeholders must monitor whether emerging liability frameworks assign responsibility to tool vendors or end-user organizations when AI-generated code introduces security vulnerabilities in production systems.
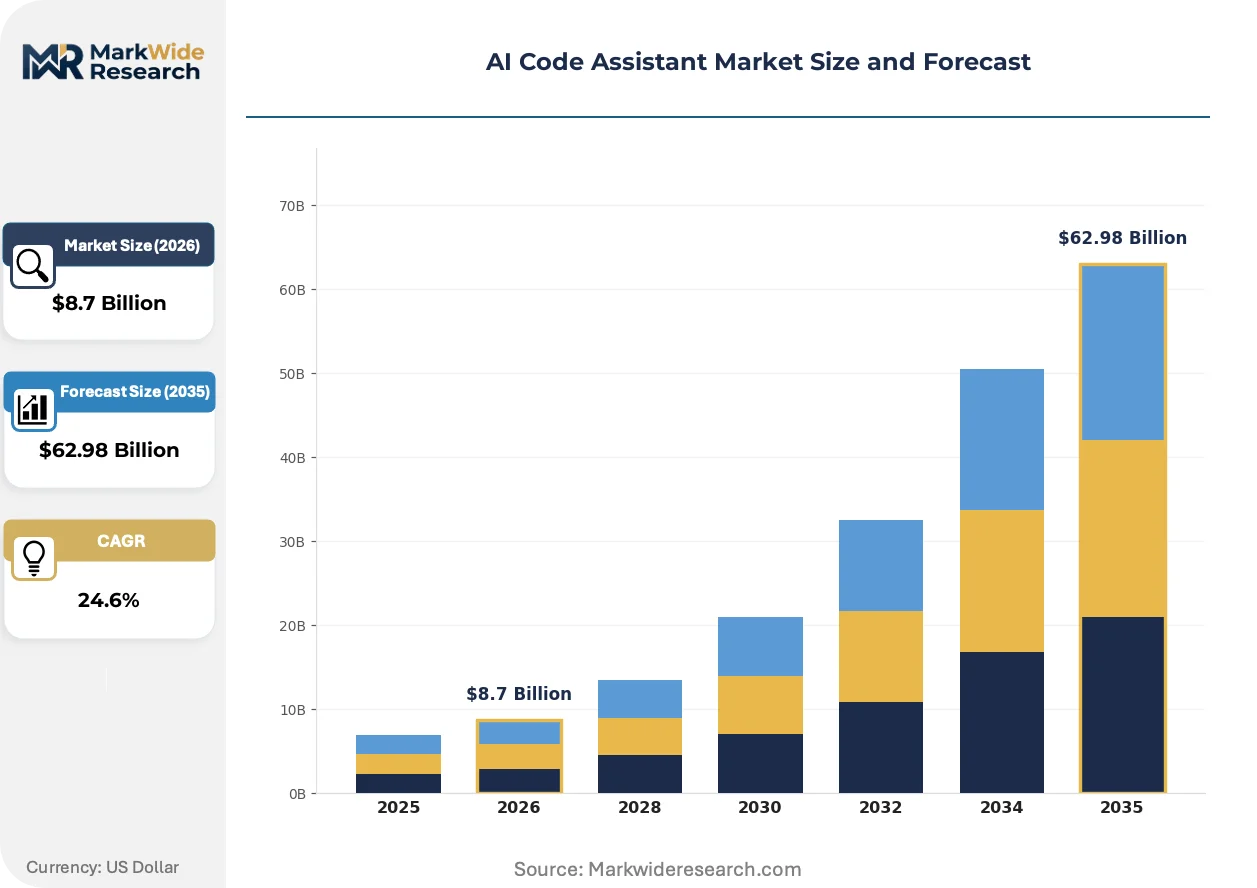
Market Dynamics
Hyperscaler cloud infrastructure concentration is reorganizing competitive access to the specialized GPU clusters that power large language model inference for code generation, privileging vertically integrated platforms over independent software vendors.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision documentation requirements in European financial services are accelerating procurement of auditable code generation tools with built-in explainability features.
- GPU cluster provisioning bottlenecks:Cloud infrastructure scarcity is pushing enterprise software teams toward managed AI code assistant subscriptions rather than self-hosted model deployments.
- Financial services compliance automation:Banks and insurers in the United States are deploying code assistants to generate regulatory reporting pipelines and reduce manual audit preparation cycles.
Market Restraints
- NVIDIA GPU supply concentration:Inference workload dependence on a single semiconductor architecture creates procurement risk and pricing volatility for AI code assistant providers.
- EU AI Act high-risk system classification:Code generation tools deployed in critical infrastructure face mandatory conformity assessment procedures that extend sales cycles by twelve to eighteen months.
- On-premise legacy toolchain persistence:Defense contractors and classified government facilities maintain air-gapped development environments incompatible with cloud-based assistant architectures.
Strategic Opportunities
- India software export sector:IT services firms serving North American and European clients represent an underpenetrated channel for code assistant adoption at scale.
- ISO/IEC 42001 alignment:Early certification to emerging AI management system standards opens procurement pathways with risk-averse European financial institutions.
- Embedded systems safety certification:Specialized code assistants that generate MISRA-C and AUTOSAR-compliant output for automotive and aerospace applications command premium positioning.
Industry Challenges
- Prompt engineering talent scarcity:Organizations lack personnel capable of designing effective context windows and retrieval-augmented generation pipelines for proprietary codebases.
- Security vulnerability attribution:Unclear liability frameworks complicate risk assessment when AI-generated code introduces exploitable defects into production systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Code Assistant Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Solution Type: Code Completion, Debugging Support, Code Generation, Code Refactoring Application: Web Development, Mobile App Development, Embedded Systems, Game Development End User Type: Software Developers, Quality Assurance Engineers, DevOps Engineers, Technical Writers |
| Companies Covered | Microsoft, GitHub, Google, Amazon Web Services, JetBrains, Tabnine, Sourcegraph, Replit, GitLab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Code Assistant Market Trends and Innovations
Foundation model capabilities for code understanding are advancing faster than enterprise governance frameworks can adapt, creating tension between automation potential and risk management protocols.
Retrieval-augmented generation architectures are bifurcating the market between general-purpose assistants and enterprise-specific systems that ingest proprietary repositories. Large technology firms are deploying internal code models trained on their own version control histories. This capability divergence is compressing vendor differentiation around data moats rather than base model performance.
The EU AI Act's risk classification framework is forcing vendors to engineer explainability features that trace generated code to training data provenance. Tool providers must now maintain technical documentation sufficient for third-party audit. Financial services procurement teams in Germany and France are prioritizing vendors with established conformity assessment pathways.
Consumption patterns among enterprise buyers are fragmenting away from per-seat licensing toward metered token billing that aligns costs with actual inference utilization. Procurement teams at Fortune 500 software divisions are negotiating usage-based contracts with spend caps. This shift is most pronounced in the United States, where cloud marketplaces facilitate granular consumption tracking and chargeback allocation.
AI Code Assistant Market Segmentation
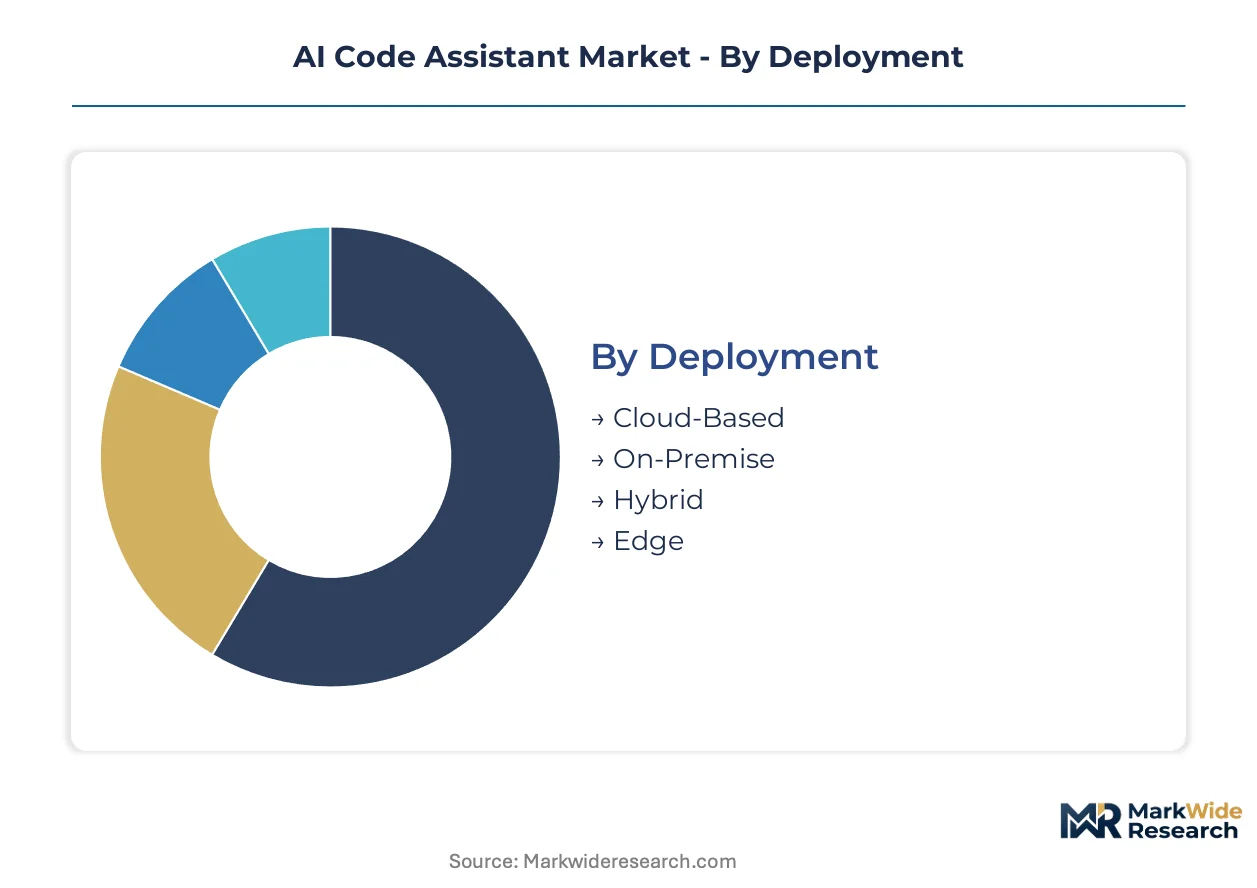
Segmentation in the AI code assistant market reveals how deployment constraints, solution maturity, and end-user workflows fragment procurement patterns. Understanding these divides helps vendors align infrastructure investments with buyer readiness and regulatory exposure.
Deployment:
Cloud-based architectures dominate North American procurement channels, while European financial institutions and Asian government facilities sustain hybrid and on-premise demand due to data sovereignty requirements.
- Cloud-Based:Managed GPU clusters deliver inference at scale without capital expenditure on specialized hardware. United States enterprise software teams prefer this model for rapid provisioning and automatic model updates, though EU AI Act documentation obligations complicate vendor selection.
- On-Premise:Air-gapped installations run on captive NVIDIA GPU infrastructure within enterprise data centers. Defense contractors in classified facilities and German automotive OEMs with strict IP controls drive this segment despite higher total cost of ownership.
- Hybrid:Sensitive codebases remain on-premise while routine completions route to cloud endpoints. French banking consortiums and Japanese electronics manufacturers favor this architecture for regulatory compartmentalization.
- Edge:Containerized models deploy on developer workstations or local servers for sub-50 millisecond latency. Game studios in South Korea and embedded systems teams in Stuttgart use edge deployment for real-time feedback loops.
Cloud-based deployment commands the established base. The steepest expansion runs through hybrid architectures as European compliance requirements harden.
Solution Type:
Margin concentration follows automation depth, with tools that generate entire functions capturing premium pricing over autocomplete utilities.
- Code Completion:Context-aware token prediction accelerates routine syntax entry. This foundational capability saturates North American software teams but faces commoditization pressure as base model performance equalizes across providers.
- Debugging Support:Static analysis integration with LLM reasoning identifies root causes from error traces. Indian IT services exporters purchase debugging suites to reduce offshore delivery defect rates for North American clients.
- Code Generation:Natural language prompts produce complete functions, test scaffolding, and API integrations. Financial services procurement teams in London and Singapore negotiate enterprise licenses for regulatory reporting pipeline automation.
- Code Refactoring:Architectural modernization suggestions migrate legacy systems to contemporary frameworks. German insurance carriers and Dutch pension funds deploy refactoring tools to address COBOL and mainframe technical debt.
Code generation solutions command the established base. The steepest expansion runs through debugging support as quality assurance budgets absorb AI tooling.
Application:
Safety certification requirements create divergent adoption timelines across software domains.
- Web Development:Full-stack frameworks and JavaScript ecosystems attract the highest assistant utilization rates. United States SaaS companies and Brazilian fintech startups deploy assistants across frontend and backend teams without regulatory friction.
- Mobile App Development:Swift and Kotlin code generation accelerates iOS and Android release cycles. Consumer app publishers in Tel Aviv and Jakarta prioritize mobile assistants for rapid feature iteration.
- Embedded Systems:MISRA-C and AUTOSAR compliance checking constrains AI-generated output validity. Automotive suppliers in Stuttgart and aerospace contractors in Toulouse demand specialized assistants with certified code pathways.
- Game Development:Shader programming and physics simulation scripting benefit from pattern-heavy code generation. Studios in Montreal and Helsinki integrate assistants into proprietary engine workflows.
Web development commands the established base. The steepest expansion runs through embedded systems as automotive software complexity outpaces manual coding capacity.
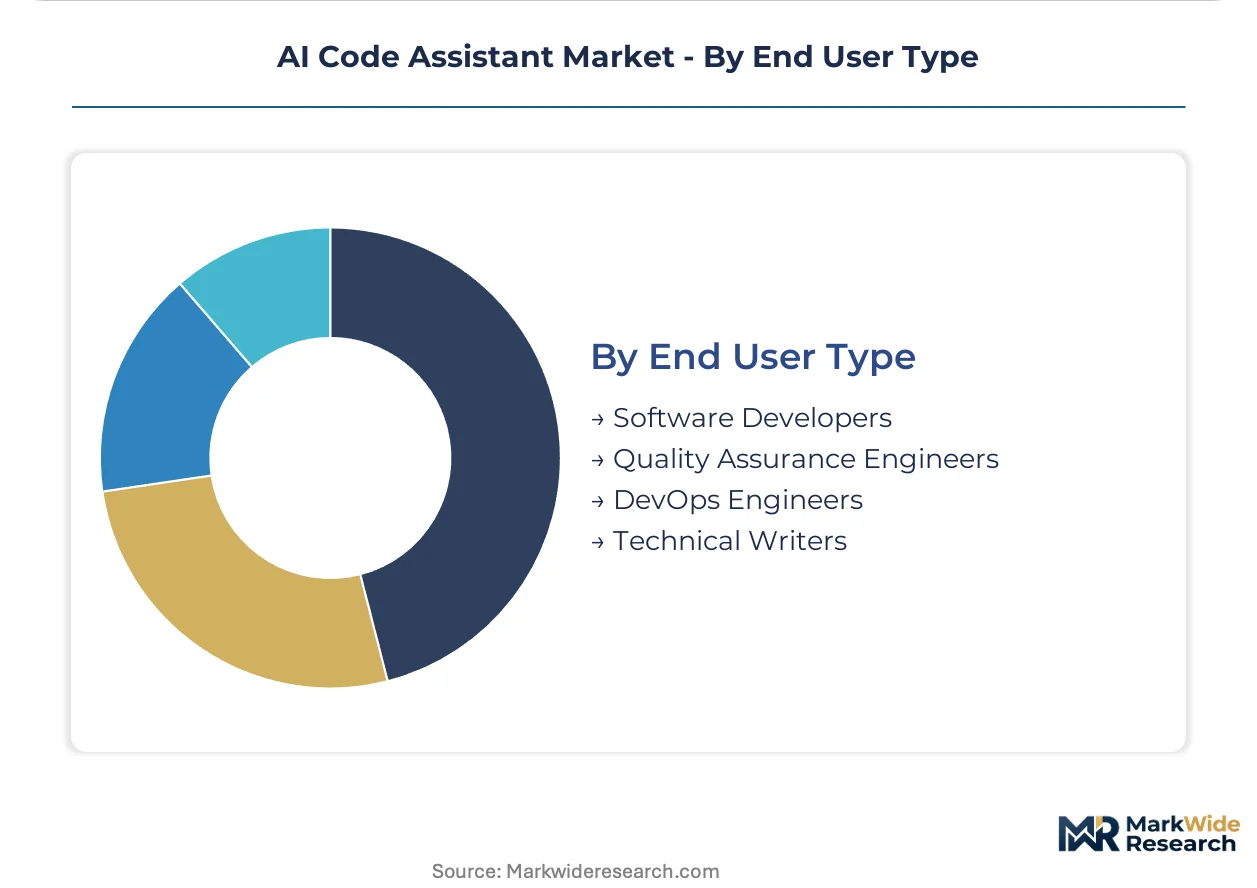
End User Type:
Procurement authority varies by organizational maturity, with platform engineering teams consolidating purchasing decisions.
- Software Developers:Individual contributors and team leads represent the primary consumption base. United States venture-backed startups issue per-seat licenses as standard equipment.
- Quality Assurance Engineers:Test automation script generation and defect triage assistance expand QA team throughput. Indian software testing firms serving European clients adopt assistants to compress delivery timelines.
- DevOps Engineers:Infrastructure-as-code generation and pipeline debugging accelerate platform reliability work. Cloud-native enterprises in Singapore and Sydney prioritize DevOps assistant integration.
- Technical Writers:API documentation generation and code snippet extraction support developer experience teams. API-first software companies in Stockholm and San Francisco deploy writing assistants for documentation velocity.
Software developers command the established base. The steepest expansion runs through DevOps engineers as platform engineering investments concentrate tooling budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States cloud infrastructure providers while European financial institutions absorb compliance premiums for auditable tooling. German automotive OEMs and French banking consortiums negotiate longer procurement cycles against stricter documentation obligations.
United States
Venture-backed SaaS companies and hyperscaler cloud divisions drive subscription volume through per-seat licensing models. FTC scrutiny of competitive bundling shapes vendor contracting terms for enterprise procurement teams. San Francisco Bay Area and Seattle technology clusters anchor platform engineering investments that consolidate tooling budgets around integrated assistant suites.
Germany
Automotive software complexity and embedded systems safety certification requirements sustain demand for specialized code generation tools. EU AI Act conformity assessment procedures extend sales cycles for tools deployed in critical infrastructure applications. Stuttgart automotive suppliers and Munich industrial software firms prioritize MISRA-C compliant assistants with established audit pathways.
United Kingdom
London financial services procurement teams negotiate enterprise licenses for regulatory reporting pipeline automation. Prudential Regulation Authority expectations for model risk management influence vendor selection criteria among banking institutions. City of London fintech clusters and Cambridge research corridors attract AI code assistant deployments for quantitative development workflows.
India
IT services exporters serving North American and European clients represent accelerating adoption channels for quality assurance and debugging support tools. Software Technology Parks of India incentives support captive development center expansions in Bengaluru and Hyderabad. Mumbai-headquartered system integrators compress offshore delivery timelines through test automation script generation capabilities.
Singapore
Cloud-native enterprises and regional headquarters of multinational technology firms prioritize DevOps assistant integration for infrastructure-as-code generation. Monetary Authority of Singapore AI governance guidelines shape procurement specifications for financial services technology vendors. One-North technology corridor and Marina Bay financial district concentrate platform engineering investments that absorb metered token billing models.
AI Code Assistant Market Competitive Landscape
Concentration sits with hyperscaler cloud platforms that control GPU cluster provisioning and distribution channels. Microsoft leverages Azure infrastructure to embed Copilot across developer workflows, while GitHub sustains repository network effects. Amazon Web Services extends capabilities through Bedrock integration into existing enterprise procurement relationships. Competitive dynamics center on M&A activity targeting specialized debugging and refactoring capabilities, alongside strategic partnerships that embed assistants into integrated development environments.
Within the cloud-native tooling tier, GitHub and GitLab exemplify platform-centric positioning that consolidates version control and assistant functionality. Amazon Web Services anchors the infrastructure-integrated archetype. Tabnine represents specialized independent vendors competing on proprietary model architectures and air-gapped deployment options for regulated environments. These three occupy distinct competitive positions based on integration depth versus deployment flexibility trade-offs.
| Leading Market Players |
|---|
| Microsoft |
| GitHub |
| Amazon Web Services |
| JetBrains |
| Tabnine |
| Sourcegraph |
| Replit |
| GitLab |
| Others |
Pricing and Supply Chain Analysis
Metered token billing with spend-cap contracts locks in GPU cluster access for enterprise software teams while anchoring price visibility against inference utilization volatility. This structure concentrates procurement leverage with United States cloud marketplace operators and European banking consortiums negotiating granular consumption tracking.
Pricing Analysis
The customization-premium spread separates standard per-seat subscriptions from enterprise-configured deployments with air-gapped infrastructure and ISO/IEC 42001 certification documentation. SaaS-tiered subscription models dominate North American procurement, with price differentiation driven by audit-readiness tier and integration depth into existing DevOps pipelines. Cost compression in standard completion tiers intensifies as base model performance equalizes across hyperscaler offerings. Indian IT services exporters exhibit highest price sensitivity, while German automotive OEMs absorb premiums for MISRA-C compliant output validation.
Supply Chain Analysis
Strategic stockpile preferences for NVIDIA GPU infrastructure dominate vendor capacity planning, with hyperscalers reserving multi-year foundry allocations ahead of independent software vendors. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for cloud infrastructure orchestration, and South Korea for high-bandwidth memory modules. The chain draws from specialized AI accelerator chips, enterprise-grade server hardware, and proprietary training datasets. Single-source vulnerability in GPU architecture licensing creates procurement risk concentration. Distribution runs through hyperscaler cloud marketplaces and direct enterprise sales teams serving regulated financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in AI code assistance hinge on retrieval-augmented generation architectures that embed proprietary codebases into inference pipelines, shifting value capture from base model performance toward data moat depth.
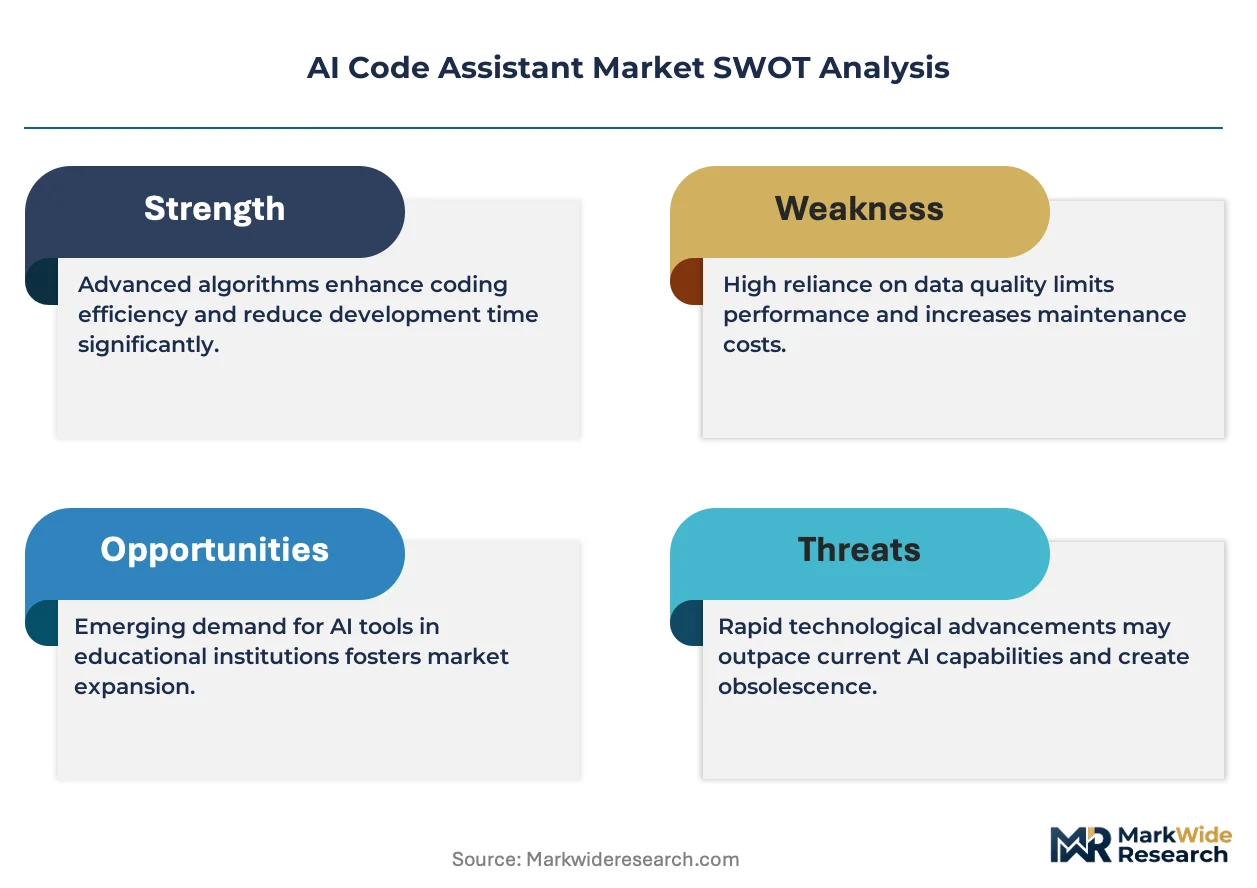
For Market Incumbents: Shield repository network effects by deepening GitHub Copilot integration with Azure DevOps workflows and GitLab CI/CD pipelines. Consolidation through acquisition of specialized debugging vendors addresses emerging competition from internal code models at Meta and Google. Certification investment in EU AI Act conformity assessment pathways defends European financial services accounts against twelve-to-eighteen-month sales cycle extensions. For New Entrants and Emerging Players: ISO/IEC 42001 fast-track certification opens procurement pathways with risk-averse European banking consortiums in Frankfurt and Paris. White-space concentration sits with Indian IT services exporters serving North American clients through quality assurance and test automation script generation. DevOps engineer tooling budgets at cloud-native enterprises in Singapore represent the most penetrable segment. Go-to-market execution should anchor in metered token billing aligned with cloud marketplace consumption tracking. For Investors and Strategic Acquirers: Air-gapped deployment specialists with established defense contractor relationships represent the priority acquisition archetype for regulatory compartmentalization exposure. Long-term viability across the analysis window rests on inference cost curves and GPU cluster provisioning concentration. The signal to watch is hyperscaler M&A activity targeting embedded systems safety certification capabilities for automotive and aerospace verticals. Revision becomes warranted when NVIDIA supply allocation policy shifts toward captive cloud infrastructure over third-party software vendor licensing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft embeds Copilot across Azure DevOps to lock in enterprise developer workflows. |
| Acquisition of Specialist Firm | Hyperscalers target MISRA-C compliant tool vendors for automotive software complexity capture. |
| Geographic Expansion | Indian IT services exporters accelerate debugging support adoption for North American delivery compression. |
| Product Launch | Tabnine releases air-gapped enterprise editions for EU AI Act documentation compliance. |
| Strategic Partnership | AWS Bedrock integration extends AI code capabilities into existing enterprise procurement channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler capex disclosures, GitHub repository activity metrics, and EU regulatory filings. Primary interviews engaged CTOs at venture-backed SaaS companies, platform engineering directors at Fortune 500 software divisions, procurement leads at London financial services institutions, and integration specialists at Indian system integrators. Secondary validation drew from App Annie developer tool adoption data, hyperscaler infrastructure investment reports, and ISO/IEC standards documentation. Bottom-up deployment model sizing triangulates against top-down cloud marketplace revenue segmentation.
Segmentation dimensions modeled include deployment architecture, solution automation depth, application safety certification requirements, and end-user technical role across the projection horizon. CAGRs derive from inference utilization trajectory analysis and GPU cluster provisioning elasticity assumptions. Industry-specific forecast inputs incorporate EU AI Act implementation timeline uncertainty and embedded systems MISRA-C compliance validation pipeline development.
Decision-makers should treat outputs as directional under assumptions of continued NVIDIA architecture dominance and stable hyperscaler cloud marketplace growth; material deviation would warrant model refresh. Specific risk factors include regulatory liability framework shifts assigning vendor responsibility for AI-generated security vulnerabilities, and supply disruption in Taiwan semiconductor fabrication capacity. Revision becomes warranted when GPU cluster provisioning scarcity crosses thresholds that displace managed subscription demand toward on-premise deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
AI Recruitment Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Self-Supervised Learning Market
Artificial Intelligence (AI)
Autonomous AI and Autonomous Agents Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Smart Home Digital Assistant [Voice] Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Generative AI in Coding Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market