
 AI-Powered Formulary Management Market | 2026-2036
AI-Powered Formulary Management Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Powered Formulary Management Market Insights
Cloud-native architecture with real-time FHIR interoperability is rotating toward the center of procurement criteria for enterprise formulary platforms. Optum Rx leverages its vertically integrated payer-PBM structure to sustain pricing leverage across health plan contracts. CVS Caremark anchors its competitive position through direct control over retail pharmacy networks and specialty dispensing operations. Express Scripts by Evernorth differentiates via proprietary therapeutic resource centers that centralize clinical pharmacist expertise.
AI-powered formulary management denotes software systems that apply machine learning algorithms to drug coverage policies, employing natural language processing to parse clinical trial data and predictive models to forecast utilization patterns against cost benchmarks. These platforms primarily enable pharmacy benefit managers and health plans to automate coverage determinations while maintaining compliance with state and federal mandates. Decision support solutions lead current revenue composition due to their embedment within existing EHR workflows, whereas genomic data integration represents the fastest-expanding segment as precision medicine contracts multiply. Workflow automation applications command premium pricing because they reduce manual prior authorization processing from days to minutes.
FDA oversight of AI-enabled clinical decision support tools under the 2022 final guidance creates compliance thresholds that filter smaller vendors from enterprise procurement pools. HIPAA interoperability rules and state-level pharmacy audit requirements further constrain platform architecture choices, particularly for cloud deployments handling protected health information. Stakeholders must monitor whether CMS reimbursement policy shifts will mandate real-time formulary transparency as a condition of Medicare Advantage plan participation.
Market Dynamics
Real-time FHIR interoperability mandates are compressing vendor consolidation timelines as hospital networks demand cloud-native architectures that integrate directly with Epic and Cerner EHR ecosystems.
Growth Catalysts
- CMS Medicare Advantage Transparency Mandates:Federal reimbursement rules now require real-time formulary data disclosure, forcing PBMs to upgrade legacy systems or lose contract eligibility.
- Precision Medicine Contract Proliferation:Genomic-guided therapy pipelines at integrated delivery networks in California and Massachusetts are expanding AI formulary modules to manage gene therapy coverage.
- Natural Language Processing Advances:Clinical trial parsing algorithms now extract safety signals from unstructured FDA label data, automating coverage policy updates that previously required manual pharmacist review.
Market Restraints
- Cloud Infrastructure Concentration:AWS and Azure dominance in healthcare-compliant hosting creates single-point-of-failure risk for formulary platforms processing protected health information.
- State Pharmacy Audit Fragmentation:Inconsistent prior authorization documentation requirements across Texas, Florida, and New York force vendors to maintain jurisdiction-specific compliance modules.
- Interoperability Standard Gaps:HL7 FHIR R4 implementation variability between EHR vendors forces costly custom integration work for each health system deployment.
Strategic Opportunities
- Medicaid Expansion States:Arkansas, Missouri, and South Dakota are deploying AI formulary tools to manage managed care organization drug lists with limited internal pharmacy expertise.
- Specialty Pharmacy Integration:Infusion center networks seek embedded formulary decision support at the point of care to prevent prior authorization denials for oncology biologics.
- FDA AI/ML-Based SaMD Guidance:The 2022 clinical decision support software framework creates first-mover advantage for vendors achieving predetermined change control plan approval.
Industry Challenges
- Clinical Informaticist Scarcity:Health systems struggle to hire pharmacists with simultaneous training in machine learning validation and therapeutic category management.
- Legacy PBM System Migration:Decades-old claims adjudication engines at regional plans require expensive middleware development to connect with modern AI formulary layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Powered Formulary Management Market |
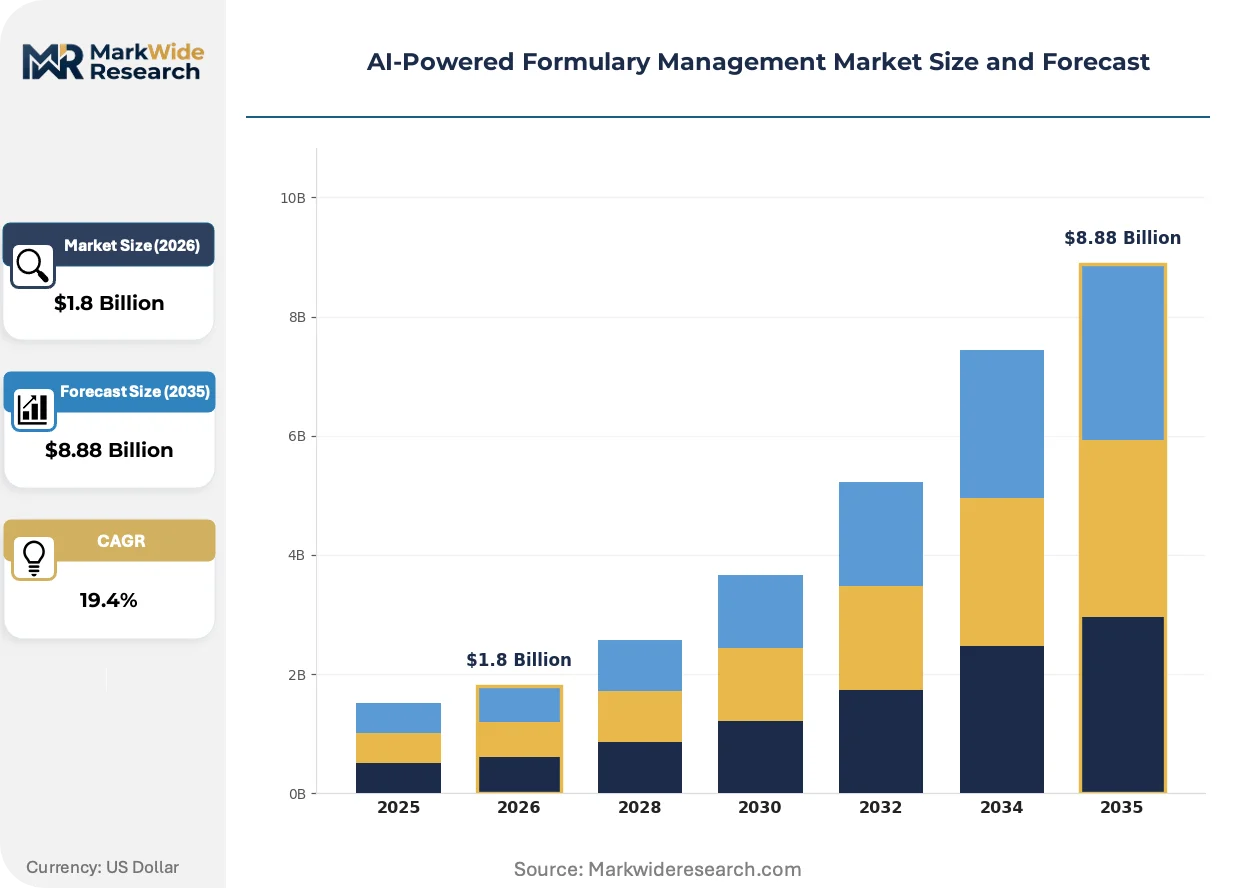
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.88 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Decision Support, Predictive Analytics, Workflow Automation, Compliance Management, Cost Optimization Application: Drug Utilization Review, Prior Authorization, Clinical Pathway Management, Benefit Design, Therapeutic Interchange End User: Pharmacy Benefit Managers, Health Plans, Hospital Networks, Managed Care Organizations, Specialty Pharmacies Data Integration Method: Electronic Health Records, Claims Data, Patient Reported Outcomes, Real-World Evidence, Genomic Data |
| Companies Covered | Optum Rx, CVS Caremark, Express Scripts by Evernorth, Surescripts, DrFirst, CoverMyMeds, Arrive Health, Prime Therapeutics, MedImpact Healthcare Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Powered Formulary Management Market Trends and Innovations
FHIR-native microservices architectures are displacing monolithic formulary databases as health systems prioritize API-first procurement criteria that enable real-time data exchange with provider workflows.
Large language models trained on FDA drug labels and clinical trial registries are fragmenting traditional pharmacy and therapeutics committee functions by automating evidence synthesis for coverage determinations. Regional health plans in the Upper Midwest are piloting these tools to reduce formulary update cycles from quarterly to continuous. The compression of manual review work is reallocating clinical pharmacist time toward complex specialty drug case management.
The FDA's 2022 guidance on clinical decision support software is bifurcating vendor compliance strategies between those pursuing full device regulation and those restructuring platforms to qualify as non-device clinical support. PBMs with captive pharmacy operations are investing in predetermined change control plans to enable iterative algorithm updates without repeated 510(k) submissions. This regulatory segmentation favors incumbent vendors with dedicated regulatory affairs infrastructure over emerging competitors.
Consolidated procurement by integrated delivery networks is compressing vendor sales cycles as Kaiser Permanente and Sutter Health-style organizations demand enterprise-wide formulary standardization across dozens of hospitals. Traditional point-solution vendors face displacement unless they demonstrate multi-site deployment scalability with centralized policy governance. The buying pattern shift concentrates contract value in fewer vendor relationships with longer implementation timelines.
AI-Powered Formulary Management Market Segmentation
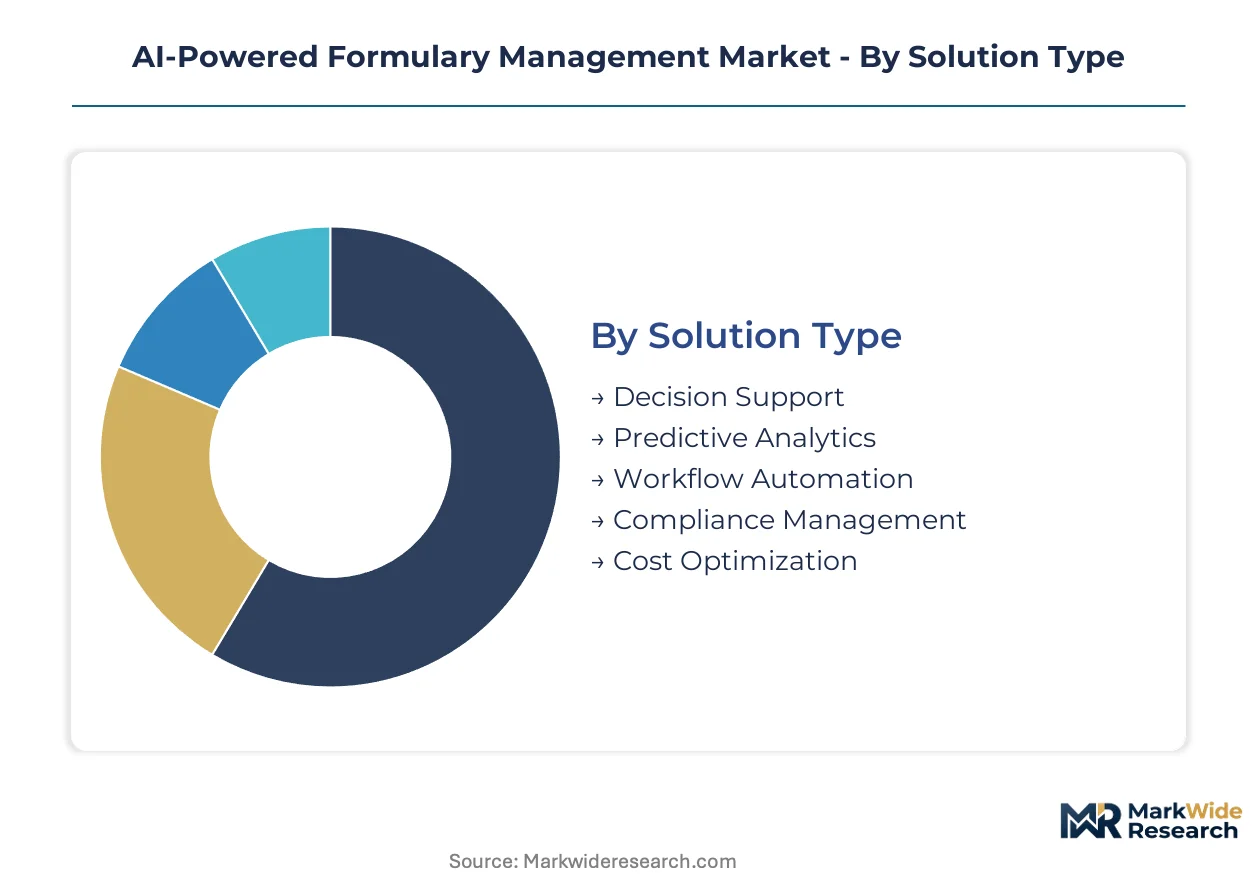
Segmentation in AI-powered formulary management reflects divergent procurement patterns across payer types and care delivery settings. Solution architecture, data integration depth, and end-user workflow requirements create distinct commercial entry points for vendors targeting enterprise versus point-solution deployments.
Solution Type:
Channel distribution varies sharply by solution complexity, with enterprise platforms flowing through direct sales to health plan IT procurement while modular tools reach hospital networks via EHR marketplace channels.
- Decision Support:Embedded clinical recommendation engines parse drug-drug interaction alerts and dosing guidelines within EHR workflows. Kaiser Permanente and Sutter Health in California are standardizing these modules across integrated delivery networks to reduce therapeutic duplication. Demand concentrates where pharmacy and therapeutics committees require automated evidence synthesis for coverage policy updates.
- Workflow Automation:Prior authorization processing engines reduce manual review cycles from days to minutes through natural language processing of clinical documentation. Arkansas, Missouri, and South Dakota Medicaid programs deploy these tools to offset limited internal pharmacy expertise in managed care oversight. Premium pricing reflects measurable administrative cost reduction.
- Predictive Analytics:Machine learning models forecast drug utilization patterns against cost benchmarks.
- Compliance Management:Automated tracking of FDA label changes and state pharmacy audit requirements.
- Cost Optimization:Algorithms identifying therapeutic interchange opportunities and formulary exclusion candidates.
Decision Support dominates installed base. Workflow Automation is where expansion concentrates.
Application:
Functional deployment follows a cost-tier logic, with high-volume administrative applications commanding per-transaction pricing while clinical pathway tools use annual licensing.
- Prior Authorization:Real-time eligibility verification and medical necessity determination engines process specialty drug requests. CVS Caremark and Express Scripts leverage these systems to manage oncology biologic approvals across captive pharmacy networks. CMS Medicare Advantage transparency mandates are forcing upgrades to legacy authorization infrastructures.
- Drug Utilization Review:Retrospective claims analysis identifies inappropriate prescribing patterns and opioid overutilization. Texas, Florida, and New York state pharmacy audit fragmentation creates jurisdiction-specific compliance module requirements. Health plans deploy these tools to satisfy Medicaid managed care oversight contracts.
- Clinical Pathway Management:Evidence-based treatment protocols embedded at point of care.
- Benefit Design:Actuarial modeling for formulary tier placement and cost-sharing structures.
- Therapeutic Interchange:Automated substitution recommendations at pharmacy dispensing.
Prior Authorization captures the largest transaction volume. Clinical Pathway Management is gaining share fastest as precision medicine contracts multiply.
End User:
Customer type determines implementation complexity, with Pharmacy Benefit Managers demanding multi-tenant architectures while Hospital Networks prioritize EHR-native interoperability.
- Pharmacy Benefit Managers:Optum Rx, CVS Caremark, and Express Scripts operate vertically integrated platforms spanning payer-PBM-pharmacy value chains. These entities require real-time formulary transparency APIs to satisfy CMS Medicare Advantage contract eligibility. Procurement concentrates on cloud-native systems with FHIR R4 connectivity.
- Hospital Networks:Epic and Cerner EHR ecosystems drive API-first procurement criteria for embedded formulary decision support. Consolidated buying by Kaiser Permanente-style integrated delivery networks is compressing vendor sales cycles toward enterprise-wide standardization. Multi-site deployment scalability is the primary selection filter.
- Health Plans:Commercial and Medicare Advantage insurers managing drug coverage policy.
- Managed Care Organizations:Medicaid MCOs in expansion states with limited pharmacy infrastructure.
- Specialty Pharmacies:Infusion center networks seeking point-of-care formulary guidance.
Pharmacy Benefit Managers anchor current revenue. Hospital Networks represent the steepest expansion trajectory as EHR interoperability mandates tighten.
Data Integration Method:
Integration depth correlates with pricing tier, with basic claims connectivity at standard rates and genomic data pipelines commanding premium positioning.
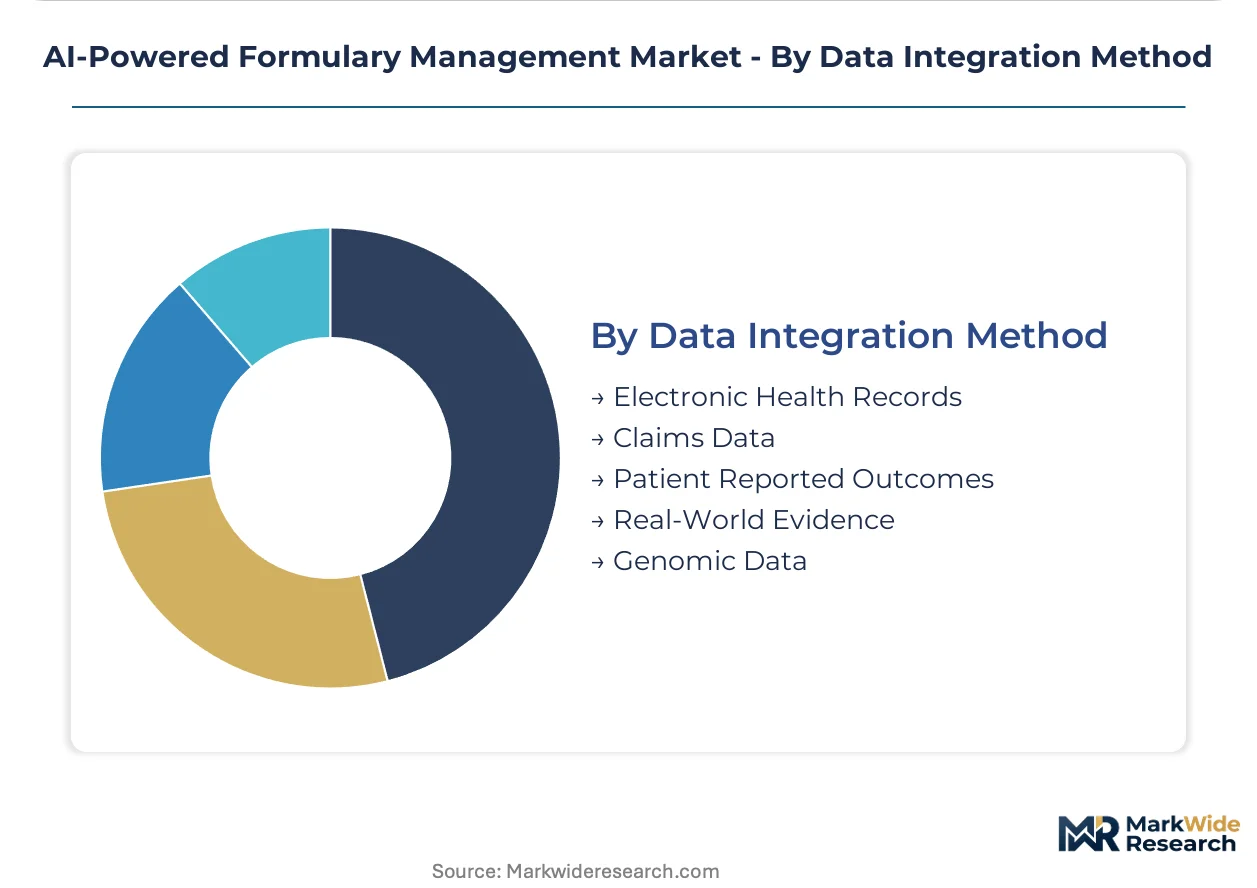
- Electronic Health Records:FHIR-native microservices architectures enable real-time formulary data exchange with Epic and Cerner workflows. HL7 FHIR R4 implementation variability between EHR vendors forces costly custom integration work per health system. Cloud-native platforms with pre-built EHR connectors capture procurement preference.
- Genomic Data:Integration of pharmacogenomic test results and gene therapy coverage criteria. Massachusetts and California integrated delivery networks are expanding AI formulary modules to manage CAR-T and gene therapy pipelines. This segment is expanding most quickly as precision medicine contracts proliferate.
- Claims Data:Historical utilization patterns for predictive modeling and retrospective review.
- Real-World Evidence:FDA Sentinel network and patient registry data for safety signal detection.
- Patient Reported Outcomes:Quality-of-life metrics for specialty drug value assessment.
Electronic Health Records dominate current deployment. Genomic Data is where vendor R&D investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure for AI-powered formulary platforms concentrates in jurisdictions with mature health data exchange frameworks and concentrated payer-provider integration. Regulatory divergence across national pharmaceutical agencies shapes vendor compliance investment patterns and deployment sequencing.
United States
Hospital networks in California and Massachusetts drive enterprise formulary platform procurement, with Kaiser Permanente and Sutter Health deploying standardized systems across integrated delivery networks. FDA guidance on AI-enabled clinical decision support software under the 2022 framework creates compliance thresholds that filter vendor pools. The FDA's predetermined change control plan pathway enables iterative algorithm updates without repeated submissions, favoring established vendors with regulatory infrastructure.
Germany
The country's statutory health insurance funds are piloting AI-driven drug utilization review systems to manage pharmaceutical expenditure growth within the G-BA (Federal Joint Committee) benefit assessment framework. EMA coordination with national regulators on AI/ML-based software as a medical device creates alignment pressure for vendors seeking cross-border deployment. Berlin and Munich health technology clusters host interoperability testing facilities for FHIR R4 implementations targeting the German Hospital Future Act digitization mandates.
United Kingdom
NHS England's Integrated Care Systems are consolidating formulary decision-making authority across former Clinical Commissioning Groups, creating demand for centralized AI policy management platforms. MHRA guidance on software as a medical device post-Brexit diverges from EU MDR implementation timelines, forcing vendors to maintain parallel compliance tracks. The London health tech corridor sees concentrated deployment of genomic data integration modules for precision medicine pathways within tertiary referral centers.
Japan
PMDA's phased implementation of software as a medical device regulations for AI clinical decision support is compressing vendor market entry timelines for pharmaceutical cost management tools. METI's healthcare data exchange standards initiative promotes FHIR adoption among regional insurer-provider consortia. The Kanto region's university hospital networks serve as pilot sites for automated prior authorization systems targeting high-cost specialty drug categories.
India
CDSCO's evolving framework for AI-based medical device regulation is creating uncertainty for formulary management software classification as clinical decision support versus administrative tools. The country's National Digital Health Mission is establishing health data exchange standards that will eventually mandate real-time formulary transparency for empanelled providers. Hyderabad and Bengaluru health IT clusters host development centers for cloud-native formulary platforms targeting both domestic insurers and export markets.
AI-Powered Formulary Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the AI-powered formulary management market. Vertically integrated payer-PBM entities command pricing leverage through captive pharmacy networks and direct control over claims data pipelines. Specialized workflow automation vendors compete on implementation speed and EHR-native interoperability. The dominant competitive moves center on FHIR-native microservices architecture development and predetermined change control plan approval under FDA guidance to enable iterative algorithm deployment.
Among vertically integrated payer-PBM entities, Optum Rx, CVS Caremark, and Express Scripts by Evernorth occupy positions defined by control over pharmacy networks and specialty dispensing operations. These organizations exemplify the scale-driven archetype where formulary platform development serves captive contract flows. Their competitive positioning rests on real-time data access across integrated value chains rather than third-party software licensing.
| Leading Market Players |
|---|
| Optum Rx |
| CVS Caremark |
| Express Scripts by Evernorth |
| Surescripts |
| DrFirst |
| CoverMyMeds |
| Arrive Health |
| Prime Therapeutics |
| MedImpact Healthcare Systems |
| Others |
Pricing and Supply Chain Analysis
Per-transaction SaaS licensing locks in supply access for health plan procurement teams while anchoring price visibility against utilization volume commitments. This contract structure concentrates pricing power with cloud-native platform vendors serving vertically integrated payer-PBM entities.
Pricing Analysis
FDA's 2022 clinical decision support software guidance dictates the pricing tier structure across the AI-powered formulary management landscape. Three-tier pricing separates enterprise-wide deployments from modular EHR plugins and basic prior authorization tools. Premium positioning rests on predetermined change control plan approval status. Cost compression in the standard tier is intensifying because Medicaid expansion states demand budget-constrained procurement. Managed care organizations exhibit highest price sensitivity; vertically integrated PBMs show least.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes feed into cloud infrastructure hosting costs for formulary platforms processing protected health information. Software development concentrates in India, the United States, and Germany. Raw material dependencies center on GPU compute capacity, FHIR interoperability middleware, and clinical NLP training datasets. Single-source vulnerability runs through AWS and Azure dominance in healthcare-compliant hosting. Distribution runs through direct enterprise sales to health plans and EHR marketplace channels for hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered formulary management functions as a service-attach opportunity where workflow automation modules expand faster than core decision support licensing. Recurring revenue from prior authorization processing APIs outpaces one-time implementation fees.
For Market Incumbents: Fortify regulatory affairs infrastructure to maintain predetermined change control plan approvals under FDA guidance. Deepen FHIR-native microservices development to defend against emerging interoperability specialists. Vertical integration into captive pharmacy networks preserves pricing leverage as CMS transparency mandates compress margins. For New Entrants and Emerging Players: Differentiate on genomic data integration capabilities targeting precision medicine contracts at Massachusetts and California integrated delivery networks. White-space concentrates in Medicaid expansion states with limited internal pharmacy expertise. Pursue EHR marketplace distribution to bypass lengthy enterprise procurement cycles. For Investors and Strategic Acquirers: Cloud-native workflow automation vendors with FHIR R4 certification represent the priority acquisition archetype. Long-term viability hinges on regulatory compliance scalability across multiple FDA guidance iterations. Watch for CMS reimbursement policy shifts mandating real-time formulary transparency as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Microservices Development | API-first architecture captures procurement preference from Epic and Cerner EHR ecosystems. |
| Predetermined Change Control Plan Submission | FDA approval enables iterative algorithm updates without repeated 510(k) submissions. |
| Genomic Data Pipeline Integration | Precision medicine contracts at Kaiser Permanente and Sutter Health drive premium positioning. |
| Medicaid Expansion State Penetration | Arkansas, Missouri, and South Dakota deployments offset limited pharmacy expertise. |
| Specialty Pharmacy Workflow Embedding | Point-of-care formulary guidance prevents prior authorization denials for oncology biologics. |
Research Methodology
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings in this analysis. Conversations with formulary directors, pharmacy benefit manager executives, EHR integration specialists, and hospital procurement managers combine with FDA 510(k) filings, CMS Medicare Advantage contract disclosures, ClinicalTrials.gov records, and GPO procurement databases. Bottom-up health system deployment tracking and top-down payer technology spending analysis provide triangulation.
Sensitivity analysis around CMS reimbursement policy scenarios shapes the forecast framework across the projection horizon. Segmentation dimensions include solution type, application function, end-user category, and data integration depth. CAGRs derive from utilization pattern modeling against cost benchmark trajectories. Forecast inputs incorporate EHR interoperability mandate timelines and precision medicine contract proliferation rates.
The analysis sits within stated boundaries; outcomes outside FDA guidance stability or CMS transparency mandate implementation would require recalibration. Forecasts reflect assumptions about cloud infrastructure cost curves and clinical informaticist labor availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global E-Health Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
Artificial Intelligence (AI) Healthcare Market
Health Informatics
Healthcare API Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
IHE XDS.B Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
United States Healthcare Fraud Detection Market