
 Healthcare Natural Language Processing Market | 2026-2036
Healthcare Natural Language Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Natural Language Processing Market Foresight
The United States is reconfiguring healthcare NLP capacity through cloud infrastructure expansion and federal health IT investment. IBM leverages its Watson Health heritage to sustain enterprise clinical AI deployments. Google anchors cloud-native NLP services for population-scale health analytics. Microsoft competes through Azure AI integration with existing hospital information systems.
Healthcare Natural Language Processing encompasses computational methods that extract, classify, and generate meaning from unstructured clinical text and voice data, operating across syntax parsing, named entity recognition, and semantic relationship modeling with latency thresholds under 200 milliseconds for real-time documentation. Its primary purpose is converting physician dictation, electronic health records, and patient-generated text into structured, actionable data for care coordination and billing. Speech recognition dominates current deployment volumes due to embedded EHR workflows, while sentiment analysis represents the fastest-expanding segment as health systems prioritize patient experience measurement. Cloud-based deployment captures the majority of new implementations, though hybrid architectures retain stronghold status among institutions with strict data residency requirements.
FDA oversight of AI-enabled medical devices intersects with HIPAA privacy mandates to create a dual compliance burden for NLP vendors seeking hospital adoption. The EU AI Act's high-risk system classification for healthcare applications adds cross-border certification complexity for multinational platform providers. Stakeholders must monitor evolving FDA predicate device pathways and state-level algorithmic accountability legislation to anticipate deployment barriers.
Market Dynamics
FDA predicate device pathway revisions are compressing validation timelines for clinical NLP vendors while cloud infrastructure investments by integrated health systems accelerate procurement velocity.
Growth Catalysts
- HIPAA-aligned cloud migration:Hospital systems are consolidating data lakes on HIPAA-compliant infrastructure, creating procurement pull for embedded NLP documentation tools.
- EU AI Act high-risk classification:The EU AI Act's healthcare application tier is forcing vendors to pre-certify clinical decision-support modules, accelerating enterprise sales cycles.
- Real-time speech-to-text latency thresholds:Sub-200 millisecond processing requirements are driving replacement of legacy dictation hardware with cloud-native clinical documentation platforms.
Market Restraints
- Dual compliance architecture costs:Simultaneous FDA 510(k) validation and HIPAA technical safeguard implementation requires specialized legal-engineering teams, elevating vendor operating costs.
- Annotated clinical corpus scarcity:Curated training datasets for rare disease entity recognition concentrate at three academic medical centers, creating supply bottlenecks for specialized NLP model development.
- Structured data substitution:FHIR-standardized EHR APIs are displacing NLP extraction for medication reconciliation in ambulatory settings, compressing addressable volume in primary care.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in the US Mountain West remain underpenetrated by enterprise NLP vendors due to legacy EHR fragmentation.
- Multimodal diagnostic convergence:Integration of radiology report NLP with DICOM metadata extraction is opening new workflow automation categories in integrated diagnostic networks.
- State algorithmic accountability mandates:New York and California legislation requiring clinical AI transparency documentation is creating compliance-service revenue streams for NLP platform providers.
Industry Challenges
- Clinical informaticist talent scarcity:Health systems face 18-month hiring cycles for specialists capable of bridging NLP model tuning with bedside workflow integration.
- Legacy EHR API fragmentation:Proprietary data exchange protocols at Cerner and Epic installations force costly custom integration engineering for each hospital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Natural Language Processing Market |
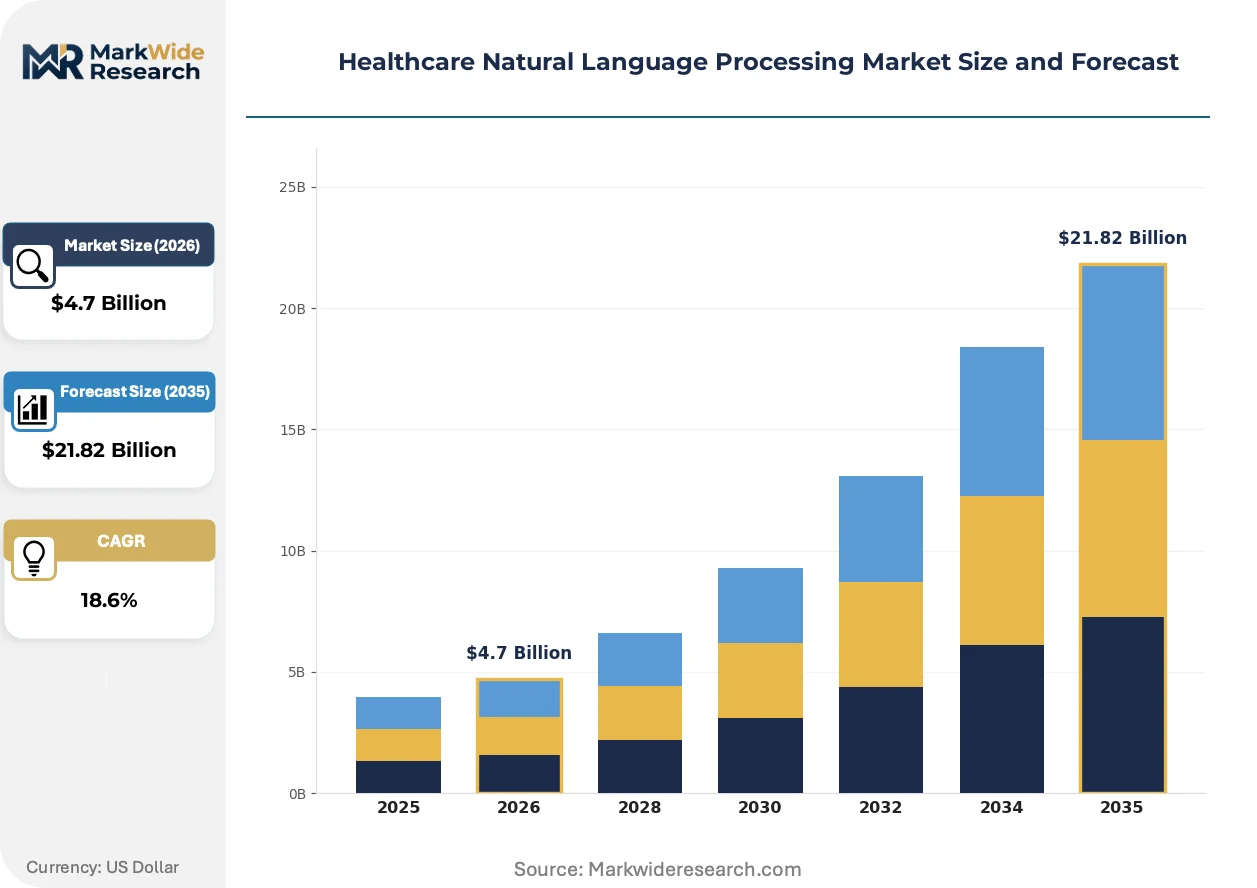
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Text Analytics, Speech Recognition, Machine Translation, Sentiment Analysis End User: Healthcare Providers, Pharmaceuticals, Research Institutions, Health Insurance Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Application: Clinical Documentation, Patient Engagement, Population Health Management, Medical Coding |
| Companies Covered | IBM, Google, Microsoft, Amazon Web Services, IQVIA, Cerner Corporation, Nuance Communications, Optum, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Natural Language Processing Market Shifts & Advancements
Transformer-based clinical language models are compressing development cycles while regulatory sandbox programs are accelerating validation pathways for AI-enabled documentation tools.
Large language models fine-tuned on de-identified clinical notes are rendering obsolete rule-based natural language processing systems that required manual feature engineering for each medical specialty. Health systems with mature data science teams are deploying these models for automated prior authorization drafting, reducing administrative burden. The structural consequence is a consolidation of vendor relationships around platforms offering continuous model retraining capabilities.
The EU AI Act's high-risk system classification for clinical decision-support applications is mandating conformity assessment procedures that extend validation timelines by four to six months. Vendors are responding by establishing dedicated EU regulatory affairs functions and pre-positioning technical documentation for notified body review. Academic medical centers in Germany and France are prioritizing procurement of CE-marked NLP modules to preempt compliance disruption.
Health system procurement committees are unbundling NLP capabilities from monolithic EHR contracts, creating direct vendor relationships for specialized clinical documentation tools. This disintermediation is most pronounced among US-based integrated delivery networks with dedicated innovation budgets, which are running parallel pilot programs with three to four specialized NLP vendors simultaneously. The shift is compressing incumbent platform renewal cycles and elevating interoperability requirements in RFP specifications.
Healthcare Natural Language Processing Market Segmentation
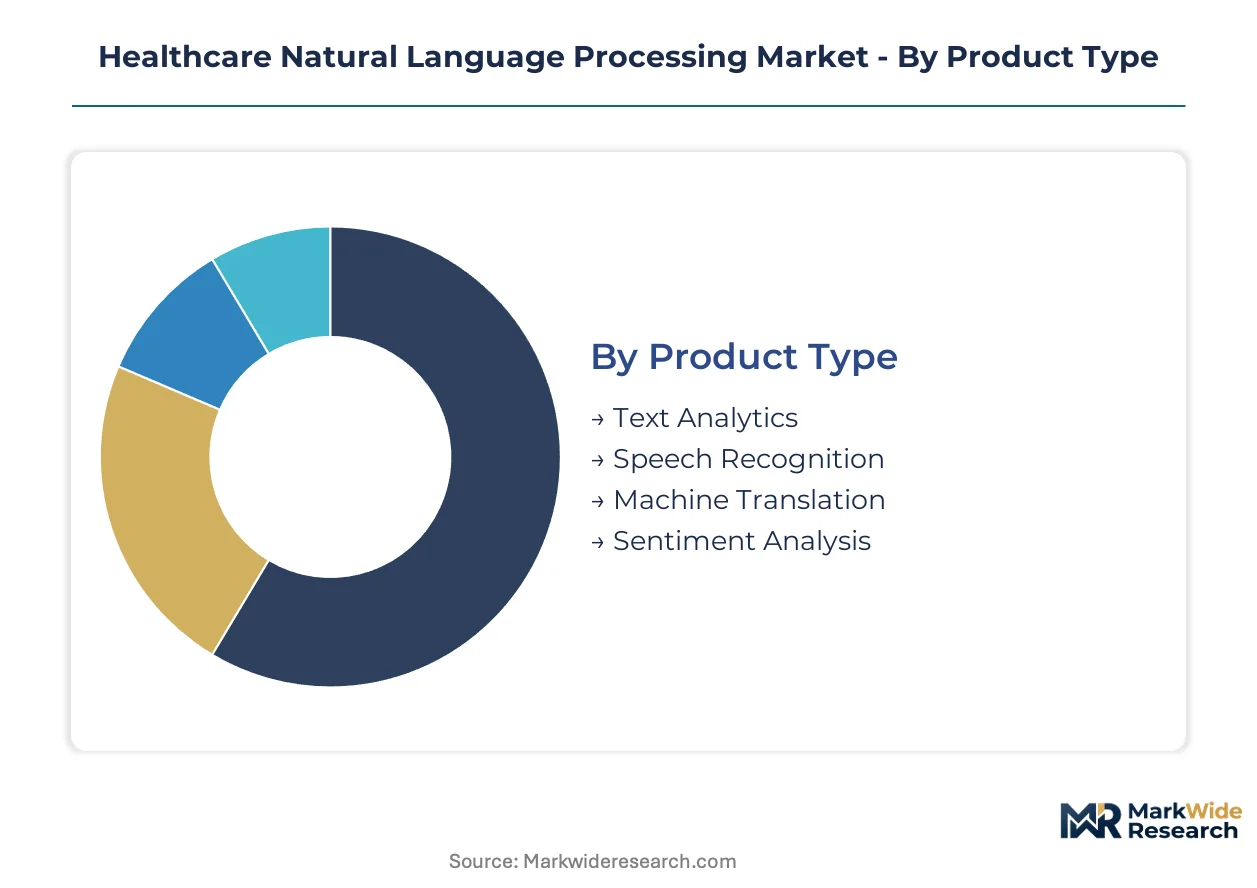
Healthcare NLP procurement cycles vary dramatically by segment, with documentation tools refreshing every 18-24 months while infrastructure deployments stretch across 5-7 year horizons. Understanding these velocity differentials enables vendors to calibrate R&D investment and sales resource allocation against actual revenue recognition timelines.
Product Type:
Speech recognition platforms turn over fastest due to embedded EHR refresh cycles, while machine translation systems exhibit the longest replacement intervals given specialized training requirements and integration complexity.
- Text Analytics:Rule-based and transformer-powered extraction engines that parse unstructured clinical notes for entity recognition and relationship mapping. Demand concentrates in US integrated delivery networks automating prior authorization workflows, driven by CMS documentation requirements for value-based care contracts.
- Speech Recognition:Real-time dictation and ambient clinical documentation systems processing physician-patient encounters with sub-200 millisecond latency. US health systems with Epic and Cerner deployments represent the primary demand concentration, propelled by physician burnout reduction mandates and EHR vendor partnerships.
- Machine Translation:Cross-lingual clinical communication tools enabling non-English patient encounters and multinational trial coordination.
- Sentiment Analysis:Patient experience measurement and social media monitoring applications for reputation management and quality improvement.
Speech recognition dominates installed base. Sentiment analysis is where expansion concentrates.
End User:
Cost tier stratification separates enterprise health systems with dedicated innovation budgets from resource-constrained research institutions operating on grant funding cycles.
- Healthcare Providers:Hospitals, health systems, and physician practices deploying NLP for clinical workflow automation and documentation efficiency. US-based integrated delivery networks with value-based care contracts drive procurement velocity, constrained by 18-month informaticist hiring cycles that delay implementation.
- Pharmaceuticals:Life sciences organizations applying NLP to regulatory submission drafting, pharmacovigilance, and real-world evidence generation. Clinical trial protocol automation and FDA submission preparation represent concentrated demand, fueled by PDUFA timeline pressures and competitive filing urgency.
- Research Institutions:Academic medical centers developing specialized models for rare disease entity recognition and clinical discovery.
- Health Insurance:Payers leveraging NLP for claims adjudication, fraud detection, and member risk stratification.
Healthcare providers absorb the majority of current deployment volume. Pharmaceuticals represent the steepest expansion trajectory.
Deployment:
Volume distribution skews toward cloud-native implementations among new adopters, while data residency requirements sustain hybrid architecture demand among established institutions.
- Cloud-Based:Fully managed SaaS platforms delivering continuous model updates and elastic compute scaling. US health systems consolidating data lakes on HIPAA-compliant infrastructure represent the primary demand locus, driven by federal health IT investment and reduced capital expenditure requirements.
- On-Premises:Air-gapped installations for institutions with strict data sovereignty or classified research mandates.
- Hybrid:Split architectures retaining sensitive processing on-site while leveraging cloud training and model distribution. German and French academic medical centers prioritizing EU AI Act compliance demonstrate concentrated adoption, compelled by pre-certification requirements for high-risk clinical decision-support systems.
- Edge Computing:Distributed processing for point-of-care devices and rural clinic deployments with intermittent connectivity.
Cloud-based deployment captures new implementation majority. Hybrid architectures retain stronghold status among compliance-sensitive institutions.
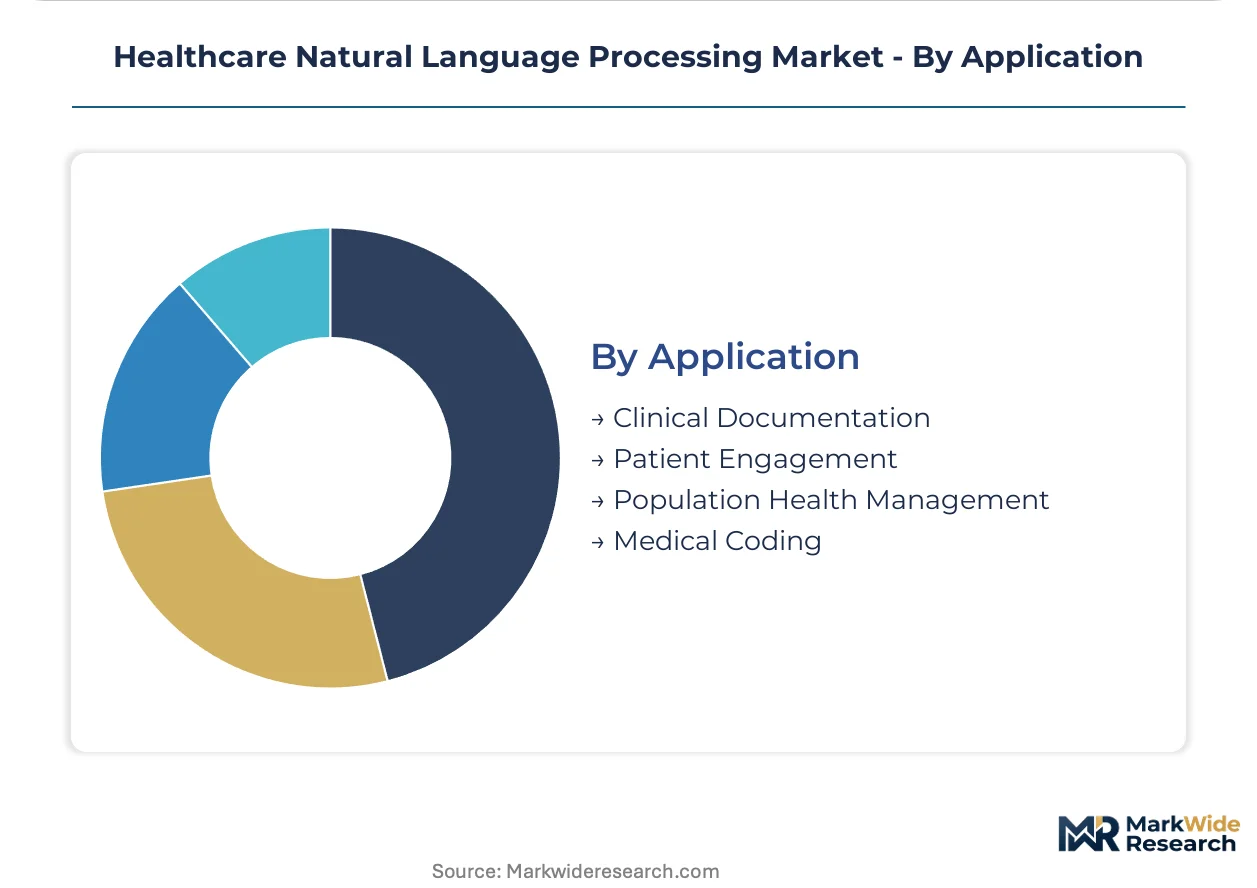
Application:
Customer type differentiation separates acute care documentation priorities from ambulatory population health management requirements.
- Clinical Documentation:Automated note generation, coding suggestion, and encounter summarization for physician workflow efficiency. US health systems with physician burnout reduction initiatives drive concentrated demand, constrained by FDA predicate device pathway timelines for AI-enabled documentation tools.
- Patient Engagement:Conversational interfaces, symptom checkers, and personalized health communication platforms. Health systems prioritizing HCAHPS score improvement and digital front door strategies represent focused demand, propelled by consumerization expectations and reimbursement tie-ins.
- Population Health Management:Risk stratification, care gap identification, and social determinants extraction from unstructured records.
- Medical Coding:Automated ICD-10 and CPT code assignment for billing accuracy and revenue cycle optimization.
Clinical documentation anchors current revenue. Patient engagement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA predicate device pathways and HIPAA technical safeguards anchor procurement decisions in the United States, while the EU AI Act's high-risk classification system is compressing vendor validation timelines across European health systems. Cloud infrastructure investments and federal health IT spending are redrawing competitive boundaries in concentrated national markets.
United States
Integrated delivery networks with value-based care contracts are consolidating data lakes on HIPAA-compliant cloud infrastructure, creating procurement pull for embedded NLP documentation tools. The FDA's evolving guidance on AI-enabled medical devices is reshaping product validation requirements for clinical decision-support modules. Academic medical centers in Boston and the San Francisco Bay Area are prioritizing CE-marked NLP modules to preempt compliance disruption in multinational trial coordination.
Germany
Academic medical centers in Berlin and Munich are prioritizing procurement of CE-marked NLP modules to preempt EU AI Act compliance disruption. The country's national pharmaceutical regulator, BfArM, is aligning with EMA guidance on software-as-medical-device classifications for clinical NLP applications. The Rhine-Ruhr metropolitan region is witnessing concentrated adoption of hybrid deployment architectures retaining sensitive processing on-site.
United Kingdom
NHS England's digitization mandates are accelerating cloud-native NLP procurement for clinical documentation efficiency across integrated care systems. The Medicines and Healthcare products Regulatory Agency is developing post-market surveillance frameworks for AI-enabled medical devices that intersect with NHS data governance requirements. London's health tech cluster is driving pilot programs with specialized NLP vendors for automated prior authorization drafting.
France
Paris-based hospital systems are unbundling NLP capabilities from monolithic EHR contracts, creating direct vendor relationships for specialized clinical documentation tools. ANSM and CNIL oversight is mandating conformity assessment procedures that extend validation timelines for clinical decision-support applications. The Île-de-France region is witnessing concentrated procurement of transformer-based clinical language models for population-scale health analytics.
Japan
PMDA software-as-medical-device classifications are compressing validation timelines for clinical NLP vendors seeking hospital adoption in Tokyo and Osaka metropolitan areas. METI investment in health IT infrastructure is accelerating cloud migration among integrated health systems with strict data residency requirements. The Kansai region's academic medical centers are developing specialized models for rare disease entity recognition.
Healthcare Natural Language Processing Market Competitive Landscape
Cloud hyperscalers and specialized health IT incumbents split the market between infrastructure-layer dominance and workflow-embedded clinical applications. Vendor relationships are consolidating around platforms offering continuous model retraining capabilities. Three archetypes define competitive positioning: cloud-native service providers with population-scale analytics capacity, EHR-integrated documentation specialists with embedded workflow presence, and life sciences platform vendors with regulatory submission expertise. M&A activity targets specialized clinical corpus assets, while strategic partnerships with integrated delivery networks are securing pilot-to-scale conversion pathways.
Within the cloud-native tier, Amazon Web Services and Google exemplify infrastructure-layer positioning through HIPAA-compliant health data lakes and elastic compute scaling for real-time documentation workloads. Microsoft occupies a hybrid archetype spanning Azure AI integration with existing hospital information systems. Cerner Corporation and Nuance Communications anchor the EHR-embedded specialist segment, with the latter representing ambient clinical documentation capabilities acquired into broader health IT platforms.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| Amazon Web Services |
| IQVIA |
| Cerner Corporation |
| Nuance Communications |
| Optum |
| 3M |
| Others |
Supply & Pricing Matrix
The trans-Pacific fiber-optic cable corridor carries de-identified clinical corpus transfers between US academic medical centers and Asian annotation facilities, with bandwidth costs constituting 12-18% of NLP model training overhead and compressing margins for vendors serving mid-tier health systems while enabling premium pricing for HIPAA-compliant sovereign cloud deployments in Germany and France.
Pricing Analysis
US-based cloud-native NLP services command 40-60% premiums over equivalent European offerings due to embedded Epic and Cerner integration engineering. Pricing stratifies across enterprise-grade clinical decision-support modules, mid-market documentation automation, and lightweight API access tiers. Cost compression in the mid-market segment is intensifying because health systems are unbundling NLP from monolithic EHR contracts. Federally qualified health centers in rural markets exhibit highest price sensitivity, while integrated delivery networks with innovation budgets show lowest elasticity.
Supply Chain Analysis
Contract manufacturing of specialized GPU clusters for clinical NLP training concentrates with Taiwan Semiconductor Manufacturing, NVIDIA, and AMD foundry partnerships. The supply chain draws from US-based cloud hyperscalers for elastic compute, Indian and Philippine medical transcription labor pools for annotation services, and German precision engineering for on-premises hardware. Single-source vulnerability in advanced GPU architectures poses structural risk to model development timelines. Distribution runs through direct enterprise sales teams for health systems and channel partners for pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare NLP sits in early-cycle expansion as ambient clinical documentation penetrates from academic medical centers into community hospital networks, with physician burnout reduction mandates accelerating procurement velocity beyond traditional EHR refresh cycles.
For Market Incumbents: Pre-empt disintermediation by health system procurement committees through embedded workflow partnerships with Epic and Cerner that deepen switching costs. Fortify annotation corpus assets through exclusive licensing with Boston and San Francisco Bay Area academic medical centers before specialized rare disease datasets concentrate further. Cloud hyperscaler competition represents the primary margin pressure point; vertical integration into continuous model retraining capabilities is the defensive lever. For New Entrants and Emerging Players: US Mountain West rural health clinics present white-space expansion opportunity given legacy EHR fragmentation and absence of enterprise NLP vendor presence. Target pharmaceutical regulatory submission automation as the most penetrable segment, where PDUFA timeline pressures override procurement risk aversion. Lead with lightweight API-first deployment that bypasses lengthy hospital IT security review cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from health IT conglomerates with undermonetized NLP assets buried in broader documentation portfolios. Long-term viability favors platforms with continuous model retraining infrastructure and established FDA predicate device pathways. Watch health system pilot-to-scale conversion rates as the inflection indicator for enterprise sales cycle normalization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates hospital procurement by satisfying AI-enabled medical device validation requirements. |
| CE Marking Pre-Certification | Enables EU AI Act compliance for clinical decision-support modules in German and French markets. |
| Academic Medical Center Partnership | Secures exclusive access to rare disease annotated corpora for specialized model development. |
| Epic/Cerner Embedded Integration | Captures workflow presence that procurement committees prioritize over standalone alternatives. |
| Continuous Model Retraining Platform | Differentiates vendor relationships as health systems abandon rule-based NLP systems. |
Research Methodology
The analysis maps speech recognition platforms, text analytics engines, machine translation systems, and sentiment analysis tools, each validated through hospital CIOs, clinical informaticists, biomedical engineers, and GPO contracts managers. Primary interviews with health system procurement committees and pharmaceutical regulatory affairs leads combined with secondary validation against FDA 510(k) filings, CMS Medicare documentation requirements, hospital procurement databases, and GPO contract repositories. Bottom-up deployment volume estimates triangulated against top-down cloud infrastructure spending data.
Assumptions held fixed include HIPAA technical safeguard compliance requirements and FDA predicate device pathway timelines, while EU AI Act implementation velocity and health system cloud migration rates were varied across scenarios. Segmentation modeling incorporated deployment architecture, end-user type, application workflow, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted adoption curves weighted by procurement cycle lengths specific to documentation versus infrastructure segments. Forecast inputs included Epic and Cerner EHR refresh schedules and federal health IT investment trajectories.
Practitioners should monitor FDA guidance revisions on AI-enabled medical devices and state-level algorithmic accountability legislation for early signals of compliance burden shifts. Forecasts reflect assumptions about cloud infrastructure cost trajectories and annotation labor market tightness. Quarterly review of health system pilot program conversion rates and EU notified body backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Vocal Biomarkers Market
Health Informatics
Artificial Intelligence in Epidemiology Market
Health Informatics
Healthcare BI Market
Health Informatics
Clinical Intelligence Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Global E-Health Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
Global Non Clinical Information System Market
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Global Cardiology Information System Market