
 Clinical Intelligence Market | 2026-2036
Clinical Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Intelligence Market Analysis
Modular platform bundling is expanding as health systems seek unified clinical intelligence stacks rather than point solutions. Epic Systems Corporation anchors its position through deep EHR integration that locks in longitudinal patient data workflows. Cerner Corporation leverages cloud-native architecture to compete across ambulatory and acute care settings. IBM differentiates through Watson Health's specialized oncology and life sciences analytics modules.
Clinical intelligence encompasses the systematic collection, integration, and analysis of patient data, clinical workflows, and operational metrics to support real-time decision-making in care delivery, typically processing structured and unstructured data through natural language processing engines with sub-second query response thresholds. The technology segment shows AI and machine learning commanding premium pricing as health systems prioritize predictive risk stratification over retrospective reporting. Cloud computing sustains the fastest expansion trajectory as hybrid infrastructure resolves latency concerns for emergency department applications.
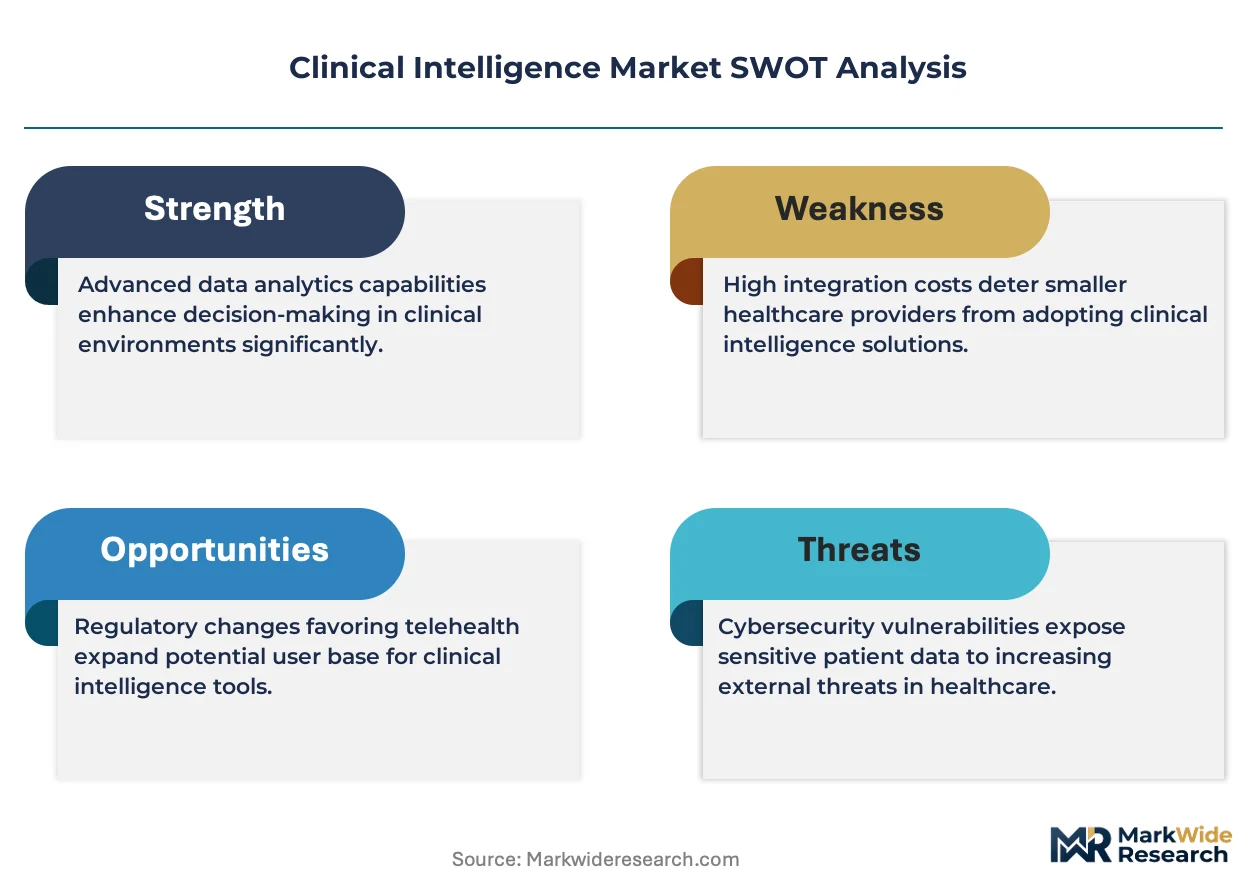
The FDA regulates clinical decision support software under its software-as-medical-device framework, while HIPAA and the 21st Century Cures Act mandate interoperability standards that determine market access for new entrants. The ONC certification program creates compliance gates that favor established vendors with dedicated regulatory affairs teams. Stakeholders must monitor how CMS value-based payment models reshape the business case for population health analytics versus operational efficiency modules.
Market Dynamics
Hospital network consolidation is compressing vendor selection cycles as integrated delivery systems demand unified clinical intelligence stacks rather than fragmented point solutions. This structural pressure favors platform vendors with proven interoperability and regulatory certification depth.
Growth Catalysts
- HIPAA interoperability mandates:The 21st Century Cures Act's information blocking provisions compel health systems to replace siloed data architectures with open APIs, accelerating platform replacement cycles.
- CMS value-based payment models:Medicare's accountable care organization trackings and bundled payment programs create direct financial incentives for predictive analytics investments.
- Cloud-native architecture migration:Health systems are retiring on-premise data warehouses for hybrid cloud deployments that reduce latency in emergency department decision support.
Market Restraints
- ONC certification complexity:The Office of the National Coordinator's rigorous testing requirements create 18-24 month approval timelines that freeze out smaller software vendors lacking dedicated regulatory affairs teams.
- Specialized talent scarcity:The shortage of clinical informaticists with both medical credentials and machine learning expertise inflates implementation costs for advanced analytics modules.
- Legacy EHR lock-in:Deep integration with entrenched electronic health record systems creates switching costs that suppress competitive churn even when superior alternatives exist.
Strategic Opportunities
- Rural health system penetration:Critical access hospitals in the United States remain underserved by enterprise clinical intelligence platforms, presenting white space for modular, lower-cost deployments.
- FDA software-as-medical-device pathway:The agency's clarified guidance for AI-enabled diagnostic support creates a regulatory fast-track for validated algorithms in radiology and pathology.
- Natural language processing and computer vision convergence:Multimodal AI systems that simultaneously parse clinical notes and medical imaging are opening new diagnostic automation categories.
Industry Challenges
- Algorithmic bias validation:Health systems struggle to demonstrate equitable model performance across racial and socioeconomic patient subgroups, exposing institutions to liability and reputational risk.
- Cross-platform data harmonization:Inconsistent terminologies and coding standards between EHR vendors require expensive custom mapping layers that delay implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Intelligence Market |
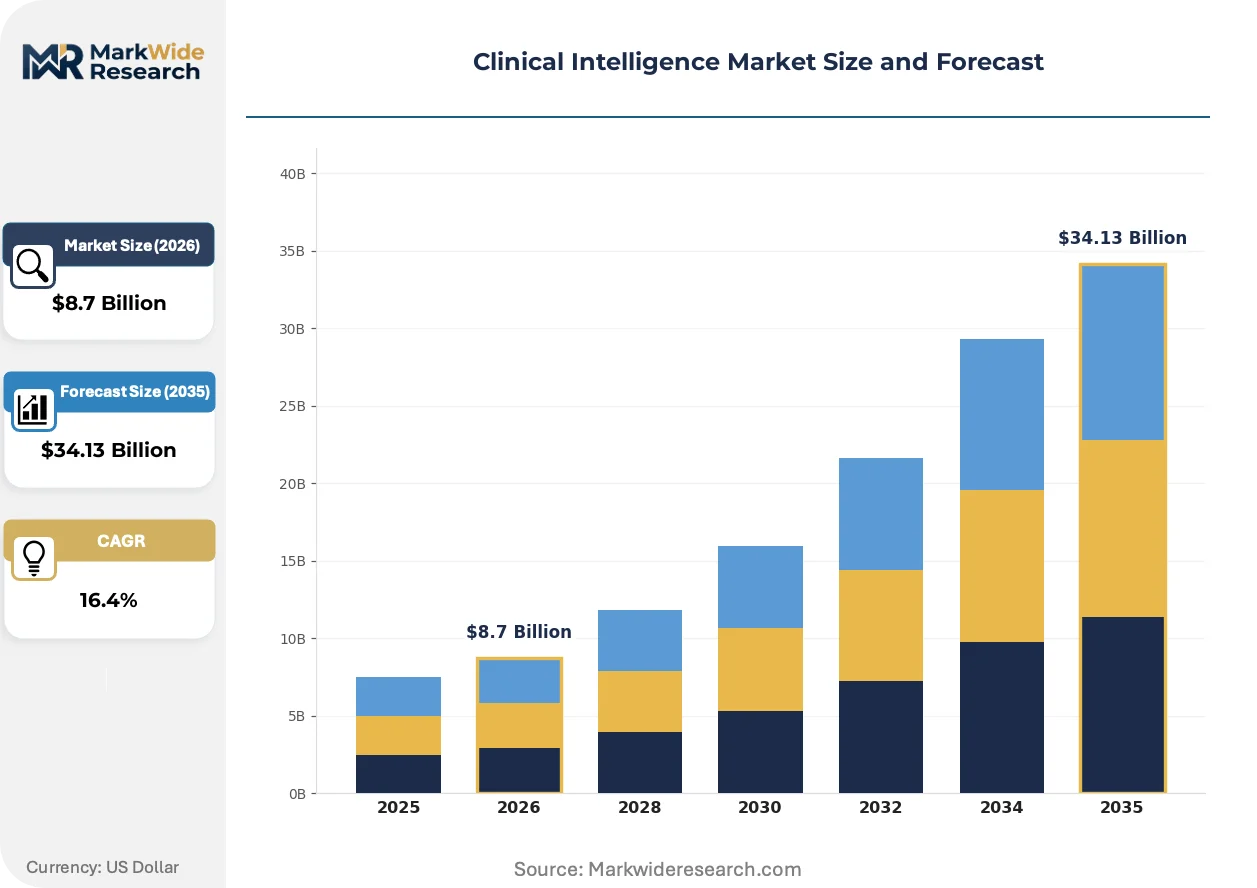
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Analytics, Patient Management, Clinical Decision Support, Risk Management End User: Hospitals, Clinics, Research Institutions, Healthcare Systems Technology: AI, Machine Learning, Cloud Computing, Data Warehousing Application: Operational Efficiency, Patient Engagement, Population Health, Quality Reporting |
| Companies Covered | IBM, Epic Systems Corporation, Cerner Corporation, McKesson Corporation, NXGN Management, LLC, Allscripts Healthcare, LLC, eClinicalWorks, Optum, Inc., IQVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Intelligence Market Emerging Trajectories
Real-time inference at the point of care is displacing retrospective dashboard analytics as the defining capability for clinical intelligence platforms. This shift demands sub-second query response architecture and edge computing deployment models.
Federated learning architectures are overtaking centralized data lakes as the dominant training paradigm for multi-site health systems. Mayo Clinic and Kaiser Permanente are deploying federated networks that train models across institutions without transferring raw patient records. This approach is compressing regulatory review timelines while preserving HIPAA compliance boundaries.
The FDA's software-as-medical-device pre-certification program is creating a two-tier vendor landscape where pre-certified developers gain accelerated review pathways. Device manufacturers with established quality management systems receive prioritized processing for algorithm updates. Smaller AI startups without predicate device experience face extended validation requirements that favor incumbent platform vendors.
Subscription-based platform licensing is displacing perpetual software licenses as the dominant procurement structure among United States health systems. Chief information officers prefer operational expenditure models that bundle implementation, training, and continuous algorithm updates. This shift is most visible among mid-sized regional hospital networks with constrained capital budgets and limited internal IT infrastructure.
Clinical Intelligence Market Segmentation
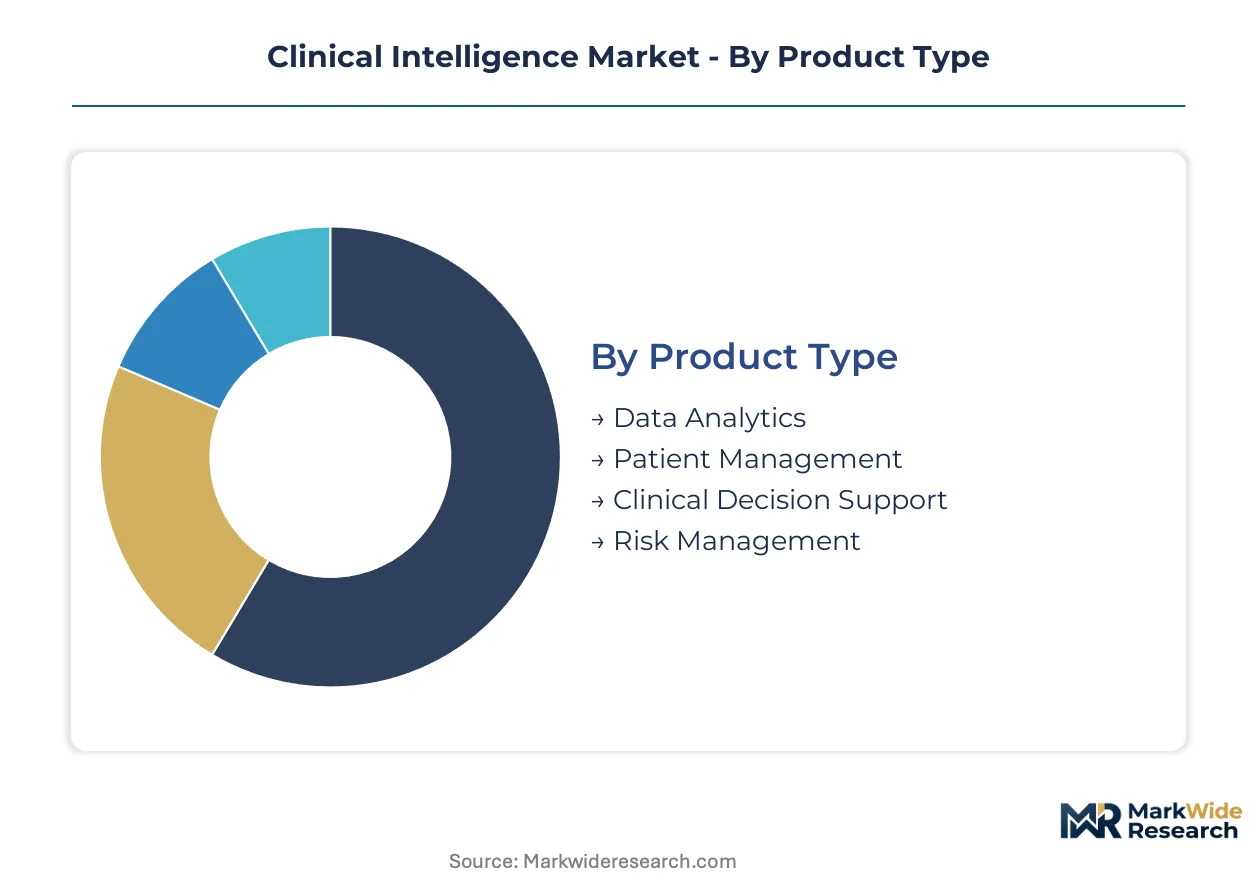
Clinical intelligence platforms serve divergent buyer priorities across care settings, from academic medical centers requiring research-grade analytics to rural hospitals seeking operational dashboards. Segmentation reveals how vendor pricing, deployment complexity, and regulatory certification requirements map to distinct customer archetypes and use cases.
Product Type:
Hospital procurement teams prioritize integration depth and workflow disruption when selecting among clinical intelligence modules, with enterprise buyers favoring unified platforms over point solutions.
- Data Analytics:Processes structured and unstructured clinical data through natural language processing engines to surface population-level patterns. Academic medical centers in the United States drive premium demand for multi-site federated learning deployments that preserve HIPAA boundaries while enabling cross-institutional model training. The 21st Century Cures Act's information blocking provisions accelerate replacement of siloed reporting tools.
- Clinical Decision Support:Delivers real-time alerts and care recommendations at the point of clinical encounter, requiring sub-second query response architecture. Emergency departments and intensive care units concentrate demand as CMS value-based payment models penalize preventable adverse events. FDA software-as-medical-device classification creates compliance gates that favor vendors with established quality management systems.
- Patient Management:Coordinates longitudinal care transitions across ambulatory and acute settings through risk-stratified registries.
- Risk Management:Identifies clinical and operational liabilities through predictive models and automated surveillance of adverse event patterns.
Data analytics leads volumes today; clinical decision support is gaining share fastest.
End User:
Scale of IT infrastructure and regulatory sophistication separates buyers, with integrated delivery systems demanding enterprise-wide governance while standalone clinics prioritize plug-and-play deployment.
- Hospitals:Span academic medical centers, community hospitals, and critical access facilities with divergent analytics maturity. Large health systems in the United States consolidate vendor relationships to reduce interoperability complexity, while rural hospitals remain underserved by modular, lower-cost deployments. ONC certification requirements create 18-24 month procurement cycles that freeze out smaller vendors.
- Healthcare Systems:Encompass integrated delivery networks and accountable care organizations managing population risk across multiple sites. Kaiser Permanente and Mayo Clinic deploy federated learning architectures that train models without transferring raw patient records. Cloud-native platforms displace on-premise data warehouses as hybrid infrastructure resolves latency concerns.
- Clinics:Include ambulatory surgery centers and specialty practices with limited internal IT resources.
- Research Institutions:Drive demand for de-identified data extraction and multi-omic integration capabilities.
Hospitals dominate procurement volumes; healthcare systems show the steepest expansion trajectory.
Technology:
Technical architecture choices determine latency performance, regulatory pathway, and total cost of ownership across deployment scenarios.
- AI:Encompasses deep learning models for diagnostic imaging, clinical note summarization, and treatment recommendation engines. Radiology and pathology departments concentrate early adoption as FDA pre-certification programs create accelerated review pathways for validated algorithms. Algorithmic bias validation requirements expose health systems to liability risk across racial and socioeconomic patient subgroups.
- Cloud Computing:Enables elastic scaling and edge deployment for emergency department applications requiring real-time inference. Hybrid architectures resolve data sovereignty concerns while reducing capital expenditure burdens for mid-sized regional networks. Subscription licensing models displace perpetual software licenses among United States health systems with constrained capital budgets.
- Machine Learning:Powers risk stratification and predictive analytics through supervised learning on historical outcomes data.
- Data Warehousing:Provides centralized repositories for retrospective reporting and regulatory submission workflows.
Cloud computing anchors current deployment volumes; AI is climbing the fastest.
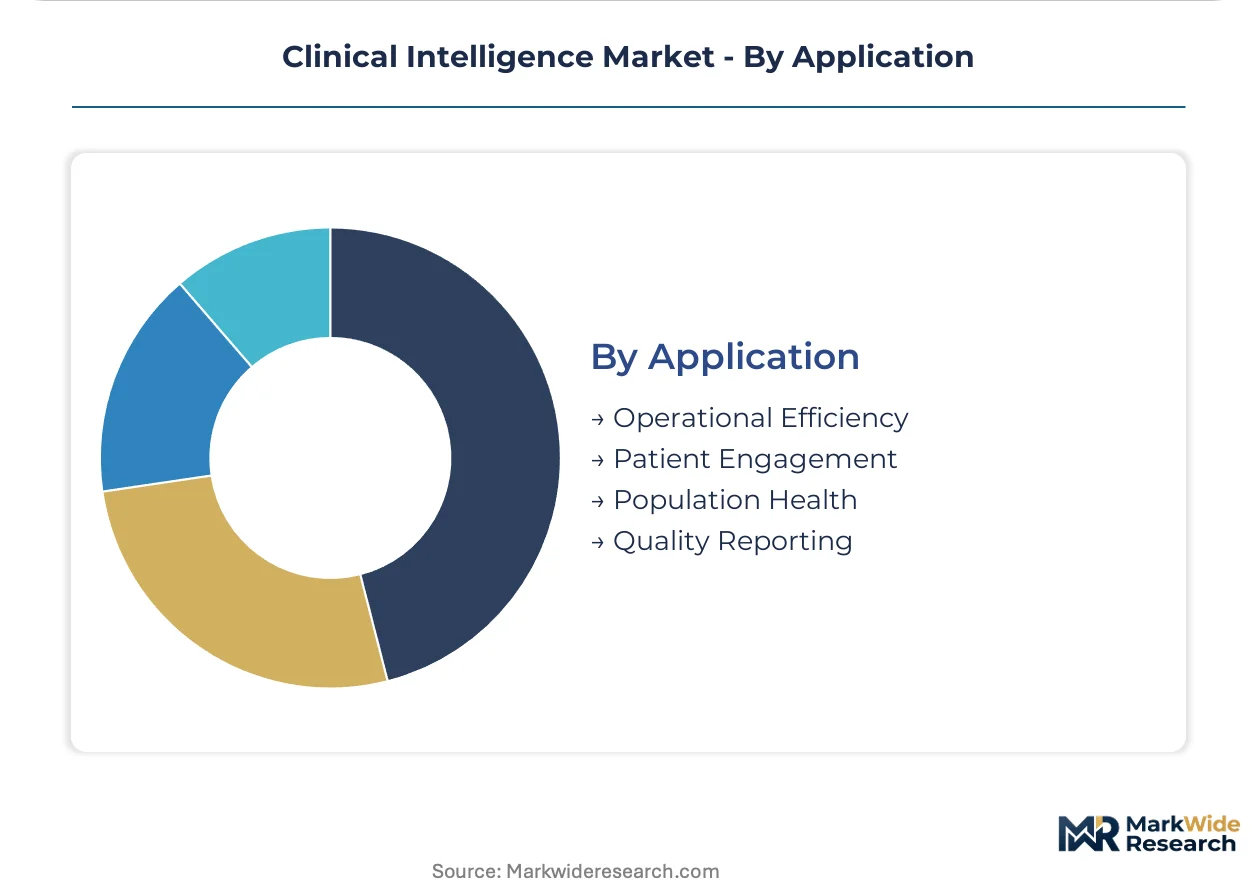
Application:
Financial incentive alignment determines buyer urgency, with CMS payment models directly rewarding population health investments while operational efficiency savings remain harder to attribute.
- Population Health:Aggregates multi-source data to identify care gaps and stratify risk across attributed patient panels. Medicare accountable care organizations and bundled payment programs create direct financial incentives for predictive analytics investments. United States health systems consolidate point solutions into unified platforms to meet HIPAA interoperability mandates.
- Operational Efficiency:Optimizes staffing, throughput, and resource allocation through real-time operational dashboards. Emergency departments and perioperative services concentrate demand as labor costs escalate and capacity constraints intensify. Cloud-native platforms reduce implementation timelines compared to legacy on-premise deployments.
- Patient Engagement:Deploys portals, automated outreach, and personalized education to improve adherence and satisfaction scores.
- Quality Reporting:Automates extraction and submission of measures for CMS, Joint Commission, and payer quality programs.
Population health leads current investment volumes; operational efficiency is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical intelligence platforms originated in the United States during the 1990s with the digitization of hospital records at academic medical centers. Early deployments at Kaiser Permanente and the Mayo Clinic established the template for enterprise-scale analytics. Regulatory frameworks in the US subsequently shaped certification requirements that vendors now navigate worldwide.
United States
Hospital network consolidation drives enterprise-scale deployments as integrated delivery systems demand unified analytics stacks. The FDA's software-as-medical-device guidance and HIPAA interoperability mandates reshape vendor certification requirements. Boston's Longwood Medical Area and California's Kaiser Permanente network anchor federated learning deployments that train models without transferring raw patient records.
Germany
University hospitals in Baden-Württemberg and Bavaria prioritize research-grade analytics for multi-omic integration and clinical trial matching. The EU AI Act and MDR classification rules determine compliance pathways for diagnostic decision support algorithms. Berlin's Charité hospital network collaborates with industrial partners on edge computing architectures for real-time emergency department inference.
United Kingdom
NHS England's federated data platform initiative accelerates procurement of cloud-native clinical intelligence across integrated care systems. The UK Medicines and Healthcare products Regulatory Agency applies software-as-medical-device standards to AI-enabled diagnostic tools. London's NHS trusts and the Oxford-Cambridge arc concentrate deployment of natural language processing engines for clinical note summarization.
Japan
Super-aging demographics intensify demand for predictive risk stratification in chronic disease management at university hospitals. PMDA guidelines for AI-enabled medical devices create structured review pathways for algorithm developers. Tokyo's metropolitan hospital network and Osaka's Kansai medical corridor lead adoption of computer vision systems for diagnostic imaging automation.
Israel
Digital health startups commercialize clinical intelligence modules for export to European and North American hospital systems. The Ministry of Health's digital health sandbox program accelerates validation timelines for AI diagnostic algorithms. Tel Aviv's Sheba Medical Center operates as a living laboratory for multimodal AI systems combining clinical notes and medical imaging.
Clinical Intelligence Market Vendor Landscape
The competitive structure tilts toward platform consolidation as health systems retire fragmented point solutions for unified stacks. Epic Systems Corporation and Cerner Corporation anchor the landscape through deep electronic health record integration that locks in longitudinal patient data workflows. Three archetypes dominate: EHR-native platform vendors, cloud-native analytics specialists, and research-focused life sciences modules. M&A activity concentrates on acquiring interoperability assets and regulatory certification expertise. Strategic partnerships between academic medical centers and technology vendors accelerate federated learning deployment.
Within the EHR-native tier, Epic Systems Corporation and Cerner Corporation exemplify vendors whose market position derives from workflow integration depth rather than standalone analytics performance. IBM occupies a specialized position through Watson Health's oncology and life sciences focus. These three entities represent distinct competitive vectors—EHR lock-in, cloud architecture, and vertical AI specialization—that shape procurement criteria for hospital networks evaluating platform replacement.
| Leading Market Players |
|---|
| IBM |
| Epic Systems Corporation |
| Cerner Corporation |
| McKesson Corporation |
| NXGN Management, LLC |
| Allscripts Healthcare, LLC |
| eClinicalWorks |
| Optum, Inc. |
| IQVIA |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure spot pricing indices cascade through clinical intelligence vendor cost structures, compressing margins for mid-tier platform providers while enabling SaaS-tiered pricing differentiation that separates enterprise health system deployments from modular point solutions aimed at critical access hospitals.
Pricing Analysis
Subscription-based platform licensing with tiered performance levels dominates procurement as chief information officers prefer operational expenditure models bundling implementation, training, and continuous algorithm updates. Price differentiation hinges on ONC certification depth and real-time query response thresholds, with emergency department sub-second latency commanding premium positioning. Cost compression in the mid-market intensifies as Epic Systems and Cerner leverage EHR-native integration to bundle analytics at marginal cost. Critical access hospitals exhibit highest price sensitivity, while academic medical centers prioritize research-grade federated learning capabilities over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers Amazon Web Services, Microsoft Azure, and Google Cloud Platform, which anchor compute infrastructure for hybrid clinical intelligence deployments. GPU accelerator supply draws from Taiwan Semiconductor Manufacturing and NVIDIA's foundry partnerships, while natural language processing engines rest on proprietary training datasets locked within Epic's Cosmos and Cerner's HealtheIntent networks. Tariff exposure on semiconductor components threatens edge computing hardware timelines for emergency department inference. Distribution runs through health system group purchasing organizations and direct enterprise sales teams, with regional implementation partners handling rural hospital deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clinical intelligence market reads as a late-cycle quality story where hospital network consolidation filters procurement toward platforms with proven interoperability depth and regulatory certification track records, as value-based payment models from CMS reward predictive analytics investments over retrospective reporting tools.
For Market Incumbents: Extend platform consolidation momentum by acquiring interoperability assets and regulatory affairs expertise from smaller AI startups facing ONC certification bottlenecks. Deepen backward integration into cloud-native architecture development to reduce hyperscaler dependency and defend margin position against cloud-native analytics specialists. Prioritize federated learning network expansion with academic medical centers to lock in research-grade data partnerships. For New Entrants and Emerging Players: Begin with modular, lower-cost deployments targeting critical access hospitals in rural United States markets underserved by enterprise platform vendors. Pursue FDA software-as-medical-device pre-certification for narrow diagnostic applications in radiology or pathology where validation pathways are clarified. Leverage channel partnerships with regional health information exchanges rather than competing directly for integrated delivery system contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory certification complexity creates 18-24 month approval timelines that freeze out smaller vendors lacking dedicated compliance teams. Long-term viability favors platform vendors with established EHR integration depth and recurring revenue bases above project-based implementation models. Watch for inflection signals in CMS value-based payment model expansion that accelerate predictive analytics procurement cycles beyond operational efficiency investments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates review timelines for AI-enabled diagnostic algorithms in radiology and pathology applications. |
| Hospital System Partnership | Locks in longitudinal patient data workflows through deep EHR integration with Epic or Cerner platforms. |
| Federated Learning Network | Enables Mayo Clinic and Kaiser Permanente to train models across institutions without HIPAA boundary violations. |
| Cloud-Native Architecture Migration | Reduces latency for emergency department decision support while shifting capital expenditure to operational models. |
| Regulatory Affairs Team Expansion | Addresses ONC certification complexity that creates 18-24 month procurement cycles freezing out smaller competitors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital chief information officers, clinical informaticists, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, CMS Medicare claims data, hospital procurement databases, and ONC certification records. Bottom-up vendor revenue estimates and top-down health system IT spending analysis provided cross-checks on market sizing.
Comparable-period anchoring linked projection assumptions to historical deployment trajectories across the analysis window, with segmentation modeling across product type, end user, technology architecture, and application use case. CAGRs derived from logistic adoption curves fitted to health system digitization maturity patterns, incorporating cloud infrastructure capex disclosures and EHR vendor reported analytics module attach rates as industry-specific inputs.
Several conditions sit outside the modeled scope, including potential algorithmic bias litigation outcomes, unexpected FDA software-as-medical-device reclassification, and macroeconomic disruptions to health system capital budgets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare API Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Global Laboratory Information Management System (LIMS) Market
Health Informatics
IHE XDS.B Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
Global Laboratory Information System Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
AI in Healthcare Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Global Healthcare Cognitive Computing Market