
 Healthcare API Market | 2026-2036
Healthcare API Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare API Market Intelligence
Payer organizations are bifurcating from hospital-centric procurement toward direct API contracting with specialized vendors. Epic Systems Corporation anchors its position through deep EHR integration that locks in provider workflows. Microsoft Corporation leverages its Azure cloud footprint to capture enterprise-scale healthcare contracts. MuleSoft, LLC specializes in middleware connectivity that bridges legacy systems with modern cloud architectures.
A Healthcare API is a software interface that enables standardized data exchange between disparate health information systems using protocols such as HL7 FHIR, REST, and OAuth 2.0 security frameworks, serving primarily to eliminate information silos across clinical, administrative, and financial workflows. Integration API deployments dominate current infrastructure spending as health systems prioritize EHR connectivity over greenfield analytics investments. Cloud-Based deployment is expanding fastest among telehealth providers seeking elastic capacity without capital-intensive server commitments. Payment API functionality commands premium positioning as real-time claims adjudication becomes a competitive differentiator for insurers.
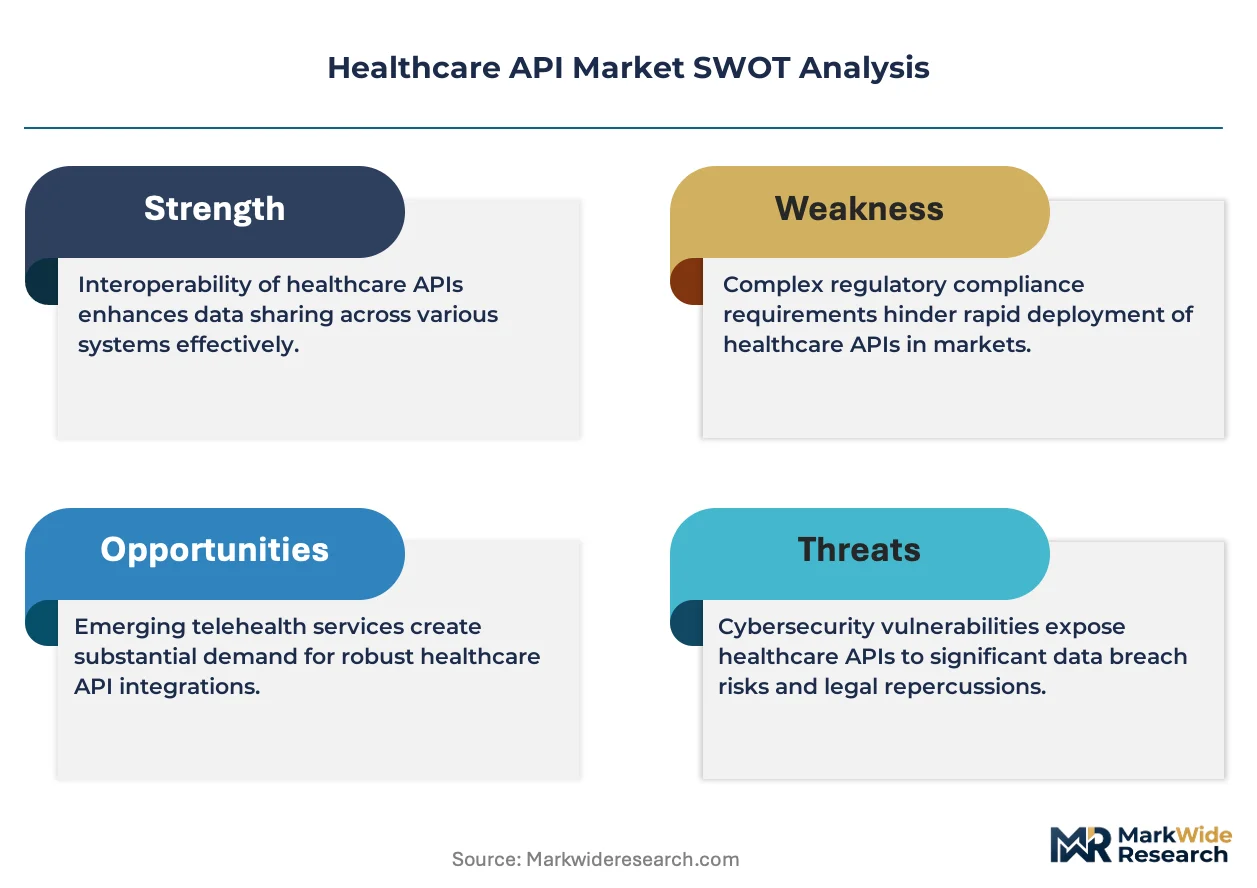
The FDA enforces interoperability standards under the 21st Century Cures Act, while HIPAA mandates encryption and access controls that shape API security architecture, and ONC certification rules gate market access for vendors serving federally funded providers. Stakeholders must monitor how CMS reimbursement policies for remote patient monitoring will reshape API traffic patterns between clinical endpoints and payer systems.
Market Dynamics
Payer-provider data friction is compressing procurement cycles as health systems abandon multi-year EHR lock-ins for modular API contracts that promise faster claims adjudication and real-time eligibility verification.
Growth Catalysts
- CMS Remote Patient Monitoring Reimbursement:Medicare payment codes for RPM services are forcing health systems to deploy patient-facing APIs that stream biometric data directly into clinical workflows.
- Telehealth Volume Concentration:Virtual care platforms in the United States are scaling API infrastructure to handle episodic visit spikes without capital-intensive server commitments.
- HL7 FHIR R4 Mandates:The ONC's interoperability final rule requires standardized data exchange, compelling EHR vendors to open proprietary systems through certified APIs.
Market Restraints
- Cloud Concentration Risk:Three hyperscalers control the majority of healthcare API hosting infrastructure, creating single-point-of-failure exposure for critical patient data pipelines.
- Cybersecurity Talent Scarcity:HIPAA Security Rule compliance demands specialized engineers that command premium salaries, inflating operational costs for mid-sized API vendors.
- Legacy System Technical Debt:Decades-old hospital information systems lack RESTful architecture, forcing expensive middleware layers that erode API deployment margins.
Strategic Opportunities
- Prior Authorization Automation:Real-time pharmacy benefit APIs are eliminating manual fax workflows between prescribers and PBMs, opening white space for specialized intermediaries.
- Social Determinant Data Integration:Housing, transportation, and food security APIs are converging with clinical records to enable value-based care contracts in Medicaid expansion states.
- India's Digital Health Stack:The country's ABHA identifier system and health claims exchange are creating standardized API infrastructure for exportable telehealth platforms.
Industry Challenges
- Multi-Jurisdictional Compliance Burden:API vendors serving cross-border telehealth must reconcile HIPAA encryption standards with GDPR data residency requirements and state-level breach notification laws.
- Interoperability Certification Delays:ONC's rigorous testing procedures for FHIR API certification extend product launch timelines by 8-14 months, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare API Market |
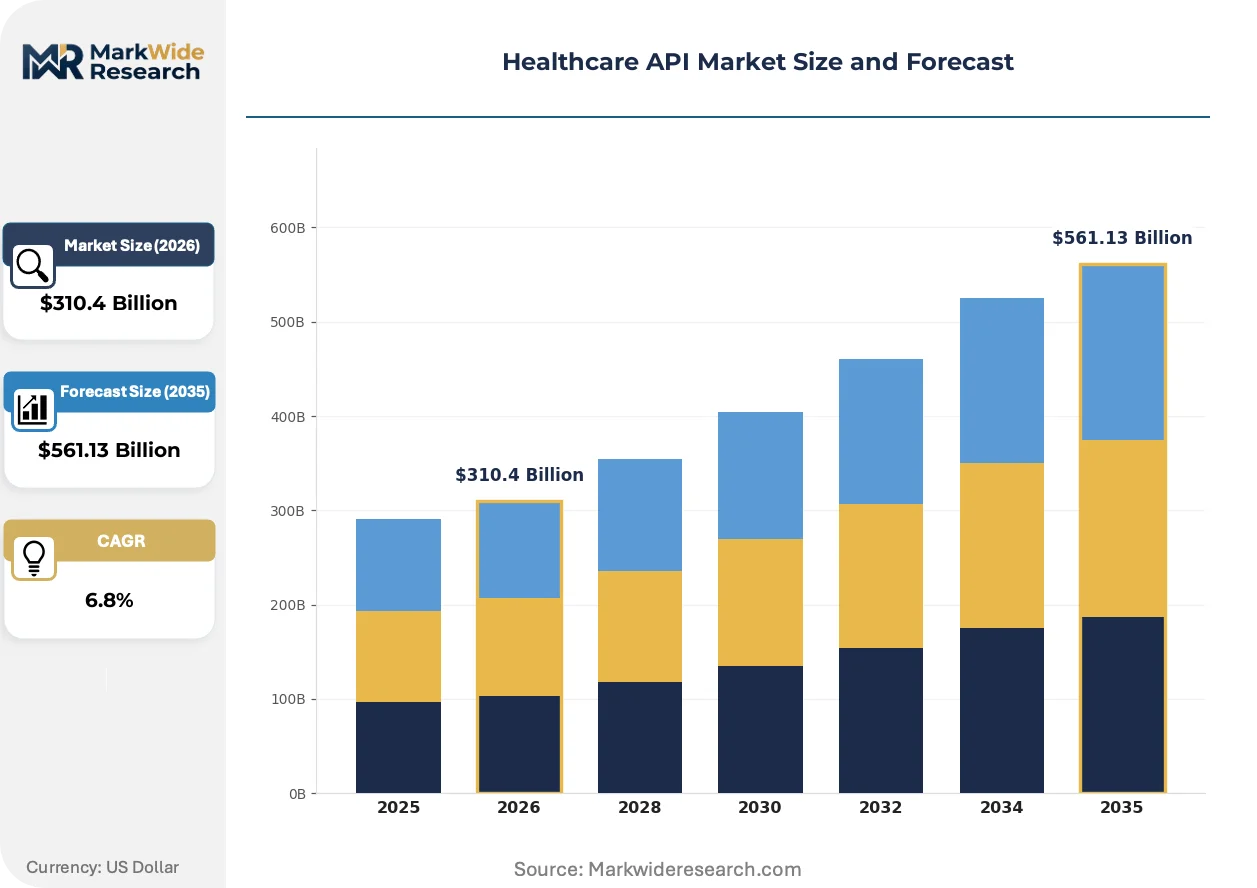
| Market Size in 2026 | $310.4 Billion |
| Market Size in 2035 | $561.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integration API, Data API, Messaging API, Payment API End User: Hospitals, Clinics, Telehealth Providers, Health Insurance Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Functionality: Data Exchange, Security Protocols, Interoperability Standards, Analytics Tools |
| Companies Covered | Microsoft Corporation, Apple, Inc., Epic Systems Corporation, MuleSoft, LLC, General Electric Company, Greenway Health, LLC, Practice Fusion, Inc., Allscripts Healthcare Solutions, eClinicalWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare API Market Strategic Shifts & Innovations
Real-time data streaming is displacing batch-processing architectures across payer and provider systems, forcing infrastructure reinvestment and reshaping vendor competitive positioning.
FHIR-native API gateways are displacing legacy HL7 v2 interface engines in hospital IT departments. Large health systems in Texas and California are deploying these gateways to enable third-party app ecosystems without core EHR modifications. The structural shift is compressing integration timelines from months to weeks while exposing incumbent vendors to disintermediation.
The FDA's interoperability enforcement under the 21st Century Cures Act is compelling EHR developers to publish standardized APIs or face information blocking penalties. This regulatory pressure is accelerating vendor compliance investments and creating certification bottlenecks at ONC-authorized testing laboratories. Specialty EHR vendors serving ambulatory surgery centers are experiencing the steepest compliance cost escalation.
Direct contracting between payers and API specialists is fragmenting traditional channel structures dominated by EHR-embedded solutions. UnitedHealth and CVS Health are building proprietary API marketplaces that bypass legacy vendor distribution, concentrating procurement influence among the largest national insurers. This pattern is most pronounced in Florida and Arizona markets where Medicare Advantage penetration drives advanced analytics demand.
Healthcare API Market Segmentation
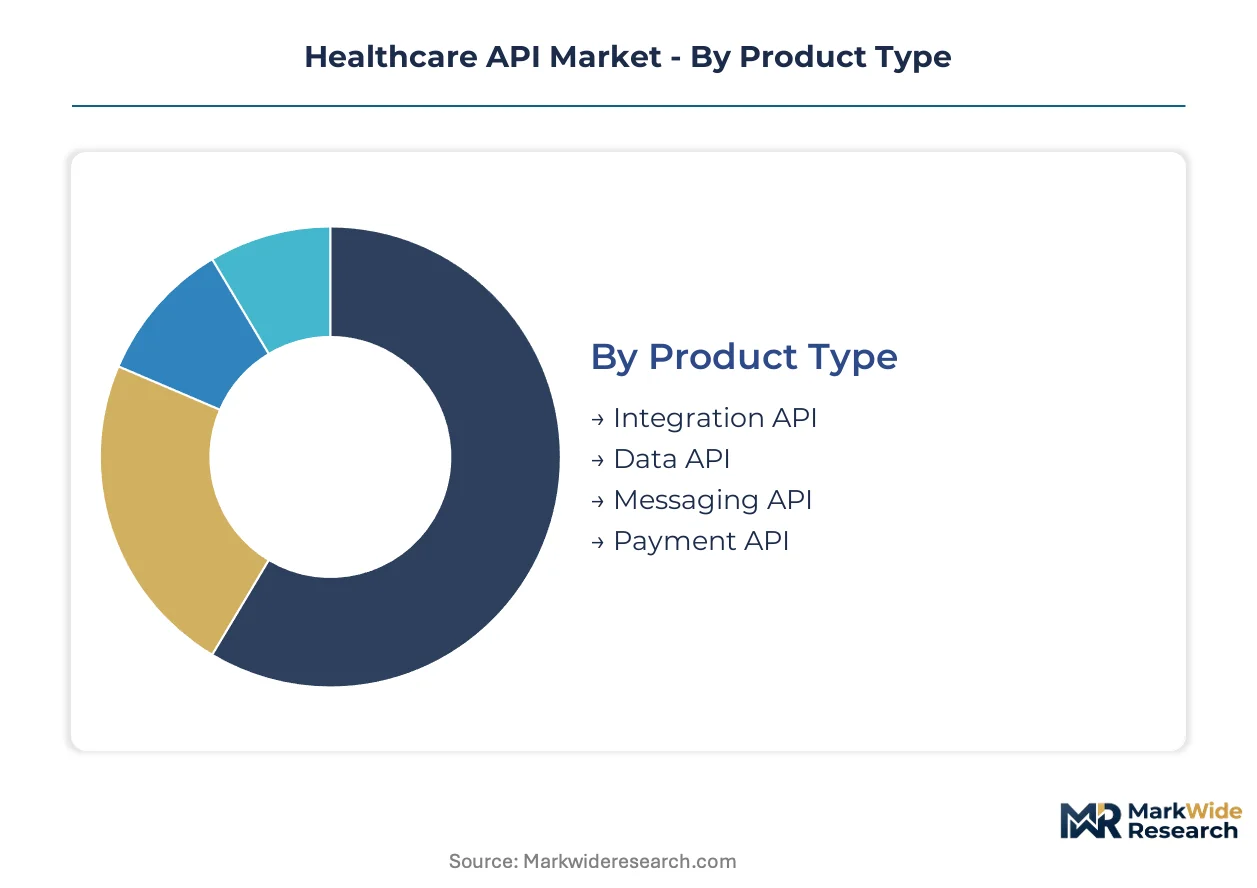
Healthcare API segmentation reveals how procurement channels fragment across institutional buyers and deployment architectures. Each category maps distinct technical requirements to specific compliance burdens and integration timelines.
Product Type:
Integration APIs flow through EHR vendor channels, while Payment APIs increasingly route through direct payer contracting bypassing traditional distribution.
- Integration API:Middleware solutions bridge HL7 v2 legacy systems with FHIR-native cloud architectures using RESTful protocols. Hospital IT departments in Texas and California are deploying these gateways to enable third-party app ecosystems without core EHR modifications, compressing integration timelines from months to weeks.
- Payment API:Real-time claims adjudication engines connect providers directly to payer systems using X12 EDI standards and emerging FHIR financial resources. UnitedHealth and CVS Health are building proprietary marketplaces that bypass legacy vendor distribution, concentrating procurement influence among national insurers in Florida and Arizona Medicare Advantage markets.
- Data API:Structured clinical data access layers enable patient record retrieval and population health queries.
- Messaging API:Asynchronous communication protocols support care coordination alerts and patient outreach workflows.
Integration API dominates installed base. Payment API is where expansion concentrates.
End User:
Cost tier stratification separates enterprise health systems from ambulatory and virtual care platforms.
- Telehealth Providers:Virtual care platforms require elastic API infrastructure to handle episodic visit spikes without capital-intensive server commitments. These organizations prioritize cloud-native deployment models and are scaling fastest among United States digital health startups seeking rapid geographic expansion.
- Hospitals:Large health systems demand comprehensive API suites spanning clinical, administrative, and financial workflows with deep EHR integration that locks in provider workflows. Epic Systems Corporation anchors this segment through entrenched infrastructure relationships.
- Clinics:Ambulatory settings require lightweight, modular API contracts with faster implementation cycles.
- Health Insurance:Payer organizations are bifurcating from hospital-centric procurement toward direct API contracting with specialized vendors for real-time eligibility verification.
Hospitals anchor current revenue concentration. Telehealth Providers are climbing the fastest.
Deployment:
Volume distribution shifts dramatically as telehealth scale demands elastic capacity without hardware procurement cycles.
- Cloud-Based:Hyperscaler-hosted solutions provide auto-scaling compute resources for variable patient encounter volumes. Microsoft Corporation leverages its Azure cloud footprint to capture enterprise-scale healthcare contracts, though three hyperscalers control the majority of infrastructure creating single-point-of-failure exposure.
- Hybrid:Split architectures keep protected health information on-premises while routing analytics workloads to cloud environments. Health systems facing HIPAA Security Rule compliance demands are adopting this model to balance control with flexibility, particularly where cybersecurity talent scarcity inflates operational costs.
- On-Premises:Self-managed server infrastructure persists in security-sensitive settings with dedicated IT operations.
- Edge Computing:Distributed processing nodes enable low-latency biometric data streaming for remote patient monitoring devices.
On-Premises retains legacy footprint. Cloud-Based is gaining share fastest.
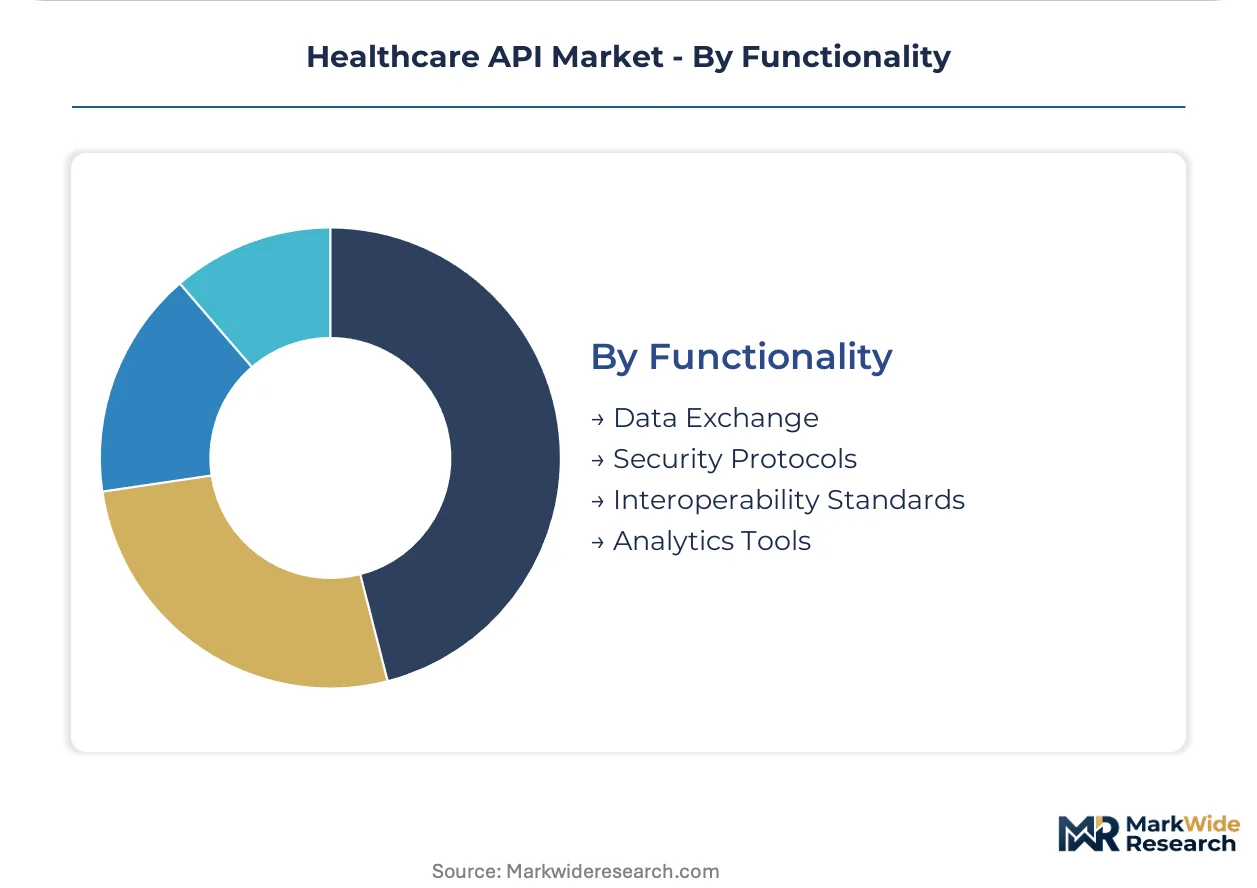
Functionality:
Application maturity separates foundational interoperability from advanced analytics capabilities.
- Interoperability Standards:FHIR R4 implementation and HL7 v2 compatibility layers form the technical foundation for ONC certification compliance. The FDA's interoperability enforcement under the 21st Century Cures Act is compelling EHR developers to publish standardized APIs or face information blocking penalties, accelerating vendor compliance investments.
- Security Protocols:OAuth 2.0 frameworks, encryption at rest and in transit, and audit logging mechanisms address HIPAA mandates. Multi-jurisdictional API vendors must reconcile these encryption standards with GDPR data residency requirements and state-level breach notification laws.
- Data Exchange:Bidirectional information flows between disparate health information systems.
- Analytics Tools:Population health insights and predictive risk stratification capabilities.
Data Exchange underpins current infrastructure. Interoperability Standards is where steepest expansion trajectory lies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports API infrastructure expertise to Southeast Asian telehealth platforms, while United States health systems import FHIR compliance consulting from European specialists. Cross-border data flow corridors concentrate between these three poles, with regulatory divergence shaping procurement patterns.
United States
Medicare Advantage penetration in Florida and Arizona drives demand for real-time claims APIs, while hospital consolidation in Texas and California accelerates EHR gateway procurement. HIPAA and the FDA's 21st Century Cures Act interoperability mandates enforce encryption and access control standards. The Dallas-Fort Worth metro anchors health system IT procurement, where Epic Systems Corporation maintains entrenched infrastructure relationships.
Germany
Hospital digitization funding under the Hospital Future Act (KHZG) channels investment into FHIR-native integration layers. GDPR data residency requirements intersect with national electronic health record infrastructure (gematik) specifications. The Berlin-Brandenburg cluster hosts middleware specialists bridging legacy hospital systems with cloud architectures.
India
ABHA identifier system deployment and the health claims exchange platform create standardized API infrastructure for domestic and exportable telehealth solutions. CDSCO digital health guidance shapes vendor compliance investments. The Bengaluru-Hyderabad corridor concentrates health-tech engineering talent for API gateway development.
United Kingdom
NHS England's Federated Data Platform procurement drives demand for interoperability standards compliance. UK GDPR and NHS Digital security requirements govern data exchange architecture. The London-Southeast cluster concentrates health informatics consultancies supporting NHS trust API implementations.
Japan
Ministry of Economy, Trade and Industry (METI) smart healthcare initiatives promote FHIR adoption for cross-provider data sharing. Pharmaceutical and Medical Devices Agency (PMDA) software as medical device guidance shapes clinical API validation requirements. The Tokyo-Kanto region anchors health IT procurement for integrated delivery networks.
Healthcare API Market Key Industry Players
Listed leaders compete with private specialists across cloud infrastructure and EHR-embedded distribution channels. Microsoft Corporation and General Electric Company leverage public market capital for hyperscale data center expansion, while Epic Systems Corporation and MuleSoft, LLC operate with private strategic flexibility. Three archetypes dominate: cloud-native platform providers, EHR-anchored incumbents, and middleware connectivity specialists. Competitive moves concentrate on direct payer contracting partnerships and FHIR certification acceleration to bypass ONC testing bottlenecks.
Among cloud-native platform providers, Microsoft Corporation occupies a position exemplifying enterprise-scale healthcare contracts through Azure infrastructure. Epic Systems Corporation and MuleSoft, LLC represent contrasting archetypes—EHR-embedded workflow lock-in versus middleware bridge solutions for legacy system modernization. These three anchors illustrate how vendor positioning fragments across deployment architecture preferences and procurement channel strategies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Apple, Inc. |
| Epic Systems Corporation |
| MuleSoft, LLC |
| General Electric Company |
| Greenway Health, LLC |
| Practice Fusion, Inc. |
| Allscripts Healthcare Solutions |
| eClinicalWorks |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud capacity utilization in the United States creates asymmetric cost structures that compress price floors for mid-tier API vendors while concentrating margin power among three dominant infrastructure providers. This scale dynamic forces smaller middleware specialists to absorb certification and compliance costs that larger platforms distribute across enterprise contracts, reshaping procurement negotiations between health systems and specialized vendors.
Pricing Analysis
HL7 FHIR R4-certified API gateways command substantial premiums over legacy HL7 v2 interface engines, while next-generation AI-augmented analytics APIs remain in pilot pricing phases with value-based contract structures. SaaS-tiered subscription models dominate deployment economics, with price differentiation driven by ONC certification tier and embedded security protocol depth. Pricing pressure stems from UnitedHealth and CVS Health building proprietary marketplaces that bypass traditional vendor distribution channels. Telehealth providers exhibit highest price sensitivity due to episodic volume unpredictability, while large hospital systems anchored to Epic workflows demonstrate lowest sensitivity given switching cost barriers.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for healthcare API hosting, while India concentrates engineering talent for gateway development and Germany specializes in FHIR compliance consulting for European hospital digitization. Raw material dependencies center on cryptographic hardware security modules, open-source FHIR framework libraries, and OAuth 2.0 identity management components. Supply chain risk concentrates in single-source hyperscaler vulnerability where three providers control majority hosting capacity. Distribution runs through direct payer contracting channels that fragment traditional EHR-embedded procurement structures, particularly in Florida and Arizona Medicare Advantage markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized FHIR engineering talent scarcity constrains vendor scaling velocity, with HIPAA Security Rule compliance expertise commanding premium compensation that inflates operational costs disproportionately for mid-sized API developers. This capability gap creates defensive moats for incumbents with certified workforce depth while exposing resource-constrained entrants to certification timeline compression.
For Market Incumbents: Consolidate certification advantage by accelerating ONC testing laboratory partnerships to compress FHIR R4 validation timelines ahead of emerging middleware specialists. Deepen vertical integration into cloud infrastructure layers to reduce hyperscaler dependency exposure. Defend against direct payer contracting fragmentation by embedding workflow lock-in through Epic EHR integration depth that raises switching costs for hospital IT departments in Texas and California consolidation markets. For New Entrants and Emerging Players: Prior authorization automation workflows represent the most penetrable service-layer gap where manual fax processes persist between prescribers and PBMs. Target Medicaid expansion states for social determinant data integration APIs that converge housing, transportation, and food security records with clinical workflows. Deploy India-exportable telehealth platform architectures leveraging ABHA identifier standardization to capture Southeast Asian market development ahead of domestic infrastructure maturation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors middleware connectivity specialists bridging legacy HL7 v2 systems with FHIR-native cloud architectures over pure cloud-native platform providers facing hyperscaler margin compression. Long-term viability across the projection horizon rests on certification backlog management capability and direct payer marketplace access. Acquisition target archetype: FHIR-certified specialists with established UnitedHealth or CVS Health marketplace presence. Signal to watch: CMS remote patient monitoring reimbursement code expansion reshaping API traffic volume concentration between clinical endpoints and payer systems.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR R4 Certification Acceleration | ONC testing laboratory partnerships compress product launch timelines by 8-14 months ahead of competitors. |
| Direct Payer Marketplace Integration | UnitedHealth and CVS Health proprietary API marketplaces bypass legacy EHR-embedded distribution channels. |
| Legacy System Bridge Development | HL7 v2-to-FHIR middleware solutions capture hospital technical debt modernization budgets in Texas and California. |
| Remote Patient Monitoring API Deployment | CMS reimbursement codes for RPM services force patient-facing biometric data streaming infrastructure investment. |
| India Health Stack Export Platform | ABHA identifier system standardization enables telehealth platform replication across Southeast Asian markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings from cloud infrastructure providers, CMS Medicare reimbursement databases, and ONC interoperability certification records. Primary interviews engaged health system CIOs, payer digital transformation officers, FHIR implementation specialists, and hospital procurement committee members across United States consolidation markets. Secondary validation incorporated FDA 21st Century Cures Act enforcement documentation, hyperscaler healthcare vertical capex disclosures, and GPO contract aggregation databases. Bottom-up deployment volume estimates triangulated against top-down addressable market sizing derived from health system IT budget allocation patterns.
Segmentation dimensions modeled span product type (Integration, Payment, Data, Messaging API), deployment architecture (Cloud-Based, Hybrid, On-Premises, Edge Computing), end-user category (Telehealth Providers, Hospitals, Clinics, Health Insurance), and functionality layer (Interoperability Standards, Security Protocols, Data Exchange, Analytics Tools). CAGRs were derived from regression analysis of historical procurement cycle data projected across the analysis window. Industry-specific forecast inputs incorporated HL7 FHIR adoption velocity metrics and CMS remote patient monitoring reimbursement policy trajectory.
Underlying assumptions cover sustained HIPAA encryption standard enforcement, continued ONC certification rule stringency, and hyperscaler cloud infrastructure capacity expansion, with deviation risk concentrated in multi-jurisdictional compliance burden escalation and cybersecurity talent scarcity wage inflation. Recalibration cycles align with material shifts in FDA interoperability enforcement patterns and CMS reimbursement code expansion events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Interoperability Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Global Healthcare Integration Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Global Radiology Information Systems Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Healthcare Electronic Data Interchange (EDI) Market
Health Informatics
USA Electronic Health Records (EHR) Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Middle East and Africa Healthcare Archiving and Ediscovery Market
Health Informatics
North America Laboratory Information System Market