
 IHE XDS.B Market | 2026-2036
IHE XDS.B Market Size, Share, and Industry Trends Forecast 2026-2036
IHE XDS.B Market Foresight
The United States is rewriting competitive dynamics in cross-enterprise document sharing as federal interoperability mandates harden procurement requirements. Cerner Corporation leverages its entrenched EHR footprint to anchor hospital system deployments. Microsoft competes through Azure-powered health data services that extend cloud infrastructure into clinical workflows. Oracle sustains relevance via enterprise database architectures that dominate backend health information exchange operations.
IHE XDS.B designates a technical framework for cross-enterprise document sharing that enables healthcare organizations to register, store, and retrieve clinical documents across disparate systems using ebXML registry standards and SOAP-based transactions. The specification supports structured metadata submission with patient identity matching and document lifecycle management for continuity of care. Document management solutions lead product type demand as health systems consolidate fragmented imaging and clinical records into unified repositories. Cloud-based deployment models represent the fastest-expanding segment as hospital IT departments trade capital-intensive on-premise infrastructure for operational expenditure models with managed security.
FDA oversight of clinical decision support tools and ONC certification requirements for health IT interoperability shape product development roadmaps and market access conditions for XDS.B vendors. HIPAA security rule provisions govern document exchange architectures, while the 21st Century Cures Act information blocking provisions enforce API accessibility standards that directly impact vendor technical obligations. Stakeholders must monitor evolving TEFCA framework implementation timelines and state-level health information exchange governance to anticipate procurement standardization and compliance-driven replacement cycles.
Market Dynamics
Federal interoperability mandates are compressing procurement timelines for cross-enterprise document sharing infrastructure as health systems race to comply with API accessibility requirements.
Growth Catalysts
- ONC 21st Century Cures Act:API-driven data sharing mandates compel hospitals to upgrade document exchange architectures, creating immediate procurement pull for certified XDS.B implementations.
- Cloud migration:Health information exchanges are abandoning capital-intensive on-premise infrastructure in favor of operational expenditure models with managed security and elastic scale.
- Patient identity matching:Advanced matching algorithms reduce duplicate records and enable reliable document retrieval across disparate clinical systems.
Market Restraints
- Legacy system entrenchment:Decades-old EHR installations in community hospitals resist standard-based integration without costly middleware layers.
- Skilled workforce scarcity:Health IT departments face acute shortages of engineers proficient in ebXML registry standards and SOAP transaction protocols.
- State-level fragmentation:Inconsistent health information exchange governance across jurisdictions complicates multi-state integrated delivery network deployments.
Strategic Opportunities
- TEFCA framework expansion:Trusted Exchange Framework and Common Agreement implementation creates standardized connectivity requirements that favor established XDS.B vendors.
- Clinical decision support integration:Convergence of document sharing with real-time analytics enables contextual retrieval of relevant patient records at point of care.
- Rural health networks:Federally qualified health centers in underserved regions require affordable cloud-based document management to participate in regional exchanges.
Industry Challenges
- Metadata standardization:Inconsistent application of XDS affinity domain specifications across vendors forces costly custom mapping during multi-system integrations.
- Document lifecycle governance:Health systems struggle to implement automated expiration, amendment, and replacement workflows that satisfy legal health record requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IHE XDS.B Market |
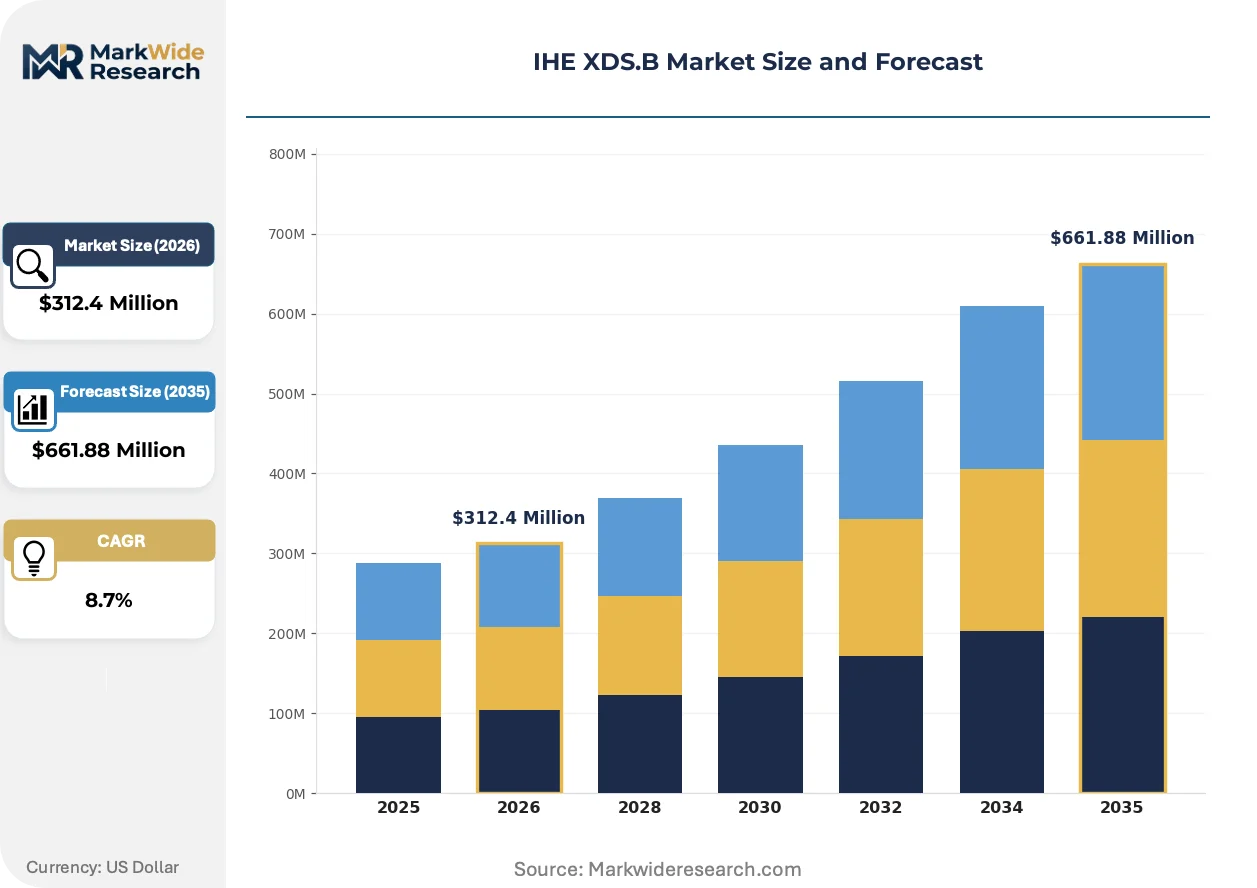
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Image Repository, Data Archive, Workflow Manager Application: Healthcare Interoperability, Medical Imaging, Patient Management, Electronic Health Records Deployment Model: Cloud-Based, On-Premise, Hybrid, Managed Service End User: Hospitals, Ambulatory Care, Diagnostic Centers, Health Information Exchanges |
| Companies Covered | CareEvolution, BridgeHead Software, Microsoft, Synedra, Lexmark International, NEN, Oracle, Allscripts Healthcare Solutions, Cerner Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IHE XDS.B Market Shifts & Advancements
Document exchange architectures are pivoting toward real-time interoperability as batch-oriented retrieval models lose favor among clinicians requiring immediate access to longitudinal records.
FHIR-based APIs are migrating from experimental pilots to production infrastructure as Epic and Cerner implementations expose document references through RESTful endpoints. Large integrated delivery networks in Texas and California are deploying these interfaces to enable mobile clinician access. This migration from SOAP-based transactions is compressing integration timelines from months to weeks.
The FDA's oversight of clinical decision support software is tightening documentation requirements for algorithms that retrieve and process patient records. Developers must now demonstrate traceability from source documents to algorithmic outputs. XDS.B repository vendors serving academic medical centers are responding by embedding audit logging directly into metadata submission workflows.
Subscription-based pricing for document exchange services is displacing perpetual license models as hospital CFOs prioritize predictable operational expenditures. Health information exchanges in Michigan and Florida are leading this transition, unbundling storage, retrieval, and identity resolution into separately metered services. This shift is most visible among mid-sized hospitals with limited capital budgets.
IHE XDS.B Market Segmentation
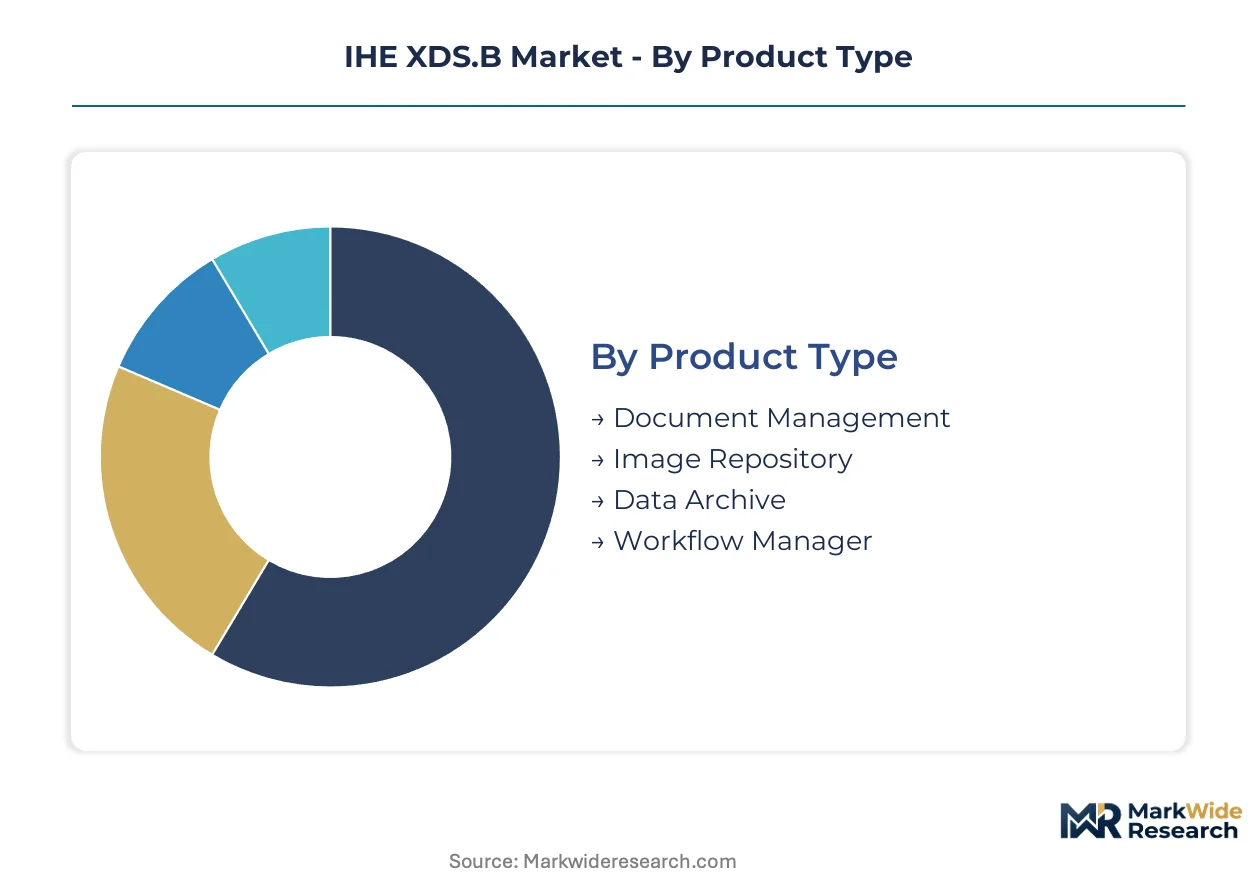
IHE XDS.B implementations vary dramatically in technical architecture and procurement patterns across healthcare delivery settings. Segment-level analysis reveals where cloud migration pressures, interoperability mandates, and capital constraints reshape vendor opportunity.
Product Type:
Mature document handling systems coexist with emerging workflow automation layers in current procurement cycles.
- Document Management:Core registry and repository functions enabling metadata submission, patient identity matching, and cross-enterprise retrieval across ebXML standards. Large integrated delivery networks in Texas and California concentrate procurement here as they consolidate fragmented clinical records into unified repositories ahead of ONC certification deadlines.
- Image Repository:Specialized storage architectures for DICOM and non-DICOM imaging with lifecycle governance and compression optimization. Academic medical centers drive demand as FDA oversight of clinical decision support tools tightens documentation requirements for algorithmic image analysis.
- Data Archive:Long-term retention systems with legal health record compliance and automated expiration workflows.
- Workflow Manager:Orchestration layers coordinating multi-step document submission, validation, and distribution across affinity domains.
Document Management handles the majority of throughput; Workflow Manager is the fastest mover on share.
Application:
Cost tier differentiation separates enterprise-wide deployments from departmental point solutions in current RFP patterns.
- Healthcare Interoperability:Cross-enterprise information exchange infrastructure connecting disparate EHR systems through standardized metadata registries. Health information exchanges in Michigan and Florida prioritize this segment as TEFCA framework implementation creates standardized connectivity requirements.
- Medical Imaging:Radiology and cardiology image sharing with priors retrieval and critical result notification workflows.
- Patient Management:Identity resolution, consent management, and longitudinal record assembly across care transitions.
- Electronic Health Records:Direct EHR integration modules enabling seamless document consumption within clinician workflows.
Healthcare Interoperability commands the largest deployment budgets; Medical Imaging is climbing the fastest as imaging volume explodes.
Deployment Model:
Customer type segmentation shows CFO-driven preference shifts away from capital-intensive ownership models.
- Cloud-Based:Multi-tenant SaaS architectures with elastic storage, managed security, and subscription pricing. Mid-sized hospitals with limited capital budgets concentrate demand here as they abandon on-premise infrastructure for operational expenditure models.
- On-Premise:Dedicated hardware installations with full data sovereignty and customized security controls.
- Hybrid:Mixed architectures retaining sensitive data on-premise while leveraging cloud for burst capacity and disaster recovery.
- Managed Service:Outsourced operations where vendors assume full infrastructure and staffing responsibility.
Cloud-Based deployments absorb the most new logos; Managed Service is gaining share fastest among rural health networks.
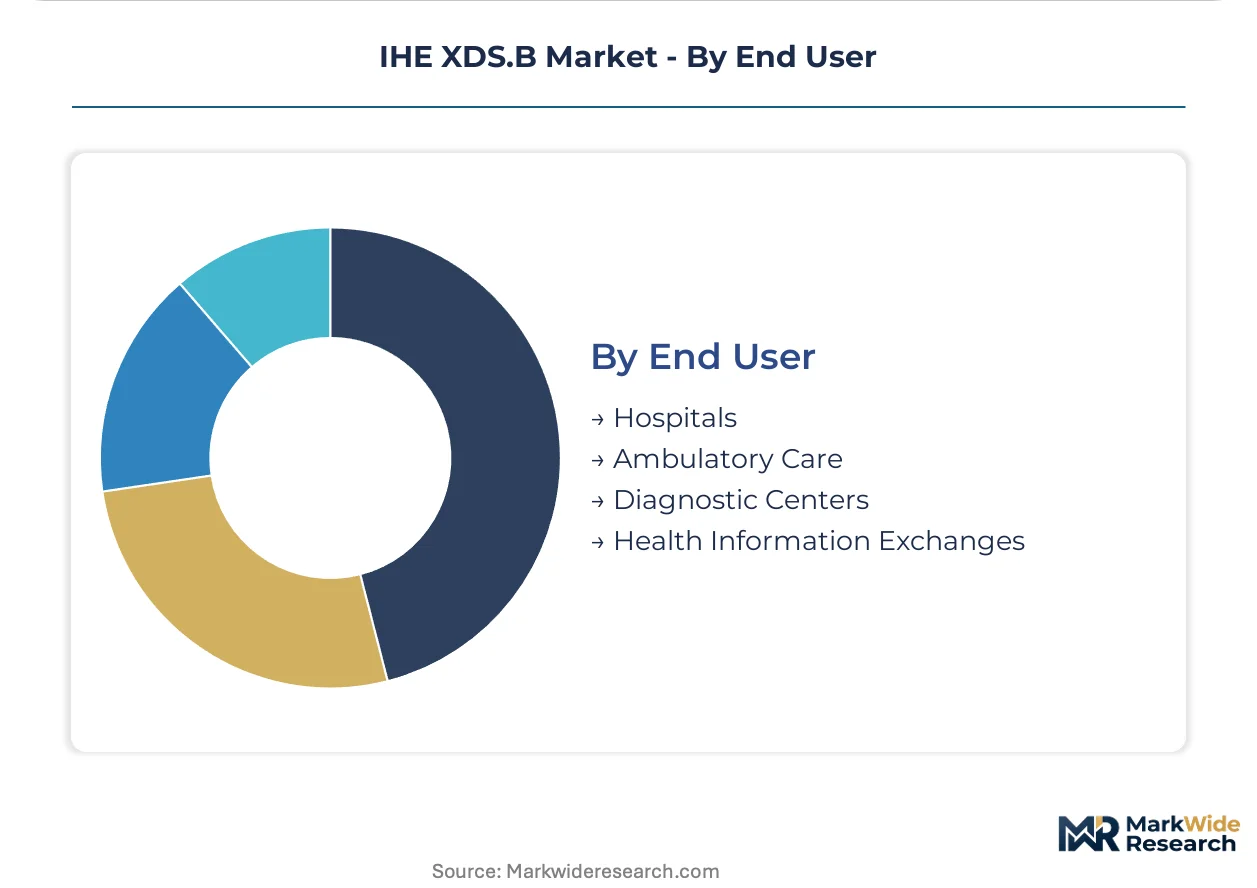
End User:
Volume concentration varies sharply between consolidated systems and fragmented outpatient settings.
- Hospitals:Enterprise-scale implementations serving emergency departments, inpatient units, and specialty clinics through unified infrastructure. Cerner and Epic footprints anchor procurement here as health systems race to comply with API accessibility mandates.
- Ambulatory Care:Federally qualified health centers and physician practices requiring lightweight, affordable connectivity to regional exchanges.
- Diagnostic Centers:Independent imaging facilities prioritizing seamless prior retrieval and report distribution to referring physicians.
- Health Information Exchanges:State-designated entities aggregating documents across competing hospital systems and payer networks.
Hospitals generate the largest contract values; Health Information Exchanges are expanding most quickly as TEFCA participation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for IHE XDS.B infrastructure diverge sharply between federal mandate-driven procurement in North America and voluntary regional exchange development across Europe and Asia-Pacific.
United States
Federal interoperability mandates from ONC and CMS accelerate hospital system upgrades ahead of compliance deadlines. The 21st Century Cures Act information blocking provisions enforce API accessibility standards that reshape vendor technical obligations. Texas and California integrated delivery networks concentrate procurement activity as large health systems consolidate fragmented clinical records into unified repositories.
Germany
Teilhabe am Leben in der Gemeinschaft legislation and the national electronic health card initiative drive cross-enterprise document sharing adoption. BfArM and gematik coordinate technical standards for the telematics infrastructure connecting ambulatory and hospital sectors. Berlin-Brandenburg and Bavaria health information exchanges lead deployment of XDS.B registry architectures for regional care networks.
United Kingdom
NHS England's interoperability standards and the GP Connect program mandate structured document exchange between primary and secondary care. NHS Digital oversees conformance testing for systems handling patient summary records across organizational boundaries. London and Greater Manchester integrated care systems pilot cloud-based repository deployments for population health management.
France
Mon espace santé personal health record expansion and the SI-Interop framework create procurement pull for certified document sharing infrastructure. ANS publishes technical specifications for cross-enterprise document repositories serving regional health agencies. Île-de-France and Auvergne-Rhône-Alpes academic hospital clusters anchor early production deployments of XDS.B metadata registries.
Japan
Ministry of Health, Labour and Welfare promotion of standardized medical information exchange supports regional health information network development. METI guidelines on healthcare data utilization encourage cloud-based document management adoption. Kanto and Kansai metropolitan hospital consortia implement XDS.B repositories for patient referral continuity and imaging prior retrieval.
IHE XDS.B Market Competitive Landscape
Capability concentration sits with specialized health IT vendors possessing deep ebXML registry expertise; scale advantage sits with cloud hyperscalers leveraging existing enterprise infrastructure relationships. The vendor base stratifies across three tiers: entrenched EHR incumbents anchoring hospital system deployments, cloud platform providers extending infrastructure services into clinical workflows, and specialized document management vendors serving health information exchange operators. Dominant competitive moves include strategic partnerships between EHR vendors and cloud providers, plus portfolio diversification into adjacent clinical data archival segments.
Among the specialized health IT tier, CareEvolution and BridgeHead Software exemplify vendors with concentrated expertise in cross-enterprise document registry architectures. Microsoft and Oracle occupy positions at the infrastructure-anchored end, leveraging Azure and cloud database services to extend enterprise relationships into clinical document exchange workflows. Cerner Corporation represents the EHR-integrated archetype, using entrenched hospital system footprints to anchor comprehensive interoperability deployments.
| Leading Market Players |
|---|
| CareEvolution |
| BridgeHead Software |
| Microsoft |
| Synedra |
| Lexmark International |
| NEN |
| Oracle |
| Allscripts Healthcare Solutions |
| Cerner Corporation |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States anchors margin capture downstream, where AWS, Azure, and Google Cloud data center regions in Virginia, Ohio, and California determine hosting cost structures for XDS.B registry deployments. Health information exchanges and hospital systems absorb these upstream pricing dynamics through multi-year SaaS contracts that bundle storage, retrieval, and identity resolution into predictable operational expenditure models.
Pricing Analysis
Long-term offtake agreements dominate procurement, with three-to-five-year SaaS subscriptions displacing perpetual licenses as hospital CFOs prioritize budget predictability. Price differentiation hinges on ONC certification tier and transaction volume scale, with certified implementations commanding premium positioning over uncertified alternatives. Pricing pressure stems from subscription fatigue among mid-sized hospitals facing multiple concurrent cloud migrations. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers prioritize compliance assurance over cost minimization.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized health IT systems integrators in the United States, Germany, and Japan, where vendors with deep ebXML registry expertise assemble production-grade XDS.B infrastructure. Software components draw from open-source IHE toolkits, commercial identity matching engines, and cloud-native orchestration layers. Single-source vulnerability around patient identity resolution algorithms poses structural risk, as proprietary matching engines from dominant vendors create lock-in. Distribution runs through direct enterprise sales teams serving health information exchanges and hospital procurement committees, supplemented by GPO contracts for mid-sized provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent XDS.B vendors face substitution defense imperatives as FHIR-native document exchange architectures threaten to displace SOAP-based transaction models. The convergence of RESTful APIs with real-time interoperability requirements creates existential pressure on legacy registry deployments.
For Market Incumbents: Pre-empt FHIR displacement by embedding RESTful endpoints alongside existing SOAP infrastructure, preserving backward compatibility while capturing next-generation procurement cycles. Accelerate certification investment in TEFCA-compliant connectivity to anchor health information exchange RFPs before cloud hyperscalers deepen clinical workflow penetration. Cloud-native entrants with pre-built FHIR stacks represent the primary substitution threat; vertical integration into identity resolution algorithms defends margin pools.
For New Entrants and Emerging Players: Build out lightweight, FHIR-first document exchange platforms targeting rural health networks and federally qualified health centers underserved by enterprise vendor sales motions. White-space concentration sits in cloud-based workflow orchestration for mid-sized hospitals abandoning capital-intensive on-premise infrastructure. Go-to-market leverage through regional health information exchange partnerships bypasses direct competition with entrenched EHR incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized document registry vendors possessing deep IHE conformance expertise and existing health information exchange customer relationships, as these assets command scarcity premiums in consolidation scenarios. Long-term viability across a five-to-ten year horizon rests on successful navigation from SOAP-based to FHIR-native architectures. Monitor TEFCA framework implementation velocity and state-level procurement standardization as inflection indicators for vendor replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | RESTful API architectures capture ONC Cures Act compliance procurement ahead of SOAP legacy displacement. |
| TEFCA Certification Investment | Trusted Exchange Framework conformance opens health information exchange RFP participation and multi-state network eligibility. |
| Cloud Infrastructure Partnership | Azure and AWS co-selling agreements accelerate hospital system deployment timelines through existing enterprise relationships. |
| Patient Identity Resolution Acquisition | Proprietary matching algorithm ownership defends margin pools and creates switching costs for health information exchange customers. |
| Rural Health Network Expansion | Federally qualified health center penetration builds volume base and positions for Medicaid reimbursement policy shifts. |
Research Methodology
Operator-level perspectives from health information exchange executives, hospital CIOs, biomedical informaticists, and ONC certification specialists anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from CMS Medicare data, hospital procurement databases, GPO contract disclosures, and IHE Connectathon conformance results. Bottom-up deployment tracking across affinity domains and top-down market sizing through vendor revenue analysis enabled triangulation.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity analysis applied to TEFCA implementation timelines and cloud migration velocity assumptions. Segmentation dimensions modeled include deployment model, end-user organization scale, product type architecture, and regional regulatory cluster. CAGRs derived from historical deployment trajectories and policy-mandated procurement deadlines, incorporating hospital capital expenditure cycles and health information exchange funding patterns as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers into clinical workflow integration or unexpected FHIR standard acceleration would shift outcomes beyond modeled ranges. Quarterly review of ONC certification deadline compliance rates, TEFCA framework participation metrics, and health information exchange procurement announcement volume is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Healthcare Information Exchange Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
AI-Powered Formulary Management Market
Health Informatics
Global E-Health Market
Health Informatics
US Healthcare Payer Analytics Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Ambulatory Electronic Health Record Market
Health Informatics
United States EHR Cloud Computing Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Global Healthcare Middleware Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Global Healthcare EDI Market