
 Artificial Intelligence (AI) Healthcare Market | 2026-2036
Artificial Intelligence (AI) Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) Healthcare Market Intelligence
China's rapid build-out of AI computing infrastructure and national healthcare data platforms is reconfiguring the development landscape for medical algorithms. NVIDIA Corporation leverages its GPU hardware to power complex diagnostic models. Microsoft Corporation provides essential cloud infrastructure through its Azure platform for scalable AI solution deployment. Siemens Healthineers AG integrates AI directly into its diagnostic imaging and laboratory systems, creating embedded intelligence within hospital workflows.
Artificial intelligence in healthcare applies machine learning to analyze complex medical data, often using convolutional neural networks for image interpretation. The core purpose is to enhance diagnostic accuracy, predict patient outcomes, and personalize treatments. Diagnostic AI systems, particularly for imaging analytics in the oncology therapy area, constitute a leading product segment. Hospitals are the primary end users, though deployment through telemedicine providers is accelerating rapidly.
Regulatory bodies like the US FDA and the EMA in Europe define the approval pathways for AI software as a medical device. Data privacy regulations, including HIPAA in the United States and GDPR in Europe, impose strict constraints on the use of patient information for model training. Navigating these complex and diverging international standards while proving tangible clinical value remains the central challenge for all market participants.
Market Dynamics
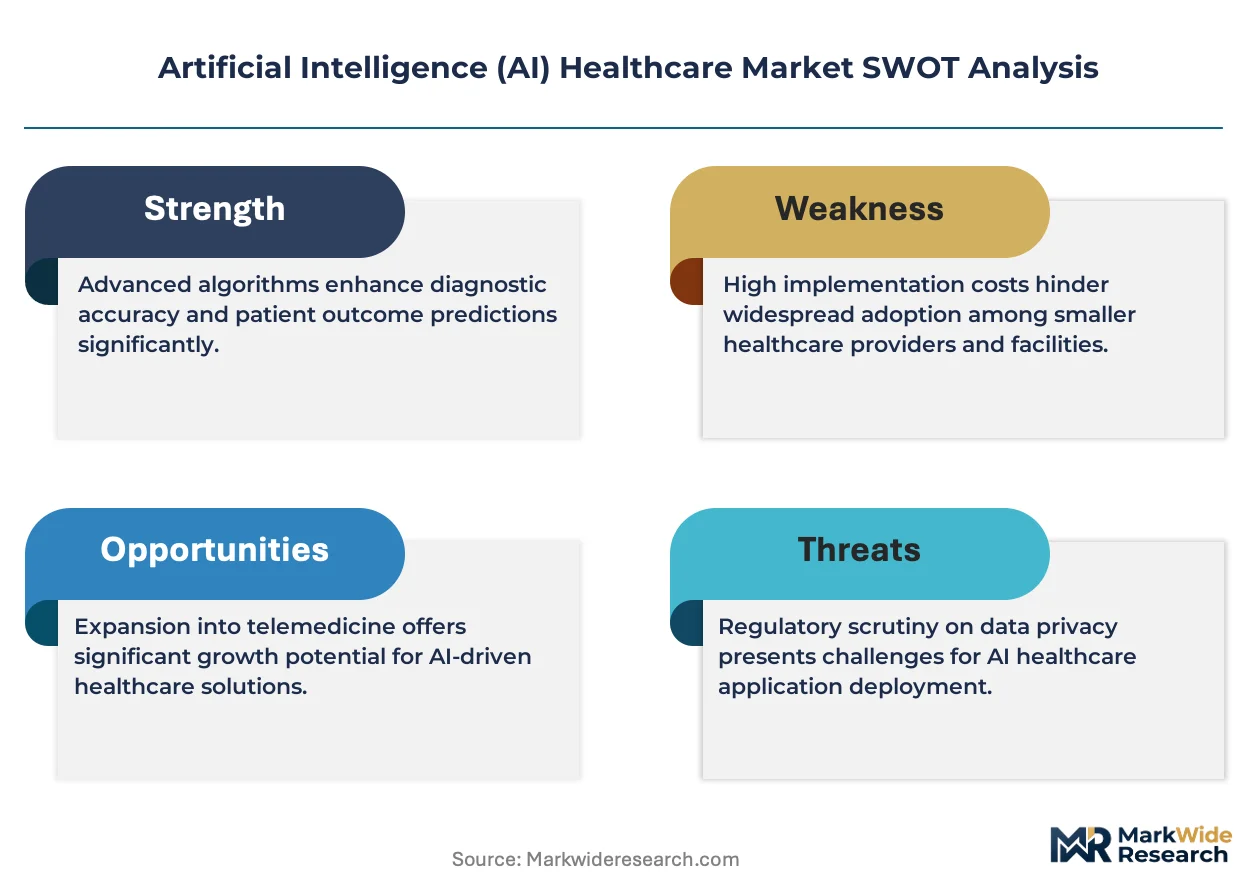
The central dynamic in the AI healthcare market is the friction between the rapid innovation cycles of machine learning technology and the necessarily deliberate, evidence-based timelines of regulatory bodies. This tension shapes development priorities, forcing a focus on clinical validation and explainability over raw predictive power.
Growth Catalysts
- Advanced Neural Networks:The increasing sophistication of convolutional neural networks improves the accuracy of image analysis, accelerating adoption within diagnostic laboratories for complex oncology and neurology imaging tasks.
- Regulatory Clarity:Formal guidance from regulators like the US FDA on Software as a Medical Device (SaMD) provides developers with a structured pathway for market approval, reducing uncertainty and investment risk.
- National Health Initiatives:Government-led healthcare modernization programs, particularly in China, are driving massive investment in technology infrastructure and creating concentrated demand for AI-powered diagnostic and population health tools.
Market Restraints
- Data Curation Costs:The significant expense and ethical complexity of acquiring, cleaning, and annotating large, high-quality clinical datasets for model training remains a primary structural barrier to entry and scalability.
- Fragmented Privacy Regulations:Diverging data privacy laws, such as HIPAA in the United States and GDPR in Europe, create compliance challenges and operational friction for companies developing globally applicable AI models.
- Clinical Explainability Gap:The inherent "black box" nature of some deep learning algorithms impedes clinical trust and adoption, as physicians often require transparent, interpretable outputs to validate an AI-generated recommendation.
Strategic Opportunities
- Predictive Chronic Disease Management:Expanding AI applications beyond diagnostic imaging into predictive analytics for managing chronic conditions like diabetes and heart disease represents a major area for future growth.
- Precision Medicine Convergence:The integration of AI with genomic data analysis offers a significant opportunity to develop hyper-personalized treatment protocols and novel drug discovery platforms, particularly in oncology.
- Telemedicine Platform Integration:Embedding AI diagnostic support tools directly into rapidly growing telemedicine and virtual care platforms creates a new, high-volume distribution channel that bypasses traditional hospital procurement cycles.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the technical difficulty of integrating new AI applications with existing and often outdated hospital IT infrastructure, including disparate Electronic Health Record (EHR) systems.
- Specialized Talent Scarcity:The market faces a persistent shortage of professionals with hybrid expertise in both data science and clinical workflows, which slows down the effective deployment and validation of AI tools in real-world settings.
- Lengthy Validation Cycles:Proving tangible clinical utility and securing reimbursement codes require long, expensive clinical trials and health economics studies, delaying return on investment for new algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) Healthcare Market |
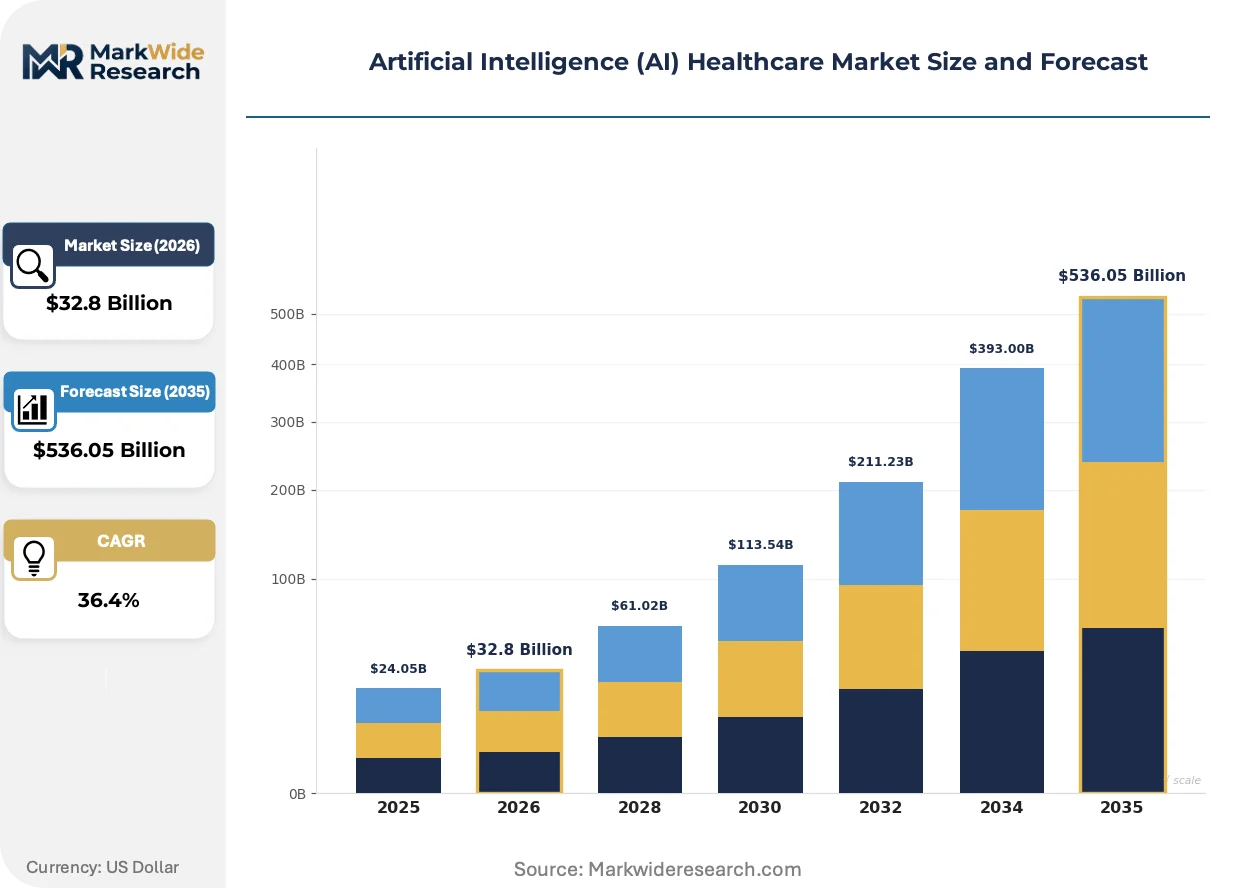
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $536.05 Billion |
| CAGR (2026 – 2036) | 36.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic AI Systems, Clinical Decision Support, Predictive Analytics, Imaging Analytics, Virtual Health Assistants Therapy Area: Oncology, Cardiovascular, Neurology, Radiology, Infectious Diseases End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Laboratories, Telemedicine Providers, Rehabilitation Centers Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Microsoft Corporation, NVIDIA Corporation, GE Healthcare, Koninklijke Philips N.V., IBM, Siemens Healthineers AG, Oracle, Medtronic, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) Healthcare Market Strategic Shifts & Innovations
A fundamental shift is occurring as AI tools evolve from standalone, expert-in-the-loop systems to deeply embedded, automated components within clinical and operational workflows. This trend is moving the market toward ambient intelligence that augments decision-making in real time across the care continuum.
Federated learning allows AI models to train on data from multiple decentralized sources without the sensitive data ever leaving its origin location. Hospitals and research consortia are adopting this technique to build more robust and diverse models while adhering to strict patient privacy rules. The development paradigm is migrating from centralized data lake architectures to distributed, privacy-preserving machine learning frameworks that can scale across institutional and geographic boundaries.
The European Union's AI Act classifies most clinical AI as high-risk systems, which imposes stringent new requirements for data governance, transparency, and human oversight. This regulation forces developers to build comprehensive risk management and post-market surveillance processes directly into their product lifecycle. The diagnostic imaging and digital pathology segments are most impacted, now prioritizing the integration of explainability features to meet compliance demands.
Healthcare providers show a growing preference for subscription-based or consumption-based pricing for AI software, moving away from large, one-time capital outlays. This change disrupts the traditional perpetual software license model and benefits cloud-native vendors offering scalable Software-as-a-Service (SaaS) solutions. This procurement behavior is most prominent among hospital systems in the United States and Europe aiming to convert fixed IT costs into variable operational expenses.
Artificial Intelligence (AI) Healthcare Market Segmentation
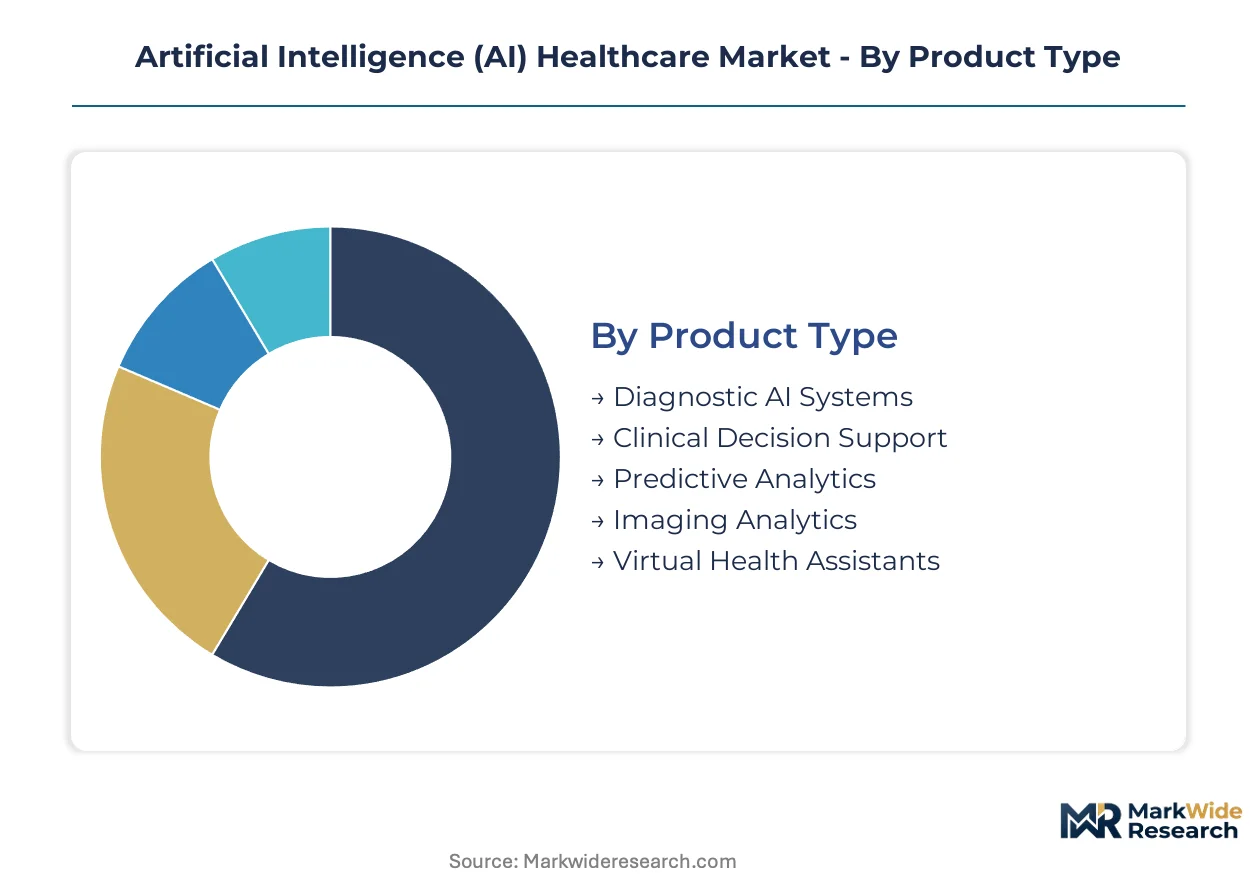
The Artificial Intelligence (AI) Healthcare Market segmentation provides granular insights into the diverse applications and underlying technologies driving innovation. Understanding these distinct market segments is crucial for identifying areas of concentrated investment and evolving clinical demand.
Product Type:
The product type segmentation highlights varying development and deployment cycle times, from rapid iterative updates in virtual assistants to longer validation periods for diagnostic AI systems.
- Diagnostic AI Systems:These platforms leverage machine learning algorithms to assist in disease identification and prognosis, often requiring extensive clinical validation. Demand concentrates in hospitals in the United States, driven by the need for enhanced accuracy in complex cases.
- Clinical Decision Support:AI-powered clinical decision support tools provide evidence-based recommendations to clinicians at the point of care, improving treatment consistency.
- Predictive Analytics:Predictive analytics utilize historical patient data to forecast disease progression, patient outcomes, or population health risks.
- Imaging Analytics:Imaging analytics applies deep learning, particularly convolutional neural networks, to interpret medical images like X-rays, CTs, and MRIs. Deployment is accelerating in diagnostic laboratories in China, supported by national healthcare modernization initiatives.
- Virtual Health Assistants:These AI-driven interfaces offer patient engagement, appointment scheduling, and preliminary symptom assessment, enhancing patient access.
Diagnostic AI Systems dominate the installed base. Imaging Analytics is where expansion concentrates.
Therapy Area:
The therapy area classification reflects where AI applications deliver the most significant clinical impact, influencing treatment pathways and patient outcomes across various medical specialties.
- Oncology:AI in oncology focuses on early detection, personalized treatment planning, and drug discovery, analyzing vast genomic and clinical datasets. Cancer centers in Europe are increasingly adopting these tools to refine diagnostic precision.
- Cardiovascular:AI tools for cardiovascular health predict disease risk, optimize treatment strategies, and monitor patient conditions through wearables and imaging. Hospitals in Germany utilize AI for proactive management of chronic heart conditions.
- Neurology:AI solutions in neurology aid in the diagnosis of neurological disorders, stroke detection, and cognitive assessment.
- Radiology:AI in radiology assists in image interpretation, anomaly detection, and workflow optimization for radiologists.
- Infectious Diseases:AI applications support outbreak prediction, drug discovery, and rapid diagnostic testing for infectious agents.
Oncology applications currently drive the highest value within the market. Cardiovascular AI exhibits the steepest expansion trajectory.
End User:
End-user segments reveal distinct procurement behaviors and integration challenges, influencing AI solution design and market penetration strategies across healthcare settings.
- Hospitals:Hospitals represent the traditional primary end-users, integrating AI into existing Electronic Health Record (EHR) systems and diagnostic workflows. Adoption in large hospital networks in the United States is driven by efficiency gains and improved patient care.
- Ambulatory Surgery Centers:These outpatient facilities increasingly leverage AI for surgical planning optimization and patient flow management.
- Diagnostic Laboratories:Diagnostic laboratories use AI for complex image analysis, automation of sample processing, and genomic sequencing interpretation.
- Telemedicine Providers:Telemedicine platforms embed AI diagnostic support and virtual consultation tools, extending access to specialized medical expertise. Growth in these providers across India is fueled by the need for scalable remote healthcare solutions.
- Rehabilitation Centers:AI assists rehabilitation centers with personalized therapy planning, progress monitoring, and assistive technology integration.
Hospitals constitute the largest segment by current expenditure. Telemedicine providers represent the fastest-growing segment.
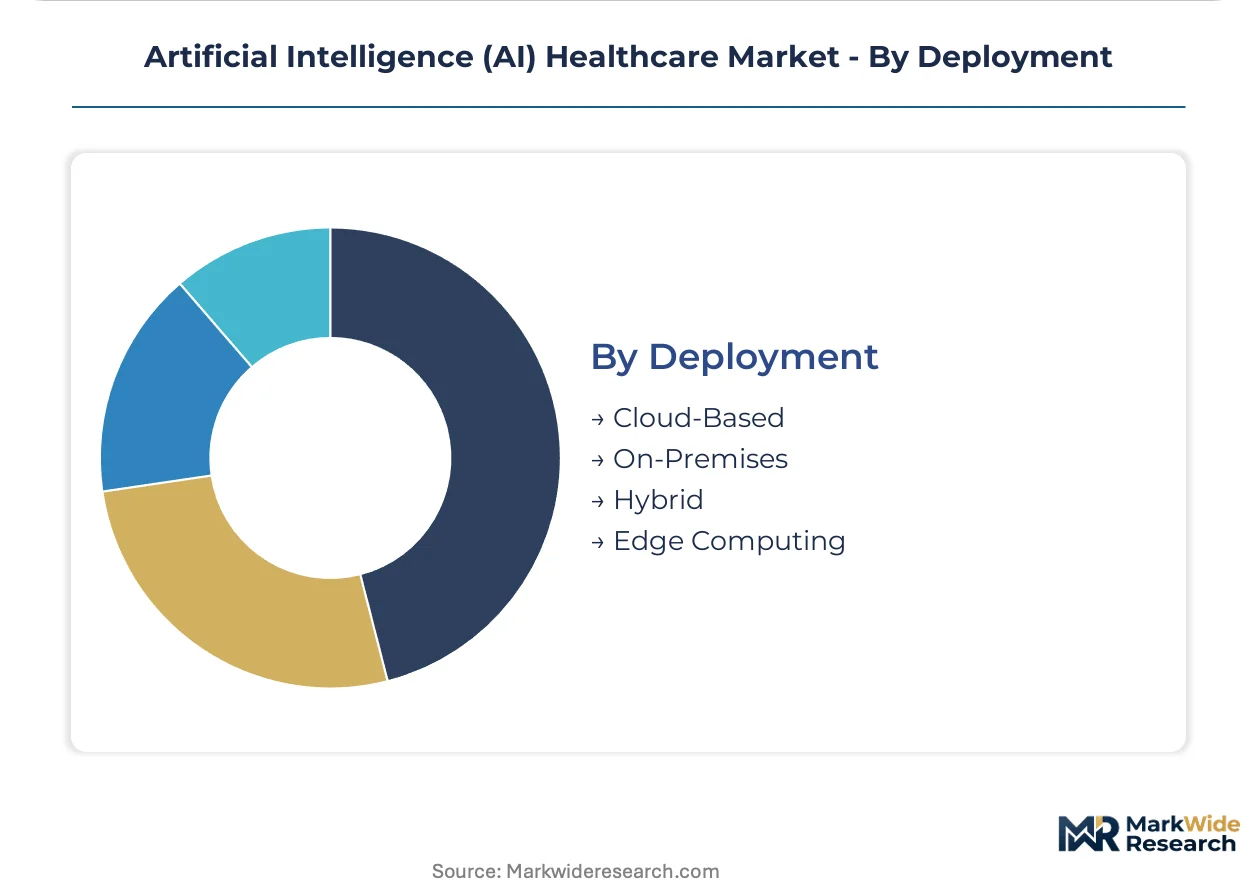
Deployment:
Deployment models determine the scalability, data security posture, and operational cost structures for AI solutions in healthcare, impacting accessibility and regulatory compliance.
- Cloud-Based:Cloud-based deployment offers flexible, scalable computing resources for AI model training and inference, reducing upfront infrastructure costs. Adoption by research institutions in the UK is driven by collaborative data sharing initiatives.
- On-Premises:On-premises solutions host AI software and data within an organization’s local infrastructure, providing maximum control over data security and compliance. Healthcare systems in France prefer this model for sensitive patient information protection.
- Hybrid:Hybrid deployment combines elements of both cloud and on-premises solutions, balancing scalability with data sovereignty requirements.
- Edge Computing:Edge computing processes AI algorithms closer to the data source, enabling real-time insights and reducing latency for critical applications.
Cloud-based solutions are gaining significant market share. On-premises deployments retain a strong foothold for critical data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development and deployment of Artificial Intelligence (AI) healthcare solutions primarily concentrate in key innovation hubs globally. These regions provide essential infrastructure, regulatory support, and a high demand for advanced medical technologies. Significant investment in digital health initiatives further solidifies their positions.
United States
Diagnostic AI systems and clinical decision support tools experience strong demand in the United States, driven by the need for enhanced accuracy. The US FDA's clear guidance on AI as a medical device provides a structured pathway for market approval. Innovation clusters in Boston and California's Silicon Valley foster significant AI healthcare development.
China
China exhibits concentrated demand for AI-powered diagnostic and population health tools, fueled by national healthcare modernization initiatives. The government's massive investment in technology infrastructure supports the rapid build-out of AI computing capabilities. Major tech hubs like Beijing and Shenzhen are centers for medical algorithm development.
Germany
Hospitals in Germany increasingly utilize AI for proactive management of chronic heart conditions and to refine diagnostic precision. The EMA defines approval pathways for AI software, while GDPR imposes strict data privacy constraints. Technology clusters in Munich and Berlin drive innovation in integrated AI diagnostic imaging.
United Kingdom
Research institutions in the United Kingdom drive AI adoption, particularly for collaborative data sharing initiatives and advanced model training. The UK adheres to stringent data privacy regulations, influencing AI model development and deployment. London and the Oxford-Cambridge arc host numerous AI health tech startups and research consortia.
India
Telemedicine providers across India represent a rapidly growing segment, fueled by the country's need for scalable remote healthcare solutions. Government initiatives like the National Digital Health Mission support the integration of AI diagnostic tools. Technology centers in Bengaluru and Hyderabad are becoming hubs for AI-driven virtual care platforms.
Artificial Intelligence (AI) Healthcare Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential hardware and software infrastructure. The market exhibits a tiered structure, with established technology giants and specialized healthcare solution providers. Strategic archetypes include cloud infrastructure providers, GPU hardware developers, and embedded AI imaging solution vendors. Companies frequently engage in strategic partnerships to combine expertise and accelerate market entry. Portfolio diversification also serves as a common competitive move, expanding offerings across various clinical applications.
Among the technology giants providing foundational infrastructure, Microsoft Corporation offers its Azure platform, supporting scalable AI solution deployment for healthcare organizations globally. NVIDIA Corporation represents a critical hardware specialist, leveraging its GPU technology to power complex diagnostic models that require intensive computational resources for image analysis. Siemens Healthineers AG exemplifies the embedded AI solution archetype, integrating artificial intelligence directly into its diagnostic imaging and laboratory systems to enhance hospital workflows. These entities collectively anchor distinct segments of the AI healthcare value chain, from foundational computing to integrated clinical applications.
| Leading Market Players |
|---|
| Microsoft Corporation |
| NVIDIA Corporation |
| GE Healthcare |
| Koninklijke Philips N.V. |
| IBM |
| Siemens Healthineers AG |
| Oracle |
| Medtronic |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes for high-performance computing components influence the foundational costs for AI hardware infrastructure. These cost dynamics impact the supply concentration of specialized GPUs and servers, which in turn affects the downstream price differentiation of AI healthcare solutions.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for high-risk clinical AI systems, emphasizing compliance costs within solution pricing. Subscription-based Software-as-a-Service (SaaS) models dominate, reflecting a shift from capital expenditure to operational expense for healthcare providers. Price differentiation stems from the level of clinical validation (e.g., FDA clearance) and the complexity of integration with existing hospital Electronic Health Record (EHR) systems. Pricing pressure stems from the significant data curation costs required for robust model training. Telemedicine providers represent the most price-sensitive segment, while large hospital networks prioritize value-based outcomes.
Supply Chain Analysis
Leading contract manufacturers in East Asia, particularly in Taiwan and South Korea, hold substantial capacity for advanced semiconductor production, critical for AI hardware. The supply chain draws from specialized inputs like high-performance GPUs and data storage components. A structural risk is geopolitical instability affecting semiconductor fabrication, creating potential chokepoints for essential hardware. Distribution runs through major cloud infrastructure providers like Microsoft Azure, and direct integration into diagnostic imaging systems from vendors such as Siemens Healthineers AG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift toward personalized medicine and remote care, creating numerous specialized niches.
For Market Incumbents: Build robust regulatory compliance frameworks, establishing a strong moat against emerging, less validated solutions. Invest in federated learning infrastructure to leverage diverse data sources while adhering to stringent data privacy regulations like GDPR. The threat of niche AI startups with agile development cycles necessitates continuous R&D in explainable AI. Form strategic partnerships with academic research institutions to accelerate clinical validation.
For New Entrants and Emerging Players: AI solutions for chronic disease management in underserved rural populations represent the most penetrable entry point. Focus on developing highly specialized diagnostic tools for specific oncology sub-types, leveraging genomic data. A viable go-to-market angle involves offering consumption-based SaaS models directly to telemedicine providers in regions like India, minimizing upfront investment barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from large, diversified healthcare technology conglomerates seeking to divest non-core AI assets. Acquisition targets should include mid-sized firms specializing in privacy-preserving machine learning or explainable AI algorithms. The signal to watch is the broad adoption of common data interoperability standards across major hospital systems, indicating readiness for scaled AI integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamlessly embed AI tools within existing EHR systems, enhancing hospital workflows. |
| Regulatory Approval Pathway | Secure FDA or EMA clearance, establishing clinical credibility for AI solutions. |
| Strategic Partnership | Collaborate with cloud providers like Microsoft Azure, expanding scalable AI solution deployment. |
| Acquire Specialist Firm | Gain niche expertise in areas like federated learning or genomics for precision medicine. |
| Reimbursement Strategy | Develop clear pathways for AI-driven diagnostics, ensuring financial viability for providers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, scientific publications, and industry reports. Primary interviews were conducted with clinical leads, hospital IT directors, regulatory affairs specialists, and data scientists across multiple geographies. This approach enabled comprehensive bottom-up and top-down triangulation of market data.
Forecast inputs being considered include technology adoption rates, healthcare spending trends, and regulatory changes across the analysis window. The analytical framework modeled segmentation dimensions such as product type, therapy area, end-user, deployment model, and clinical workflow integration. Compound Annual Growth Rates were derived from historical data analysis and projected market trajectory, incorporating AI model performance benchmarks and regulatory approval timelines.
Stress conditions across regulatory changes, technological breakthroughs in AI, and healthcare spending shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market evolution and competitive dynamics. Quarterly review of new FDA/EMA AI approvals, major hospital system AI deployments, and venture capital investment in health AI is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
US Laboratory Informatics Market
Health Informatics
Healthcare Interoperability Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
Clinical Intelligence Market
Health Informatics
Global Healthcare Cognitive Computing Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Healthcare Operational Analytics Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Global Health IT Security Market
Health Informatics
United States Healthcare Fraud Detection Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
Ehealth Software and Services Market
Health Informatics
Health Intelligent Virtual Assistant Market