
 AI In Packaging Design Market | 2026-2036
AI In Packaging Design Market Size, Share, and Industry Trends Forecast 2026-2036
AI In Packaging Design Market Insights
Multi-source procurement for generative design tools is broadening as FMCG brands diversify beyond legacy CAD vendors. Autodesk leverages cloud-native simulation to anchor enterprise packaging workflows across North American CPG accounts. Adobe competes through creative-cloud integration that extends brand asset management into structural mockup generation. Esko specializes in prepress-to-die-line automation that controls narrow-format folding carton markets for European confectionery brands.
AI in packaging design denotes the application of computational algorithms to automate or augment the creation, testing, and optimization of primary and secondary packaging formats, typically operating on parametric geometry databases, material stress models, and consumer preference datasets to reduce physical prototyping by predictive rendering. The technology serves industrial and commercial purposes by compressing development timelines, minimizing material overuse, and aligning shelf performance with regulatory compliance. Machine learning dominates current deployment for pattern recognition in consumer behavior analysis, where algorithms process retail scanner data to predict structural preferences. Computer vision is displacing manual inspection in quality assurance for printed substrates, with margin pools concentrating in high-speed label verification systems. Cloud-based delivery now leads deployment architecture among mid-market design agencies seeking SaaS accessibility without on-premises GPU infrastructure.
FDA food-contact substance notifications and EU REACH chemical compliance frameworks shape material selection algorithms by embedding restricted substance databases into generative models. The EU Packaging and Packaging Waste Regulation tightens recyclability mandates that AI sustainability assessment modules must validate against country-specific sorting infrastructure. Stakeholders should monitor whether emerging extended producer responsibility schemes in OECD jurisdictions force retrofitting of legacy design archives into circularity-scoring algorithms.
Market Dynamics
Generative algorithms are compressing structural prototyping cycles from weeks to hours across food and beverage packaging workflows. The EU Green Deal's packaging waste directives now mandate AI-validated recyclability proofs before market entry.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for country-specific sorting infrastructure validation are forcing brands to embed AI sustainability modules into material selection algorithms.
- Folding carton engineering:German industrial packaging clusters integrate machine learning into die-line optimization, reducing physical mockup iterations by predictive stress modeling.
- Cloud-native simulation:Mid-market design agencies adopt SaaS delivery architectures to bypass on-premises GPU infrastructure requirements.
Market Restraints
- Substrate material volatility:Recycled fiber and bio-based polymer input costs fluctuate with agricultural commodity indexes, destabilizing generative model cost assumptions.
- Prepress vendor concentration:European confectionery supply chains rely on a narrow base of automated die-line specialists, creating single-point-of-failure risk in narrow-format markets.
- FDA food-contact substance databases:Notification lag times for novel AI-recommended material configurations extend commercialization timelines by 12-18 months.
Strategic Opportunities
- Extended producer responsibility schemes:OECD jurisdictions are piloting circularity-scoring algorithms that retrofit legacy design archives into compliance-ready asset libraries.
- Computer vision convergence:Quality assurance systems for printed substrates integrate with generative design platforms to close the loop between design intent and production output.
- India PLI scheme for packaging machinery:Domestic equipment incentives attract AI-integrated folding carton lines for export-oriented pharmaceutical blister packaging.
Industry Challenges
- Parametric geometry expertise:Packaging engineering programs lack curriculum integration with machine learning toolchains, constraining talent pipelines for hybrid design-automation roles.
- Legacy CAD archive migration:Decades of proprietary file formats resist automated conversion into training datasets for generative models.
- Cross-border chemical compliance:EU REACH restricted substance lists update asynchronously with FDA notifications, forcing redundant validation workflows for multinational brand portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI In Packaging Design Market |
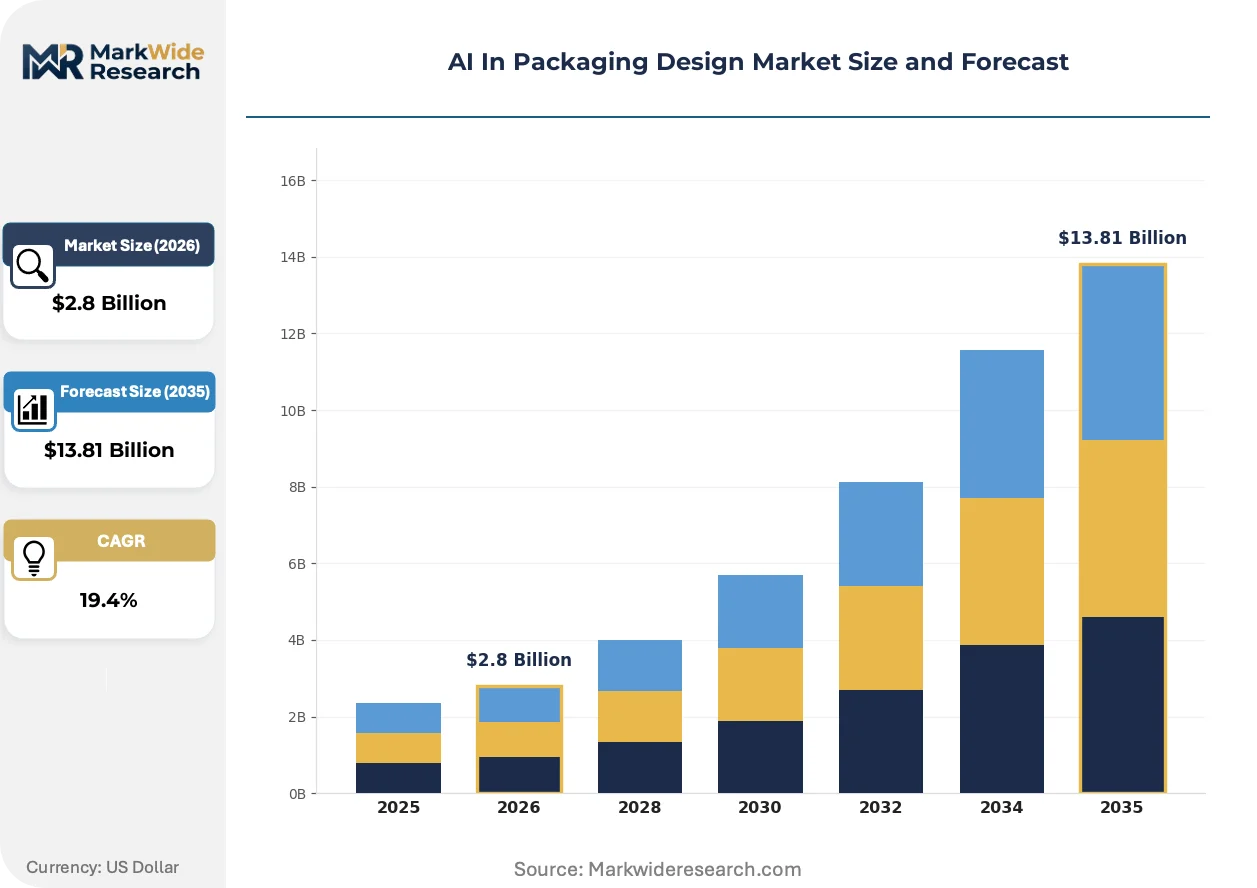
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Reinforcement Learning, Predictive Analytics Application: Label Optimization, Structural Design, Material Selection, Consumer Behavior Analysis, Sustainability Assessment End User: FMCG Brands, Packaging Manufacturers, Design Agencies, Retail Chains, E-commerce Platforms Deployment: Cloud-based, On-premises, Hybrid, Edge Computing, SaaS |
| Companies Covered | Autodesk, Adobe, Siemens, SAP, Amazon Web Services, Microsoft, IBM, Dassault Systèmes, Esko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI In Packaging Design Market Trends and Innovations
Computational design workflows are fragmenting across specialized vendor ecosystems rather than consolidating under monolithic platforms. Three distinct vectors are reshaping how packaging intelligence moves from concept to shelf.
Generative adversarial networks for structural optimization are expanding into beverage secondary packaging, where algorithms iterate rib geometries and corner radii against automated drop-test simulations. Premium spirits brands in France deploy these tools to reduce glass weight without compromising stack strength. The compression of physical prototyping cycles is reallocating R&D budgets toward consumer preference modeling rather than mold fabrication.
The EU AI Act's risk classification framework now captures packaging design algorithms that influence food safety-critical material selections. High-risk system obligations mandate training data documentation and human oversight protocols that extend development timelines. German folding carton exporters face dual compliance burdens as the regulation intersects with existing EU Green Deal recyclability mandates.
Brand asset management platforms are absorbing structural mockup generation capabilities previously siloed in engineering departments. Consumer packaged goods marketers in North America now iterate shelf-ready 3D renders without CAD specialist intermediation. This disintermediation concentrates purchasing authority within marketing technology budgets rather than industrial design procurement channels.
AI In Packaging Design Market Segmentation
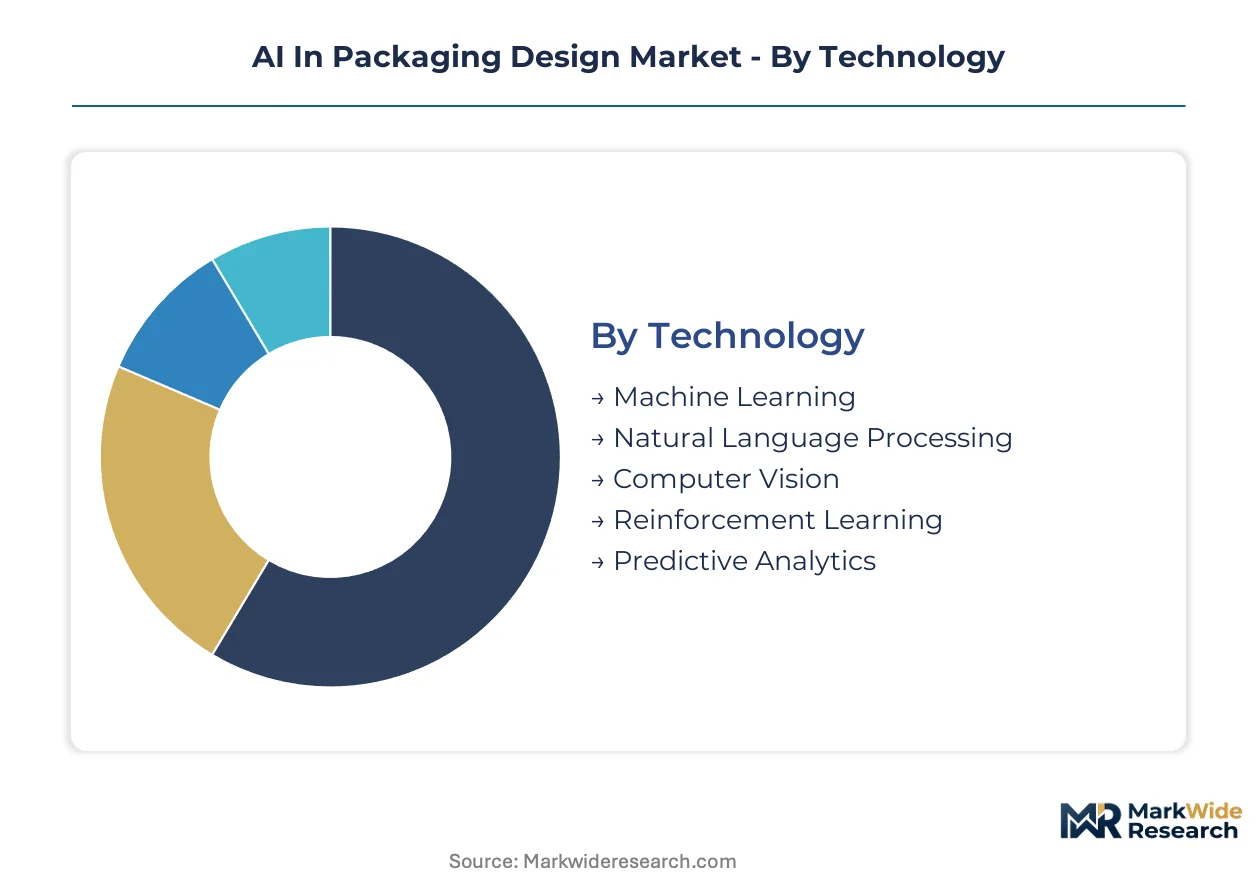
Segmentation in AI packaging design reveals how computational capabilities distribute across workflow stages, from generative ideation through compliance validation. Technology choices determine whether brands embed intelligence into existing CAD ecosystems or deploy standalone platforms. Application focus separates material-science automation from consumer-facing optimization engines.
Technology:
Integration depth varies sharply: some technologies operate as embedded modules within legacy design suites, while others demand standalone infrastructure with dedicated GPU clusters.
- Machine Learning:Algorithms process parametric geometry databases and material stress models to predict structural performance without physical prototyping. Demand concentrates in German folding carton engineering clusters, where die-line optimization algorithms reduce mockup iterations by predictive modeling of board compression strength.
- Computer Vision:Systems perform automated substrate inspection and printed label verification at production-line speeds. High-margin deployments focus on narrow-format European confectionery markets, where prepress-to-die-line automation controls quality assurance for premium chocolate and biscuit packaging.
- Natural Language Processing:Parses regulatory text from FDA food-contact substance notifications and EU REACH restricted substance lists to automate compliance screening.
- Reinforcement Learning:Iterates packaging geometries against simulated drop-test and stack-stress scenarios for beverage secondary packaging optimization.
- Predictive Analytics:Processes retail scanner data to forecast consumer structural preferences and shelf-performance outcomes.
Volume placements concentrate in Machine Learning; the faster expansion belongs to Computer Vision.
Application:
Cost tier stratification separates high-investment structural engineering from lower-barrier consumer analytics modules accessible to mid-market design agencies.
- Structural Design:Generative algorithms iterate rib geometries, corner radii, and panel thicknesses against automated stress simulations. Premium spirits brands in France deploy these tools to reduce glass weight while maintaining stack strength for palletized distribution.
- Material Selection:AI validates recyclability proofs against country-specific sorting infrastructure databases, driven by EU Packaging and Packaging Waste Regulation mandates for pre-market compliance documentation.
- Label Optimization:Automates typography scaling and regulatory text placement for multi-jurisdiction product launches.
- Consumer Behavior Analysis:Pattern recognition algorithms process purchase data to predict packaging format preferences across demographic segments.
- Sustainability Assessment:Scores design archives against circularity metrics for extended producer responsibility scheme compliance in OECD jurisdictions.
Revenue concentrates in Structural Design; Sustainability Assessment is climbing the fastest as regulatory deadlines tighten.
End User:
Customer type determines procurement authority—whether engineering departments control budgets or marketing technology spend absorbs new capabilities.
- FMCG Brands:Enterprise CPG accounts anchor demand for cloud-native simulation platforms that compress development timelines across multinational portfolios. North American marketers increasingly iterate shelf-ready 3D renders without CAD specialist intermediation.
- Packaging Manufacturers:Industrial clusters integrate machine learning into folding carton and corrugated board production lines, with German engineering hubs leading die-line automation adoption.
- Design Agencies:Mid-market agencies favor SaaS delivery architectures to bypass on-premises GPU infrastructure investments.
- Retail Chains:Deploy private-label packaging optimization to differentiate shelf presence against national brands.
- E-commerce Platforms:Prioritize ship-ready structural designs that minimize dimensional weight charges and damage rates in last-mile delivery.
Procurement volume concentrates in FMCG Brands; Packaging Manufacturers show the steepest expansion trajectory as supplier-side automation deepens.
Deployment:
Supply concentration in cloud infrastructure vendors shapes accessibility for different buyer scale tiers.
- Cloud-based:SaaS architectures dominate mid-market agency adoption, eliminating capital expenditure for GPU clusters while enabling subscription-based access to generative design tools.
- SaaS:Purpose-built packaging design platforms deliver prepress-to-die-line automation through browser interfaces, concentrating in European confectionery supply chains.
- On-premises:Enterprise CPG accounts maintain captive infrastructure for proprietary parametric geometry databases and restricted substance compliance libraries.
- Hybrid:Combines local CAD workstation performance with cloud-based rendering farms for complex simulation workloads.
- Edge Computing:Deploys quality assurance algorithms directly on production-line hardware for millisecond-latency defect detection.
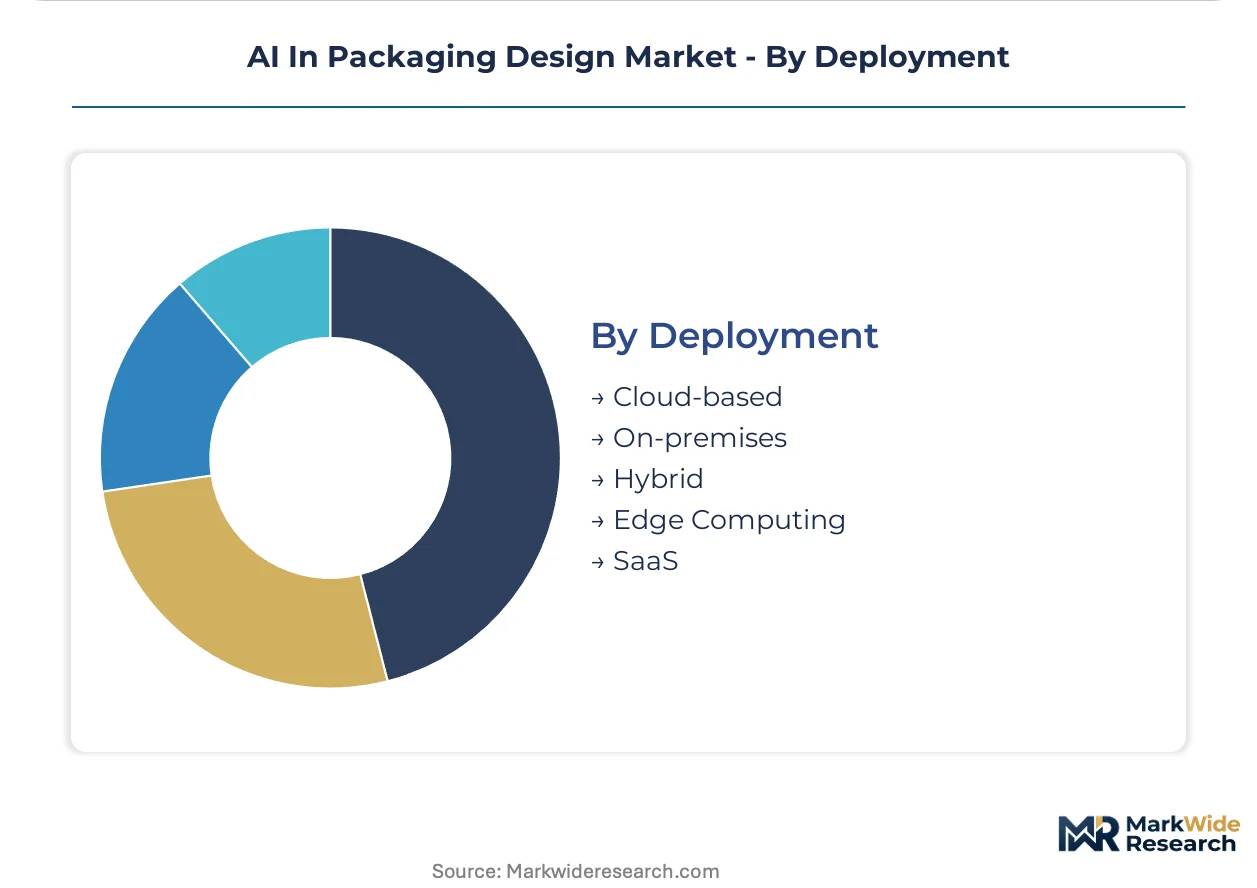
Adoption concentrates in Cloud-based delivery; Edge Computing is gaining share fastest as real-time production integration priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial packaging clusters anchor European demand for AI-integrated folding carton engineering, while North American CPG marketers drive cloud-native simulation adoption. Asian pharmaceutical export hubs and Middle Eastern luxury goods packaging centers complete the geographic spread.
Germany
Baden-Württemberg and North Rhine-Westphalia host dense concentrations of folding carton automation specialists serving confectionery and pharmaceutical brands. The EU AI Act's high-risk system obligations intersect with EU Green Deal recyclability mandates, forcing dual compliance documentation. Stuttgart-area engineering hubs integrate machine learning into die-line optimization, compressing physical prototyping cycles through predictive board stress modeling.
United States
Enterprise CPG accounts in the Midwest and Southeast anchor demand for cloud-native structural simulation platforms. FDA food-contact substance notification requirements for novel AI-recommended material configurations extend commercialization timelines by 12-18 months. Chicago and Atlanta industrial corridors concentrate prepress-to-production integration, where brand asset management platforms absorb structural mockup generation from engineering departments.
France
Premium spirits brands in Île-de-France and Auvergne-Rhône-Alpes deploy generative adversarial networks to reduce glass weight while maintaining palletized stack strength. ANSM and CNIL oversight adds regulatory complexity to AI-validated packaging for food-contact and personal data contexts. Cognac and Champagne production clusters drive beverage secondary packaging optimization through automated drop-test simulation.
India
Maharashtra and Gujarat pharmaceutical export corridors attract AI-integrated folding carton lines under the PLI scheme for packaging machinery. FSSAI food safety compliance and CDSCO pharmaceutical labeling requirements shape material selection algorithms for domestic and export markets. Mumbai-Pune and Ahmedabad industrial zones concentrate supplier-side automation for blister and bottle packaging serving regulated export destinations.
United Arab Emirates
Dubai and Abu Dhabi luxury goods packaging centers deploy computer vision systems for high-speed label verification on premium confectionery and cosmetics. MOHAP product registration requirements and growing extended producer responsibility pilots influence circularity-scoring algorithm adoption. Jebel Ali free zone clusters serve as re-export hubs for AI-validated packaging configurations entering European and African markets.
AI In Packaging Design Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized prepress automation. The vendor base stratifies into three tiers: hyperscale cloud providers delivering GPU-enabled simulation platforms, legacy CAD vendors embedding machine learning modules into existing enterprise workflows, and narrow-format specialists controlling confectionery die-line automation. Dominant competitive moves include strategic partnerships between cloud providers and industrial software vendors, plus portfolio diversification into sustainability assessment modules.
Among design software specialists, Autodesk and Adobe occupy positions at opposite ends of the workflow integration spectrum. Autodesk exemplifies the engineering-centric archetype with cloud-native simulation anchoring enterprise packaging workflows, while Adobe represents the creative-cloud integration path extending brand asset management into structural mockup generation. Esko anchors the narrow-format specialization tier, with its prepress-to-die-line automation controlling European confectionery supply chains. Siemens and Dassault Systèmes sit within the industrial software conglomerate archetype, leveraging existing manufacturing execution system relationships to cross-sell packaging design modules.
| Leading Market Players |
|---|
| Autodesk |
| Adobe |
| Siemens |
| SAP |
| Amazon Web Services |
| Microsoft |
| IBM |
| Dassault Systèmes |
| Esko |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up CAD specialists have consolidated prepress automation assets across European confectionery supply chains, tightening pricing discipline for die-line optimization modules while compressing margins for standalone SaaS entrants competing against bundled engineering workflows.
Pricing Analysis
Service-bundling separates training-inclusive enterprise licenses from unbundled per-seat SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels tracks GPU cluster access and compliance database depth. Pricing pressure stems from mid-market agencies bypassing on-premises infrastructure through browser-based simulation tools. FMCG brand procurement shows highest price sensitivity; pharmaceutical exporters absorb premium tiers for FDA-validated material libraries.
Supply Chain Analysis
Dual-sourcing mandates from German automotive and pharmaceutical exporters force qualification of redundant GPU cloud providers alongside die-line automation specialists. Hardware concentration centers on Taiwan and South Korea for GPU fabrication, with German and US engineering hubs controlling prepress-to-die-line software. Recycled fiber and bio-based polymer feedstocks draw from agricultural commodity indexes, exposing cost assumptions to raw material volatility. Single-source vulnerability concentrates in narrow-format European confectionery automation. Distribution runs through direct enterprise sales for CPG accounts and channel partners for mid-market agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system documentation requirements erect a cost-of-compliance barrier that favors incumbents with captive regulatory affairs infrastructure over bootstrap SaaS entrants lacking compliance bandwidth.
For Market Incumbents: Anchor cloud-native simulation platforms with embedded EU Green Deal recyclability validation modules to defend against point-solution challengers. Deepen backward integration into GPU rendering farms to secure capacity priority during supply crunches. Prioritize certification investment for FDA food-contact substance databases to extend commercialization timelines as a competitive moat.
For New Entrants and Emerging Players: Computer-vision quality assurance for narrow-format label verification offers the most penetrable wedge against Esko's confectionery lock-in. Target India's PLI-subsidized pharmaceutical packaging corridors for first enterprise deployments. Pursue white-label partnerships with mid-market design agencies seeking SaaS accessibility without engineering department intermediation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor prepress-to-die-line automation specialists in Baden-Württemberg facing dual EU AI Act and Green Deal compliance costs. Five-to-ten year viability hinges on circularity-scoring algorithm portfolios for extended producer responsibility schemes. Watch OECD jurisdiction EPR pilot expansions as inflection signal for compliance-tech valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk's cloud-native simulation anchors enterprise CPG workflows across North American accounts. |
| Acquisition of Specialist Firm | Adobe extends creative-cloud brand asset management into structural mockup generation capabilities. |
| Strategic Partnership | AWS GPU infrastructure partnerships enable mid-market agency SaaS access without captive hardware. |
| Geographic Expansion | Esko controls narrow-format folding carton automation for European confectionery supply chains. |
| Product Launch | Siemens cross-sells packaging design modules through existing manufacturing execution system relationships. |
Research Methodology
SEC 10-K filings, EU regulatory submission databases, and hyperscaler capex disclosures formed the secondary backbone, cross-referenced with primary interviews across packaging engineering directors, brand managers at FMCG accounts, prepress automation specialists, and regulatory affairs leads at pharmaceutical exporters. Bottom-up deployment estimates triangulated against top-down market sizing from trade flow analysis.
Historical trendline analysis established baseline adoption curves across machine learning, computer vision, and natural language processing technology segments. The analytical framework modeled deployment architecture, end-user type, and application focus throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included EU Packaging and Packaging Waste Regulation compliance deadlines and FDA food-contact substance notification lag times.
Several conditions sit outside the modeled scope, including hypothetical EU AI Act enforcement intensity variations and unannounced extended producer responsibility scheme rollouts. Forecasts reflect documented assumptions about cloud infrastructure cost trajectories and GPU availability. Deviation in recycled fiber commodity index volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Customer Experience As a Service (Cxaas) Market
Digital Solutions
Computer Aided Engineering Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
North America API Management Market
Digital Solutions
Lecture Capture Solutions Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Digital Notepad Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Mobile Command and Control Solutions Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market