
 Interactive Response Technology Market | 2026-2036
Interactive Response Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Interactive Response Technology Market Insights
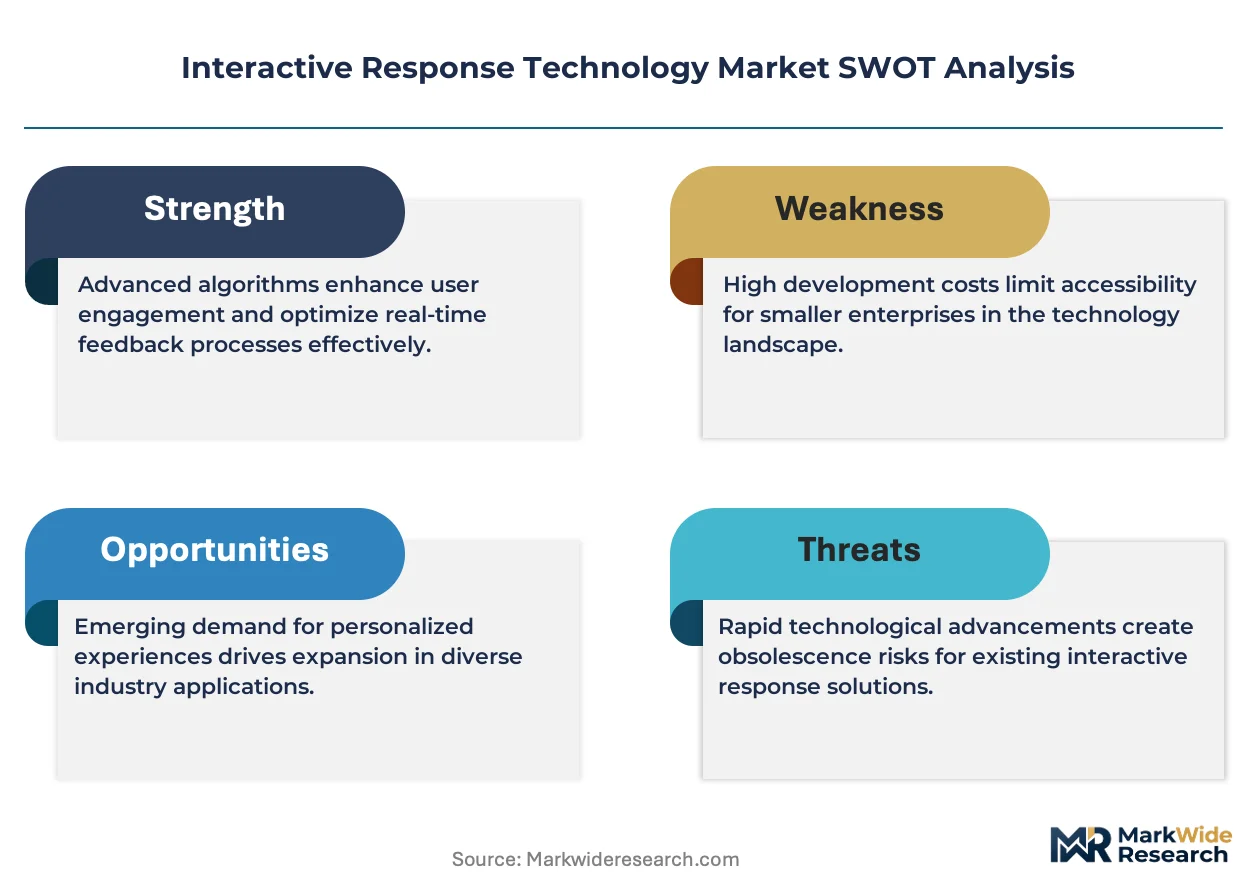
Cloud-native architecture is narrowing the gap between traditional IVR telephony and real-time digital engagement in clinical trials. Suvoda leverages its vertical specialization in life sciences to sustain premium positioning among Phase III sponsors. ICON plc anchors its offering through integrated site-patient connectivity spanning enrollment to closeout. Five9 competes by extending its contact-center infrastructure into healthcare-compliant engagement workflows.
Interactive Response Technology comprises automated systems that collect, route, and manage participant communications through voice, web, SMS, or mobile interfaces, typically supporting randomization, drug supply management, and diary capture with audit-trail integrity for regulated research. Its primary commercial purpose is to reduce trial latency, minimize human data-entry error, and maintain blinding protocols across geographically dispersed sites. Web-Based Solutions and Mobile Apps capture expanding margin pools as sponsors prioritize patient-centric decentralized trial models. Cloud-Based deployments are displacing on-premises installations among mid-size biotechnology firms seeking faster study startup without capital infrastructure.
FDA 21 CFR Part 11, EMA GCP guidelines, and HIPAA security standards collectively shape product roadmaps by mandating electronic signature validation, audit trails, and encrypted data transmission. These frameworks create compliance barriers that favor established vendors with documented quality management systems. Stakeholders must monitor how AI-Driven Platforms navigate emerging FDA algorithm-validation expectations before embedding predictive enrollment forecasting into live trials.
Market Dynamics
Clinical trial sponsors are consolidating vendor relationships around platforms that unify patient randomization, drug supply forecasting, and diary capture within a single validated environment. This integration pressure favors specialized life-science software providers over generic telephony infrastructure.
Growth Catalysts
- Decentralized Trial Mandates:Large pharmaceutical sponsors are mandating hybrid enrollment models that require real-time patient engagement across voice, SMS, and mobile interfaces. This operational shift expands platform licensing scope beyond traditional site-centric deployments.
- FDA 21 CFR Part 11:Electronic signature and audit-trail requirements for regulated research create compliance barriers that sustain premium pricing for validated systems. Sponsors cannot substitute unvalidated consumer communication tools without jeopardizing submission integrity.
- Patient Recruitment Pressure:Oncology and rare-disease studies face enrollment shortfalls that drive investment in automated retention workflows. Interactive response systems reduce dropout through scheduled adherence prompts and symptom reporting.
Market Restraints
- Validation Cost Structure:IQ/OQ/PQ documentation requirements for each protocol amendment impose fixed costs that disadvantage smaller biotechnology sponsors. This cost concentration limits addressable market expansion below mid-cap thresholds.
- Telephony Infrastructure Concentration:Voice response capabilities depend on carrier-grade PSTN and SIP trunking providers concentrated in the United States. Regional latency and redundancy gaps complicate global trial deployment.
- Technical Limitation:Real-time blinding maintenance across multimodal channels requires cryptographic separation architectures that increase integration complexity with electronic data capture systems.
Strategic Opportunities
- Asia-Pacific Expansion:Japan's PMDA and South Korea's MFDS are harmonizing electronic source data acceptance criteria. Early platform localization captures sponsor demand for regional trial execution without Western vendor latency.
- AI-Driven Enrollment Forecasting:Machine learning models trained on historical dropout patterns can optimize randomization stratification. Convergence of predictive analytics with validated response infrastructure creates new module pricing tiers.
- Site Payment Integration:Automated patient-reported outcome capture can trigger milestone-based site reimbursement workflows. This channel innovation embeds IRT platforms deeper into trial financial operations.
Industry Challenges
- Specialized Talent Scarcity:Clinical systems validation engineers with combined GxP and cloud-native architecture expertise command compensation premiums that inflate implementation timelines.
- Legacy EDC Integration:Sponsor-specific data standards and custom API configurations require bespoke middleware development that compresses project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interactive Response Technology Market |
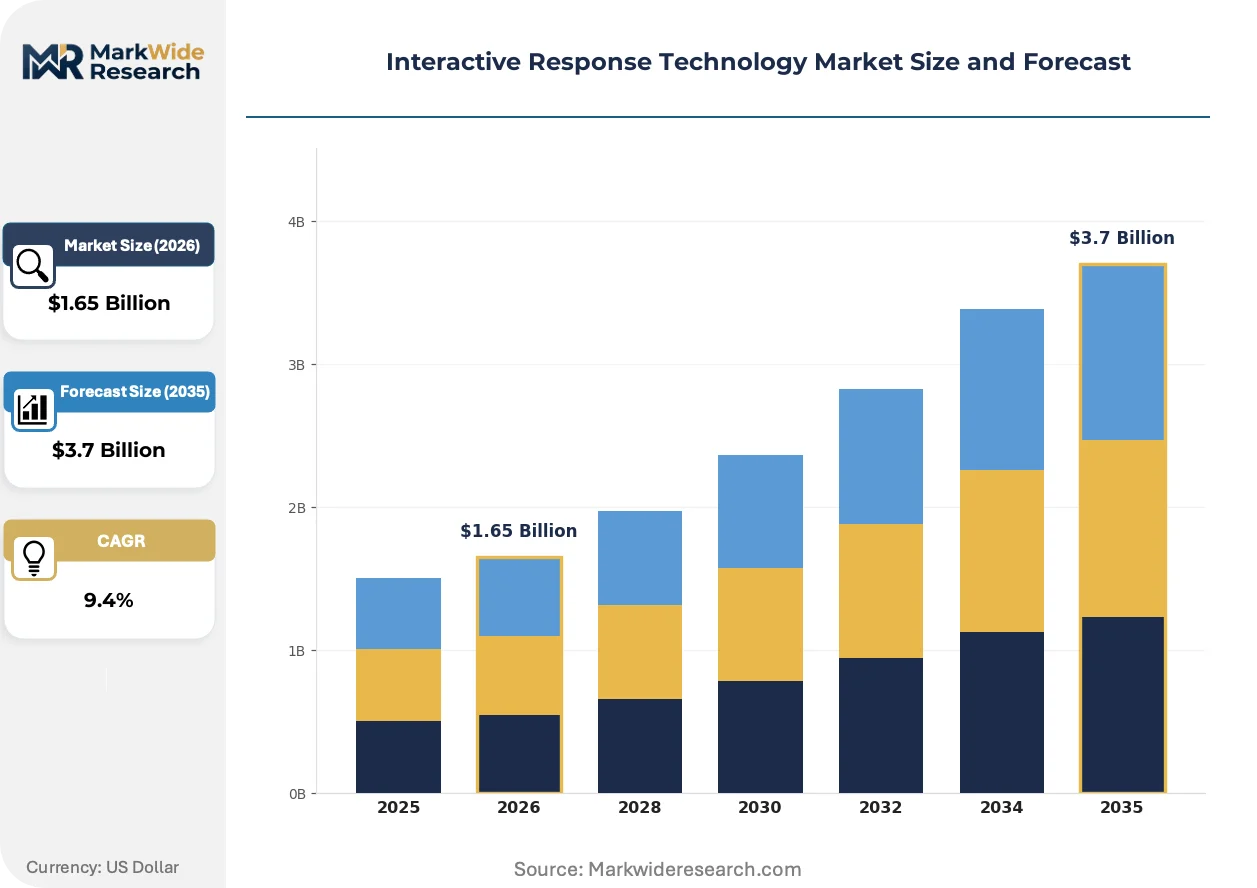
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.7 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IVR Systems, Web-Based Solutions, SMS Platforms, Mobile Apps End User: Pharmaceutical Companies, Clinical Research Organizations, Academic Institutions, Biotechnology Firms Technology: Cloud-Based, On-Premises, Hybrid Solutions, AI-Driven Platforms Application: Patient Enrollment, Data Collection, Feedback Management, Survey Administration |
| Companies Covered | DSG, Five9, Almac, ICON plc, IBM, Bracket, ePharmaSolutions, Suvoda, Cenduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interactive Response Technology Market Trends and Innovations
Cloud-native architectures are dissolving the functional separation between patient engagement, supply chain forecasting, and regulatory documentation. Platform consolidation is compressing vendor margins while expanding per-sponsor contract values.
Microservices-based randomization engines are collapsing the distinction between traditional IVR telephony and real-time digital engagement. Mid-cap biotechnology sponsors are adopting these architectures to accelerate study startup without capital infrastructure commitments. This technology compression is enabling sponsor IT departments to consolidate previously separate vendor relationships.
EMA's updated GCP guidelines on electronic source data are mandating granular audit trails for patient-facing systems. European trial sponsors must demonstrate cryptographic integrity across SMS, voice, and mobile app interactions. Oncology studies with complex adaptive designs are experiencing the most significant compliance workload increases.
Contract structures are migrating from perpetual licensing to subscription-based platform access with protocol-specific module activation. Large pharmaceutical procurement teams are unbundling implementation services from ongoing operational support. This pricing model rotation is most visible among United States-based sponsors running multi-regional Phase III programs.
Interactive Response Technology Market Segmentation
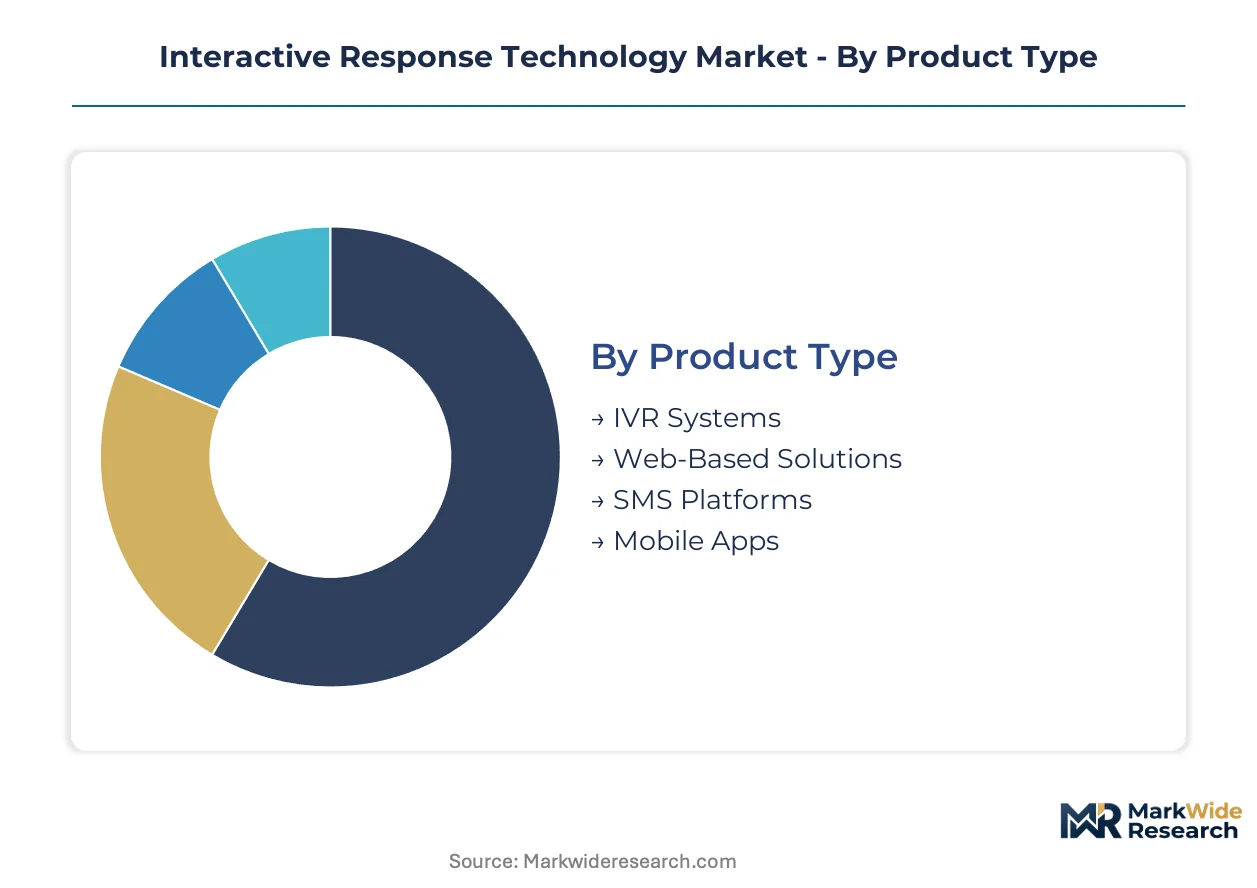
Segmentation in Interactive Response Technology reveals how vendor capabilities align with sponsor operational models. Platform architecture choices directly determine compliance overhead, deployment velocity, and total cost of ownership across trial phases.
Product Type:
After-sales service intensity varies sharply across modalities, with voice infrastructure demanding 24/7 carrier redundancy management while mobile interfaces require continuous OS compatibility patching.
- IVR Systems:Voice-based telephony platforms utilizing PSTN and SIP trunking for automated patient interaction, randomization, and unblinding. Pharmaceutical sponsors in the United States running Phase III oncology trials concentrate demand here due to FDA 21 CFR Part 11 audit-trail mandates for voice recordings. Legacy infrastructure sustains premium support contracts.
- Web-Based Solutions:Browser-accessible portals for patient-reported outcome capture and diary submission. Biotechnology firms in California and Massachusetts favor these for decentralized trial models requiring no app installation friction. Cloud-native architectures reduce validation cycles.
- SMS Platforms:Text-message interfaces for appointment reminders and adherence prompts.
- Mobile Apps:Native smartphone applications with offline capability and biometric authentication.
IVR Systems holds the largest share; momentum sits with Web-Based Solutions.
End User:
Cost tier stratification separates enterprise-grade procurement teams with dedicated validation engineers from mid-cap sponsors outsourcing compliance documentation.
- Pharmaceutical Companies:Large sponsors with internal clinical operations departments running multi-regional trials. Johnson & Johnson and Pfizer procurement teams negotiate enterprise platform licenses spanning randomization, drug supply management, and patient engagement. These buyers demand ISO 27001-certified data centers and dedicated account management.
- Clinical Research Organizations:Full-service and functional service providers managing trials on behalf of sponsors. IQVIA and Parexel operate as both technology consumers and platform resellers, creating channel complexity for pure-play IRT vendors. CROs prioritize protocol amendment agility over feature depth.
- Academic Institutions:University medical centers with investigator-initiated studies and limited IT infrastructure.
- Biotechnology Firms:Venture-backed companies with single-asset pipelines seeking rapid study startup.
Pharmaceutical Companies dominate contract values; Biotechnology Firms are expanding most quickly.
Technology:
Deployment architecture determines capital commitment patterns and regulatory validation scope across sponsor IT departments.
- Cloud-Based:Multi-tenant SaaS platforms with automated scaling and continuous compliance updates. Mid-cap biotechnology sponsors in the United States and Germany adopt these to eliminate data center capital expenditure while maintaining EMA GCP guideline adherence. Vendor-managed infrastructure shifts operational risk.
- On-Premises:Single-tenant installations within sponsor-controlled data centers. Large pharmaceutical companies in Switzerland and Japan with existing GxP-qualified infrastructure retain these for data sovereignty requirements. High fixed costs limit addressability below top-20 sponsors.
- Hybrid Solutions:Mixed deployments with sensitive randomization logic on-premises and patient-facing interfaces cloud-hosted.
- AI-Driven Platforms:Machine learning modules for enrollment forecasting and dropout prediction.
Cloud-Based deployments command the widest adoption; AI-Driven Platforms show the steepest expansion trajectory.
Application:
Functional use case concentration shapes module pricing and implementation complexity for protocol-specific configurations.
- Patient Enrollment:Automated screening, consent capture, and randomization workflows with real-time stratification. Oncology and rare-disease sponsors in the United States deploy these to compress enrollment timelines for competitive indication filings. Integration with electronic data capture systems creates implementation bottlenecks.
- Data Collection:Structured diary capture, biomarker reporting, and adverse event intake across voice, SMS, and mobile channels. Cardiovascular and metabolic trials in Germany and the United Kingdom concentrate demand here for continuous glucose monitoring and blood pressure logging. EMA source data verification requirements elevate audit-trail granularity.
- Feedback Management:Real-time patient experience monitoring and site performance dashboards.
- Survey Administration:Scheduled and event-triggered quality-of-life instrument delivery.
Patient Enrollment generates the highest per-protocol revenue; Data Collection is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based IRT vendors export platform licenses to pharmaceutical sponsors in Germany, Japan, and the United Kingdom, with cloud-native deployments now outpacing on-premises installations across all destination markets.
United States
FDA 21 CFR Part 11 mandates electronic signature validation and audit-trail integrity for voice recordings and mobile app interactions. Massachusetts and California biotechnology clusters drive adoption of decentralized trial platforms with SMS and web-based patient engagement. Large pharmaceutical sponsors in the Boston-Cambridge corridor negotiate enterprise licenses spanning randomization, drug supply forecasting, and diary capture.
Germany
EMA GCP guidelines on electronic source data verification elevate compliance granularity for patient-facing systems across cardiovascular and metabolic trials. The country's national pharmaceutical regulator enforces cryptographic integrity standards for multimodal patient communications. Frankfurt and Munich host sponsor IT departments consolidating previously separate vendor relationships around unified IRT platforms.
Japan
PMDA harmonization with ICH E6(R2) guidelines accelerates acceptance of cloud-based randomization engines for Phase III oncology studies. METI industrial policy supports digital health infrastructure investments by domestic pharmaceutical manufacturers. Tokyo and Osaka pharmaceutical R&D centers deploy hybrid IRT architectures with sensitive randomization logic maintained on-premises.
Switzerland
Swissmedic requirements for data sovereignty sustain demand for on-premises installations among large pharmaceutical companies with existing GxP-qualified infrastructure. Basel and Zurich anchor European trial operations for sponsors requiring single-tenant deployments within sponsor-controlled data centers. High fixed costs limit addressability to top-20 sponsors with dedicated validation engineering teams.
United Kingdom
MHRA recognition of FDA 21 CFR Part 11 equivalence reduces redundant validation documentation for US-exported platform licenses. London and Cambridge biotechnology sponsors prioritize web-based solutions for decentralized trial models requiring no app installation friction. Cloud-native architectures from US vendors compress study startup timelines for mid-cap sponsors.
Interactive Response Technology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented vendor relationships. Large pharmaceutical procurement teams consolidate around platforms unifying patient randomization, drug supply forecasting, and diary capture. Three archetypes dominate: life-science software specialists with vertical validation expertise, contact-center infrastructure extenders with healthcare compliance overlays, and full-service CROs operating as technology resellers. Competitive moves concentrate on strategic partnerships with electronic data capture vendors and geographic localization for Asia-Pacific regulatory acceptance.
Among life-science software specialists, Suvoda and Cenduit exemplify vertical-focused positioning validated for Phase III oncology protocols. Five9 occupies a position as a contact-center infrastructure extender adapting carrier-grade telephony for HIPAA-compliant healthcare workflows. ICON plc anchors the CRO-reseller archetype, integrating IRT platforms within full-service trial management contracts spanning enrollment to closeout.
| Leading Market Players |
|---|
| DSG |
| Five9 |
| Almac |
| ICON plc |
| IBM |
| Bracket |
| ePharmaSolutions |
| Suvoda |
| Cenduit |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in cloud-native validation engineering across the United States and Germany is compressing implementation timelines and elevating premium pricing for FDA 21 CFR Part 11-compliant deployments. This utilization squeeze simultaneously rewards established vendors with documented quality management systems and forces mid-cap biotechnology sponsors toward subscription-based platform access.
Pricing Analysis
Cost-plus contracts with inflation indexation dominate enterprise engagements for large pharmaceutical sponsors running multi-regional Phase III programs. Three-tier pricing structure across premium, standard, and economy levels separates validated life-science specialists from contact-center infrastructure extenders and unvalidated consumer communication tools. Price differentiation rests on ISO 27001 certification tier and dedicated account management intensity. Cost compression in standard-tier subscriptions is intensifying because CRO procurement teams are unbundling implementation services from ongoing operational support. Biotechnology firms with single-asset pipelines exhibit highest price sensitivity; Johnson & Johnson and Pfizer procurement teams demonstrate lowest sensitivity due to submission integrity requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as critical vendor selection criteria among clinical research organizations managing cash conversion cycles across lengthy trial durations. Platform development concentrates in the United States, Germany, and Switzerland, with cloud infrastructure provisioning anchored in AWS and Azure data centers meeting regional data sovereignty requirements. Raw material dependencies include carrier-grade PSTN and SIP trunking capacity, cryptographic hardware security modules, and continuous OS compatibility patching for mobile interfaces. Single-source vulnerability in telephony infrastructure concentration complicates global trial deployment. Distribution runs through direct enterprise sales teams for pharmaceutical sponsors and platform reseller arrangements with full-service CROs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interactive Response Technology vendors face sustained substitution pressure from unvalidated consumer communication platforms that jeopardize submission integrity. Incumbents must defend through compliance moats that generic infrastructure cannot replicate.
For Market Incumbents: Build regulatory-validation moats through preemptive FDA algorithm-validation documentation for AI-driven enrollment forecasting modules. Incumbents should deepen backward integration into electronic data capture system APIs to compress implementation bottlenecks. This defensive posture neutralizes threat from contact-center infrastructure extenders adapting carrier-grade telephony for healthcare workflows. Certification investment in PMDA and MFDS localization captures sponsor demand for Asia-Pacific trial execution without Western vendor latency. For New Entrants and Emerging Players: Pursue white-space targets in Japan and South Korea where PMDA and MFDS harmonization with ICH E6(R2) guidelines accelerates acceptance of cloud-based randomization engines. Mid-cap biotechnology sponsors in Germany seeking rapid study startup without capital infrastructure commitments represent the most penetrable segment. Go-to-market angle should emphasize microservices-based architectures that collapse distinction between traditional IVR telephony and real-time digital engagement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among life-science software specialists with vertical validation expertise validated for Phase III oncology protocols. Long-term viability over the five-to-ten year window favors platforms unifying patient randomization, drug supply forecasting, and diary capture within single validated environments. Acquisition target archetype: specialized vendors with documented quality management systems and established pharmaceutical sponsor relationships. Signal to watch is FDA draft guidance on AI/ML-enabled medical devices affecting algorithm-validation expectations for predictive enrollment forecasting.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifying randomization, drug supply, and diary capture within FDA 21 CFR Part 11-compliant environments reduces vendor fragmentation. |
| Geographic Expansion | PMDA and MFDS localization in Japan and South Korea captures sponsor demand for regional trial execution. |
| Regulatory Approval Pathway | Preemptive FDA algorithm-validation documentation for AI-driven modules creates compliance barriers against generic competitors. |
| Strategic Partnership | Electronic data capture vendor alliances compress integration bottlenecks and accelerate study startup timelines. |
| Product Launch | Microservices-based randomization engines enable mid-cap biotechnology sponsors to accelerate deployment without capital infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with clinical operations executives, regulatory affairs leads, GxP validation engineers, and CRO procurement managers; and secondary validation through FDA 21 CFR Part 11 guidance documents, EMA GCP guideline updates, ClinicalTrials.gov protocol registries, and ISO 27001 certification databases. Bottom-up triangulation across sponsor-specific deployment data and top-down reconciliation against aggregate platform licensing disclosures ensured dimensional consistency.
Forecast inputs considered deployment architecture transitions, regulatory harmonization trajectories, and sponsor consolidation patterns across the projection horizon. Segmentation dimensions modeled include product type, end-user archetype, technology deployment model, and application function with regulatory cluster overlay. CAGRs were derived from protocol amendment velocity, validation cycle compression rates, and cloud-native adoption curves specific to mid-cap biotechnology sponsors.
Sensitivities concentrate around FDA algorithm-validation guidance timing, PMDA electronic source data acceptance criteria evolution, and telephony infrastructure redundancy disruptions. Forecasts reflect documented assumptions regarding regulatory harmonization pace and sponsor IT consolidation behavior. Macroeconomic contraction affecting pharmaceutical R&D budgets, regulatory deviation from ICH E6(R2) harmonization, or breakthrough consumer communication platforms achieving validated status would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Global Tag Management System Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Big Data Technology Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Global Web Hosting Service Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
Document Management System Market
Digital Solutions
Kenya ICT Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Global Multichannel Campaign Management Market
Digital Solutions
Bangladesh ICT Market
Digital Solutions
Global Unified Endpoint Management Market