
 Lecture Capture Solutions Market | 2026-2036
Lecture Capture Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Lecture Capture Solutions Market Outlook
Market Context
Corporate training demand is realigning the buyer base as enterprises replace traditional learning management systems with integrated video platforms. Panopto Inc. leverages its higher education installed base to extend into corporate accounts. YuJa Corporation anchors its position through aggressive SaaS pricing and multi-tenant architecture. Echo360 Inc. differentiates via analytics-driven engagement tools that track learner participation metrics.
Technical Definition and Segment Structure
Lecture capture solutions encompass integrated audiovisual recording systems, media processing software, and cloud distribution platforms that encode, store, and stream educational or training content with resolution standards up to 4K and real-time captioning latency below three seconds. Cloud-based deployments are capturing the fastest expansion as institutions shed capital-intensive on-premise hardware refresh cycles. Managed services within the deployment model segment concentrate margin pools through multi-year service contracts that bundle storage, support, and content migration.
Regulatory Frame and Outlook
The US Department of Education enforces Section 508 accessibility mandates that require captioning and transcript availability for federally funded institutions, while the EU AI Act imposes transparency obligations on automated transcription tools deployed in European universities. These frameworks elevate compliance costs for entrants but protect incumbents with certified accessibility pipelines. Stakeholders must monitor pending updates to the Americans with Disabilities Act standards and the EU's forthcoming Digital Education Framework to anticipate procurement specification shifts.
Market Dynamics
Hybrid learning infrastructure mandates are compressing procurement cycles as universities race to deploy AI-enabled transcription and searchable video archives before the 2025 academic calendar. Institutions now treat lecture capture as core instructional infrastructure rather than supplemental technology.
Growth Catalysts
- Section 508 mandates:US federally funded institutions must provide captioning and transcript availability, creating compliance-driven procurement of certified accessibility pipelines.
- Corporate learning management replacement:Enterprises are retiring traditional LMS platforms in favor of integrated video platforms that unify training content distribution.
- Cloud-hosted deployment preference:Institutions are shedding capital-intensive on-premise hardware refresh cycles in favor of SaaS models with bundled storage and support.
Market Restraints
- GPU compute cost volatility:Real-time AI transcription and 4K encoding require specialized cloud compute resources subject to supply constraints and pricing spikes.
- EU AI Act transparency obligations:Automated transcription tools deployed in European universities face algorithmic audit requirements that extend sales cycles and elevate compliance costs.
- Legacy on-premise sunk costs:Institutions with recent hardware investments resist full cloud migration, fragmenting vendor addressable market.
Strategic Opportunities
- K-12 district penetration:Primary and secondary education systems remain underpenetrated relative to higher education, offering greenfield deployment potential.
- Medical and clinical training:Healthcare simulation centers require HIPAA-compliant video archiving with granular search capabilities for case review.
- Multi-tenant architecture:SaaS platforms serving multiple institutions from shared infrastructure capture operating leverage unavailable to single-tenant competitors.
Industry Challenges
- Integration complexity with legacy AV systems:Existing classroom hardware from disparate manufacturers requires custom middleware for unified capture and distribution.
- Real-time captioning latency requirements:Sub-three-second caption delivery demands specialized engineering talent scarce outside major technology hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecture Capture Solutions Market |
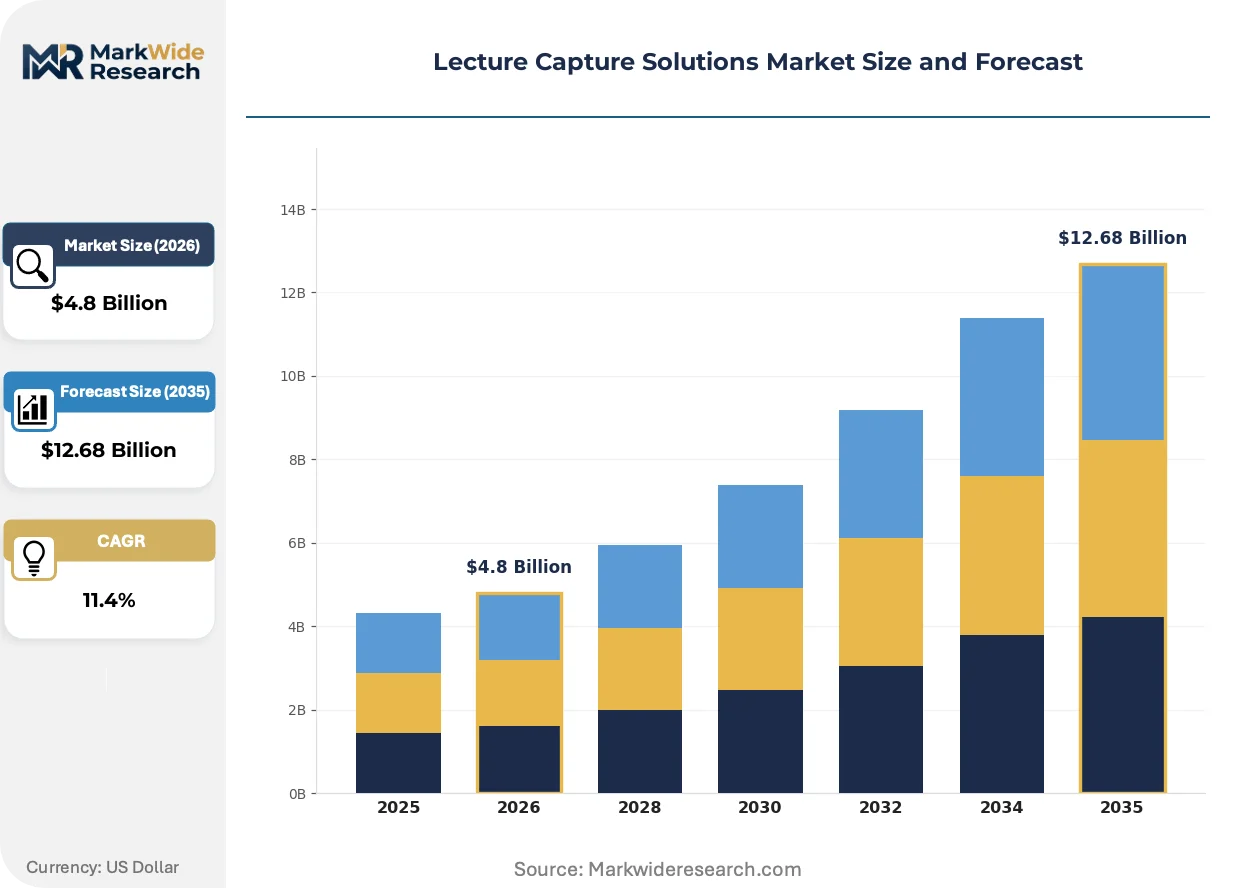
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
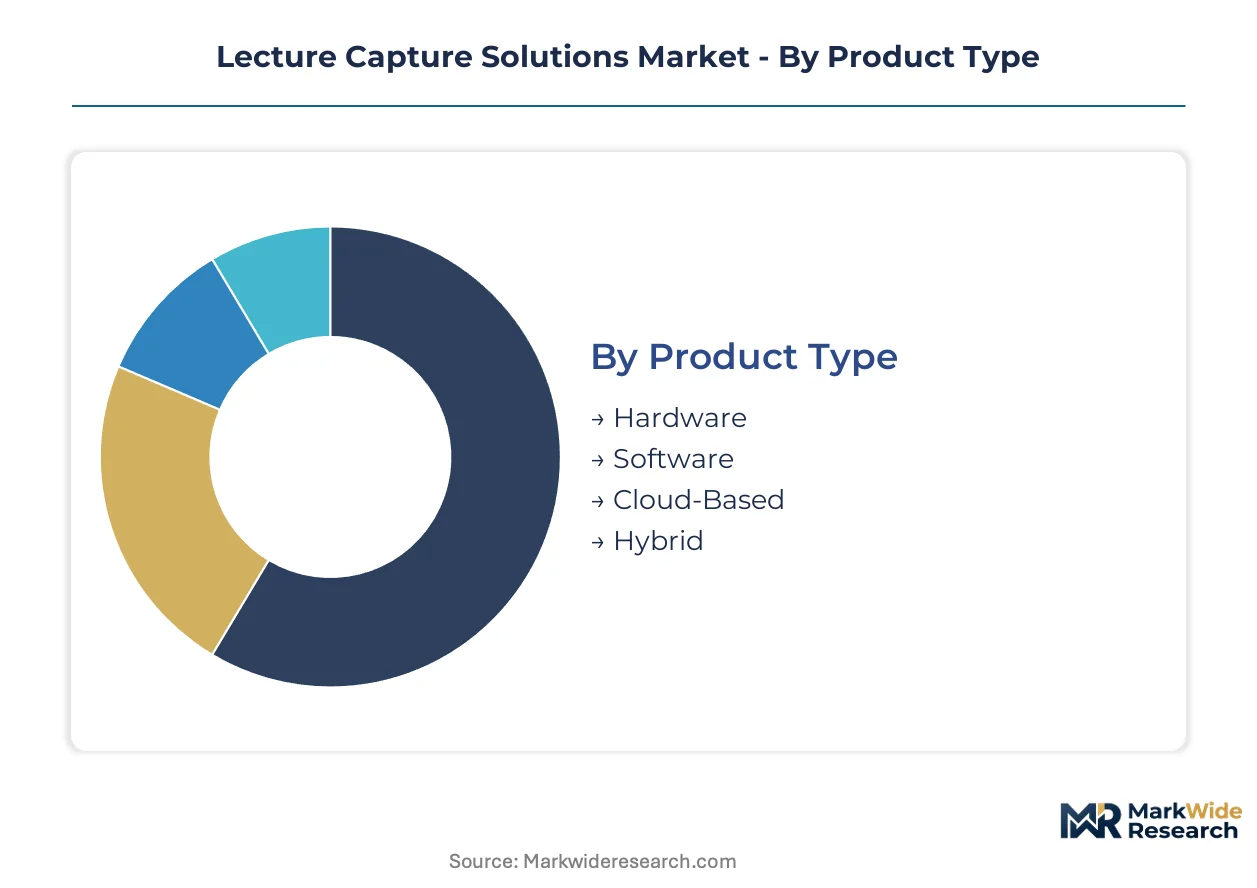
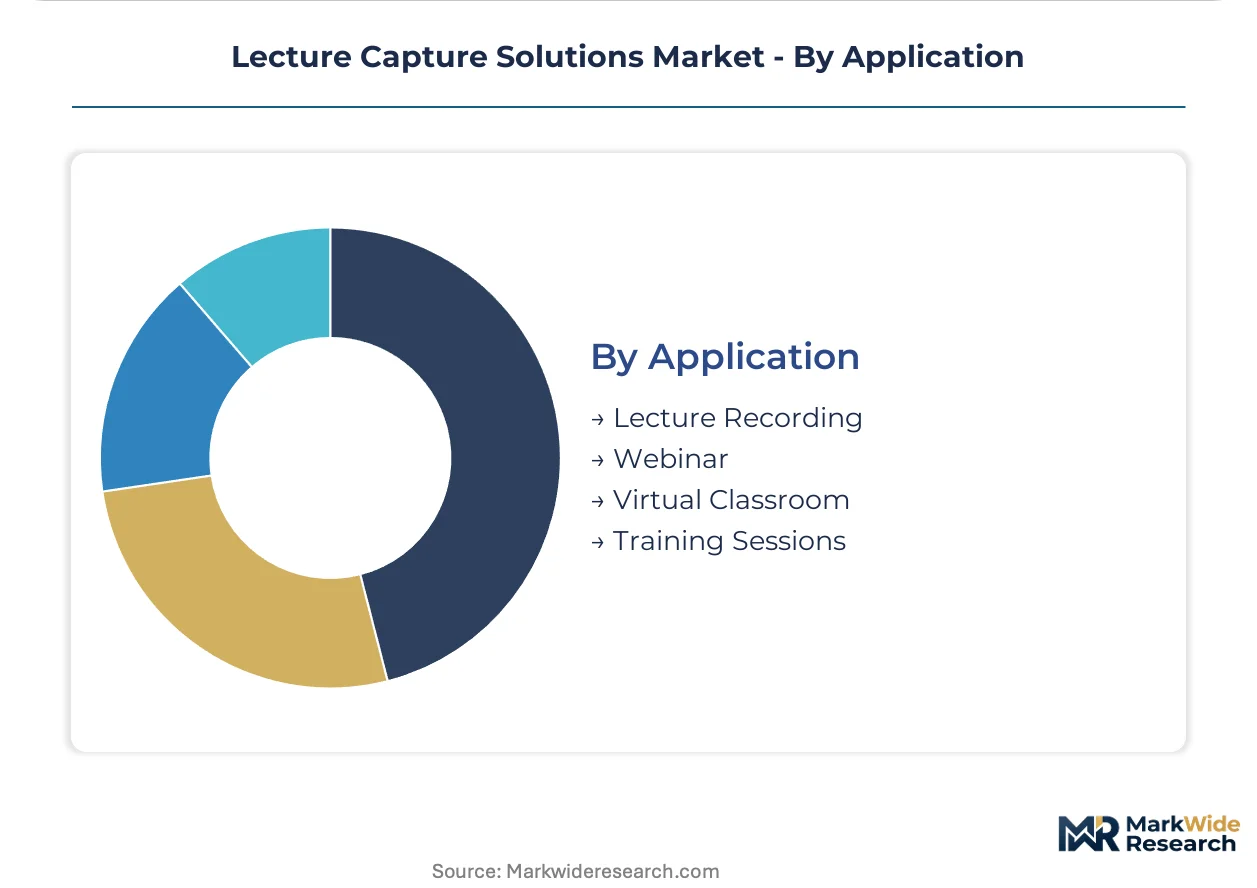
| Segmentation | Product Type: Hardware, Software, Cloud-Based, Hybrid Deployment Model: On-Premise, Cloud-Hosted, SaaS, Managed Services End User: Higher Education, K-12 Schools, Corporate Training, Government Application: Lecture Recording, Webinar, Virtual Classroom, Training Sessions |
| Companies Covered | Panopto Inc., YuJa Corporation, Echo360 Inc., TechSmith Corporation, Cisco Systems Inc., Kaltura Inc., Sonic Foundry, Haivision Systems Inc., Crestron Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecture Capture Solutions Market Strategic Shifts
Artificial intelligence is restructuring how educational content is produced, discovered, and consumed. Three developments are reshaping competitive positioning and procurement specifications.
Generative AI transcription engines with speaker diarization and technical vocabulary training are electrifying content discoverability in STEM lecture archives. Engineering faculties at research-intensive universities are adopting these tools fastest, compressing the time required to locate specific concepts across semester-long recordings from hours to seconds.
The EU AI Act imposes transparency obligations on automated transcription tools deployed in European universities. Vendors must document training data provenance and algorithmic decision logic, elevating compliance costs for entrants while protecting incumbents with certified accessibility pipelines. Procurement specifications in Germany, France, and the Netherlands now mandate AI Act conformity assessments.
Enterprise learning departments are unbundling video platform procurement from incumbent LMS contracts. Corporate training buyers now evaluate lecture capture solutions on standalone ROI metrics including engagement analytics and knowledge retention measurement, displacing bundled purchasing decisions dominated by IT procurement. This pattern is most visible in North American financial services and technology sectors.
Lecture Capture Solutions Market Segmentation
Procurement patterns in lecture capture diverge sharply by institutional IT maturity and compliance burden. Buyers with federal funding obligations prioritize certified accessibility pipelines, while cost-constrained K-12 districts favor bundled SaaS offerings that minimize capital deployment.
Product Type:
Capital intensity and refresh cycles determine buyer preference across hardware-software boundaries.
- Hardware:Dedicated encoder appliances and capture appliances with SDI/HDMI ingest process 4K streams at sub-100ms latency. Demand concentrates in research-intensive universities with legacy AV infrastructure investments across the United States, Germany, and Japan, where facilities teams resist full cloud dependency.
- Software:Browser-based capture clients and media processing engines enable AI transcription and searchable metadata generation without dedicated appliances. Corporate training departments in financial services and technology sectors across the United States and United Kingdom are adopting these tools fastest, driven by LMS replacement mandates and standalone ROI evaluation.
- Cloud-Based:Fully managed ingestion, processing, and distribution eliminates on-premise maintenance overhead.
- Hybrid:Local capture with cloud processing balances latency sensitivity with scalability.
Volume sits with hardware due to installed base persistence; growth tilts toward software as institutions shed capital refresh cycles.
Deployment Model:
Operating model preferences reflect institutional risk tolerance and IT staffing constraints.
- Cloud-Hosted:Vendor-managed infrastructure with dedicated tenant isolation delivers SOC 2 Type II and HIPAA compliance without client-side engineering. Higher education institutions across Canada, Australia, and the Netherlands are migrating fastest, compelled by shrinking capital budgets and EU AI Act transparency obligations that favor certified vendor pipelines.
- Managed Services:Multi-year contracts bundling storage, captioning, and content migration capture recurring revenue pools. Enterprise learning departments with dispersed global workforces favor this model for unified SLA coverage across the United States, United Kingdom, and Singapore.
- On-Premise:Self-hosted infrastructure persists in defense and classified research environments.
- SaaS:Shared multi-tenant platforms minimize per-seat cost for price-sensitive buyers.
Revenue concentrates in managed services due to contract duration; expansion accelerates in cloud-hosted as procurement cycles compress.
End User:
Compliance mandates and procurement authority structures reshape addressable market boundaries.
- Higher Education:Federally funded universities in the United States face Section 508 captioning mandates that elevate certified solution requirements. Research-intensive institutions across California, Massachusetts, and Texas are deploying AI-enabled transcription fastest, treating lecture capture as core instructional infrastructure rather than supplemental technology.
- Corporate Training:Enterprise learning departments unbundle video platform procurement from incumbent LMS contracts. Financial services and technology firms across New York, London, and San Francisco evaluate solutions on engagement analytics and knowledge retention metrics, displacing IT-dominated bundled purchasing.
- K-12 Schools:Primary and secondary systems remain underpenetrated relative to higher education, offering greenfield deployment potential.
- Government:Federal and state agencies require FedRAMP or equivalent security certification.
Spend dominance rests with higher education; steepest expansion trajectory emerges in corporate training as LMS replacement accelerates.
Application:
Use case specificity dictates feature prioritization and integration complexity.
- Lecture Recording:Semester-long course capture with searchable archives and granular playback controls. Engineering and medical faculties at research universities across the United States, Switzerland, and South Korea are adopting generative AI transcription with technical vocabulary training fastest, compressing concept location from hours to seconds.
- Virtual Classroom:Real-time synchronous delivery with sub-three-second caption latency and engagement analytics. Healthcare simulation centers across Florida, Pennsylvania, and Ontario require HIPAA-compliant archiving with case review search capabilities, driving specialized procurement.
- Webinar:Marketing and external training delivery prioritizes registration tracking and CRM integration.
- Training Sessions:Compliance and skills certification workflows demand completion verification and assessment linkage.
Deployment scale favors lecture recording; capability investment tilts toward virtual classroom as healthcare simulation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and similar innovation zones across the United States concentrate lecture capture solution development through university-industry partnerships and federal research funding pipelines.
United States
Section 508 accessibility mandates from the Department of Education drive compliance-heavy procurement at federally funded universities. California's public university system deploys AI-enabled transcription fastest, treating lecture capture as core infrastructure rather than supplemental technology. Massachusetts Institute of Technology and Stanford University anchor demand clusters in Greater Boston and Silicon Valley.
Germany
The EU AI Act imposes transparency obligations on automated transcription tools, extending sales cycles for vendors without certified accessibility pipelines. Technical universities in Bavaria and Baden-Württemberg prioritize hardware-software hybrid deployments to balance latency sensitivity with cloud scalability. RWTH Aachen and Karlsruhe Institute of Technology lead adoption of generative AI transcription with technical vocabulary training.
United Kingdom
Corporate training departments in London's financial services sector unbundle video platform procurement from incumbent LMS contracts. The Equality Act accessibility requirements elevate certified captioning solutions in higher education procurement. Oxford and Cambridge universities anchor research-intensive demand for searchable video archives with granular playback controls.
Canada
Shrinking capital budgets at Canadian universities accelerate migration to cloud-hosted deployment models with SOC 2 Type II compliance. Ontario's healthcare simulation centers require HIPAA-equivalent archiving with case review search capabilities. University of Toronto and McGill University drive demand for real-time synchronous delivery with sub-three-second caption latency.
Australia
Disability Discrimination Act compliance mandates elevate certified accessibility pipeline requirements across higher education institutions. Universities in New South Wales and Victoria prioritize SaaS models with bundled storage and support to minimize capital deployment. Monash University and University of Melbourne anchor adoption of multi-tenant architecture platforms serving multiple institutions from shared infrastructure.
Lecture Capture Solutions Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with software vendors capturing disproportionate investment growth while hardware incumbents defend installed base positions. The vendor base organizes into three tiers: cloud-native SaaS platforms, legacy on-premise system providers, and hybrid solution integrators. Two competitive moves dominate: multi-year managed service contracts that bundle storage and support, and AI transcription capability acquisitions that compress concept location from hours to seconds.
Within the cloud-native tier, Panopto Inc., YuJa Corporation, and Echo360 Inc. exemplify divergent strategic positioning. Panopto leverages its higher education installed base to extend into corporate accounts. YuJa anchors market position through aggressive SaaS pricing and multi-tenant architecture. Echo360 differentiates via analytics-driven engagement tools that track learner participation metrics.
| Leading Market Players |
|---|
| Panopto Inc. |
| YuJa Corporation |
| Echo360 Inc. |
| TechSmith Corporation |
| Cisco Systems Inc. |
| Kaltura Inc. |
| Sonic Foundry |
| Haivision Systems Inc. |
| Crestron Electronics Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native SaaS tiers diverge sharply from legacy on-premise bundles, with the former commanding subscription premiums for SOC 2 Type II certification and EU AI Act compliance while the latter faces price erosion from sunk hardware depreciation. This bifurcation concentrates margin pools in vendor-managed infrastructure even as GPU compute cost volatility squeezes transcription engine profitability.
Pricing Analysis
Short lead-time premiums attach to cloud-hosted deployments with sub-48-hour provisioning, while spot inventory discounts emerge for end-of-life encoder appliances. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in captioning latency guarantees and AI transcription accuracy thresholds. Cost compression in the hardware tier is intensifying because institutions resist capital refresh cycles. K-12 districts exhibit acute price sensitivity; research-intensive universities prioritize compliance certification over unit cost.
Supply Chain Analysis
Specialized engineering talent scarcity in Taiwan and South Korea constrains real-time captioning module production. Component sourcing draws from Taiwanese semiconductor foundries for encoding chipsets, South Korean memory suppliers for archival storage, and Chinese sensor manufacturers for AV capture hardware. Single-source vulnerability concentrates in GPU cloud compute provisioning for AI transcription engines. Distribution runs through direct vendor sales teams for enterprise accounts and value-added resellers for mid-market education clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based AI transcription is displacing legacy hardware-dependent capture systems, compressing procurement cycles as institutions shed capital-intensive refresh obligations. Vendors must navigate this transition while managing GPU compute cost exposure and regulatory certification burdens.
For Market Incumbents: Deepen multi-year managed service contract penetration to lock recurring revenue against SaaS pricing erosion from aggressive cloud-native entrants. Prioritize backward integration into captioning engine development to reduce third-party API dependency and defend margin structure. Fortify EU AI Act certification pipelines to extend sales cycle protection in European procurement.
For New Entrants and Emerging Players: Value-added resellers serving underpenetrated K-12 districts offer the fastest channel to revenue without direct incumbent confrontation. Target healthcare simulation centers in North America with HIPAA-compliant archiving solutions, where specialized search capabilities command premium positioning. Lead with aggressive SaaS pricing and multi-tenant architecture to capture operating leverage unavailable to single-tenant competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native platforms possessing certified accessibility pipelines given Section 508 and EU AI Act compliance mandates. Long-term viability favors vendors with demonstrated AI transcription accuracy improvements and established higher education installed bases. Monitor GPU cloud compute pricing indices as the inflection signal for margin compression or expansion across the sector.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Transcription Engine Acquisition | Compresses concept location from hours to seconds in STEM archives at MIT and Stanford. |
| Multi-Tenant Architecture Deployment | Captures operating leverage serving multiple Canadian and Australian universities from shared infrastructure. |
| HIPAA-Compliant Archiving Certification | Unlocks healthcare simulation center procurement in Florida, Pennsylvania, and Ontario. |
| EU AI Act Conformity Assessment | Extends sales cycle protection against uncertified entrants in German and French technical universities. |
| Corporate LMS Replacement Partnership | Displaces bundled IT procurement in New York and London financial services firms. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with CTOs at research-intensive universities, IT procurement officers in K-12 districts, platform engineers at cloud-native vendors, and integration specialists serving corporate training departments. SEC 10-K disclosures, EDGAR accessibility compliance reports, and EU AI Act conformity assessment databases provided validation. Bottom-up deployment counts and top-down education technology expenditure estimates were triangulated to constrain variance.
Granularity-level modeling captured deployment mode, institutional size tier, vertical segment, integration complexity, and regional regulatory cluster across the analysis window. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated GPU compute pricing indices and Section 508 enforcement intensity assumptions.
Caveats apply where GPU supply constraints or EU AI Act enforcement delays could materially shift the outlook. Forecasts embed assumptions regarding cloud migration velocity and AI transcription accuracy improvement curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Global E-Visa Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Chile ICT Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Data Marketplace Platform Market
Digital Solutions
Global Product Design and Development Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Global Document Scanning Services Market