
 Global Ad Tech Software Market | 2026-2036
Global Ad Tech Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ad Tech Software Market Foresight
Programmatic media buying revenue is tilting from open-exchange auctions toward private marketplace deals and retail media networks. Google LLC dominates the sell-side and buy-side stack through its integrated demand-side and supply-side platforms. Amazon.com, Inc. leverages its first-party commerce data to anchor retail media growth. The Trade Desk, Inc. specializes in independent demand-side platform services for agencies and brands seeking data portability.
Ad tech software comprises systems for automating digital media transactions, audience segmentation, campaign execution, and performance measurement across display, video, mobile, and connected television channels. Core functional parameters include sub-100-millisecond bid response latency in real-time bidding environments and interoperability with identity resolution frameworks. Cloud-based deployment leads solution architecture as publishers and agencies prioritize elastic infrastructure over fixed on-premises capacity. Demand-side platforms capture concentrated margin pools as advertisers consolidate spending through unified buying interfaces. Data management platforms face structural pressure as browser cookie deprecation and mobile identifier restrictions erode third-party data utility.
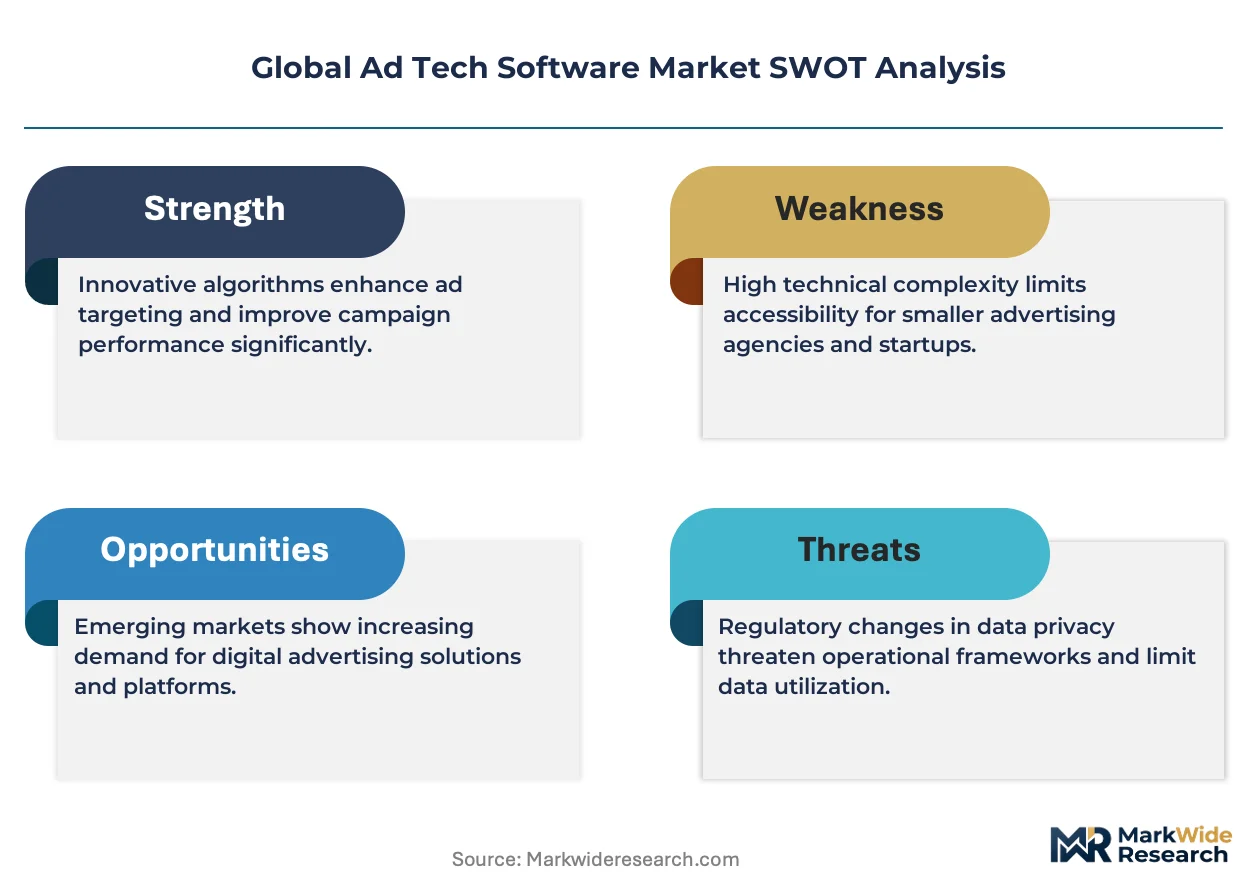
The Federal Trade Commission in the United States scrutinizes ad tech concentration and data practices, while the European Commission enforces GDPR and the Digital Markets Act to restrict platform self-preferencing. China's MIIT and SAMR impose data localization and algorithmic recommendation rules that shape how multinational ad tech vendors operate domestically. Stakeholders must monitor evolving privacy enforcement patterns and identity alternatives to determine capital allocation between contextual targeting, cohort-based measurement, and authenticated user solutions.
Market Dynamics
The deprecation of third-party browser cookies and mobile advertising identifiers is forcing a wholesale reconstruction of identity infrastructure across programmatic advertising systems. Publishers and platforms must now rebuild audience targeting around authenticated first-party data relationships and contextual signal processing.
Growth Catalysts
- Retail Media Networks:Commerce platforms with proprietary transaction data are expanding their advertising inventory, creating new demand for ad tech infrastructure that bridges sales and media execution.
- GDPR and EU AI Act:European privacy enforcement is accelerating investment in consent management platforms and privacy-preserving measurement techniques that comply with cross-border data transfer restrictions.
- Connected Television:Streaming video inventory growth is pulling programmatic buying interfaces into television budgets previously managed through upfront negotiations.
Market Restraints
- Identity Fragmentation:The absence of a universal cross-device identifier is fragmenting audience addressability and inflating campaign frequency management costs.
- Cloud Infrastructure Concentration:Dominant hyperscalers in the United States control the elastic compute resources required for sub-100-millisecond bidding, creating vendor lock-in risk.
- Regulatory Friction:China's MIIT data localization requirements constrain how multinational ad tech vendors deploy algorithmic recommendation engines domestically.
Strategic Opportunities
- India Digital Advertising:Underpenetrated programmatic adoption among regional language publishers creates whitespace for localized supply-side platform deployment.
- Clean Room Infrastructure:Privacy-preserving data collaboration environments are enabling advertisers to activate first-party data without direct consumer identifiers.
- Contextual Intelligence:Natural language processing and computer vision are converging to replace behavioral targeting with content-based audience inference.
Industry Challenges
- Measurement Standardization:Cross-platform attribution remains unresolved as platforms deploy incompatible incrementality testing methodologies.
- Legacy System Integration:Enterprise marketers face friction connecting modern programmatic interfaces with established media planning and financial reconciliation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ad Tech Software Market |
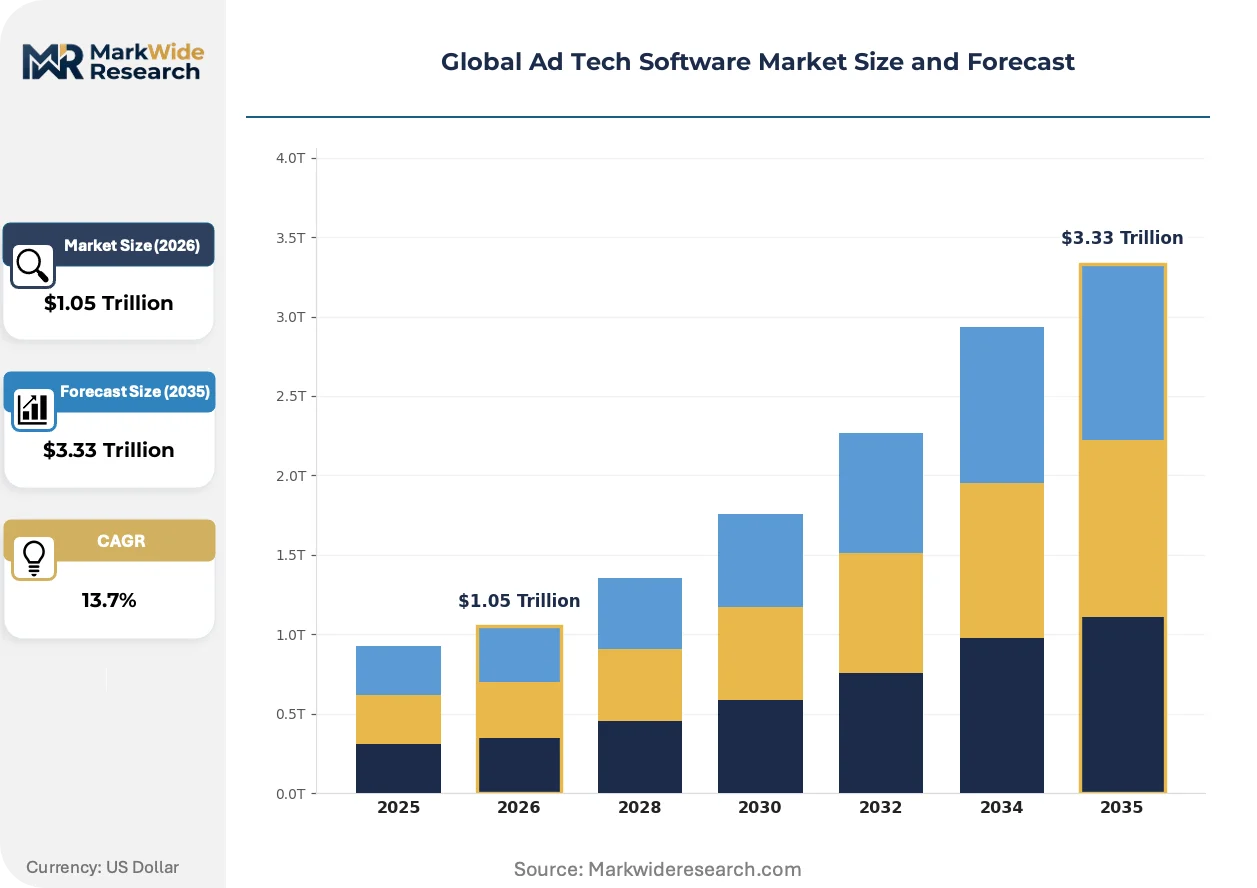
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $3.33 Trillion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services Solution: Demand-Side Platform, Supply-Side Platform, Data Management Platform, Ad Exchange, Attribution Software Application: Programmatic Advertising, Audience Targeting, Campaign Management, Real-Time Bidding, Analytics End User: Digital Agencies, Publishers, Advertisers, Marketing Teams, Content Creators |
| Companies Covered | Google LLC, Amazon.com, Inc., Meta Platforms Inc., The Trade Desk, Inc., Adobe Inc., Quantcast, Criteo S.A., Microsoft Corporation, Alibaba Group Holding Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ad Tech Software Market Shifts & Advancements
Artificial intelligence is compressing the latency between consumer intent signal and creative delivery, reshaping how media buying systems allocate budget across channels. This acceleration demands new architectural approaches to data processing and decision automation.
Real-time bidding infrastructure is hybridizing deterministic identity graphs with probabilistic cohort modeling to maintain addressability without persistent user tracking. Retail media networks and connected television publishers are adopting these hybrid approaches fastest, driven by inventory scarcity and premium CPM pressure. The structural consequence is a bifurcation between authenticated user solutions for known customers and contextual inference for prospecting audiences.
The EU AI Act risk classification framework is imposing algorithmic transparency requirements on programmatic platforms deploying automated decision systems in European markets. Ad tech vendors must now document training data provenance and enable human oversight of bidding algorithms. This regulatory pressure concentrates compliance investment among smaller demand-side platforms while reinforcing integrated stack advantages for larger providers.
Agency holding companies are consolidating media spending through fewer buying interfaces, compressing the number of demand-side platforms receiving direct client mandates. Independent trading desks and mid-market agencies are consolidating relationships around three to four core technology partners. This concentration is most visible in the United States and United Kingdom, where procurement functions have imposed vendor rationalization programs.
Global Ad Tech Software Market Segmentation
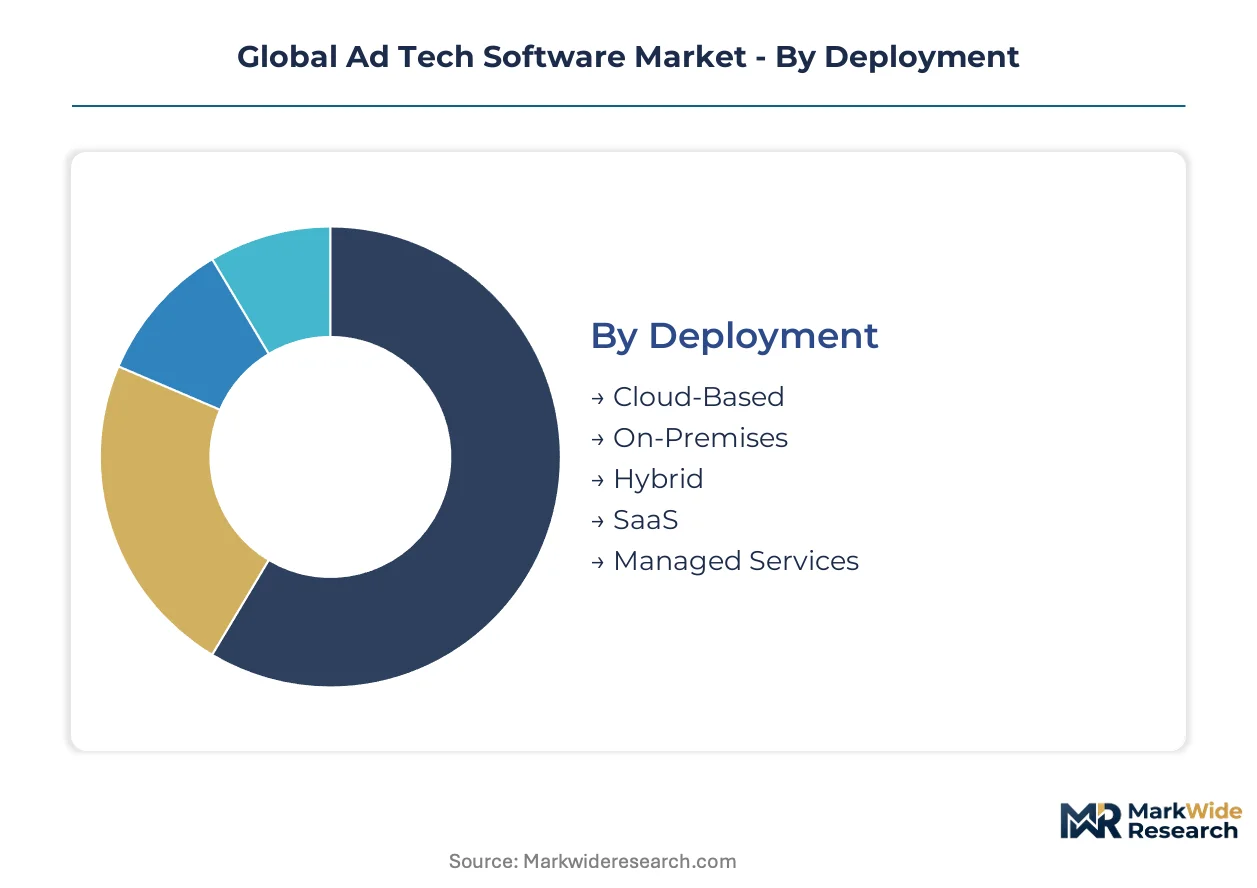
Ad tech software segmentation reveals how infrastructure choices cascade through media buying economics. Deployment models determine capital intensity and upgrade velocity. Solution types map directly to margin capture in the programmatic value chain.
Deployment:
Cloud-based deployments refresh on quarterly release cycles while on-premises installations linger across multi-year amortization schedules.
- Cloud-Based:Elastic compute resources scale bid processing capacity within minutes during traffic spikes. Retail media networks in the United States and United Kingdom prioritize this model to avoid upfront infrastructure commitment.
- On-Premises:Fixed hardware installations in regulated sectors maintain direct control over data residency and algorithmic audit trails. Financial services advertisers in Germany deploy these configurations to satisfy BaFin oversight requirements.
- Hybrid:Combines cloud burst capacity with on-premises core processing for latency-sensitive bidding.
- SaaS:Standardized interfaces accelerate time-to-campaign for mid-market agencies.
- Managed Services:Vendor-operated infrastructure transfers operational burden to specialized providers.
Cloud-based configurations anchor the volume base while SaaS offerings gain share at the steepest rate.
Solution:
Margin concentration follows proximity to advertiser budget flows, with buy-side platforms commanding premium pricing over publisher-facing tools.
- Demand-Side Platform:Unified buying interfaces consolidate spending across display, video, and connected television inventory. Agency holding companies in the United States route the majority of programmatic investment through three to four dominant DSP relationships.
- Supply-Side Platform:Publisher yield optimization tools manage header bidding wrapper configurations and floor price dynamics. Large digital publishers in the United Kingdom deploy these systems to maximize programmatic revenue per thousand impressions.
- Data Management Platform:Audience segmentation and activation infrastructure faces structural pressure from identifier deprecation.
- Ad Exchange:Liquidity venues connecting buy-side and sell-side demand.
- Attribution Software:Cross-channel measurement tools tracking incrementality across touchpoints.
Demand-side platforms anchor the volume base while attribution software gains share at the steepest rate.
Application:
Functional specialization determines integration complexity, with execution-layer tools requiring tighter real-time system coupling than planning applications.
- Programmatic Advertising:Automated media transaction systems spanning open exchange and private marketplace inventory. Advertisers in China leverage these capabilities through domestic exchanges operating under MIIT data localization frameworks.
- Audience Targeting:Identity resolution and segmentation engines rebuilding around first-party data graphs and contextual signals. European deployments emphasize GDPR-compliant consent management integration.
- Campaign Management:Workflow orchestration across creative trafficking and budget pacing.
- Real-Time Bidding:Sub-100-millisecond auction participation infrastructure.
- Analytics:Performance reporting and optimization recommendation engines.
Programmatic advertising anchors the volume base while audience targeting gains share at the steepest rate.
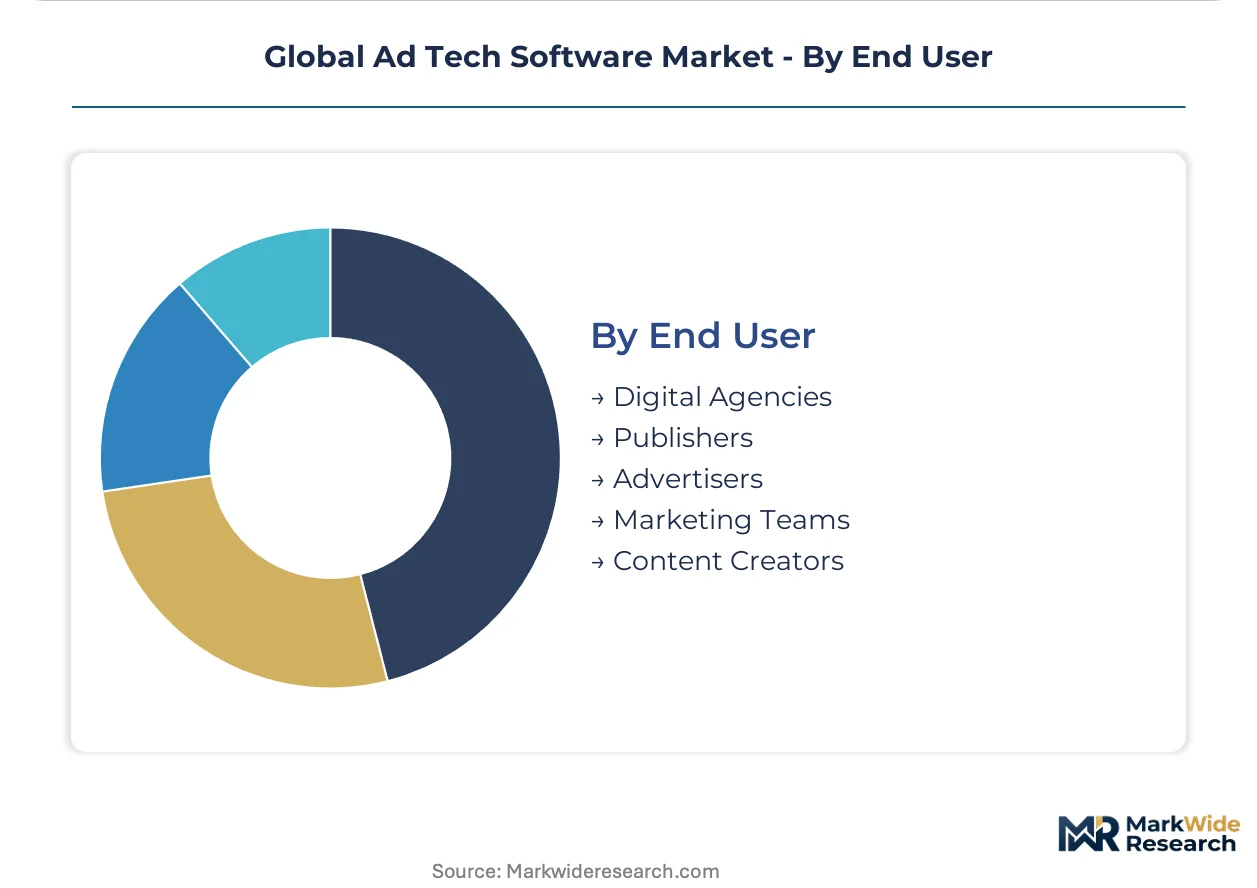
End User:
Procurement sophistication varies sharply, with enterprise marketing teams demanding API extensibility while smaller publishers prioritize managed service simplicity.
- Digital Agencies:Trading desk operations managing multi-client media investment across verticals. Large agency networks in the United States consolidate technology vendor relationships through centralized procurement functions.
- Publishers:Content monetization teams optimizing yield across direct-sold and programmatic channels. News publishers in France navigate CNIL consent requirements while maximizing programmatic fill rates.
- Advertisers:Brand-direct media teams building in-house buying capabilities.
- Marketing Teams:Product-level campaign execution within enterprise organizations.
- Content Creators:Individual and small-scale producers accessing self-serve advertising tools.
Digital agencies anchor the volume base while advertisers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertisers in the United States demonstrate the lowest price elasticity, absorbing premium CPMs for authenticated inventory, while publishers in India and Southeast Asia compete aggressively on rate efficiency to attract programmatic demand.
United States
Agency holding companies concentrate media investment through three to four dominant demand-side platforms, compressing vendor diversity. The FTC scrutinizes ad tech concentration and data practices under antitrust frameworks. New York and San Francisco host the largest cloud infrastructure clusters supporting sub-100-millisecond bidding latency.
China
Domestic exchanges capture programmatic volume through commerce platforms with proprietary transaction data. MIIT and SAMR impose data localization and algorithmic recommendation rules constraining multinational vendor operations. Beijing and Shanghai anchor the largest supply-side platform deployments for regional language publishers.
United Kingdom
Procurement functions at major agency networks enforce vendor rationalization programs, consolidating buying interfaces. The Information Commissioner's Office enforces GDPR consent requirements alongside the Digital Markets Act's platform self-preferencing restrictions. London concentrates demand-side platform engineering talent and trading desk operations.
Germany
Financial services advertisers deploy on-premises configurations to satisfy BaFin oversight requirements for algorithmic audit trails. The Bundesdatenschutzbehörde coordinates with EU regulators on cross-border data transfer enforcement. Frankfurt's data centers host elastic compute resources for latency-sensitive bidding serving central European markets.
India
Underpenetrated programmatic adoption among regional language publishers creates whitespace for localized supply-side platform deployment. TRAI guidelines shape data governance expectations for domestic advertising technology. Mumbai and Bangalore emerge as hubs for ad tech engineering serving Southeast Asian expansion.
Global Ad Tech Software Market Competitive Landscape
Integrated stack providers and independent demand-side platforms split the market between consolidated buying interfaces and specialized data portability services. The vendor base concentrates around three strategic archetypes: hyperscale cloud-anchored suites, commerce-data retail media networks, and independent trading infrastructure specialists. Competitive dynamics center on M&A activity absorbing point-solution providers and strategic partnerships bridging identity resolution gaps.
Within the independent platform tier, The Trade Desk, Inc. and Criteo S.A. exemplify demand-side specialization for agencies seeking cross-platform data portability. Google LLC and Amazon.com, Inc. occupy positions as integrated stack anchors, with the former dominating sell-side and buy-side infrastructure and the latter leveraging first-party commerce data to anchor retail media network expansion.
| Leading Market Players |
|---|
| Google LLC |
| Amazon.com, Inc. |
| Meta Platforms Inc. |
| The Trade Desk, Inc. |
| Adobe Inc. |
| Quantcast |
| Criteo S.A. |
| Microsoft Corporation |
| Alibaba Group Holding Limited |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States creates single-source dependency that determines both SaaS tier spreads and supply chain resilience architecture. Advertisers absorbing premium pricing for authenticated inventory tolerate vendor lock-in, while mid-market buyers facing cost compression migrate toward managed service bundles that outsource operational burden.
Pricing Analysis
Managed service and extended support contracts drive lifetime value capture as vendors monetize operational expertise beyond core platform licensing. SaaS tiering separates enterprise API extensibility from self-serve simplicity, with price differentiation anchored in data processing volume and integration complexity. Pricing pressure stems from identifier deprecation compressing attribution software margins as buyers demand proof of incrementality. Enterprise marketing teams show lowest price elasticity for authenticated solutions, while regional publishers in India and Southeast Asia compete aggressively on rate efficiency.
Supply Chain Analysis
Elastic compute resources draw from hyperscaler infrastructure concentrated in the United States, China, and Germany. Raw material dependencies center on semiconductor fabrication for AI acceleration, submarine cable capacity for cross-border data transfer, and rare earth elements for server manufacturing. Supply chain risk rests on regulatory friction as China's MIIT data localization requirements fragment multinational vendor operations. Distribution runs through direct enterprise sales for large advertisers, agency trading desk partnerships for media buying consolidation, and self-serve portals for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Identity infrastructure reconstruction represents a high-growth disruption justified by the EU AI Act's algorithmic transparency mandates forcing compliance investment concentration. Stakeholders must position against this regulatory inflection to capture margin pools reshaping around first-party data and contextual intelligence.
For Market Incumbents: Harden defensive moats by deepening first-party data graph integration and acquiring consent management platform specialists before compliance costs escalate. Threat vectors include independent demand-side platforms capturing agency procurement rationalization mandates and retail media networks disintermediating traditional inventory access. Priority levers center on backward integration into clean room infrastructure and captive supply of identity resolution services. For New Entrants and Emerging Players: Underpenetrated regional language publishers in India represent the most penetrable entry point for localized supply-side platform deployment. White-space targets include privacy-preserving measurement tooling for European GDPR-constrained markets and contextual intelligence engines replacing deprecated behavioral targeting. Go-to-market execution should anchor through agency trading desk partnerships rather than direct advertiser sales cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized point-solution providers with authenticated user infrastructure. Long-term viability across the next decade hinges on first-party data asset quality and regulatory compliance automation capabilities. Acquisition target archetypes include consent management platforms and natural language processing engines for contextual targeting. The signal to watch is procurement function vendor rationalization velocity at major agency networks.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies demand-side and supply-side stacks to capture margin across programmatic transactions. |
| Strategic Partnership | Bridges identity resolution gaps between retail media networks and independent publishers. |
| Acquisition of Specialist Firm | Absorbs consent management or contextual intelligence capabilities ahead of EU AI Act enforcement. |
| Geographic Expansion | Establishes localized supply-side platform presence in India's underpenetrated regional publisher market. |
| Product Launch | Deploys clean room infrastructure enabling privacy-preserving first-party data collaboration. |
Research Methodology
A standing panel of demand-side platform engineers, agency trading desk directors, publisher yield managers, and regulatory compliance officers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile advertising metrics, and EU regulatory enforcement databases. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against programmatic trading volume aggregates anchored value estimates.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling deployment configurations, solution types, application functions, and end-user procurement sophistication. Segmentation dimensions included cloud elasticity requirements, buy-side versus sell-side margin capture, real-time bidding latency thresholds, and regional regulatory cluster patterns. CAGRs derived from trend extrapolation of retail media network infrastructure investment and connected television programmatic adoption curves, cross-referenced against privacy regulation implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in digital advertising spend cyclicality or cross-border data transfer policy stringency would shift the trajectory. Forecasts reflect documented assumptions regarding identifier deprecation velocity and clean room technology maturation. Cross-checking against IAB programmatic spending benchmarks and hyperscaler cloud revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Digital Evidence Management System Market
Digital Solutions
Construction Design App Market
Digital Solutions
Real-Time (Graphics and Video) Rendering Solutions Market
Digital Solutions
System Integrator Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Web Performance Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Global Tracking As a Service Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Business Information Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Application Performance Management Market