
 Self Service Technology Market | 2026-2036
Self Service Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Self Service Technology Market Intelligence
The hardware-software capability gap between legacy ATM manufacturers and cloud-native kiosk vendors is unwinding as platform economics favor modular architectures. NCR Corporation leverages its banking heritage and retail software stack to sustain dual-sector dominance. Diebold Nixdorf anchors its position through service contracts and branch-transformation consulting for financial institutions. Toshiba Global Commerce Solutions competes in grocery and convenience retail with edge-computing checkout platforms that integrate computer vision.
Self service technology encompasses unattended terminals, automated teller machines, interactive kiosks, and intelligent vending systems that process transactions, dispense goods, or deliver services without human intervention. These systems integrate touchscreens, biometric sensors, payment card readers, and network connectivity to execute retail purchases, financial withdrawals, hospitality check-ins, and healthcare registrations. Kiosks lead product-type revenue by serving quick-service restaurants and airline ticketing lobbies where labor substitution delivers measurable throughput gains. Biometrics represents the fastest-growing technology segment as facial recognition and fingerprint authentication replace PIN entry for fraud reduction. The vending machine category remains mature in beverage and snack applications but finds renewed growth in electronics, pharmaceuticals, and industrial PPE dispensing.
The FCC governs wireless communication modules in self-service terminals across the United States, while the EU AI Act imposes risk-classification requirements on biometric-enabled kiosks deployed in European public spaces. PCI DSS compliance shapes payment-hardware design decisions, forcing manufacturers to embed certified encryption chips rather than relying on software-based security. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions restricting facial recognition and markets encouraging biometric adoption for fraud prevention.
Market Dynamics
The platform economics of modular cloud-native architectures is compressing margins for legacy ATM manufacturers while expanding addressable markets for software-first kiosk vendors. This structural shift reconfigures competitive boundaries between financial services and retail automation.
Growth Catalysts
- Labor substitution in quick-service restaurants:US quick-service chains deploy self-checkout stations to offset wage inflation and improve throughput during peak hours. Chipotle and McDonald's franchisees drive kiosk order penetration above sixty percent in urban locations.
- EU AI Act biometric mandates:European transit authorities accelerate facial recognition deployments for passenger authentication at unattended terminals, creating compliant hardware refresh cycles across France, Germany, and Netherlands hub airports.
- Edge computing integration:Computer vision-enabled checkout platforms reduce dependency on cloud latency for real-time product recognition, enabling grocery and convenience retail deployments in bandwidth-constrained environments.
Market Restraints
- Semiconductor supply concentration:Payment card reader encryption chips and touchscreen controllers face sourcing constraints from Taiwan and South Korea foundries, extending lead times for kiosk manufacturers.
- PCI DSS certification friction:Hardware-embedded encryption requirements force redesign cycles that delay product launches by twelve to eighteen months for non-compliant legacy platforms.
- Mobile wallet substitution:Smartphone-based checkout and tap-to-pay applications reduce consumer willingness to interact with physical terminals in premium retail environments.
Strategic Opportunities
- Pharmaceutical vending expansion:Unattended dispensing systems for prescription medications and diagnostic kits address understaffed pharmacy deserts in rural United States counties and Japanese aging municipalities.
- Industrial PPE automation:Manufacturing facilities in Germany and Texas deploy intelligent lockers for safety equipment tracking, integrating with enterprise resource planning systems for consumption-based replenishment.
- FCC spectrum allocation:Newly available mid-band frequencies enable wireless kiosk deployments in temporary event spaces and construction sites without fixed infrastructure.
Industry Challenges
- Embedded systems cybersecurity expertise:Manufacturers struggle to recruit firmware engineers capable of implementing zero-trust architectures for unattended payment terminals.
- Legacy banking core integration:ATM network operators face middleware complexity when connecting cloud-native transaction platforms to decades-old mainframe authorization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Service Technology Market |
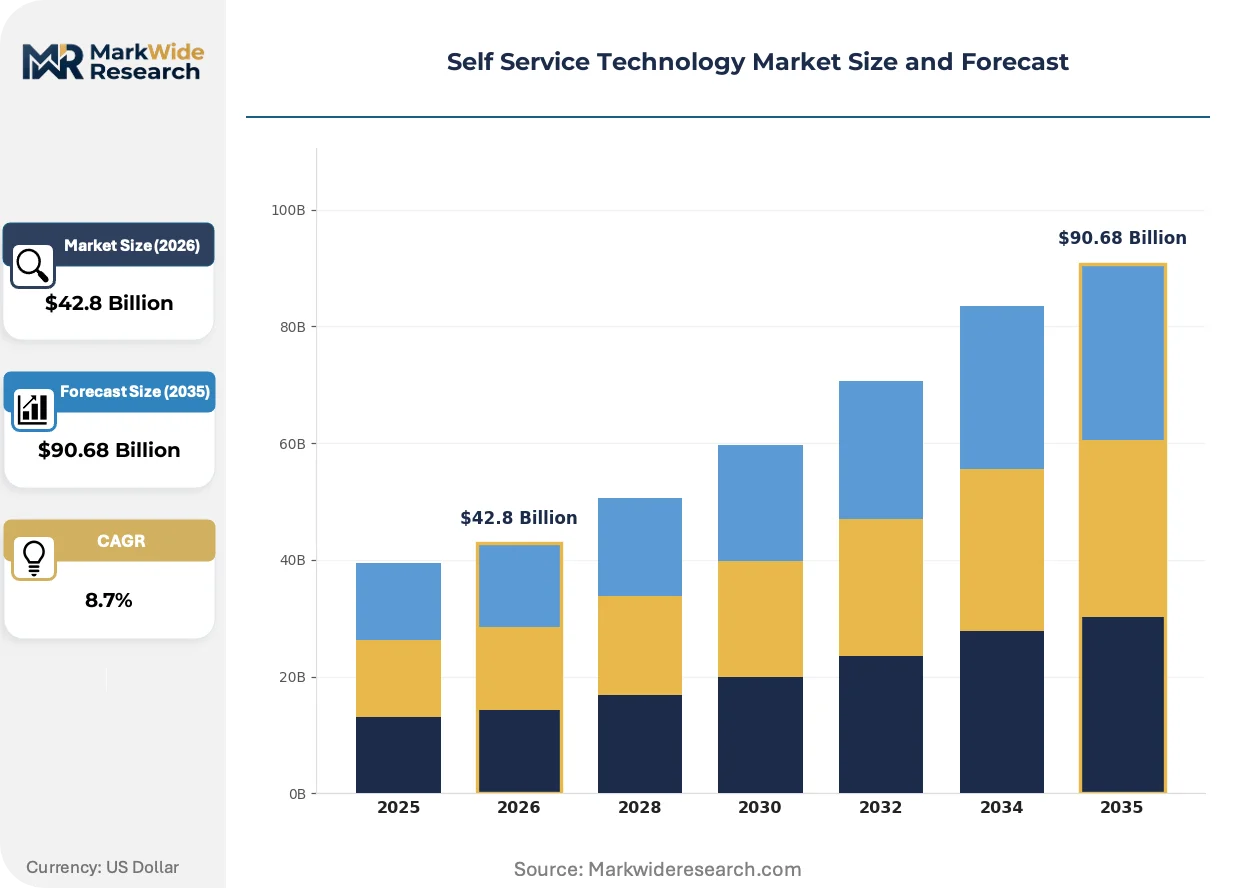
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $90.68 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kiosks, ATMs, Smart Machines, Vending Machines Technology: RFID, NFC, Touchscreen, Biometrics Application: Retail, Banking, Hospitality, Healthcare End User: Consumers, Businesses, Government, Educational Institutions |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Toshiba Global Commerce Solutions, KIOSK Information Systems, Crane Company, HESS Cash Systems, HYOSUNG TNS, Fujitsu, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Service Technology Market Strategic Shifts & Innovations
Biometric authentication methods are displacing credential-based verification across unattended terminal categories, while regulatory fragmentation between privacy-first and security-first jurisdictions forces product line diversification.
Computer vision checkout technology is bifurcating self-service retail into two deployment models. Amazon Fresh and Tesco Express locations adopt camera-only systems that eliminate barcode scanning entirely. Smaller convenience operators prefer hybrid platforms combining vision assistance with traditional scanning for lower capital commitment. This technology is bifurcating vendor strategies between full-stack platform providers and component suppliers.
The EU AI Act risk-classification framework is forcing biometric-enabled kiosk manufacturers to implement audit trails and human oversight protocols for facial recognition deployments in European public spaces. German railway stations and French municipal buildings now require explicit consent mechanisms and data retention limits. Transit operators in Spain and Italy are responding by segregating European and non-European product variants to maintain deployment velocity in less restrictive markets.
Service contract unbundling is fragmenting revenue streams for traditional hardware vendors. Diebold Nixdorf and NCR Corporation face pressure to separate software subscriptions from maintenance agreements as cloud-native competitors offer pure SaaS pricing. This shift concentrates procurement decision-making with chief information officers rather than facilities managers, most visibly in United States regional bank branch transformation programs.
Self Service Technology Market Segmentation
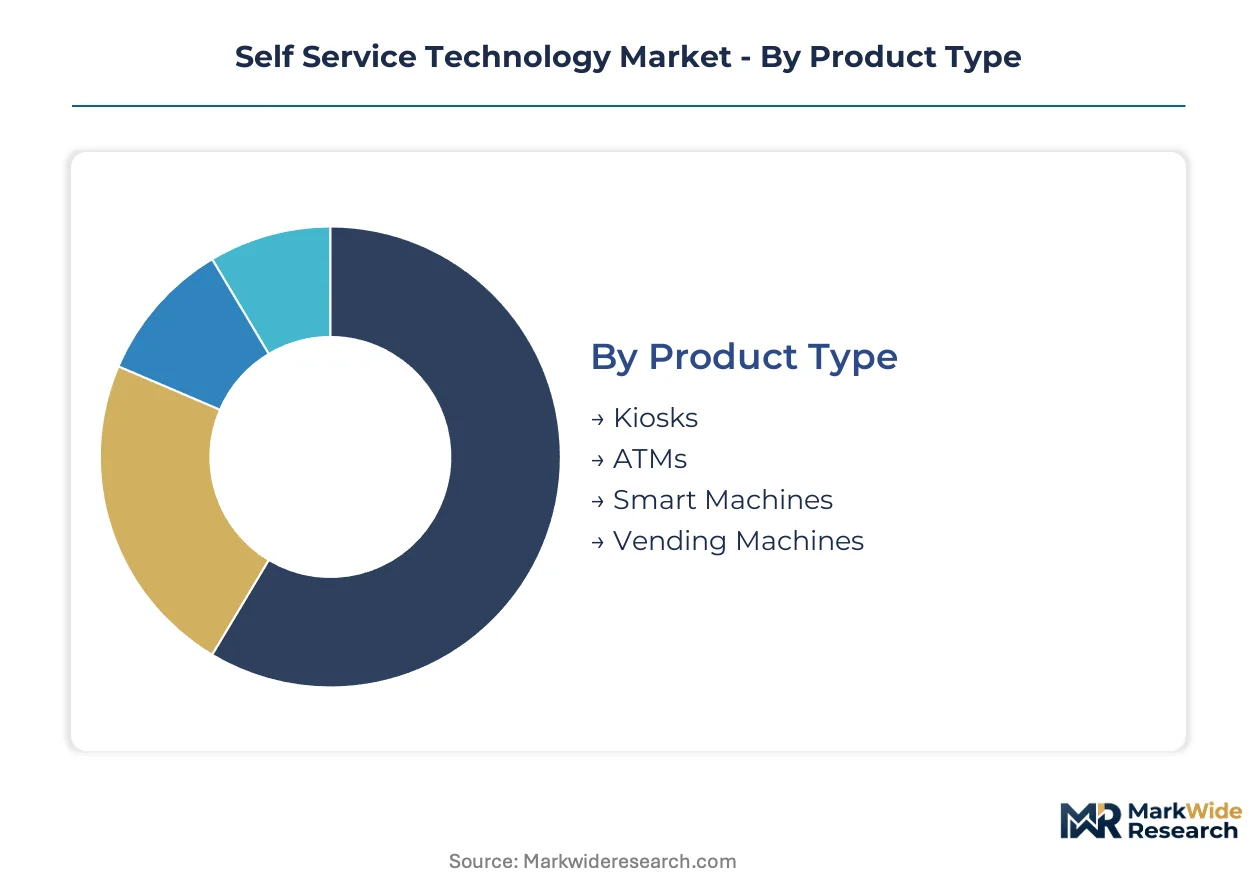
Self-service technology segmentation reveals divergent compliance burdens and hardware refresh cycles across product categories. Regulatory fragmentation between biometric-permissive and privacy-first jurisdictions forces manufacturers to maintain parallel product lines.
Product Type:
PCI DSS certification timelines and EU AI Act risk classifications create divergent go-to-market pathways for hardware categories.
- Kiosks:Interactive terminals integrate touchscreens, payment readers, and network modules for unattended transactions. Quick-service restaurants in the United States and transit hubs in France, Germany, and the Netherlands drive replacement cycles as operators seek labor substitution and passenger throughput gains.
- ATMs:Cash-dispensing terminals embed certified encryption chips and wireless communication modules governed by FCC rules in the United States. Legacy manufacturers face margin compression from cloud-native competitors offering modular software stacks.
- Smart Machines:Intelligent dispensing systems for electronics, pharmaceuticals, and industrial PPE integrate ERP connectivity for consumption-based replenishment.
- Vending Machines:Automated retail terminals for beverages and snacks remain mature, though pharmaceutical and diagnostic kit dispensing is expanding in rural United States counties and Japanese aging municipalities.
Established volume favors ATMs; emerging adoption favors kiosks.
Technology:
Hardware-software integration depth determines which authentication methods achieve regulatory clearance in European public spaces versus North American retail environments.
- Biometrics:Facial recognition and fingerprint authentication systems displace PIN entry for fraud reduction. EU AI Act mandates force audit trails and explicit consent mechanisms in French municipal buildings and German railway stations, while United States quick-service chains accelerate deployment without comparable restrictions.
- Touchscreen:Capacitive and resistive interface panels serve as the primary human-machine interaction layer across all product types. Semiconductor sourcing constraints from Taiwan and South Korea foundries extend lead times for controller procurement.
- RFID:Radio-frequency identification enables contactless product tracking and inventory management in industrial PPE lockers and pharmaceutical dispensing systems.
- NFC:Near-field communication modules support tap-to-pay transactions and mobile wallet integration, though smartphone-based checkout reduces consumer willingness to interact with physical terminals in premium retail settings.
Mature penetration favors touchscreen; steepest expansion trajectory belongs to biometrics.
Application:
Customer throughput requirements and labor cost structures determine adoption intensity across sector verticals.
- Retail:Grocery and convenience operators deploy edge-computing checkout platforms with computer vision for real-time product recognition. Hybrid platforms combining vision assistance with traditional scanning attract smaller operators seeking lower capital commitment.
- Banking:Financial institutions pursue branch transformation programs connecting cloud-native transaction platforms to legacy mainframe authorization systems. Service contract unbundling shifts procurement authority from facilities managers to chief information officers.
- Hospitality:Hotels and airports deploy self-service check-in terminals to reduce front-desk staffing during peak arrival windows.
- Healthcare:Patient registration kiosks streamline administrative intake while prescription dispensing automation addresses pharmacy deserts.
Current installed base concentrates in retail; healthcare represents the fastest-climbing application vertical.
End User:
Budget authority and procurement sophistication determine whether deployments prioritize hardware durability or software flexibility.
- Businesses:Quick-service restaurant chains and big-box retailers replace traditional checkout lanes with self-service stations to offset wage inflation. Chipotle and McDonald's franchisees drive kiosk order penetration above sixty percent in urban United States locations.
- Government:Transit authorities and municipal buildings in Europe accelerate facial recognition deployments for passenger authentication, requiring compliant hardware refresh cycles.
- Consumers:Individual adoption patterns reflect convenience preferences and trust in unattended terminal security.
- Educational Institutions:Universities deploy self-service systems for campus dining, library checkouts, and administrative services.
Procurement volume favors businesses; regulatory compliance complexity favors government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where quick-service restaurant chains and big-box retailers absorb premium hardware costs for labor substitution, while European markets face compliance-driven margin compression from biometric regulation.
United States
Chipotle and McDonald's franchisees drive kiosk order penetration above sixty percent in urban locations, offsetting wage inflation through throughput gains. FCC rules govern wireless communication modules in self-service terminals nationwide. Dallas-Fort Worth and Atlanta anchor major deployment clusters for airport and transit hub installations.
Germany
German railway stations and manufacturing facilities deploy intelligent PPE lockers and biometric-enabled terminals for passenger authentication and safety equipment tracking. The EU AI Act imposes risk-classification requirements on facial recognition systems in public spaces. Munich and Frankfurt concentrate kiosk deployments for branch transformation and transit automation.
France
French municipal buildings and transit authorities accelerate compliant hardware refresh cycles for facial recognition deployments under EU AI Act mandates. ANSM and CNIL oversight shapes data retention limits and explicit consent mechanisms. Paris hub airports lead passenger authentication terminal installations.
Japan
Aging municipalities drive pharmaceutical and diagnostic kit vending expansion in underserved pharmacy deserts. METI standards guide edge-computing checkout platform certification. Tokyo and Osaka anchor deployment clusters for hospitality check-in terminals and automated retail systems.
Netherlands
Amsterdam and Rotterdam transit hubs expand kiosk deployments for passenger check-in and baggage handling under EU AI Act compliance frameworks. Dutch quick-service operators adopt hybrid computer vision checkout platforms. Eindhoven's technology corridor supports semiconductor sourcing for touchscreen controller procurement.
Self Service Technology Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where modular software vendors capture margin expansion while legacy hardware manufacturers defend installed base relationships. The market consolidates around three strategic archetypes: banking heritage incumbents with dual-sector capabilities, retail-focused edge-computing specialists, and component suppliers with captive semiconductor access. Dominant competitive moves include service contract unbundling to shift procurement authority toward chief information officers, and geographic product segregation to maintain deployment velocity across regulatory environments.
Within the banking heritage tier, NCR Corporation and Diebold Nixdorf occupy positions sustained through branch-transformation consulting and long-term service relationships. Toshiba Global Commerce Solutions anchors the retail-focused vector, exemplifying edge-computing checkout platform specialization. These three entities represent the convergence of hardware durability requirements with software flexibility demands across financial and retail automation verticals.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| Toshiba Global Commerce Solutions |
| KIOSK Information Systems |
| Crane Company |
| HESS Cash Systems |
| HYOSUNG TNS |
| Fujitsu |
| Zebra Technologies |
| Others |
Cost & Logistics Intelligence
PCI DSS certification gates both hardware qualification and price differentiation in self-service terminals, forcing manufacturers to embed certified encryption chips before achieving premium-tier positioning against uncertified competitors. This compliance threshold simultaneously restricts supplier pools and stratifies pricing across certified and non-certified product tiers.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard kiosk configurations, particularly for biometric-enabled terminals with EU AI Act-compliant audit trails. Subscription-SaaS pricing models now dominate among cloud-native vendors, while legacy ATM manufacturers defend per-unit transactional structures. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in standard touchscreen tiers is intensifying because Taiwan and South Korea foundry constraints extend lead times. Quick-service restaurant chains exhibit lowest price sensitivity; regional bank procurement committees show highest.
Supply Chain Analysis
Taiwan and South Korea anchor semiconductor fabrication for payment card reader encryption chips and touchscreen controllers. The supply chain draws from German precision mechanics for kiosk enclosures, Chinese PCB assembly, and Japanese display panels. Single-source vulnerability concentrates in Taiwan foundry capacity for secure element production. Distribution runs through direct OEM relationships with large deployers and regional systems integrators for mid-market installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward chief information officers as procurement authority migrates from facilities managers, consolidating decision-making among technically sophisticated stakeholders who prioritize software flexibility over hardware durability.
For Market Incumbents: Compound defensive advantages by unbundling service contracts into separable software subscriptions, addressing cloud-native competitors' pure-SaaS pricing. Invest in firmware engineering capabilities for zero-trust architectures, countering embedded systems cybersecurity talent scarcity. Prioritize backward integration into semiconductor sourcing to reduce Taiwan foundry dependency. For New Entrants and Emerging Players: Pharmacy desert automation in rural United States counties represents an underserved service layer where incumbents lack dedicated deployment infrastructure. Pharmaceutical vending for prescription medications and diagnostic kits offers lowest competitive density. Target Japanese aging municipalities with ERP-integrated dispensing systems, leveraging consumption-based replenishment models as the primary go-to-market angle. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape by forcing biometric-enabled kiosk manufacturers toward audit-trail capabilities and human oversight protocols. Five-to-ten-year viability favors component suppliers with captive semiconductor access or modular software vendors with edge-computing platforms. Monitor FCC spectrum allocation decisions for mid-band frequencies as the inflection signal indicating wireless kiosk deployment acceleration in temporary infrastructure environments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native transaction stacks displace legacy ATM middleware, capturing CIO procurement authority from facilities managers. |
| Regulatory Compliance Investment | EU AI Act audit-trail capabilities enable European public space deployments while excluding non-compliant competitors. |
| Geographic Expansion | Pharmaceutical vending penetrates rural United States pharmacy deserts and Japanese aging municipalities with distinct regulatory pathways. |
| Strategic Partnership | ERP system integrations for industrial PPE lockers create consumption-based replenishment revenue streams in German manufacturing. |
| Acquisition of Specialist Firm | Computer vision engineering teams accelerate edge-computing checkout platform development for bandwidth-constrained retail environments. |
Research Approach
Operator-level perspectives from kiosk deployment managers, ATM network operators, quick-service restaurant franchise technology directors, airport passenger experience leads, and pharmaceutical supply chain coordinators anchored the qualitative base. Primary interview insights combined with secondary validation from FCC equipment authorization databases, PCI DSS certified product listings, EU AI Act implementation guidance, and SEC 10-K filings from publicly traded automation vendors. Bottom-up unit deployment estimates and top-down market sizing triangulated across hardware shipment tracking and software subscription disclosures.
Sensitivity analysis tested forecast outputs against alternative scenarios for semiconductor supply normalization and biometric regulatory divergence. The analytical framework modeled product type, technology authentication method, application vertical, and end-user procurement sophistication across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating edge-computing adoption curves and service contract unbundling velocity. Forecast inputs included kiosk penetration rates in quick-service restaurants and ATM replacement cycles tied to branch transformation consulting engagements.
Underlying assumptions cover sustained labor cost pressure in United States food service, stable EU AI Act enforcement timelines, and continued Taiwan foundry concentration for secure elements, with deviation risk concentrated in semiconductor supply disruptions and mobile wallet substitution acceleration. Recalibration cycles align with material shifts in FCC spectrum allocation, PCI DSS certification requirement revisions, and EU biometric consent mechanism court interpretations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Smart Signage Market
Digital Solutions
Mock Interview Platforms Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
Global Cloud Monitoring Tools Market
Digital Solutions
Czech Republic ICT Market
Digital Solutions
Smart Government Market
Digital Solutions
API Management Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Global DDI Market