
 North America Forklift Truck Market | 2026-2036
North America Forklift Truck Market Size, Share, and Industry Trends Forecast 2026-2036
North America Forklift Truck Market Analytics
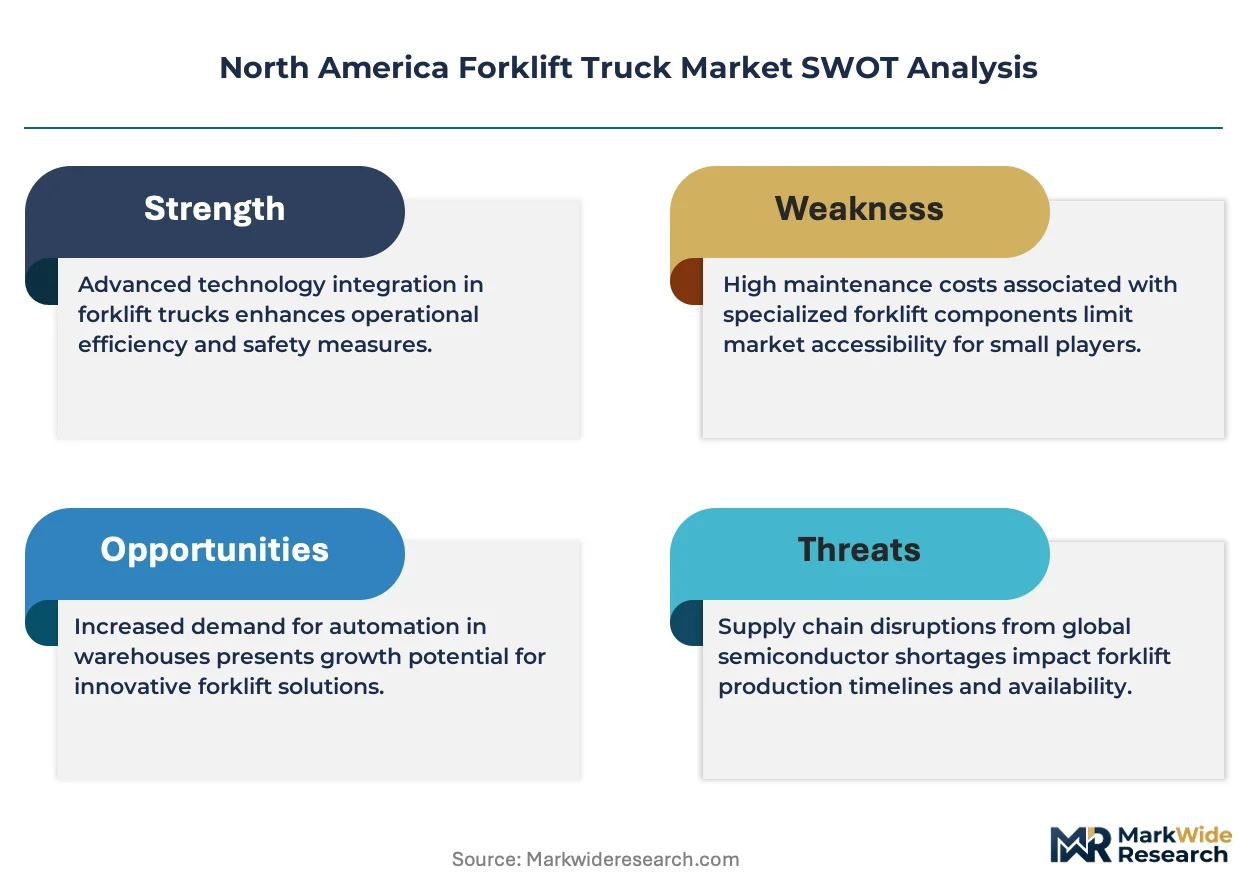
Electrification of the motive powertrain is tilting engineering priorities across the North America Forklift Truck Market. Toyota Material Handling North America leverages its hybrid manufacturing footprint to serve both battery-electric and internal-combustion demand. Crown Equipment Corporation specializes in counterbalance and narrow-aisle designs for high-density warehousing. Hyster-Yale Materials Handling Inc. anchors its competitive stance through dedicated assembly operations in the United States.
A forklift truck is a powered industrial vehicle equipped with hydraulic lifting mechanisms and fork attachments designed to raise, lower, and transport palletized loads, with rated capacities typically spanning 3,000 to 36,000 pounds and lift heights reaching 20 feet or more in standard configurations. Its primary commercial purpose centers on horizontal and vertical material movement within confined storage, production, and distribution environments. Electric product types command structural priority as warehousing end users phase out propane and diesel fleets to satisfy indoor air quality mandates. The e-commerce end user segment represents the fastest-expanding demand pool, while manual technological features still dominate unit volumes despite automation advances in greenfield distribution centers.
OSHA enforces operator certification and workplace safety standards that directly shape fleet procurement timelines and training expenditures. EPA tailpipe emissions regulations constrain diesel and LPG product configurations, particularly in California where CARB rules exceed federal stringency. The Department of Transportation coordinates with FMCSA on weight and dimensional limits affecting transport logistics for forklift delivery. Stakeholders must monitor battery supply chain localization progress and charging infrastructure buildout as electrification commitments harden across major fleet operators.
Market Dynamics
Electrification of motive powertrains is forcing fleet operators across the United States, Canada, and Mexico to restructure capital deployment around battery supply chains and charging infrastructure rather than fuel procurement networks.
Growth Catalysts
- EPA Tier 4 Final emissions standards:These rules compel warehouse operators in California and the Great Lakes corridor to accelerate electric forklift procurement ahead of diesel and LPG phase-out deadlines.
- E-commerce fulfillment densification:Third-party logistics providers operating multi-tenant distribution centers in Illinois and Ohio are expanding narrow-aisle fleet capacity to maximize cubic storage utilization.
- Lithium iron phosphate battery chemistry:Improved thermal stability and cycle life are extending duty cycles for multi-shift operations in refrigerated food distribution.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery pack cost uncertainty compresses margin visibility for fleet operators committing to five-year electrification roadmaps.
- Charging infrastructure lead times:Utility interconnection queues in Ontario and Michigan delay depot electrification projects by twelve to eighteen months.
- Residual value risk for internal combustion assets:Secondary market liquidity for diesel forklifts is thinning as Tier 4 retrofit costs erode trade-in valuations.
Strategic Opportunities
- Fleet-as-a-service subscription models:Equipment finance providers are bundling maintenance, telematics, and energy management for mid-size 3PLs in Texas and Arizona.
- Automated guided forklift convergence:Integration of vision-based navigation with standard counterbalance chassis is opening retrofit pathways for brownfield distribution centers.
- Inflation Reduction Act clean vehicle credits:Section 45W commercial clean vehicle provisions reduce effective acquisition cost for battery-electric units deployed in qualifying facilities.
Industry Challenges
- Industrial electrician skill scarcity:High-voltage battery maintenance certification programs are not scaling to match fleet electrification timelines in the Midwest manufacturing belt.
- Multi-vendor telematics integration:Proprietary data protocols from incumbent OEMs obstruct unified fleet management platforms for heterogeneous equipment bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Forklift Truck Market |
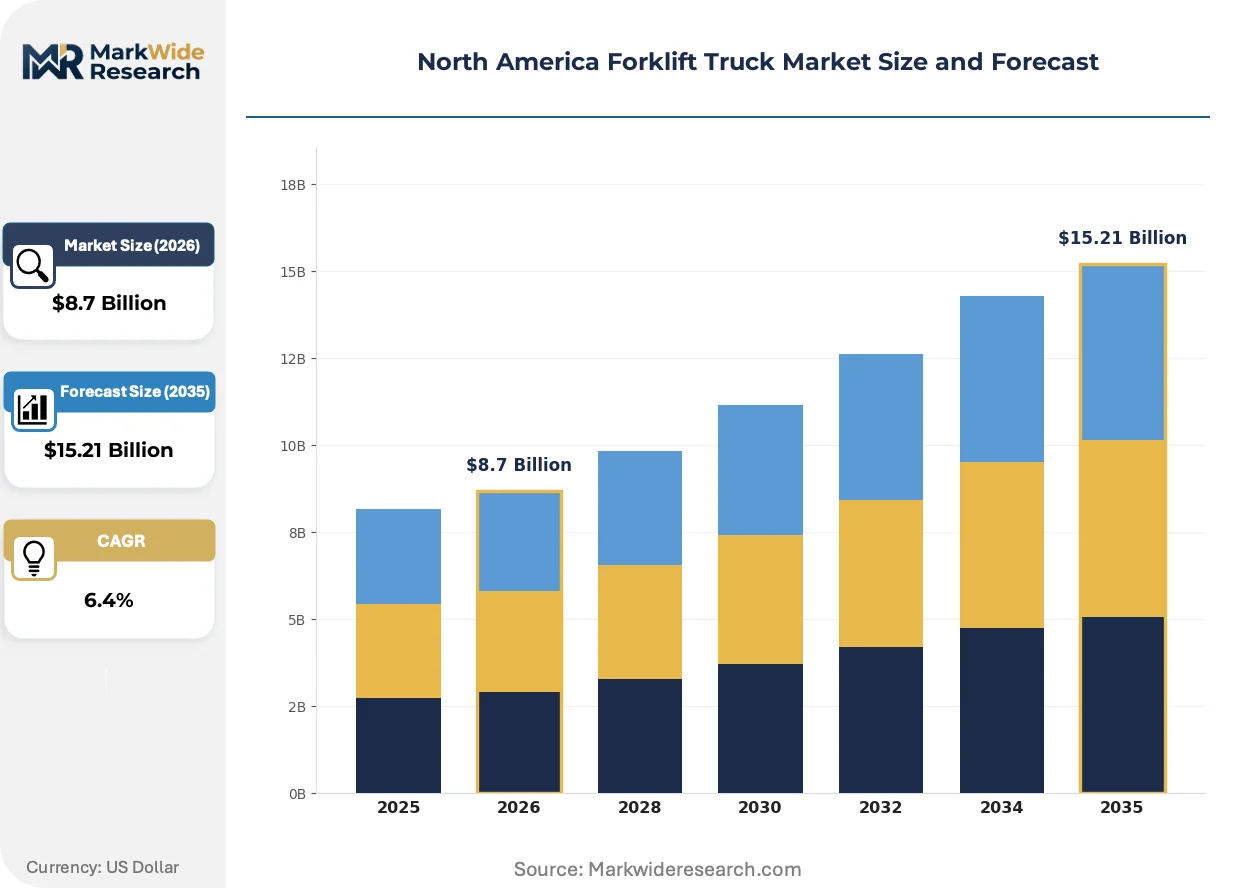
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, LPG, Walkie Stackers Industry Vertical: Manufacturing, Retail, Construction, Warehousing Technological Feature: Automated, Manual, Hybrid, Ergonomic End User: Logistics Providers, Distribution Centers, E-commerce, Food & Beverage |
| Companies Covered | Toyota Material Handling North America, Crown Equipment Corporation, Hyster-Yale Materials Handling Inc., Mitsubishi Logisnext Americas Inc., Doosan Industrial Vehicle America Corp., Komatsu America Corp., Clark Material Handling Company, Jungheinrich AG, Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Forklift Truck Market Evolving Landscape
Three distinct vectors are compressing product lifecycles and reshaping supplier relationships across the North American material handling equipment base.
Lithium-ion battery packs with integrated battery management systems are rendering obsolete traditional lead-acid forklift powertrains that require dedicated watering infrastructure and eight-hour charging cycles. Cold storage operators in Wisconsin and Pennsylvania are completing full fleet conversions within twenty-four-month windows. The elimination of battery rooms is freeing fifteen to twenty percent of warehouse footprint for revenue-generating storage.
OSHA's pending update to 29 CFR 1910.178 operator training standards will mandate recurrent certification intervals and expanded pedestrian awareness protocols. Distribution employers in the United States are budgeting twenty to thirty percent training cost increases over current baselines. The proposed rule is accelerating demand for virtual reality simulation-based training systems that reduce live equipment exposure during certification.
Consolidated procurement through national account structures is displacing decentralized branch-level fleet decisions at multi-site retail and grocery chains. Purchasing authority is migrating to corporate real estate and supply chain functions rather than regional warehouse managers. This concentration is most visible among Canadian grocery cooperatives and US big-box retailers standardizing on single-source OEM relationships across forty-plus facility networks.
North America Forklift Truck Market Segmentation
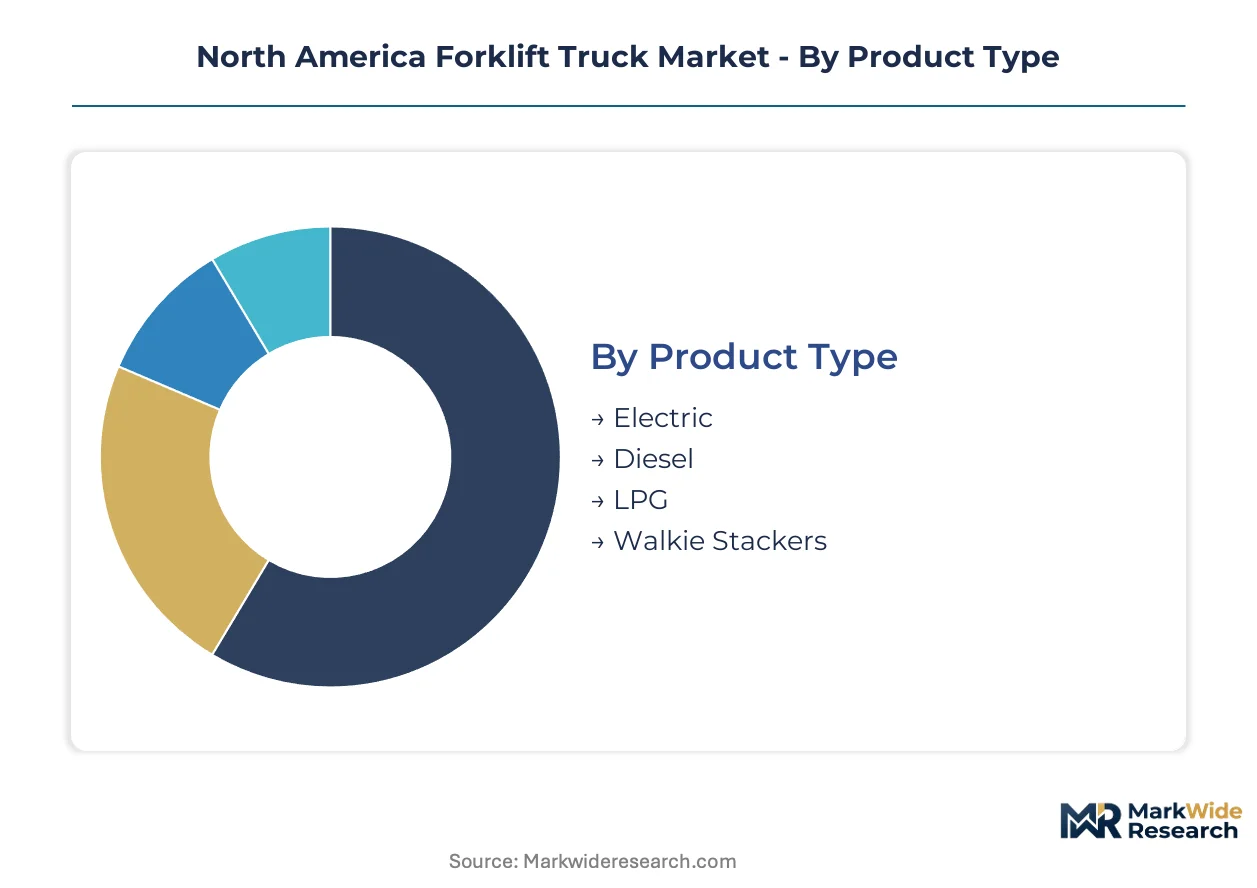
Segmentation reveals how electrification mandates and e-commerce densification are fragmenting procurement priorities across motive power, operational environment, and automation readiness. Fleet operators in the Great Lakes corridor and California are making divergent bets on battery chemistry, aisle configuration, and telematics integration.
Product Type:
Cost tier differentiation separates capital-intensive electric platforms from legacy internal-combustion alternatives with diverging residual value curves.
- Electric:Lithium iron phosphate battery packs with integrated thermal management dominate new procurement in California and Illinois distribution corridors. Cold storage operators in Wisconsin are completing twenty-four-month fleet conversions to eliminate battery room footprint and satisfy CARB indoor air quality mandates.
- Diesel:Tier 4 Final aftertreatment systems have compressed operating margins for construction and outdoor yard applications in Texas and Arizona. Secondary market liquidity is thinning as retrofit costs erode trade-in valuations against electric alternatives.
- LPG:Propane counterbalance units retain niche deployment in mixed indoor-outdoor manufacturing yards across Ohio and Michigan where charging infrastructure interconnection queues delay electrification timelines.
- Walkie Stackers:Pedestrian-operated electric pallet trucks with straddle leg configurations serve narrow-aisle retail backrooms and food service distribution in Pennsylvania.
Electric holds installed capacity. Walkie Stackers are rotating up the share rankings.
Industry Vertical:
Application intensity determines duty cycle specifications and maintenance interval economics across facility types.
- Manufacturing:Heavy-duty counterbalance fleets in Michigan automotive assembly plants operate multi-shift schedules demanding rapid opportunity charging infrastructure.
- Retail:Big-box distribution centers in Texas and Arizona are consolidating procurement authority through national account structures that standardize on single-source OEM relationships.
- Construction:Rough-terrain telehandlers and diesel pneumatic units serve outdoor material yards with exposure to EPA Tier 4 Final compliance costs.
- Warehousing:Third-party logistics providers in Illinois and Ohio are expanding narrow-aisle reach truck capacity to maximize cubic storage utilization in multi-tenant facilities.
Warehousing commands current deployment velocity. Retail is climbing the fastest as e-commerce fulfillment networks densify.
Technological Feature:
Automation maturity separates greenfield distribution centers from brownfield retrofit constraints.
- Automated:Vision-based navigation systems integrated with standard counterbalance chassis are opening retrofit pathways for brownfield distribution centers in Pennsylvania and Wisconsin.
- Manual:Operator-controlled units still dominate unit volumes despite automation advances, particularly in food and beverage distribution where SKU variability obstructs fixed-path guided vehicle deployment.
- Hybrid:Dual-mode systems combining manual override with semi-autonomous pallet transport serve mid-size 3PLs testing automation without full infrastructure commitment.
- Ergonomic:Suspended cab designs and adjustable steering columns reduce operator fatigue in refrigerated food distribution across the Midwest manufacturing belt.
Manual retains volume leadership. Automated is gaining share fastest as labor scarcity intensifies.
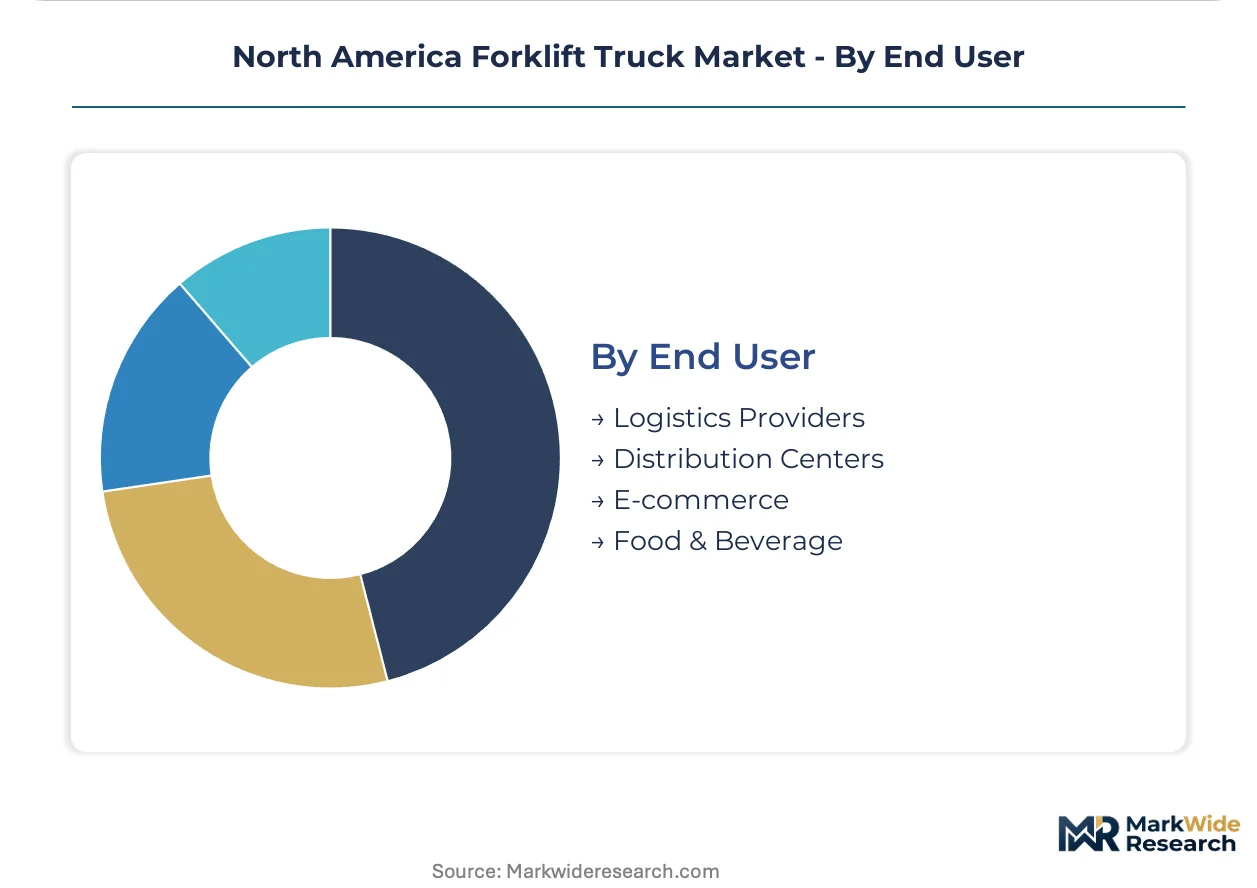
End User:
Customer type dictates fleet financing structures and telematics integration requirements.
- Logistics Providers:Third-party 3PLs operating multi-tenant facilities in Ohio and Texas are adopting fleet-as-a-service subscription models bundling maintenance, telematics, and energy management.
- Distribution Centers:Dedicated retail and grocery networks in Canada and the United States are migrating purchasing authority to corporate real estate functions away from regional warehouse managers.
- E-commerce:Fulfillment networks are expanding narrow-aisle fleet procurement most aggressively in Illinois and California to satisfy same-day delivery velocity requirements.
- Food & Beverage:Cold chain operators in Wisconsin and Pennsylvania prioritize lithium-ion thermal stability for multi-shift refrigerated distribution with extended duty cycles.
Distribution Centers anchor current installed base. E-commerce is expanding most quickly as fulfillment node density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports forklift components and finished units to distribution networks across the southwestern United States, with cross-border logistics corridors intensifying procurement coordination between Tijuana maquiladoras and California fulfillment centers.
United States
E-commerce fulfillment densification and automotive manufacturing resurgence drive fleet replacement cycles. EPA Tier 4 Final emissions standards compel warehouse operators in California and the Great Lakes corridor to accelerate electric procurement ahead of diesel phase-out deadlines. The Chicago-Detroit industrial corridor anchors multi-shift lithium-ion deployments for refrigerated food distribution.
Canada
Cold chain logistics expansion and mining sector equipment renewal sustain counterbalance demand. Health Canada coordinates with provincial occupational safety regulators on indoor air quality mandates affecting propane fleet phase-outs. Ontario's Golden Horseshoe manufacturing belt experiences twelve-to-eighteen-month utility interconnection delays for depot electrification projects.
Mexico
Nearshoring manufacturing relocation and automotive assembly plant expansion create material handling infrastructure demand. The Secretariat of Economy's industrial development programs incentivize warehouse automation adoption in Nuevo León and Baja California. Tijuana maquiladoras serve cross-border fulfillment networks with compressed delivery timelines to California distribution nodes.
North America Forklift Truck Market Competitive Landscape
On the supply side, the industry is consolidated around integrated material handling conglomerates with captive manufacturing footprints across multiple powertrain technologies. Three strategic archetypes dominate: diversified industrial equipment manufacturers with construction and mining heritage, dedicated forklift specialists with narrow-aisle engineering depth, and automotive-aligned groups leveraging electrification scale economies. Competitive moves center on lithium-ion battery supply chain backward integration and fleet-as-a-service financing platform launches.
Within the dedicated specialist tier, Crown Equipment Corporation and Jungheinrich AG exemplify engineering-intensive positioning around narrow-aisle and high-density storage configurations. Toyota Material Handling North America anchors the automotive-aligned archetype, representing scale-driven electrification commitments across hybrid manufacturing architectures. These three occupy positions that reflect divergent bets on battery chemistry standardization and automation convergence timelines.
| Leading Market Players |
|---|
| Toyota Material Handling North America |
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling Inc. |
| Mitsubishi Logisnext Americas Inc. |
| Doosan Industrial Vehicle America Corp. |
| Komatsu America Corp. |
| Clark Material Handling Company |
| Jungheinrich AG |
| Caterpillar Inc. |
| Others |
Value Network & Pricing Analysis
The Chicago-Detroit freight corridor compresses logistics costs for lithium-ion battery pack deliveries from Great Lakes assembly plants, concentrating supplier pricing power among Tier 1 OEMs while forcing mid-tier distributors to absorb fuel surcharge volatility through narrower margins on electric counterbalance units.
Pricing Analysis
The lithium-ion premium over lead-acid legacy powertrains commands a three-tier pricing structure across premium, standard, and economy levels, with thermal management sophistication and UL 2580 certification grade driving price differentiation. Fleet-as-a-service subscription bundling is displacing per-unit transactional sales among third-party logistics providers, compressing upfront hardware margins while expanding recurring service revenue pools. Cost compression in the internal-combustion segment is intensifying because Tier 4 Final aftertreatment retrofit costs erode residual valuations, rendering diesel units most price-sensitive to trade-in arbitrage.
Supply Chain Analysis
Contract manufacturing concentration for battery management systems rests on South Korean and Japanese electronics suppliers with captive foundry capacity, while final forklift assembly anchors in the United States, Mexico, and Canada. Raw material dependencies draw from Chilean lithium carbonate, Indonesian nickel processing, and Chinese cathode active material production. Single-source vulnerability around semiconductor power modules for motor controllers threatens production continuity. Distribution runs through authorized dealer networks with regional parts depots rather than direct OEM fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification roadmaps are expanding the attach rate for energy management software and predictive maintenance subscriptions, with recurring revenue per unit growing faster than hardware replacement cycles across the installed base.
For Market Incumbents: Pre-empt margin erosion in the internal-combustion residual value chain by accelerating captive battery cell sourcing through joint ventures with South Korean chemistry suppliers. Secure exclusive charging infrastructure partnerships with utility providers in Ontario and Michigan to lock in interconnection queue priority. Defend against automated guided vehicle encroachment by embedding vision-navigation modules as standard counterbalance options. For New Entrants and Emerging Players: Build out fleet-as-a-service platforms targeting mid-size food and beverage distributors in Pennsylvania and Wisconsin, where electrification mandates outpace incumbent service capacity. Narrow-aisle retrofit automation for brownfield warehouses represents the most penetrable white space. Lead with telematics-native chassis designs that bypass proprietary OEM data protocol lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lithium-ion battery pack assemblers with UL-certified thermal management and established OEM supply relationships over legacy lead-acid specialists facing stranded asset risk. Long-term viability hinges on backward integration into cathode active material processing. Monitor utility interconnection approval velocity in the Great Lakes corridor as the inflection signal for depot electrification capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium iron phosphate capacity insulates OEMs from cobalt price volatility and CARB compliance deadlines. |
| Fleet-as-a-Service Platform Launch | Subscription bundling of maintenance and energy management locks in multi-year revenue visibility with 3PLs. |
| Automated Guided Forklift Retrofit Kits | Vision-based navigation modules convert manual counterbalance fleets without greenfield infrastructure commitment. |
| Charging Infrastructure Partnership | Utility interconnection priority agreements in Michigan and Ontario accelerate depot electrification timelines. |
| Telematics Data Protocol Standardization | Open APIs for fleet management platforms reduce switching costs for heterogeneous equipment bases. |
Research Methodology
Desk research of SEC 10-K filings, EPA certification databases, and OEM technical documentation preceded structured interviews with fleet maintenance directors, plant engineers at automotive assembly facilities, third-party logistics procurement leads, and aftermarket service heads. Primary fieldwork across the Great Lakes corridor and California distribution networks was validated against customs trade data and utility interconnection queue records. Bottom-up unit deployment estimates were triangulated with top-down capital expenditure projections from national account structures.
Assumptions held fixed include EPA Tier 4 Final enforcement timelines, OSHA operator training standard implementation, and lithium iron phosphate chemistry cost curves; variables stress-tested spanned cobalt carbonate spot prices, utility interconnection approval velocities, and automated guided vehicle penetration rates. Segmentation modeling spanned motive power architecture, aisle configuration, automation readiness, and end-user financing structure across the projection horizon. CAGRs were derived from logistic adoption curves fitted to historical fleet replacement patterns and regulatory phase-out deadlines, with e-commerce fulfillment node density and cold chain expansion serving as volume scaling inputs.
Stress conditions across battery raw material price bands, charging infrastructure deployment delays, and residual value compression for internal-combustion assets were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline regulatory trajectories. Supply chain disruption from semiconductor allocation constraints or trade policy shifts on critical mineral imports could revise deployment timelines. Quarterly review of utility interconnection approval data, battery chemistry spot prices, and OEM order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Saudi Arabia Cat Food Market
Others
Sound Reinforcement Market
Others
Fresh Durian Market
Others
Vacuum Evaporators Market
Others
India Home Automation Market
Others
Global Pregnancy Tracker Apps Market
Others
Mobile Computing Devices Market
Others
Europe Virtual Reality Gaming Market
Others
Air Purification Systems Market
Others
North America Luxury Car Market
Others
3D Printing Construction Market
Others
Africa Cotton Market
Others
Europe Military 4D Printing Market
Others
Military Sensors Software Market
Others
Rope Market
Others
Saudi Arabia Laser Hair Removal Market