
 Land Surveying Equipment Market | 2026-2036
Land Surveying Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Land Surveying Equipment Market Insights
Aftermarket service revenue is tilting toward software subscription and calibration contracts rather than one-time hardware sales. Trimble Inc. leverages its GNSS ecosystem to lock in recurring revenue from fleet management portals. Hexagon AB anchors its position through Leica Geosystems AG with dense service networks spanning major metropolitan calibration hubs. South Surveying & Mapping Instrument Co., Ltd. competes aggressively on domestic replacement cycles within China.
Land surveying equipment comprises electro-optical measurement instruments, satellite positioning receivers, and laser scanning systems engineered to sub-centimeter accuracy for cadastral boundary determination and topographic mapping. Total station systems dominate installed base value due to their versatility across construction staking and control network densification, while 3D laser scanner adoption accelerates fastest in mining volumetrics and heritage documentation where point-cloud density requirements exceed photogrammetric alternatives. GPS/GNSS receivers retain structural importance in agriculture and environmental monitoring applications requiring real-time kinematic correction across wide-area networks.
FAA Part 107 governs commercial unmanned aerial system operations affecting photogrammetry deployment in the United States, while CE marking under EU Radio Equipment Directive shapes product access across European member states. China's GB standards for electromagnetic compatibility and MIIT radio frequency allocations constrain transmitter specifications for domestic GNSS manufacturers. Stakeholders must monitor evolving spectrum reallocation decisions and drone airspace integration rules that will determine which sensor platforms achieve operational scale.
Market Dynamics
The land surveying equipment sector is reconfiguring around the tension between hardware commoditization and software-driven value capture, as precision positioning migrates from instrument sales to subscription-based correction services and fleet analytics portals.
Growth Catalysts
- FAA Part 107 framework:Commercial drone operations under this US regulation have mainstreamed aerial photogrammetry workflows, cutting field data collection time by half for cadastral surveys.
- State-backed infrastructure procurement:China's MIIT radio frequency allocations for GNSS receivers align with massive transportation and utility corridor projects driving instrument replacement cycles.
- Real-time kinematic networks:Wide-area correction infrastructure is extending sub-centimeter accuracy to agriculture and environmental monitoring applications previously served by lower-precision methods.
Market Restraints
- Semiconductor input volatility:GNSS receiver chipsets and laser scanning MEMS components face concentrated fabrication capacity in East Asian foundries, exposing lead times to geopolitical friction.
- Spectrum reallocation uncertainty:FCC and EU decisions on L-band and C-band repurposing threaten to obsolete transmitter specifications in installed base equipment.
- Photogrammetric substitution:Drone-captured imagery processed through structure-from-motion algorithms displaces total station deployments for topographic mapping below 1:500 scale requirements.
Strategic Opportunities
- Heritage documentation applications:3D laser scanning demand from UNESCO site preservation and insurance risk assessment creates premium pricing power for millimeter-accuracy instruments.
- Calibration service networks:Dense metropolitan hub strategies lock in recurring revenue as construction firms outsource instrument maintenance to avoid capital deployment.
- EU Green Deal alignment:Carbon accounting mandates for infrastructure projects require precise volumetric earthwork measurement, expanding scanner deployment in civil engineering.
Industry Challenges
- Geodetic surveyor scarcity:The pipeline of technicians trained in network adjustment and error propagation analysis has not kept pace with instrument sophistication, creating bottlenecks in control survey execution.
- Multi-vendor integration complexity:Field crews struggle to synchronize data formats between legacy total stations, proprietary scanner software, and open-source photogrammetry pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Surveying Equipment Market |
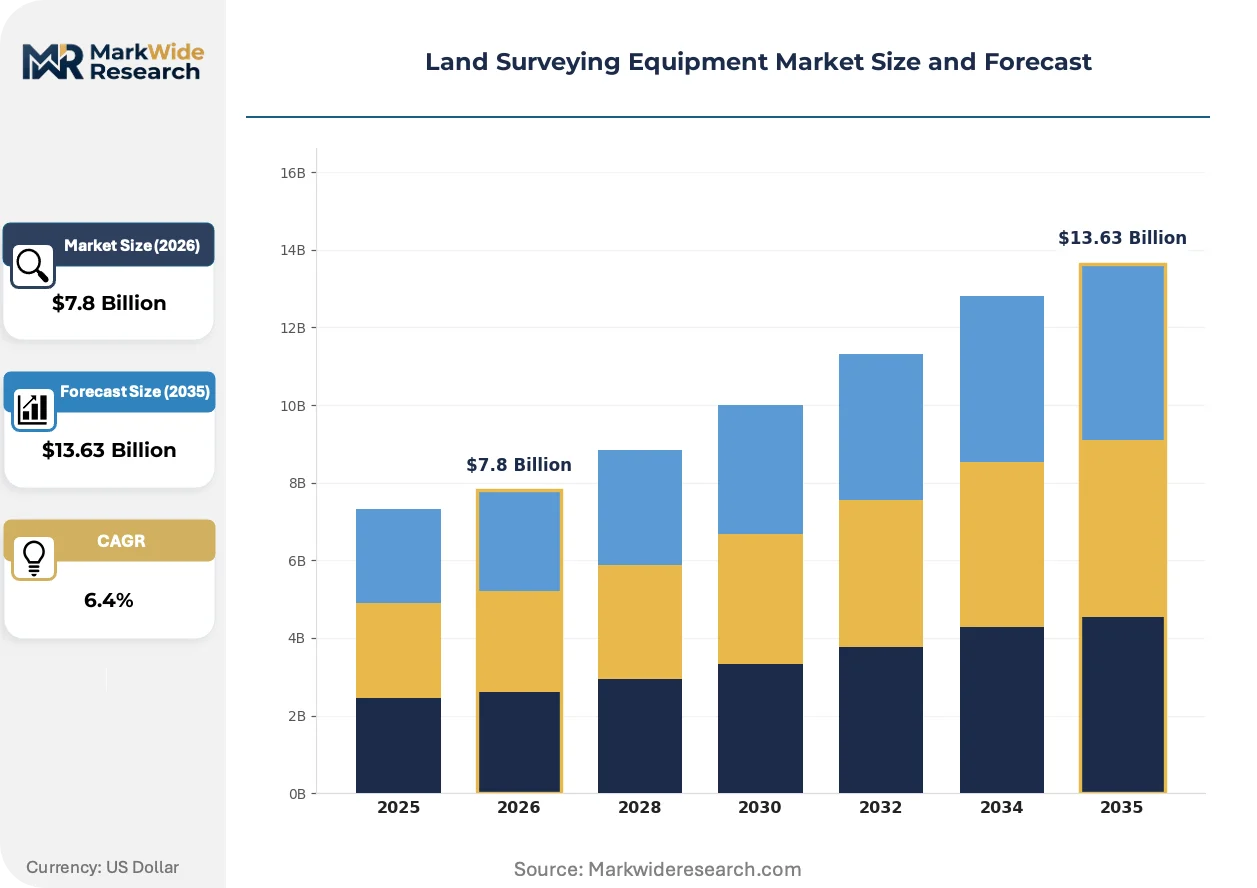
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS, Total Station, Leveling Instrument, 3D Laser Scanner Technology: Digital Imaging, Photogrammetry, Geodetic Technology, Augmented Reality Application: Construction, Mining, Agriculture, Environmental Monitoring End User: Government, Engineering Firms, Surveying Companies, Architects |
| Companies Covered | Trimble Inc., Hexagon AB, Topcon Corporation, Leica Geosystems AG, Sokkia Co., Ltd., South Surveying & Mapping Instrument Co., Ltd., GeoMax AG, FARO Technologies, Inc., CHC Navigation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Surveying Equipment Market Trends and Innovations
Sensor fusion and autonomous data collection are collapsing the distinction between field measurement and office processing, compressing project timelines while elevating software competency requirements for surveying firms.
Multi-sensor platforms combining GNSS receivers, inertial measurement units, and LiDAR scanners into single payloads are hybridizing field workflows. Mining operators and civil engineering contractors are adopting these integrated systems fastest, eliminating separate instrument setups. The technology is hybridizing competitive positioning by privileging vendors with software ecosystems over pure hardware manufacturers.
REACH substance restrictions and RoHS recast directives in Europe are tightening material compliance for electronics-containing instruments. Manufacturers must redesign circuit boards and solder compositions to maintain CE marking access. Total station and scanner product lines destined for EU member states face the steepest reformulation timelines and certification costs.
Equipment buyers are unbundling after-sales service from initial hardware transactions, negotiating calibration and repair contracts separately through third-party metrology laboratories. This disintermediation pressures manufacturer service networks in North American and Western European markets where independent calibration facilities have achieved accreditation density. Construction sector procurement departments are driving this fragmentation to optimize operating expenditure recognition.
Land Surveying Equipment Market Segmentation
Segmentation reveals how surveying technology value pools fragment across precision requirements and procurement authority. Equipment specifications diverge sharply between cadastral boundary work demanding millimeter certainty and agricultural guidance tolerating centimeter variance.
Product Type:
Cost tiers separate instrument categories by calibration complexity and sensor density.
- GPS:Satellite positioning receivers process multi-constellation signals with real-time kinematic correction for sub-centimeter accuracy. Demand concentrates in Midwestern US agriculture where wide-area network infrastructure enables automated steering systems, constrained by FCC spectrum reallocation uncertainty affecting L-band transmission.
- Total Station:Electro-optical measurement systems integrate angle encoders and distance meters for construction staking and control network densification. China MIIT procurement for transportation corridors drives replacement cycles, though semiconductor lead times from East Asian foundries create delivery volatility.
- Leveling Instrument:Optical and digital levels establish vertical datum for drainage engineering and floodplain mapping.
- 3D Laser Scanner:Phase-based and time-of-flight systems capture dense point clouds for heritage documentation and mining volumetrics.
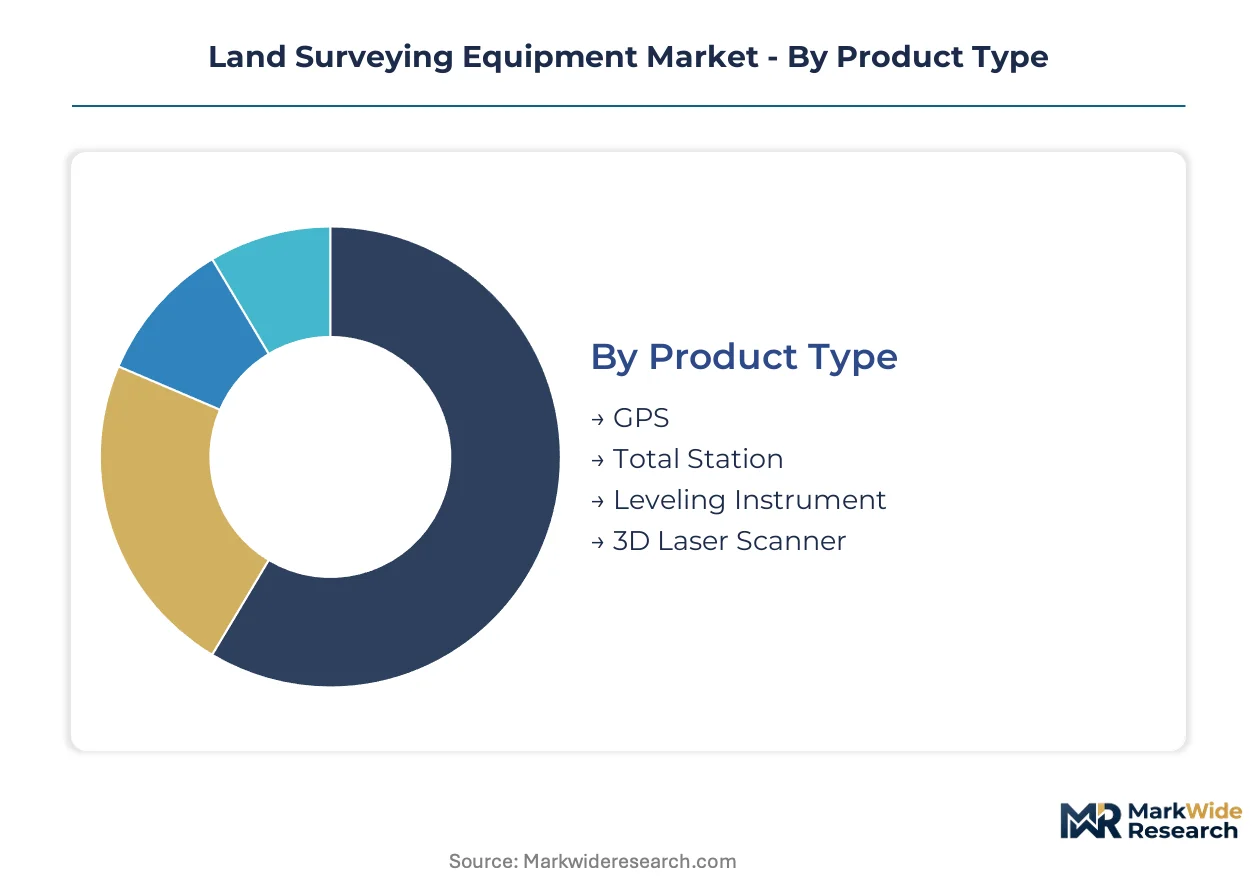
The dominant share belongs to Total Station, while 3D Laser Scanner is closing the gap fastest.
Technology:
Application maturity determines which technologies have crossed from experimental to operational deployment.
- Digital Imaging:High-resolution CMOS sensors and structure-from-motion algorithms process drone-captured imagery into orthomosaics and digital elevation models. FAA Part 107 commercial operations in the United States have mainstreamed aerial photogrammetry, cutting field collection time for cadastral surveys.
- Photogrammetry:Multi-view geometry reconstruction from overlapping images displaces total stations for topographic mapping below 1:500 scale requirements.
- Geodetic Technology:Network adjustment software and error propagation analysis underpin control survey integrity for national spatial reference frameworks.
- Augmented Reality:Heads-up displays overlay design models onto physical terrain for construction layout verification.
Photogrammetry commands the largest deployment base, though Augmented Reality is gaining share fastest in civil engineering applications.
Application:
Customer procurement scale and specification stringency create distinct margin profiles across verticals.
- Construction:Staking, machine control, and as-built documentation require versatile instrument fleets with rapid calibration turnaround. EU Green Deal carbon accounting mandates for infrastructure projects expand scanner deployment for precise earthwork measurement.
- Mining:Volumetric stockpile surveys and pit progression mapping demand explosion-rated equipment with autonomous operation capability.
- Agriculture:Sub-inch guidance for planting and spraying relies on RTK correction subscriptions rather than owned base stations.
- Environmental Monitoring:Coastal erosion tracking and glacial movement measurement utilize permanent GNSS installations with satellite telemetry.
Construction retains the deepest equipment penetration, while Environmental Monitoring is expanding most quickly as climate attribution requirements tighten.
End User:
Procurement authority and technical competency shape vendor engagement models and service attachment rates.
- Government:National mapping agencies and cadastral authorities specify metrological traceability and multi-decade archive compatibility. China's state-backed infrastructure projects drive instrument procurement through centralized tender processes.
- Engineering Firms:Multidisciplinary consultancies integrate surveying with structural and geotechnical design, favoring software ecosystems over hardware brands.
- Surveying Companies:Independent practitioners prioritize instrument portability and battery endurance for single-operator field campaigns.
- Architects:Heritage conservation and renovation projects require millimeter-accuracy documentation for BIM integration.
Engineering Firms represent the largest addressable base, while Government procurement is climbing the fastest on infrastructure stimulus.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment buyers in China show the lowest price elasticity as state procurement absorbs premium instruments, while North American independent surveyors exhibit acute sensitivity to hardware cost amid subscription fatigue for correction services.
United States
Commercial drone operations under FAA Part 107 have compressed cadastral survey timelines by fifty percent, accelerating photogrammetry adoption across Midwest agricultural counties. FCC spectrum reallocation deliberations for L-band transmissions inject uncertainty into RTK network investments. The Dallas-Fort Worth metroplex anchors dense calibration hub networks serving Texas construction corridors.
Germany
EU Green Deal carbon accounting mandates for infrastructure earthworks expand premium scanner deployment among Rhine-Ruhr civil engineering contractors. REACH substance restrictions and RoHS recast directives force circuit board redesigns for CE marking compliance. Stuttgart's precision engineering cluster concentrates metrology laboratory accreditation for cross-border instrument calibration.
China
MIIT radio frequency allocations align with state-backed transportation corridor projects driving aggressive replacement cycles for total station fleets. GB standards for electromagnetic compatibility constrain domestic GNSS transmitter specifications. The Yangtze River Delta manufacturing belt hosts dense instrument production capacity serving centralized government tender processes.
Japan
Heritage documentation demand from UNESCO site preservation creates premium pricing power for millimeter-accuracy laser systems in Kyoto and Nara prefectures. METI industrial standards shape product certification timelines for electronics-containing instruments. The Kansai region's surveying technology distributors maintain specialized service networks for conservation architects.
Australia
Mining volumetrics applications in Western Australia's Pilbara region drive autonomous scanner deployment for pit progression mapping. TGA-equivalent electromagnetic compliance frameworks regulate instrument import specifications. Perth-based equipment lessors have developed explosion-rated fleet pools serving fly-in-fly-out mine survey contracts.
Land Surveying Equipment Market Competitive Landscape
Capability concentration sits with integrated ecosystem providers; scale advantage sits with component-specialized fabricators serving price-sensitive replacement markets. The sector exhibits tiered consolidation where software-anchored platforms capture recurring service revenue while hardware manufacturers compete on procurement cycle timing. Three archetypes dominate: GNSS ecosystem integrators, precision optics specialists, and regional cost-optimized suppliers. Dominant competitive moves include backward integration into correction service networks and geographic expansion through metropolitan calibration hub density.
Within the integrated ecosystem tier, Trimble Inc. and Hexagon AB exemplify platform strategies that bind hardware to subscription revenue streams. South Surveying & Mapping Instrument Co., Ltd. occupies a position among domestic-focused suppliers leveraging proximity to China's state procurement apparatus. These three anchors illustrate how competitive positioning diverges between software-capture models and hardware-volume approaches.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB |
| Topcon Corporation |
| Leica Geosystems AG |
| Sokkia Co., Ltd. |
| South Surveying & Mapping Instrument Co., Ltd. |
| GeoMax AG |
| FARO Technologies, Inc. |
| CHC Navigation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in East Asian MEMS foundries is compressing supplier margins while elevating pricing power for precision optics manufacturers serving heritage documentation contracts. This utilization asymmetry drives divergent strategies: semiconductor-dependent vendors absorb cost volatility through service bundling, while optics specialists extract premiums from calibration-intensive applications.
Pricing Analysis
After-sales service contracts now generate the majority of lifetime value across instrument fleets, with calibration subscriptions and software correction services outpacing hardware depreciation cycles. Three-tier pricing structure across premium, standard, and economy levels separates millimeter-accuracy laser systems from construction-grade total stations and agricultural GNSS receivers. Price differentiation hinges on metrological traceability certification and geographic service network density. Cost compression in mid-tier total stations is intensifying because semiconductor lead time volatility forces vendors to inventory buffer stock. Government procurement offices in China exhibit the lowest price sensitivity, while independent surveying contractors in North American agricultural counties face acute subscription fatigue for RTK correction services.
Supply Chain Analysis
Extended payment terms from Japanese precision optics houses and supply-chain finance facilities from Taiwanese semiconductor distributors are reshaping working capital requirements for instrument assemblers. Manufacturing concentrates in China, Japan, and Germany, with the Yangtze River Delta hosting dense total station production and Stuttgart's precision engineering cluster anchoring metrology component fabrication. Raw material dependencies include rare-earth magnets for servo motors, specialized optical glass for telescope assemblies, and multi-constellation GNSS chipsets. Single-source vulnerability around East Asian MEMS foundries threatens laser scanner delivery schedules. Distribution runs through authorized dealer networks with metropolitan calibration hubs, supplemented by direct procurement for government tender processes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Land surveying equipment sits in early-cycle expansion as FAA Part 107 mainstreaming and China's infrastructure stimulus extend precision positioning into agricultural automation and environmental monitoring applications previously served by lower-accuracy methods.
For Market Incumbents: Harden subscription lock-in through fleet management portals that integrate correction services, calibration scheduling, and data analytics into single-platform contracts. Deepen backward integration into GNSS chipset design to reduce exposure to East Asian foundry lead time volatility. Prioritize certification investment for EU Green Deal carbon accounting compliance, as infrastructure contractors face mandatory volumetric measurement requirements. For New Entrants and Emerging Players: Establish a beachhead in environmental monitoring installations, where climate attribution requirements are driving permanent GNSS telemetry networks with limited incumbent presence. Target heritage documentation services in Japan and European UNESCO sites, where millimeter-accuracy specifications command premium pricing and service attachment rates exceed construction verticals. Pursue a software-first go-to-market angle, white-labeling sensor hardware while capturing recurring revenue through proprietary point-cloud processing pipelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ecosystem providers with captive correction service networks, positioning these archetypes for superior cash flow stability across the analysis window. Acquisition targets should display dense metropolitan calibration hub footprints or proprietary network adjustment software with national spatial reference framework integration. Monitor FCC spectrum reallocation decisions as the critical inflection signal—L-band repurposing would obsolete installed base transmitters and trigger replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Correction Service Network Expansion | Captures recurring revenue from agricultural RTK subscriptions under FCC Part 87 allocations. |
| Metropolitan Calibration Hub Density | Locks in government procurement through ISO 17025 traceability and rapid turnaround guarantees. |
| Multi-Sensor Platform Integration | Eliminates separate instrument setups for mining operators adopting GNSS-LiDAR-IMU hybrid payloads. |
| Heritage Documentation Specialization | Extracts premium pricing from UNESCO site preservation mandates in Kyoto and Nara prefectures. |
| EU Green Deal Compliance Certification | Enables scanner deployment for carbon-accounted earthwork measurement in Rhine-Ruhr infrastructure projects. |
Research Methodology
A spread of perspectives from geodetic surveyors, construction procurement managers, calibration laboratory directors, and agricultural guidance system operators converged on the working assumptions underlying this analysis. Primary interviews with instrument fleet managers and aftermarket service heads were validated against secondary sources including FCC spectrum allocation dockets, MIIT radio frequency filings, EU RoHS recast directive compliance databases, and customs trade records for electro-optical measurement equipment. Bottom-up triangulation across product category shipment data and top-down reconciliation against national infrastructure expenditure statistics ensured cross-verification of market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type precision tiers, technology deployment maturity, application vertical specification stringency, and end-user procurement authority. CAGRs were derived from instrument replacement cycle analysis and correction service subscription growth trajectories. Industry-specific forecast inputs included FAA Part 107 waiver issuance rates and China's state-backed transportation corridor tender award schedules.
Sensitivities concentrate around spectrum reallocation timing, semiconductor fabrication capacity utilization, and geodetic surveyor training pipeline adequacy. Forecasts reflect documented assumptions regarding regulatory stability and infrastructure stimulus continuity. Macroeconomic contraction, accelerated FCC L-band repurposing, or technological substitution by structure-from-motion photogrammetry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Optical Comparator Market
Others
Enterprise Video Content Management Market
Others
Hybrid System Market
Others
Europe Aircraft Lighting Systems Market
Others
Insoluble Sulfur Market
Others
Toy Packaging Market
Others
Video Conferencing Hardware Market
Others
Global Simulation in Healthcare Market
Others
Couscous Market
Others
Global Hardware Acceleration Market
Others
Retail Media Platform Market
Others
Wearable Solar Devices Market
Others
Ceramic Machinery Market
Others
Asia Pacific Foodservice Paper Packaging Market
Others
Africa Cotton Market
Others
Air Separation Module Kit Market