
 Traditional PC Market | 2026-2036
Traditional PC Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional PC Market Insights
Enterprise buyer concentration is consolidating around large-scale fleet refresh contracts. Lenovo Group Limited leverages its ThinkPad commercial lineup to anchor procurement relationships with Fortune 500 accounts. Dell Technologies competes through direct sales channels and configurable workstation portfolios. HP Inc. differentiates via managed print and PC service bundles that extend customer lifetime value.
Traditional PCs encompass microprocessor-based computing devices with x86 or ARM architectures, typically featuring 8 GB to 64 GB of RAM and solid-state or hard disk storage, designed for document processing, data analysis, and software development workflows. The laptop segment sustains the largest revenue pool as hybrid work arrangements persist across knowledge industries. Desktop configurations retain margin strength in engineering and financial services where multi-monitor setups and thermal headroom matter. Chrome OS traction among educational institutions and cost-sensitive business units represents the fastest-growing operating system category.
The US Environmental Protection Agency ENERGY STAR program and the European Union Ecodesign requirements shape minimum efficiency standards for power supplies and idle consumption. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain thermal interface materials and flame-retardant plastics used in chassis manufacturing. China's GB standards and MIIT certification requirements govern product access for locally assembled units. Stakeholders must monitor evolving right-to-repair mandates across multiple jurisdictions and assess how modular component strategies affect warranty cost structures and aftermarket revenue streams.
Market Dynamics
Enterprise fleet refresh cycles are compressing replacement timelines as Windows 11 hardware mandates from Microsoft force hardware obsolescence across corporate installed bases. Procurement officers now face synchronized upgrade obligations that override traditional four-to-five-year depreciation schedules.
Growth Catalysts
- Windows 11 Hardware Mandates:Microsoft's processor and TPM requirements are disqualifying legacy devices from security patch eligibility. Corporate IT departments must replace non-compliant machines to maintain enterprise support agreements.
- Hybrid Work Infrastructure:Knowledge industries require standardized laptop configurations for distributed workforces. Employers are provisioning identical device fleets to simplify remote support and security management.
- Public Sector Modernization:United States federal and state agencies are executing decade-overdue desktop and laptop refresh programs. Congressional appropriations for civilian agency IT modernization are channeling directly into PC procurement.
Market Restraints
- Semiconductor Supply Concentration:Advanced node microprocessors depend on TSMC's Taiwan fabrication capacity. Geopolitical tension across the Taiwan Strait creates inventory risk for x86 and ARM-based system vendors.
- Memory Price Volatility:DRAM contract pricing fluctuates with smartphone and server demand cycles. PC OEMs face margin compression when memory costs spike during their locked-in enterprise pricing commitments.
- Chrome OS Substitution:Google's browser-based operating system captures educational and light productivity workloads. Cost-sensitive institutions are bypassing Windows licensing entirely for cloud-native alternatives.
Strategic Opportunities
- Right-to-Repair Legislation:European Union and several United States state-level repair mandates are creating aftermarket service revenue pools. Modular component designs allow manufacturers to capture replacement part margins previously lost to third-party repair shops.
- AI-Accelerated Workstation Demand:Neural processing unit integration is creating a new performance tier between standard laptops and discrete GPU workstations. Creative and data science verticals require on-device inference capability for latency-sensitive applications.
- Device-as-a-Service Expansion:Subscription-based PC provisioning is displacing capital expenditure models in mid-market enterprises. HP and Dell service bundles demonstrate attach rate potential for managed support contracts.
Industry Challenges
- Firmware Security Certification:Secured-core PC requirements demand extensive validation cycles for UEFI and TPM implementations. Engineering teams face compressed timelines to certify new platforms against evolving threat models.
- Legacy Port Support:Enterprise customers demand USB-A, HDMI, and Ethernet connectivity despite industry transition to USB-C and Thunderbolt. Product managers must balance chassis thinness against backward compatibility requirements.
- Thermal Interface Material Compliance:EU REACH restrictions on fluorinated compounds are forcing reformulation of heat dissipation solutions. Validation of alternative thermal pastes and phase-change materials extends new product introduction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional PC Market |
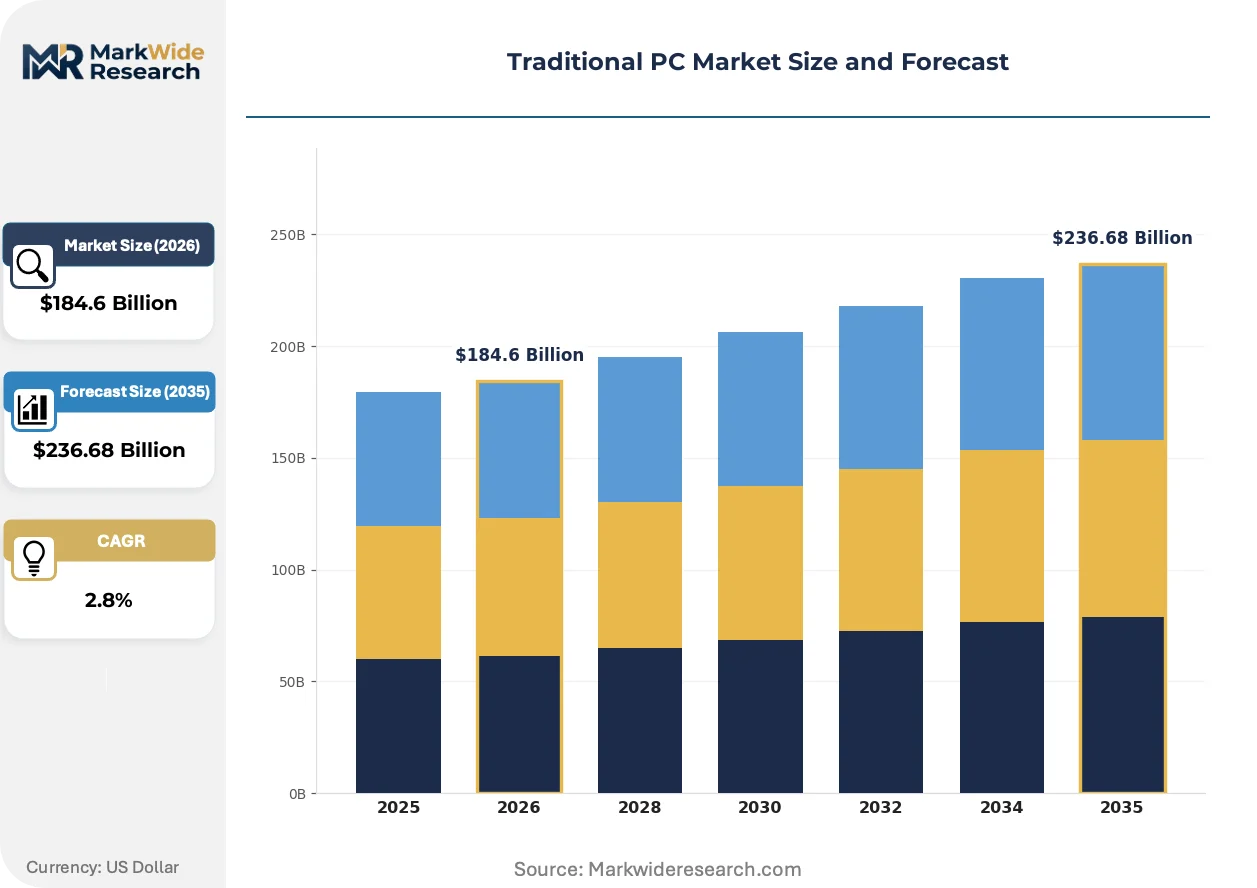
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $236.68 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop, Laptop, All-in-One, Mini PC End User: Consumer, Business, Educational Institution, Government Operating System: Windows, macOS, Linux, Chrome OS Form Factor: Tower, Compact, Convertible, Ultrabook |
| Companies Covered | Lenovo Group Limited, HP Inc., Dell Technologies, Apple, Asus, Acer, Micro-Star International, Huawei Technologies, Advanced Micro Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional PC Market Trends and Innovations
Hardware architecture is fragmenting across performance tiers as on-device AI inference becomes a standard requirement. Vendors are rebalancing silicon allocation between CPU, GPU, and NPU blocks to match workload-specific demand patterns.
Modular motherboard designs are modularizing across the commercial laptop segment. Dell's Latitude and Lenovo's ThinkPad engineering teams are adopting standardized daughterboard layouts for storage, wireless, and I/O subsystems. Corporate buyers are extending fleet lifecycles through field-replaceable component upgrades rather than full device replacement.
EU Ecodesign requirements are tightening idle power consumption limits for desktop and laptop systems. Manufacturers must redesign power delivery subsystems and implement aggressive sleep-state transitions. Enterprise SKUs face certification delays as engineering teams validate compliance across multiple thermal and workload scenarios.
Fleet management software is consolidating procurement authority within IT asset management platforms. Large employers are bypassing traditional reseller channels to negotiate direct volume agreements with OEMs. United States federal contracting vehicles and Fortune 500 reverse auctions are compressing distributor margins while accelerating price transparency.
Traditional PC Market Segmentation
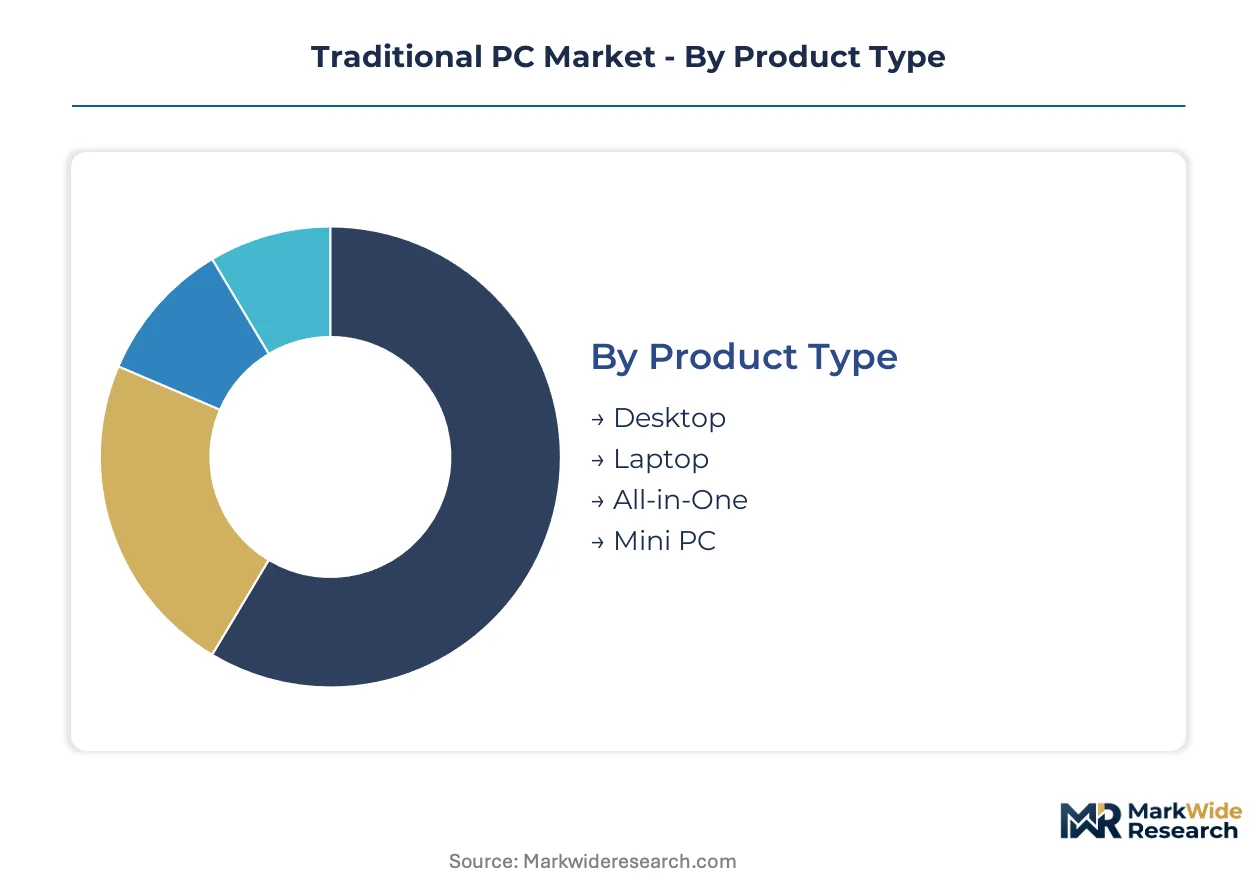
PC manufacturers configure supply chains and inventory buffers around distinct performance tiers and customer workflows. Segment-level demand patterns determine silicon allocation priorities and regional factory loading.
Product Type:
Supply concentration in laptop motherboard and display panel manufacturing tilts procurement leverage toward portable form factors.
- Laptop:Clamshell and notebook configurations dominate enterprise fleet procurement with standardized 14-inch and 15.6-inch display supply. Corporate IT departments in the United States negotiate volume agreements for hybrid work deployments. Windows 11 hardware mandates accelerate replacement cycles for aging mobile workstations.
- Desktop:Tower and small-form-factor chassis retain thermal headroom for engineering simulation and financial modeling workloads. Engineering and data science teams require multi-monitor support and discrete GPU expansion slots. Dell Technologies and HP Inc. maintain dedicated workstation assembly lines for North American corporate accounts.
- All-in-One:Integrated display-compute units serve reception desks and clinical workstations where space constraints override upgrade flexibility.
- Mini PC:Compact NUC-style enclosures target digital signage and edge computing deployments with minimal footprint requirements.
Today's leader: Laptop. Tomorrow's challenger: Desktop.
End User:
Customer procurement scale determines service bundle attach rates and direct sales channel investment.
- Business:Fortune 500 accounts negotiate three-year Device-as-a-Service contracts bundling hardware, support, and asset management. Procurement officers prioritize standardized configurations for remote workforce provisioning. Managed service attach rates climb fastest in this segment.
- Government:Federal and state agencies execute refresh programs through certified contracting vehicles with domestic assembly requirements. United States civilian agencies channel congressional IT modernization appropriations into PC procurement. EPA ENERGY STAR certification is mandatory for federal acquisitions.
- Educational Institution:K-12 districts and universities prioritize total cost of ownership over performance specifications. Chrome OS deployments bypass Windows licensing entirely for cloud-native classroom management.
- Consumer:Retail channel demand concentrates around back-to-school and holiday purchasing windows with thin margin profiles.
Business commands volume. Government delivers margin stability.
Operating System:
Platform licensing economics shape OEM profitability and end-user total cost of ownership calculations.
- Windows:Microsoft's enterprise licensing agreements dominate corporate installed bases with Active Directory and Endpoint Manager integration. IT departments face synchronized upgrade obligations as hardware mandates disqualify legacy devices from security patch eligibility. Enterprise Agreement volume commitments lock in multi-year revenue streams.
- Chrome OS:Google's browser-based platform captures educational procurement with zero-touch enrollment and cloud policy management. Cost-sensitive institutions in the United States bypass traditional Windows licensing for lightweight productivity workloads.
- macOS:Apple's vertical integration limits enterprise penetration to creative and software development verticals.
- Linux:Open-source distributions serve developer workstations and specialized scientific computing environments with minimal OEM support overhead.
Windows holds enterprise lock-in. Chrome OS climbs fastest in education.
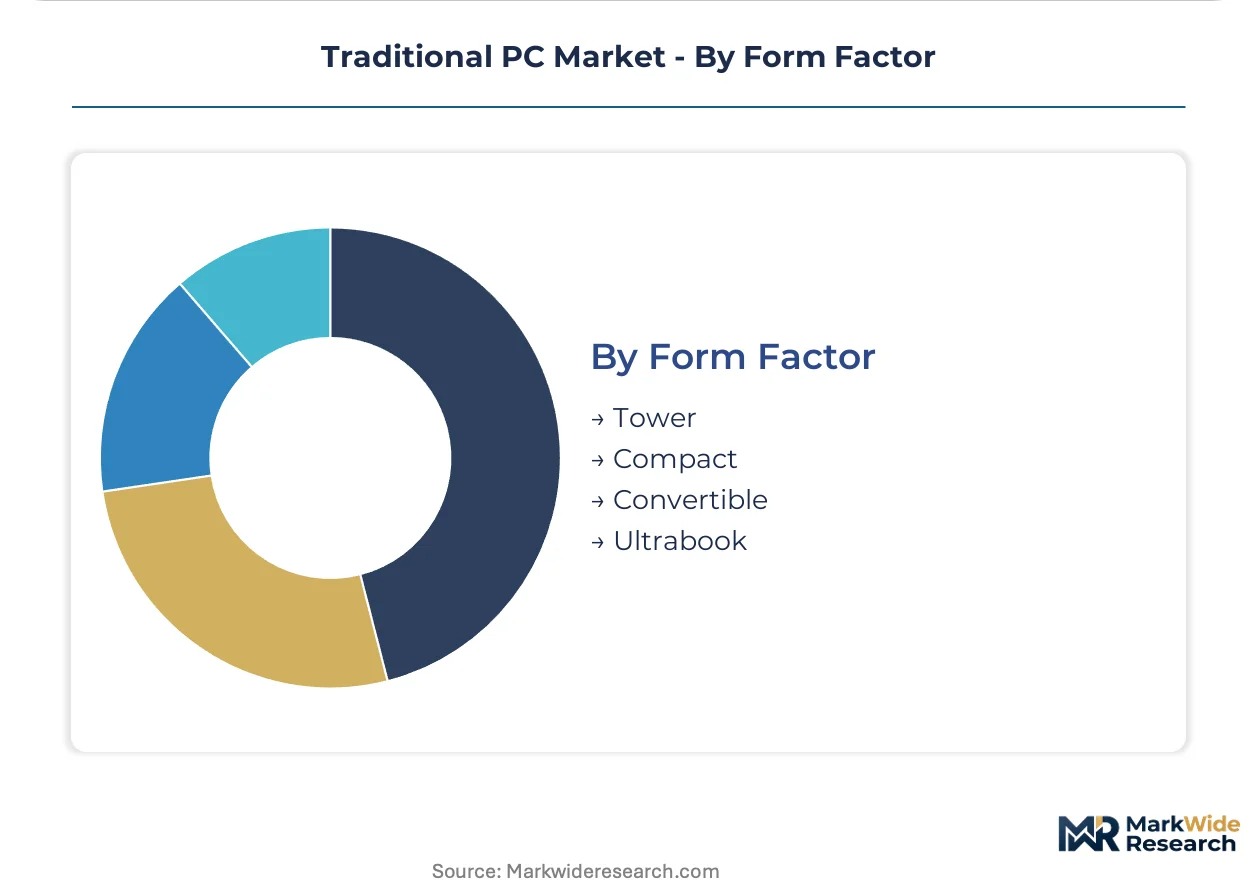
Form Factor:
Thermal design power budgets and chassis engineering costs stratify pricing tiers across mobility-versus-performance tradeoffs.
- Ultrabook:Thin-and-light designs under 1.5 kg prioritize battery endurance and airport security compliance for executive travel. Intel Evo and AMD Ryzen Pro platforms compete for premium corporate procurement with vPro and PRO manageability features. United States consulting firms standardize on identical ultrabook fleets for client-facing staff.
- Convertible:360-degree hinge mechanisms enable tablet mode for field inspection and clinical documentation workflows. Healthcare and construction verticals drive demand for stylus-enabled ruggedized configurations.
- Tower:Full-size desktop enclosures accommodate dual-GPU configurations for AI training and CAD visualization.
- Compact:Small-form-factor designs fit under-monitor deployment for trading floors and call centers.
Ultrabook defines premium mobility. Convertible expands use-case coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT talent clusters in the United States, Germany, and China anchor procurement decision-making for fleet refresh cycles. These concentrations drive divergent regulatory compliance requirements and supply chain configurations across major PC consumption centers.
United States
Federal civilian agencies and Fortune 500 corporations synchronize replacement timelines around Windows 11 hardware mandates. The EPA ENERGY STAR program certifies minimum efficiency standards for government acquisitions. Austin and Seattle tech corridors host major OEM sales engineering teams negotiating direct enterprise contracts.
China
Domestic assembly capacity serves both local enterprise demand and export manufacturing for global brands. MIIT certification requirements and GB standards govern product access for locally produced units. Shenzhen and Dongguan manufacturing clusters concentrate motherboard and display panel supply chains.
Germany
Industrial automation and automotive engineering sectors sustain workstation demand for simulation workloads. The EU Ecodesign Directive and REACH chemical restrictions constrain thermal interface materials and chassis plastics. Munich and Stuttgart engineering hubs drive premium configuration procurement.
Japan
Corporate keiretsu procurement maintains conservative refresh cycles with emphasis on domestic vendor relationships. METI efficiency standards and JIS certification requirements shape product specifications. Tokyo and Osaka metropolitan areas concentrate financial services and precision manufacturing IT demand.
India
IT services and business process outsourcing sectors expand laptop deployment for remote delivery teams. BIS certification and phased manufacturing program incentives promote local assembly capacity. Bengaluru and Hyderabad technology corridors drive enterprise fleet standardization.
Traditional PC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing bands. The vendor base stratifies between global scale operators with integrated supply chains and regional assemblers serving cost-sensitive segments. Three archetypes dominate: full-stack OEMs controlling design and distribution, component suppliers extending into systems, and contract manufacturers capturing public sector tenders. Competitive dynamics center on direct enterprise sales channel investment and modular service bundle attach rates.
Within the full-stack OEM tier, Lenovo Group Limited, HP Inc., and Dell Technologies exemplify divergent route-to-market strategies. Lenovo's ThinkPad lineage anchors commercial procurement relationships through direct sales engineering. HP bundles managed print and PC services to extend customer lifetime value. Dell leverages configurable workstation portfolios and reverse auction participation for Fortune 500 accounts. Each represents a distinct wager on enterprise buyer consolidation.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| HP Inc. |
| Dell Technologies |
| Apple |
| Asus |
| Acer |
| Micro-Star International |
| Huawei Technologies |
| Advanced Micro Devices |
| Others |
Pricing and Supply Chain Analysis
EPA ENERGY STAR certification gates qualified supply for federal procurement channels and anchors premium-tier pricing access for enterprise fleet contracts. OEMs without certified power delivery subsystems forfeit United States government revenue pools regardless of unit cost competitiveness.
Pricing Analysis
Device-as-a-Service bundles versus transactional hardware sales split the pricing architecture. Three-tier pricing structure across premium workstation, standard corporate, and economy education levels reflects NPU integration depth and managed service attach rates. Cost compression in economy tiers intensifies because Chrome OS substitutes bypass Windows licensing fees entirely. Educational institutions exhibit highest price sensitivity while Fortune 500 accounts absorb premium pricing for standardized fleet configurations.
Supply Chain Analysis
Ocean freight rate volatility from Asia to North America directly impacts landed cost calculations for motherboard and display panel imports. Advanced node microprocessors draw from Taiwan, South Korea, and United States fabrication capacity. DRAM and NAND flash memory, lithium-ion battery cells, and rare-earth magnet motors constitute critical input dependencies. Single-source vulnerability concentrates at TSMC's Taiwan facilities for x86 and ARM-based system-on-chip production. Distribution runs through direct enterprise sales channels, authorized distributors, and federal contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Assembly cost arbitrage between China and Vietnam creates margin expansion opportunities for OEMs navigating divergent tariff exposure and labor rate differentials.
For Market Incumbents: Deploy modular component architectures to capture aftermarket service revenue pools emerging from right-to-repair mandates. Lenovo, HP, and Dell must accelerate field-replaceable storage and wireless daughterboard designs before third-party repair shops capture replacement part margins. Certification investment in Secured-core PC validation cycles defends enterprise procurement relationships against firmware security threats. For New Entrants and Emerging Players: Begin with Chrome OS-based education deployments in cost-sensitive United States school districts where Windows licensing avoidance drives purchasing decisions. White-space exists in AI-accelerated workstation segments for creative verticals requiring on-device inference. Direct-to-institution channel strategies bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional Device-as-a-Service providers because enterprise buyer consolidation favors managed service bundling over pure hardware transactions. Long-term viability centers on recurring revenue attach rates rather than unit shipment volumes. Monitor NPU integration penetration rates across commercial laptop SKUs as inflection indicator for AI workstation demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Component Architecture | Enables field-upgradeable fleets that extend replacement cycles and capture service revenue. |
| Secured-Core PC Certification | Federal procurement mandates from United States civilian agencies require UEFI and TPM validation. |
| Device-as-a-Service Expansion | Subscription models displace capital expenditure approaches in mid-market enterprise accounts. |
| NPU Integration Investment | Neural processing units create performance tier between standard laptops and discrete GPU workstations. |
| Right-to-Repair Compliance | European Union and state-level mandates generate aftermarket part revenue previously lost to third parties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged PC OEM product managers, enterprise IT procurement officers, federal contracting specialists, and semiconductor supply chain directors. Secondary validation drew from SEC 10-K filings, EPA ENERGY STAR certified product databases, United States federal procurement records, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down enterprise IT spending forecasts.
Segment-weighting approaches assigned differential growth coefficients across laptop, desktop, and workstation form factors. The analytical framework modeled operating system splits, end-user verticals, and performance tier migrations across the projection horizon. CAGRs derived from historical replacement cycle compression patterns and Windows 11 hardware mandate enforcement timelines. Forecast inputs incorporated TSMC capacity allocation disclosures and DRAM contract pricing indices.
Several conditions sit outside the modeled scope, including geopolitical disruption of Taiwan Strait supply corridors and unilateral extension of Windows 10 security patch eligibility. Forecasts reflect documented assumptions about enterprise refresh synchronization and Chrome OS education penetration ceilings. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mine Rescue Vehicle Market
Others
Liposomes Market
Others
Gas Radiators Market
Others
Industrial Gauges Market
Others
Rotary Union Market
Others
Middle East Smart Home Market
Others
GCC Cigarette Market
Others
Global Cigarette Packaging Market
Others
Three Proofing Rugged Tablet Market
Others
Aboveground Storage Tanks Market
Others
Propanil Market
Others
Food Technology Market
Others
Medium-Voltage Switchgear Market
Others
UK Cat Food Market
Others
Programmatic Display Market
Others
Workbench Tanks Market