
 Mini Personal Computer Market | 2026-2036
Mini Personal Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Personal Computer Market Insights
The mini personal computer market is pivoting on a widening gap between premium NUCs with discrete GPUs and commodity stick PCs with barebones processors. Apple, Inc. leverages its M-series silicon to dominate the premium compact workstation tier with unified memory architecture. Dell Technologies, Inc. anchors enterprise procurement through direct channel control and configurable micro tower lines. HP, Inc. competes aggressively in education verticals with Chrome OS micro devices that undercut Windows equivalents on institutional tenders.
A mini personal computer integrates a complete x86 or ARM-based computing system into a chassis typically under two liters in volume, drawing between 15W and 150W depending on thermal design power and cooling configuration. These devices serve space-constrained commercial environments, digital signage backbones, and home office setups where full tower footprints prove impractical. NUCs lead product type margins due to Intel and AMD reference designs that simplify OEM customization, while stick PCs face structural pressure from ARM-based smart displays that absorb their core use case. Windows operating system variants retain volume dominance in corporate fleets, though Linux distributions gain ground among developer-focused professionals seeking kernel-level hardware control without licensing overhead.
The EPA ENERGY STAR program and EU Ecodesign for Sustainable Products Regulation constrain idle power draw and standby consumption, forcing redesigns of power delivery subsystems in compact chassis with limited thermal headroom. FCC Part 15 emissions compliance adds certification cost layers for Wi-Fi 6E and Bluetooth 5.3 implementations that pack radios tightly against CPU and storage. Stakeholders must monitor how USB-C Power Delivery standard revisions and emerging gallium nitride adapter architectures reshape BOM structures and regional sourcing requirements for compact power supplies.
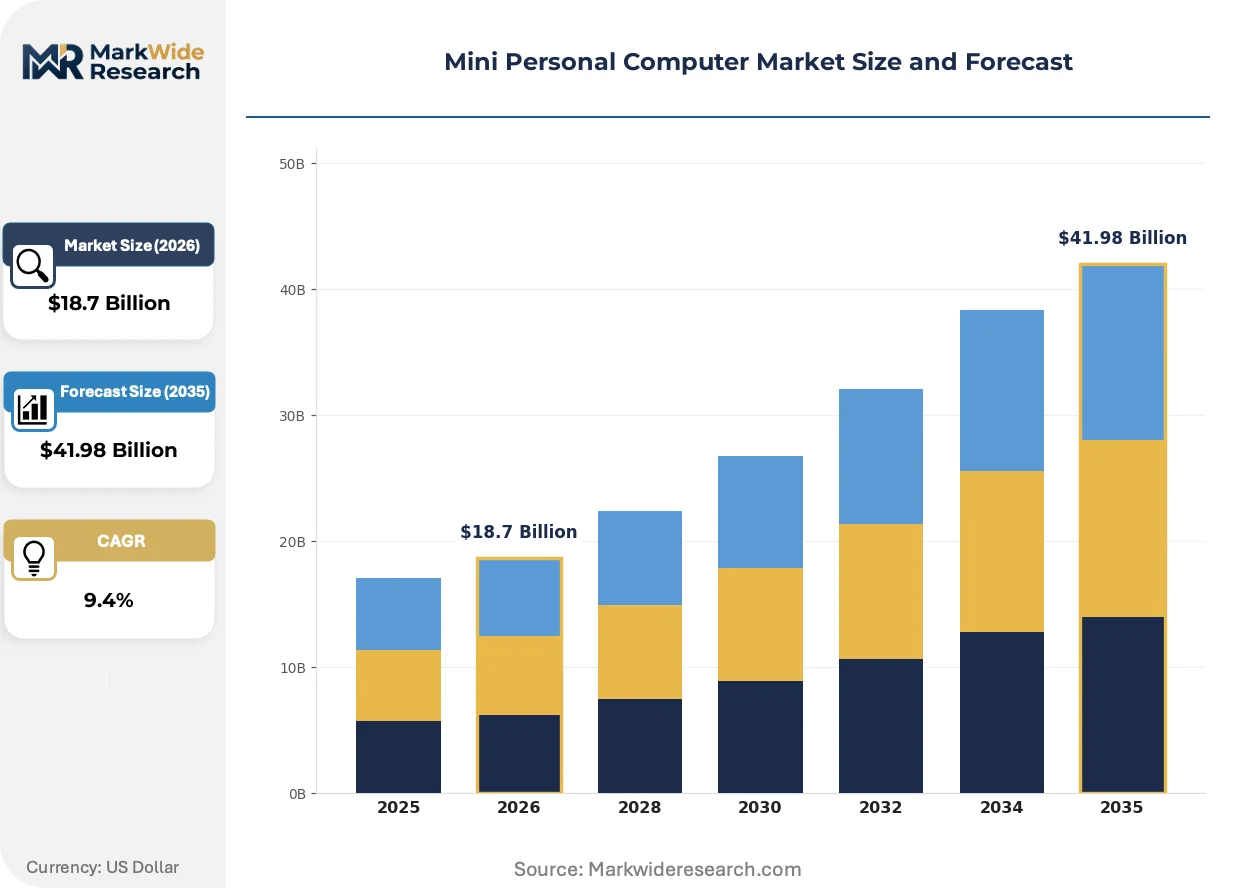
Market Dynamics
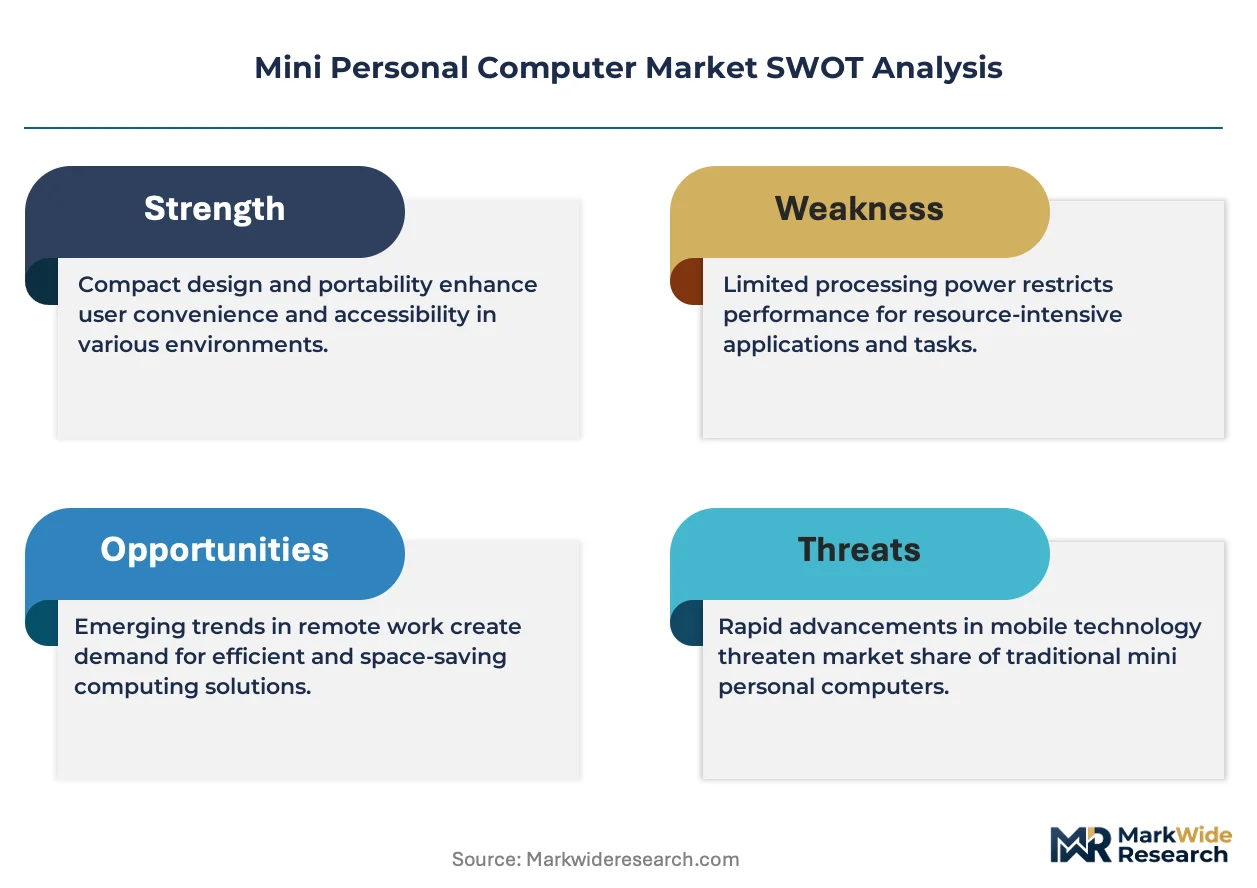
Enterprise IT refresh cycles are compressing from five-year to three-year intervals, pulling compact workstations into procurement pipelines faster than thermal engineering can optimize chassis designs for sustained load profiles.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Tightening energy efficiency thresholds for small-form-factor devices are forcing OEMs to redesign power delivery subsystems, creating upgrade demand across corporate fleets.
- Remote work infrastructure:Persistent distributed workforce requirements in the United States continue to drive NUC and micro tower procurement for home office standardization.
- Digital signage backbone expansion:Retail and hospitality verticals are deploying ARM-based compact compute nodes to replace aging media players, absorbing volume from declining stick PC segments.
Market Restraints
- Input cost volatility:Gallium nitride adapter architectures and USB-C Power Delivery component shortages are inflating BOM structures for compact power supplies sourced from concentrated Asian foundries.
- Thermal headroom limitation:Chassis volumes under two liters cannot dissipate heat from discrete GPUs without active cooling solutions that add cost and acoustic penalty.
- Substitution threat from smart displays:ARM-based integrated screens with embedded compute are absorbing core stick PC use cases in kiosk and signage applications.
Strategic Opportunities
- Underpenetrated education vertical in India:Institutional tenders for Chrome OS micro devices remain below saturation, offering white space for vendors with localized supply chains.
- Regulatory tailwind from EPA ENERGY STAR:Stricter idle power draw mandates are creating competitive differentiation for OEMs with optimized power delivery subsystems.
- Technology convergence of Wi-Fi 6E and Bluetooth 5.3:Tightly packed radio implementations are enabling cable-free docking configurations that displace traditional port expansion.
Industry Challenges
- Certification timeline compression:FCC Part 15 emissions compliance for tightly packed radios against CPU and storage is extending product launch windows by 8-12 weeks.
- Skill gap in kernel-level hardware control:Enterprise IT departments lack Linux administration depth to support developer-focused professionals seeking unlicensed operating system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Personal Computer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One, Stick PCs, NUCs, Micro Towers Target Audience: Home Users, Gamers, Students, Professionals Connectivity: Wi-Fi, Bluetooth, Ethernet, USB-C Operating System: Windows, Linux, macOS, Chrome OS |
| Companies Covered | Apple, Inc., Dell Technologies, Inc., HP, Inc., Lenovo Group Limited, Acer, Inc., ASUSTeK Computer Inc., GIGA-BYTE Technology Co., Ltd., ASRock Inc., Zotac Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Personal Computer Market Trends and Innovations
Active cooling architectures and unified memory designs are rewriting performance-per-watt benchmarks, while regulatory pressure on standby consumption is forcing power subsystem reinvention.
ARM-based system-on-chip designs with integrated neural processing units are converging with x86 NUC reference platforms at the mid-tier performance band. Industrial automation buyers are piloting these hybrid configurations for edge inference workloads. The convergence is compressing margin differentiation between premium and standard product tiers.
The EU Ecodesign for Sustainable Products Regulation is mandating measurable carbon footprint disclosure across component sourcing. OEMs must now document embodied emissions from PCB fabrication through final assembly. Compact workstation lines with localized European manufacturing footprints are capturing preferential placement in public sector tenders.
Enterprise buyers are unbundling after-sales service from hardware procurement, negotiating direct support contracts with third-party IT service providers. Channel partners in the United States are responding with subscription-based remote management offerings. This pattern is most visible in financial services verticals with stringent uptime requirements and existing managed service relationships.
Mini Personal Computer Market Segmentation
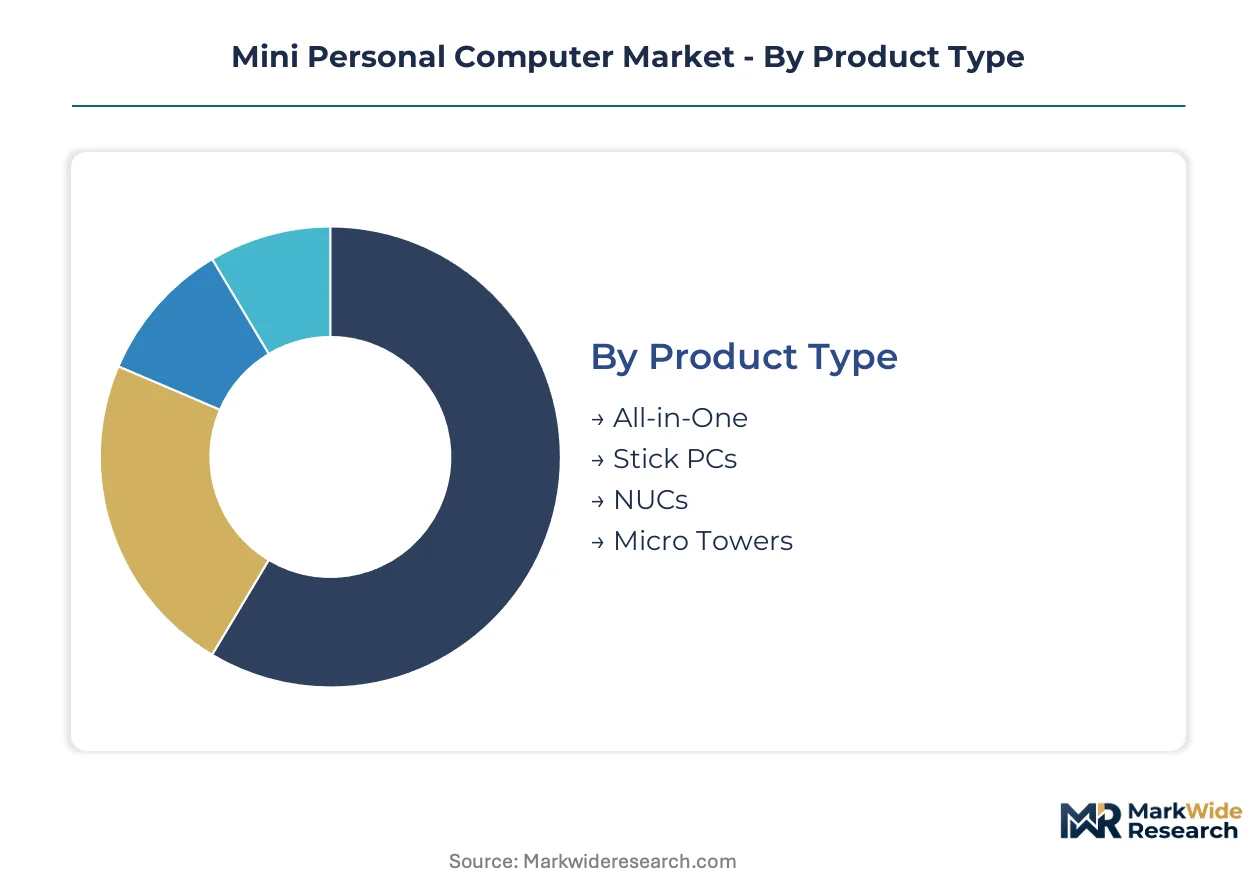
Mini personal computer segmentation reflects divergent thermal constraints and integration depth across use cases. Product architecture choices determine whether devices serve as standalone workstations or embedded compute nodes within larger systems.
Product Type:
Integration depth separates standalone desktop replacements from embedded signage controllers and portable compute sticks.
- NUCs:Modular x86 reference designs from Intel and AMD pack full desktop performance into sub-liter chassis with standardized mounting. Enterprise procurement in the United States favors these units for under-desk deployment in standardized remote work setups.
- Micro Towers:Slightly larger enclosures accommodate discrete GPUs and expansion slots while retaining sub-two-liter footprints. Thermal engineering challenges limit sustained load performance, constraining adoption to business applications without intensive graphics requirements.
- All-in-One:Display-integrated systems eliminate cable clutter for reception desks and point-of-sale terminals.
- Stick PCs:HDMI-dongle form factors face displacement from ARM-based smart displays absorbing digital signage workloads.
Volume placements concentrate in NUCs; the faster expansion belongs to Micro Towers as discrete GPU thermal solutions mature.
Target Audience:
Cost tier alignment shapes whether manufacturers prioritize BOM efficiency or performance-per-watt optimization.
- Professionals:Knowledge workers driving remote infrastructure standardization demand vPro management capabilities and dual 4K output support. Corporate fleet procurement prioritizes three-year refresh cycles with direct channel pricing.
- Students:Education vertical tenders favor Chrome OS micro devices for institutional manageability and sub-$300 price points. HP anchors this segment through district-level volume agreements.
- Home Users:Space-constrained residential buyers seek media center capabilities without tower footprints.
- Gamers:Thermal limitations in compact chassis restrict discrete GPU options, pushing enthusiast demand toward full-size builds.
Enterprise procurement dominates volume; the steepest expansion trajectory sits with Students as India's institutional digitization accelerates.
Connectivity:
Radio density and port configuration determine cable-free deployment feasibility in cluttered environments.
- USB-C:Power Delivery and DisplayPort alt-mode convergence enables single-cable docking for mobile professionals. Gallium nitride adapter architectures are reshaping BOM structures as wattage ratings climb.
- Wi-Fi:Wi-Fi 6E implementations face FCC Part 15 certification delays from tightly packed antenna configurations against CPU thermal shields.
- Bluetooth:Peripheral pairing simplification drives adoption in healthcare and retail verticals.
- Ethernet:Wired reliability requirements persist in financial services and industrial automation deployments.
Corporate standardization favors USB-C; Wi-Fi 6E adoption climbs fastest where cable infrastructure is impractical.
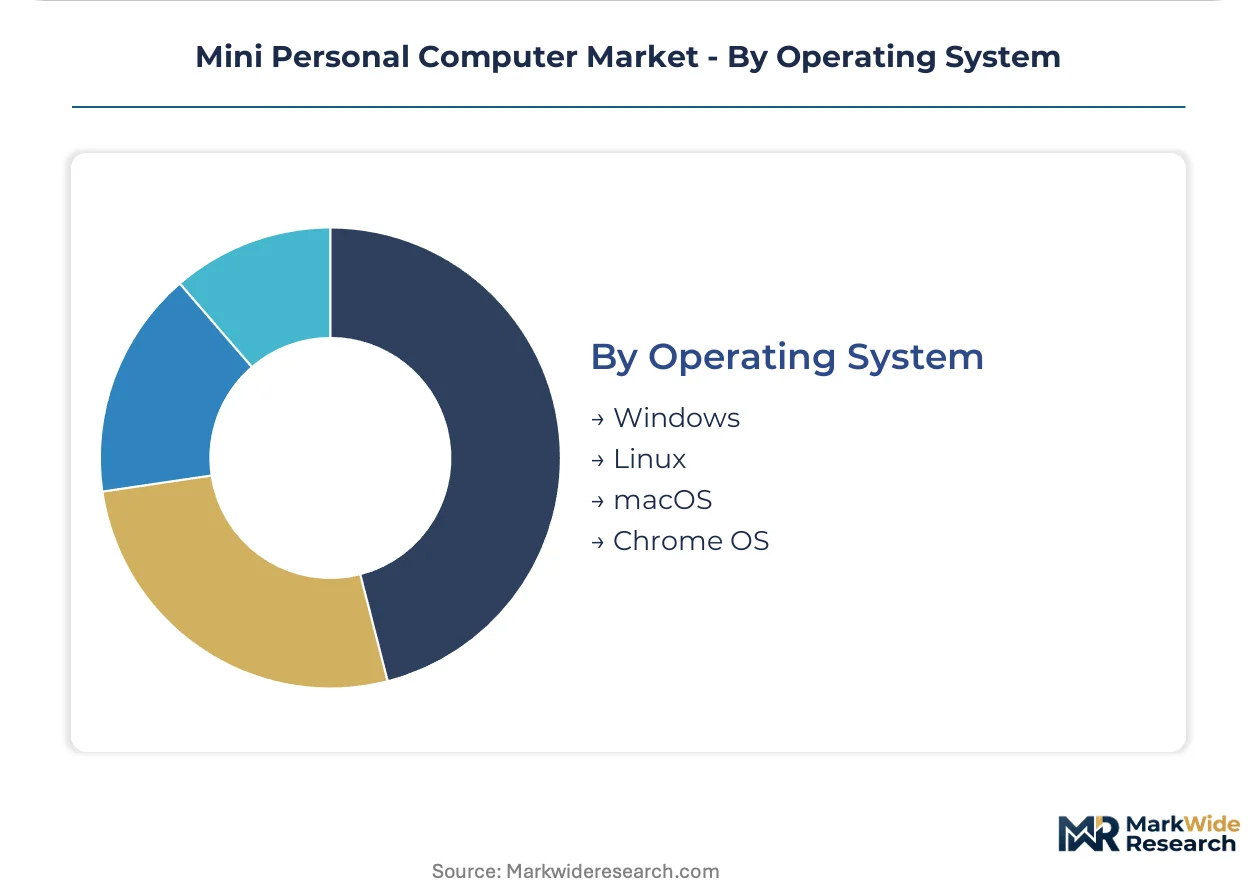
Operating System:
License economics and administrative control depth create sharp segmentation between consumer and developer-oriented deployments.
- Windows:Volume licensing agreements and Active Directory integration sustain dominance in enterprise fleets. Microsoft's Windows 11 hardware requirements are accelerating refresh cycles for older compact devices.
- Chrome OS:Cloud-native architecture and zero-touch enrollment reduce IT administration overhead for education and kiosk deployments. Google's control over update cadence limits kernel-level customization.
- Linux:Developer-focused professionals seeking container-native workflows and hardware control without licensing overhead are expanding deployments despite enterprise IT skill gaps.
- macOS:Apple's vertical integration with M-series silicon captures premium compact workstation tier through unified memory architecture unavailable to x86 competitors.
Windows retains the largest installed base; Linux gains share fastest among cloud-native development teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics manufacturing corridor anchors compact workstation assembly, with component sourcing radiating across the Pearl River Delta into Dongguan and Huizhou fabrication clusters.
United States
Enterprise procurement for remote work standardization drives NUC and micro tower volumes through direct channel agreements. The EPA ENERGY STAR program tightens idle power draw mandates, forcing power subsystem redesigns. Austin's technology corridor hosts multiple OEM configuration facilities serving federal and financial services verticals.
China
Domestic cloud infrastructure expansion and smart city deployments absorb ARM-based compact compute nodes at scale. MIIT enforces GB standards for electromagnetic compatibility in tightly packed radio configurations. Suzhou's industrial park concentration specializes in gallium nitride adapter production for USB-C Power Delivery architectures.
Germany
Industrial automation buyers pilot hybrid ARM-x86 configurations for edge inference workloads in manufacturing environments. The EU Ecodesign for Sustainable Products Regulation mandates carbon footprint disclosure across PCB fabrication through final assembly. Munich's precision engineering cluster drives thermal solution innovation for sub-liter chassis designs.
India
Institutional digitization in education verticals accelerates Chrome OS micro device tenders below saturation levels. BIS certification requirements for electronics imports create compliance barriers for unlocalized supply chains. Bengaluru's IT corridor concentrates systems integration capabilities for enterprise fleet deployments.
Japan
Corporate refresh cycles compress as METI efficiency guidelines push workstation replacement timelines. JIS standards govern thermal performance testing for compact chassis in confined office environments. Tokyo-Osaka logistics channels prioritize just-in-time delivery for space-constrained commercial deployments.
Mini Personal Computer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal design and memory architecture sophistication, with unified memory integration commanding pricing separation from modular x86 configurations. The vendor base stratifies into three tiers: silicon-integrated OEMs controlling reference designs, assembly specialists configuring white-label platforms, and regional distributors managing localized certification. Dominant competitive moves include direct channel control for enterprise procurement and gallium nitride power subsystem integration to meet tightening efficiency mandates.
Within the silicon-integrated tier, Apple, Inc. exemplifies vertical control through captive ARM architecture, while Dell Technologies, Inc. and HP, Inc. anchor enterprise procurement through configurable micro tower lines and education vertical specialization respectively. These three entities occupy positions spanning premium compact workstations through institutional volume agreements, representing divergent strategic bets on unified versus modular memory approaches.
| Leading Market Players |
|---|
| Apple, Inc. |
| Dell Technologies, Inc. |
| HP, Inc. |
| Lenovo Group Limited |
| Acer, Inc. |
| ASUSTeK Computer Inc. |
| GIGA-BYTE Technology Co., Ltd. |
| ASRock Inc. |
| Zotac Technology Limited |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride adapter architectures are simultaneously compressing power supply costs and concentrating sourcing requirements around Shenzhen and Suzhou fabrication clusters, reshaping how OEMs negotiate component access against tightening EU Ecodesign efficiency mandates.
Pricing Analysis
Performance-per-watt benchmarks anchor value-based pricing across NUC and micro tower tiers, with unified memory configurations commanding substantial premiums over modular x86 alternatives. Certification grade under EPA ENERGY STAR and EU Ecodesign tiers separates premium from standard positioning, while volume scale agreements with federal and financial services buyers compress margins at the procurement core. Cost compression in stick PC segments is intensifying because ARM-based smart displays absorb signage workloads, forcing barebones vendors toward unsustainable price points. Education vertical tenders exhibit highest price sensitivity through sub-$300 Chrome OS targets, whereas enterprise remote work standardization shows lowest sensitivity due to three-year refresh cycle bundling.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States federal and financial services verticals, while distributor networks serve fragmented education and small business segments. Component sourcing concentrates in China, Taiwan, and South Korea, with gallium nitride semiconductors, DDR5 memory modules, and Wi-Fi 6E radio chipsets drawing from concentrated foundry capacity. Single-source vulnerability around USB-C Power Delivery controllers creates procurement risk as automotive and consumer electronics sectors compete for identical silicon allocations. Distribution runs through Austin configuration facilities for United States government compliance and Bengaluru integration centers for Indian institutional tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride adapter foundry capacity constraints prop pricing power for OEMs with secured supply allocations, insulating premium tiers from commodity erosion.
For Market Incumbents: Cement direct channel control through configurable micro tower lines with vPro management capabilities, locking federal and financial services buyers into three-year refresh cycles. Deepen backward integration into gallium nitride power subsystem design to defend against thermal engineering talent scarcity at Asian foundries.
For New Entrants and Emerging Players: The $200-400 price-point gap between premium NUCs and economy stick PCs offers white space for ARM-based compact workstations with integrated neural processing units. India's underpenetrated education vertical presents the most penetrable geography, with Chrome OS micro devices below institutional saturation levels. Pursue white-label partnerships with Shenzhen assembly specialists to bypass BIS certification barriers through localized supply chain presence.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by silicon-integrated OEMs seeking thermal engineering capabilities and gallium nitride adapter intellectual property. Long-term viability favors vendors with unified memory architecture or captive ARM designs over modular x86 assemblers facing margin compression. Watch USB-C Power Delivery standard revision timing as inflection indicator for power subsystem vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Adapter Integration | EPA ENERGY STAR compliance creates procurement preference for OEMs with optimized power delivery subsystems. |
| Direct Channel Control Expansion | Federal and financial services verticals favor vendors with Austin-based configuration and support infrastructure. |
| ARM Architecture Pivot | Hybrid ARM-x86 configurations capture edge inference workloads from industrial automation buyers in Germany. |
| Education Vertical Localization | Bengaluru systems integration capabilities enable Indian institutional tender compliance against BIS requirements. |
| Unified Memory Architecture Investment | Vertical silicon integration commands premium pricing separation from modular DDR5-based competitors. |
Research Methodology
Multi-period observation of NUC shipment volumes, thermal design power trajectories, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with OEM product managers, enterprise IT procurement officers, thermal engineering specialists, and education vertical channel partners. Secondary validation drew from EPA ENERGY STAR certification databases, EU Ecodesign regulatory filings, FCC Part 15 equipment authorization records, and SEC 10-K disclosures from listed hardware vendors. Bottom-up assembly cost modeling triangulated against top-down procurement survey data across the analysis window.
Segment-weighting applied product type, target audience, connectivity configuration, and operating system as primary dimensions, with regional regulatory cluster as secondary stratification. CAGRs were derived from logistic adoption curves fitted to historical refresh cycle compression patterns and enterprise fleet standardization trajectories. Gallium nitride adapter cost trajectories and Wi-Fi 6E certification timeline assumptions fed sensitivity bands throughout the forecast period.
Inputs from OEM shipment disclosures and regulatory certification databases were available through the study window; gaps in channel inventory positioning and unreported education tender awards introduce uncertainty bands around volume estimates. Forecasts reflect documented assumptions regarding refresh cycle duration and remote work infrastructure persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Edge Computing Market
Others
Global Smart Devices Market
Others
Fluorite Market
Others
Flexible PVC Films and Sheets Market
Others
PC As a Service Market
Others
US Cat Food Market
Others
Badminton Apparel Market
Others
Reusable Wine Bags Market
Others
Global Cosmetovigilance Market
Others
Agitator Bead Mill Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Smart Card Market
Others
United States Bean Bags Market
Others
Fluid Dispensing Systems Market
Others
North America Flexographic Printing Market
Others
Nuclear Power Cables Market