
 Digital Supply Chain Market | 2026-2036
Digital Supply Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Supply Chain Market Analysis
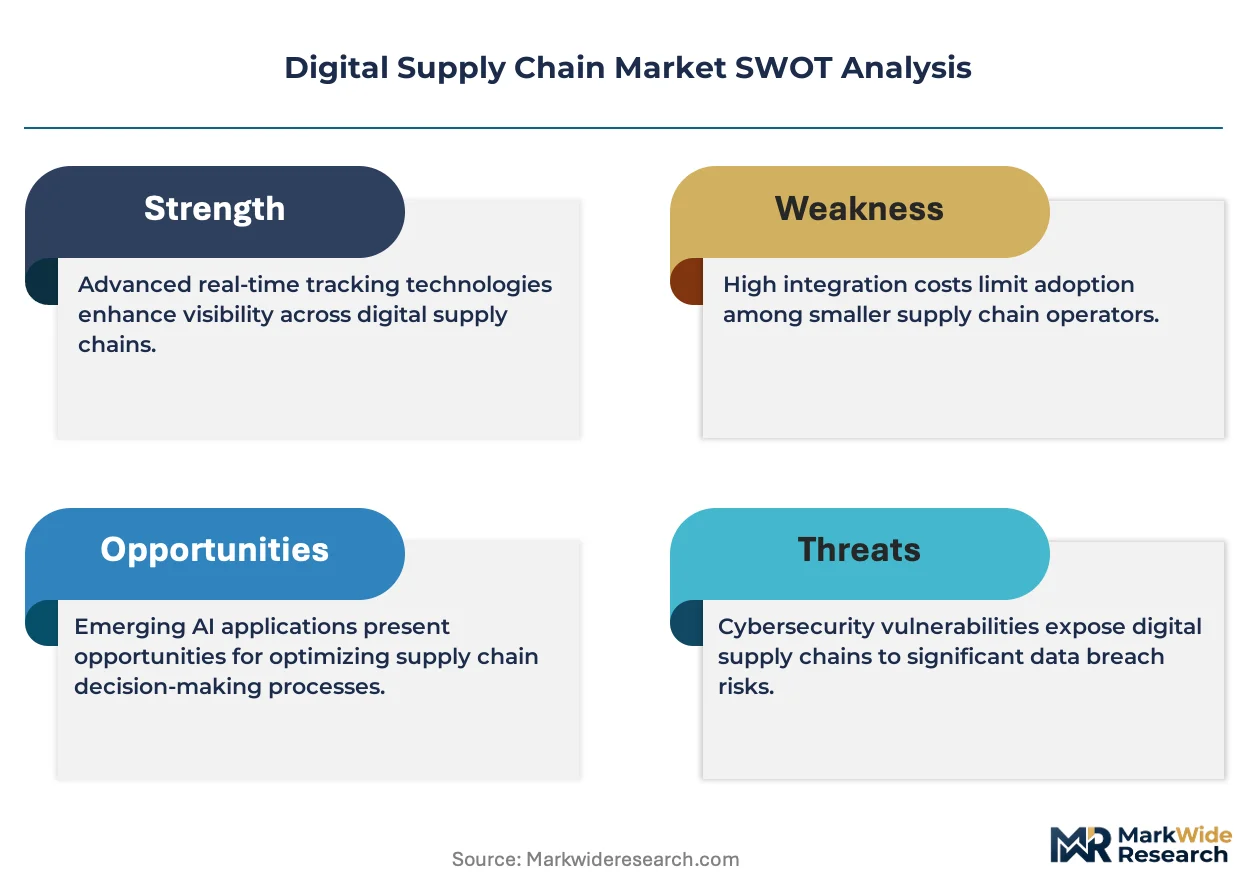
Modular unbundling of supply chain software suites is decoupling visibility tools from monolithic ERP contracts, letting mid-market buyers purchase demand forecasting and inventory modules à la carte. SAP SE leverages its S/4HANA backbone to anchor enterprise clients seeking integrated logistics planning. Blue Yonder Group, Inc. specializes in AI-native demand forecasting, differentiating its cloud architecture from legacy on-premise stacks. IBM Corporation extends its blockchain-enabled food trust network, competing on provenance verification where regulatory compliance pressures intensify.
Digital supply chain denotes the integrated use of software platforms, sensor networks, and data analytics to orchestrate material flows, inventory positions, and logistics movements across multi-tier supplier networks, typically operating through API-connected cloud architectures with sub-second refresh rates on inventory status. Its primary commercial purpose is to compress cash-to-cash cycles and reduce bullwhip amplification across distributed manufacturing and retail ecosystems. Cloud-based deployment models are capturing the fastest expansion as enterprises retire data center footprints, while visibility tools command premium pricing due to their role in meeting mandatory disclosure requirements. Blockchain and AI technologies within the technology segment are reshaping competitive positioning, with early movers in pharmaceutical and cold-chain verticals building defensible compliance advantages.
The FDA Food Safety Modernization Act traceability mandates and the EU Green Deal supply chain due diligence framework are forcing food and automotive manufacturers to adopt interoperable visibility platforms that can authenticate supplier claims and document carbon intensity at the batch level. EMA serialization requirements under the Falsified Medicines Directive add parallel compliance burdens across European pharmaceutical distribution. Stakeholders must weigh the capital efficiency of cloud-native architectures against the data sovereignty risks that hybrid deployments are designed to address.
Market Dynamics
Cloud-native architectures are compressing deployment cycles from months to weeks while EMA serialization mandates force pharmaceutical distributors into real-time track-and-trace compliance, creating a bifurcation between agile mid-market adopters and legacy-bound enterprises.
Growth Catalysts
- FDA Food Safety Modernization Act:Traceability mandates compel food manufacturers to deploy batch-level visibility platforms, accelerating replacement of paper-based lot tracking.
- AI-native demand forecasting:Machine learning models trained on POS and weather data are reducing forecast error rates, pulling investment from statistical planning tools.
- German pharmaceutical distribution:EMA Falsified Medicines Directive enforcement is expanding serialization infrastructure across wholesale and pharmacy tiers.
Market Restraints
- Data sovereignty compliance:GDPR cross-border transfer restrictions and China's data localization rules fragment cloud architecture decisions, forcing redundant regional deployments.
- Legacy ERP integration costs:Custom API development to connect 1990s-era warehouse management systems consumes 40-60% of implementation budgets.
- Semiconductor sensor shortages:IoT device lead times for cold-chain monitoring hardware extend 26-40 weeks, delaying fleet-wide visibility rollouts.
Strategic Opportunities
- EU Green Deal due diligence:Carbon intensity documentation requirements at the batch level create first-mover advantages for platforms with embedded emissions calculators.
- India PLI scheme for electronics:Manufacturing incentives are spawning greenfield facilities without legacy system debt, enabling cloud-native supply chain deployment from inception.
- Blockchain-AI convergence:Smart contracts automating payment release upon verified delivery completion are reducing days-sales-outstanding for 3PL providers.
Industry Challenges
- API talent scarcity:Supply chain orchestration platforms require engineers fluent in EDI X12 and modern REST architectures, a skill intersection with limited labor pool depth.
- Multi-tier supplier onboarding:Tier-3 and Tier-4 visibility mandates from automotive OEMs face resistance from small component shops lacking IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Supply Chain Market |
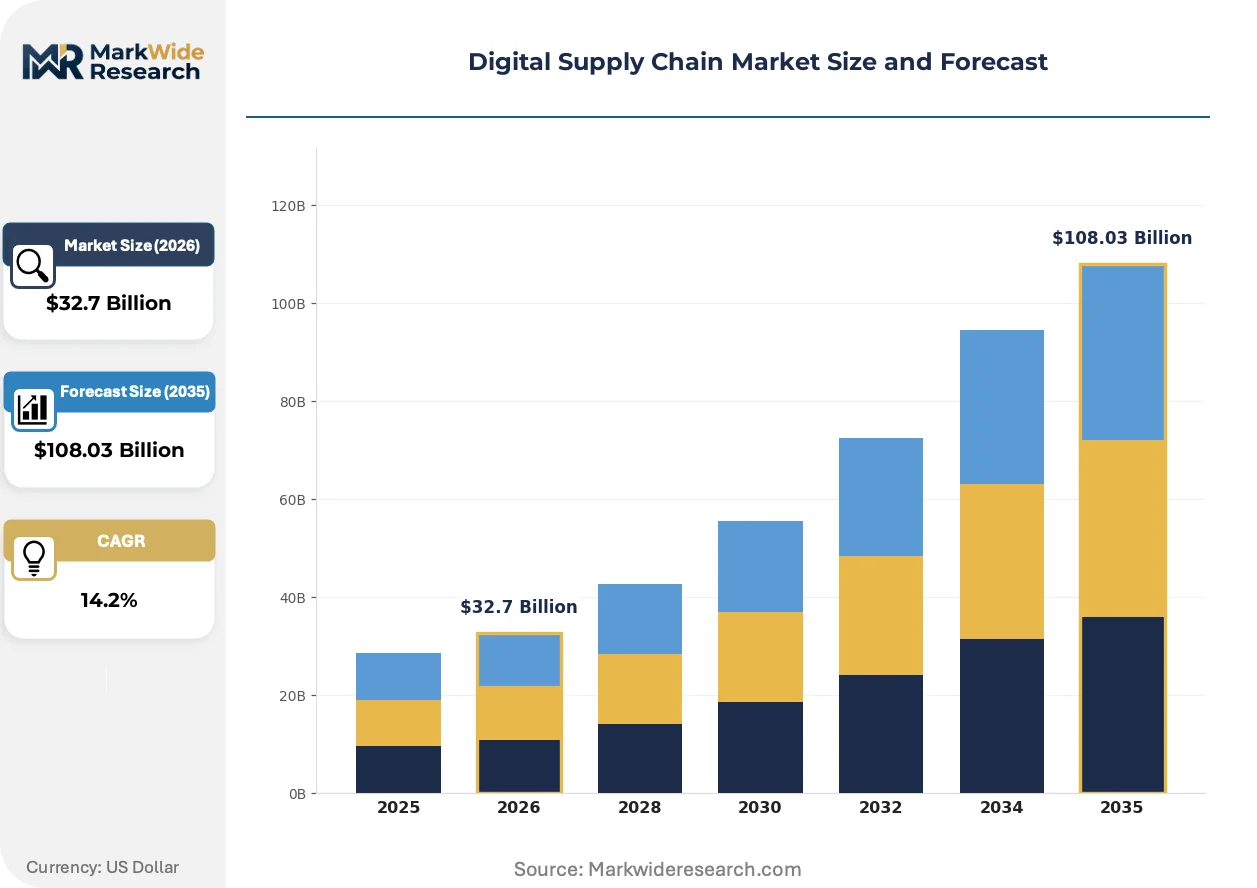
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $108.03 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Inventory Management, Order Processing, Demand Forecasting, Visibility Tools End User: Retail, Manufacturing, Wholesale, E-commerce Deployment Model: Cloud-Based, On-Premise, Hybrid, Managed Services Technology: IoT, Blockchain, AI, Big Data |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Salesforce.com, Inc., Software AG, Infor, Inc., Microsoft, Blue Yonder Group, Inc., Cloudera, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Supply Chain Market Emerging Trajectories
Real-time inventory visibility is absorbing capital allocation as enterprises recognize that sub-second refresh rates compress safety stock requirements more effectively than demand forecasting improvements alone.
Digital twin technology is absorbing physical supply chain complexity by creating virtual replicas of warehouse flows and transportation networks. Retailers with high SKU volatility are deploying these models to simulate fulfillment path changes before capital deployment. The technology is absorbing risk from network redesign decisions that previously required physical pilot programs.
EU CSRD sustainability reporting requirements are mandating granular supplier emissions data disclosure across fiscal years 2024-2026. Automotive and apparel manufacturers must now authenticate Scope 3 claims through interoperable platforms. German industrial clusters are responding fastest, embedding carbon accounting modules directly into procurement workflows.
Subscription-based visibility pricing is displacing perpetual license models among mid-market manufacturers. Buyers prefer operational expenditure treatment for software that requires continuous algorithmic updates. This shift is most pronounced in United States food processing, where quarterly FDA audit readiness demands evergreen compliance feature access.
Digital Supply Chain Market Segmentation
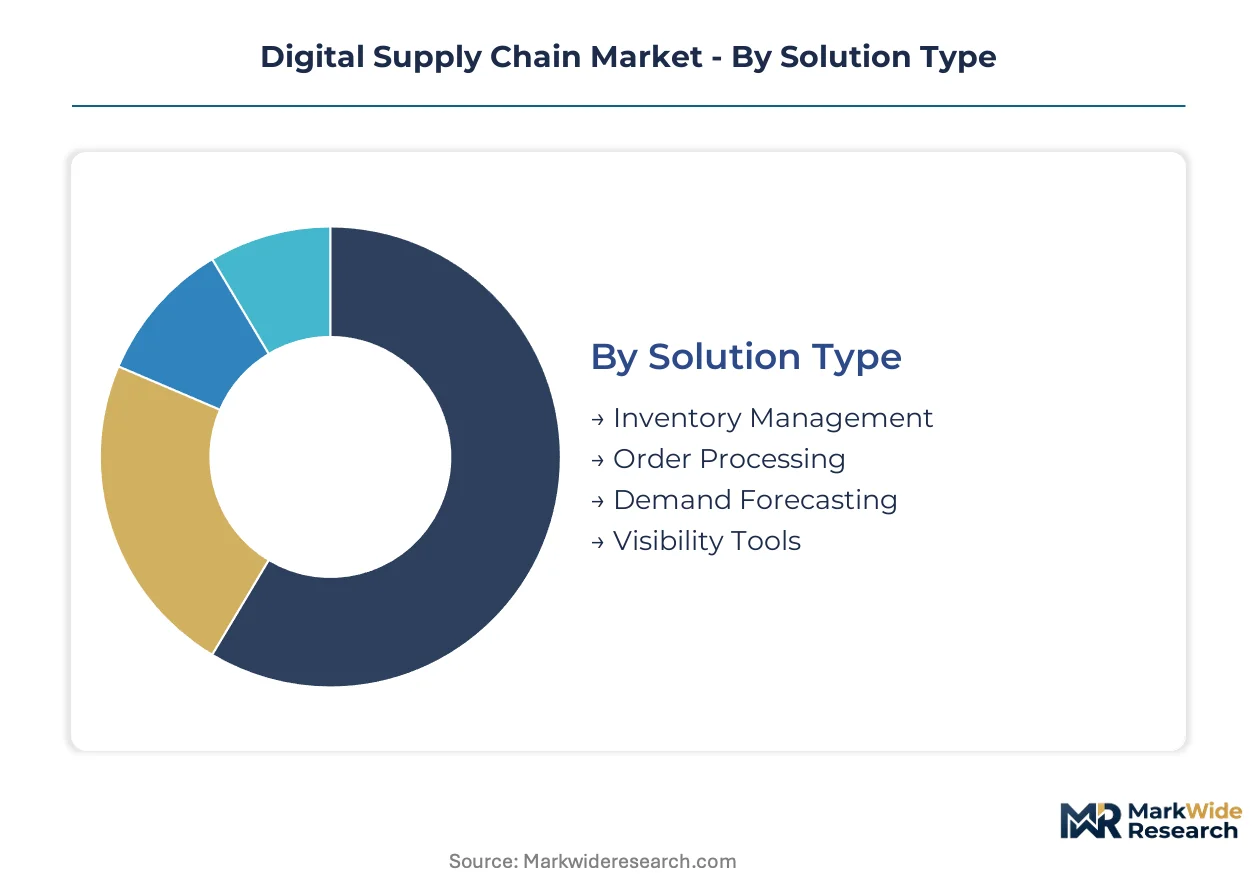
Digital supply chain buyers fragment sharply by technical maturity and regulatory exposure, with compliance-driven enterprises favoring integrated suites while agile mid-market operators pursue modular point solutions. Segmentation reveals where pricing power concentrates and which integration pathways dictate vendor selection.
Solution Type:
Buyers in this category differentiate by operational pain point severity and the degree of ERP entanglement they are willing to tolerate.
- Inventory Management:Real-time stock positioning across multi-echelon networks, typically delivered through API-connected warehouse execution systems. Demand concentrates among US food processors facing FDA Food Safety Modernization Act lot-tracking mandates, where batch-level granularity now replaces periodic cycle counts.
- Visibility Tools:Sub-second refresh platforms tracking goods-in-transit and supplier network status through sensor fusion and EDI aggregation. German pharmaceutical distributors under EMA serialization requirements are expanding deployments fastest, as Falsified Medicines Directive enforcement tightens across wholesale tiers.
- Demand Forecasting:Machine learning models ingesting POS, weather, and macro signals to reduce forecast error.
- Order Processing:Orchestration engines automating purchase-to-pay workflows and exception management.
Inventory Management leads volumes today; Visibility Tools is gaining share fastest.
End User:
Margin pressure and SKU velocity determine investment urgency across these verticals.
- Retail:High-velocity omnichannel operators deploying digital twins to simulate fulfillment path changes before capital deployment. US grocery chains with private-label expansion programs are prioritizing platforms that unify supplier scorecards with carbon accounting modules under emerging CSRD-aligned disclosure requirements.
- Manufacturing:Discrete and process producers seeking to compress cash-to-cash cycles through supplier collaboration portals. Automotive OEMs in Germany are mandating Tier-3 visibility into component shops, though small suppliers resist onboarding due to IT infrastructure gaps.
- E-commerce:Pure-play and hybrid sellers with returns-heavy economics.
- Wholesale:Distributors managing high SKU counts across fragmented supplier bases.
Manufacturing leads volumes today; Retail is climbing the fastest.
Deployment Model:
Data sovereignty risk tolerance and legacy system debt shape architecture decisions.
- Cloud-Based:Multi-tenant SaaS architectures with continuous algorithmic updates and API-first integration. US food processors prefer operational expenditure treatment here, as quarterly FDA audit readiness demands evergreen compliance feature access without version-lock.
- Hybrid:Split configurations keeping sensitive planning data on-premise while leveraging cloud analytics. European manufacturers with GDPR cross-border transfer concerns are adopting this model to satisfy data residency requirements without sacrificing computational scale.
- On-Premise:Single-tenant installations in regulated or air-gapped environments.
- Managed Services:Outsourced operation of supply chain platforms by third-party providers.
Cloud-Based leads volumes today; Hybrid is expanding most quickly.
Technology:
Proof-of-concept maturity and integration cost determine which capabilities reach production scale.
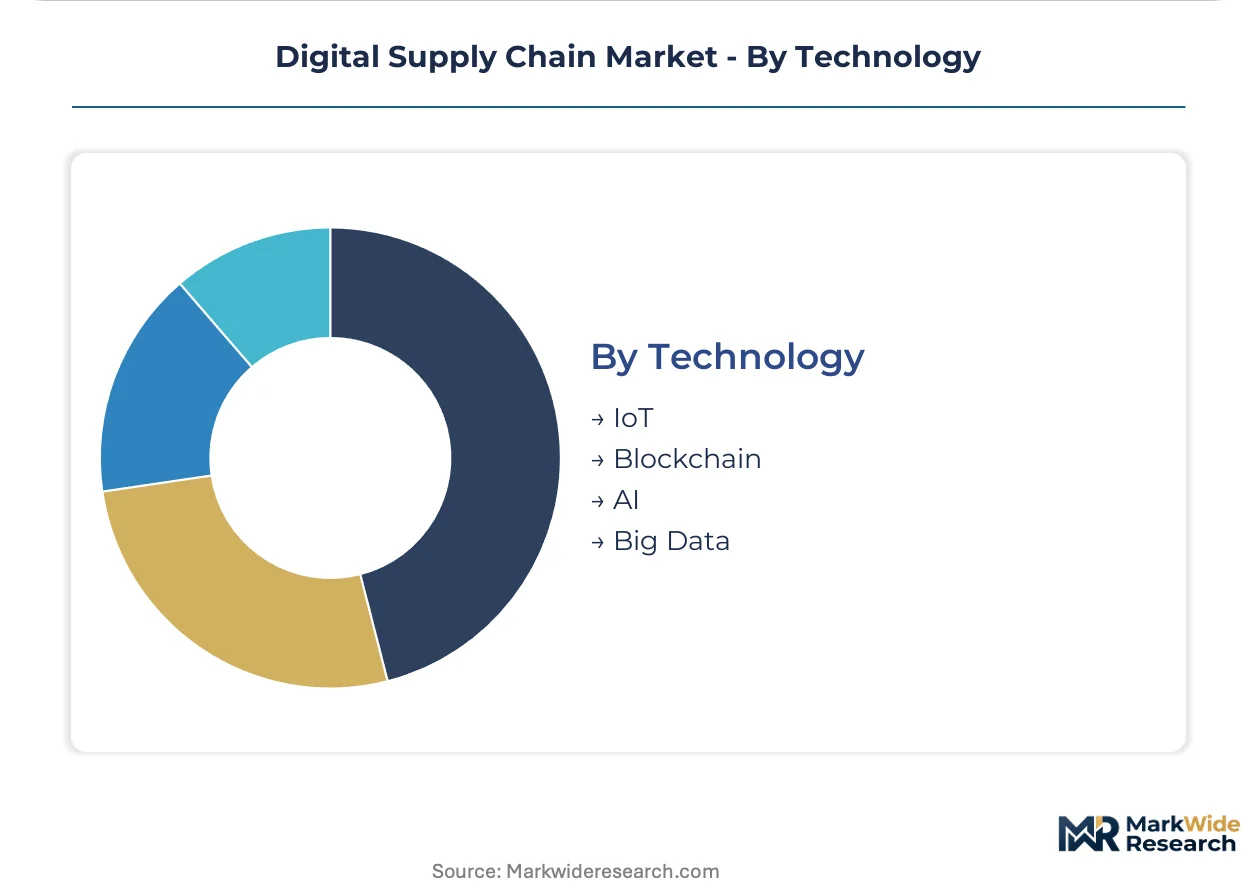
- AI:Predictive models for demand sensing, network optimization, and autonomous exception handling. Blue Yonder and comparable vendors differentiate through cloud-native architectures that bypass legacy on-premise latency constraints.
- IoT:Sensor networks for cold-chain monitoring, asset tracking, and condition-based alerts. Semiconductor shortages have extended hardware lead times to 26-40 weeks, delaying fleet-wide rollouts for pharmaceutical and food distributors.
- Blockchain:Immutable ledgers for provenance verification and smart contract automation.
- Big Data:Lakehouse architectures unifying structured and unstructured supply chain telemetry.
AI leads volumes today; Blockchain is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The digital supply chain industry traces its commercial roots to post-war American manufacturing and logistics automation, with German engineering and Japanese lean production methods later embedding sensor-driven visibility into global trade infrastructure. Regulatory fragmentation now shapes regional deployment patterns as data sovereignty concerns intensify.
United States
Cloud-native visibility platforms dominate procurement decisions as food processors confront FDA Food Safety Modernization Act traceability deadlines. The FDA mandates batch-level electronic records for high-risk foods by 2026. Chicago-based meatpackers and California produce distributors are retiring paper-based lot tracking in favor of API-connected warehouse execution systems.
Germany
Automotive OEMs mandate Tier-3 supplier visibility into component shops across the Baden-Württemberg and Bavaria industrial belts. The EU Green Deal supply chain due diligence framework requires carbon intensity documentation at the batch level. Stuttgart-area manufacturers embed emissions calculators directly into procurement workflows to satisfy CSRD-aligned disclosure requirements.
China
Domestic e-commerce giants drive demand for real-time inventory orchestration across the Yangtze River Delta manufacturing corridor. The country's data localization rules under MIIT guidance fragment cloud architecture decisions. Shenzhen electronics assemblers deploy hybrid configurations to satisfy residency requirements without sacrificing computational scale.
India
Greenfield electronics manufacturing under the PLI scheme enables cloud-native supply chain deployment without legacy system debt. The DGFT and Ministry of Electronics and Information Technology prioritize traceability infrastructure for pharmaceutical exports. Karnataka and Tamil Nadu industrial clusters attract visibility platform vendors targeting contract manufacturers.
United Kingdom
London-based commodity traders and Liverpool port operators invest in blockchain-enabled provenance verification for post-Brexit customs compliance. The UK Medicines and Healthcare products Regulatory Agency enforces serialization standards aligned with former EMA frameworks. Midlands automotive suppliers face pressure from German OEMs to upgrade IT infrastructure for multi-tier visibility.
Digital Supply Chain Market Vendor Landscape
Premium-margin players sit above commodity-margin players across compliance depth and integration complexity. The vendor base separates into three tiers: enterprise suite providers anchoring integrated logistics planning, AI-native specialists commanding pricing power on forecasting accuracy, and modular point-solution vendors capturing mid-market buyers seeking à la carte procurement. Consolidation pressure concentrates among cloud-native architectures displacing on-premise legacy stacks. Strategic moves center on API-first platform expansion and vertical-specific compliance module development.
Within the enterprise suite tier, SAP SE and Oracle Corporation anchor integrated logistics planning for multinational manufacturers seeking to compress cash-to-cash cycles. Blue Yonder Group, Inc. occupies a specialist position exemplifying AI-native demand forecasting architectures that bypass legacy latency constraints. IBM Corporation represents the blockchain-provenance vector, with its food trust network competing on regulatory compliance verification where disclosure pressures intensify.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Salesforce.com, Inc. |
| Software AG |
| Infor, Inc. |
| Microsoft |
| Blue Yonder Group, Inc. |
| Cloudera, Inc. |
| Others |
Supply Flow & Price Mechanics
Semiconductor sensor lead times stretching 26-40 weeks cascade through digital supply chain hardware procurement, forcing pharmaceutical and food distributors into premium pricing tiers for cold-chain monitoring equipment while compressing margins on commoditized visibility software subscriptions.
Pricing Analysis
Subscription-based SaaS pricing with tiered feature access dominates procurement decisions across mid-market manufacturers seeking operational expenditure treatment. Price differentiation hinges on compliance certification depth—FDA Food Safety Modernization Act audit-ready platforms command premiums over basic inventory modules—and integration complexity with legacy ERP stacks. Pricing pressure stems from modular unbundling as buyers purchase demand forecasting à la carte rather than accepting monolithic suite contracts. Small component shops in automotive supply chains exhibit highest price sensitivity, while German pharmaceutical distributors under EMA serialization mandates show lowest elasticity due to regulatory non-negotiability.
Supply Chain Analysis
IoT sensor supply rests on Taiwanese semiconductor foundries, South Korean memory manufacturers, and Chinese PCB assembly clusters for cold-chain hardware production. Cloud infrastructure draws from US hyperscaler regions, Irish and Dutch European data centers, and Singaporean Asia-Pacific nodes. Single-source vulnerability concentrates in advanced AI chipsets for demand forecasting workloads. Distribution runs through direct enterprise sales for integrated suites, channel partners for mid-market point solutions, and managed service providers for hybrid deployments lacking internal IT capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital supply chain market functions as a regulatory compounder where FDA Food Safety Modernization Act traceability deadlines and EU Green Deal due diligence frameworks generate recurring compliance-driven replacement cycles.
For Market Incumbents: Deploy API-first platform expansion to anchor enterprise clients against modular point-solution erosion. Deepen backward integration into cloud infrastructure to reduce hyperscaler dependency costs. Fortify certification moats around FDA audit-ready and EMA serialization-aligned modules before compliance deadlines harden switching costs. For New Entrants and Emerging Players: Capture greenfield electronics manufacturing in India under PLI scheme incentives where legacy system debt is absent. Target Tier-3 supplier visibility mandates in German automotive clusters where small component shops lack IT infrastructure and resist incumbent onboarding. Lead with carbon accounting modules embedded directly into procurement workflows to satisfy CSRD-aligned disclosure requirements faster than suite providers can retrofit. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native demand forecasting specialists possessing cloud architectures that bypass legacy latency constraints. Long-term viability centers on vendors with vertical-specific compliance module depth rather than horizontal platform breadth. Watch for semiconductor sensor lead time normalization as the inflection indicator for hardware-enabled visibility platform expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first connectivity compresses deployment cycles from months to weeks for mid-market adopters. |
| Acquisition of Specialist Firm | Carbon accounting module targets EU Green Deal due diligence requirements in German industrial clusters. |
| Geographic Expansion | India PLI scheme greenfield facilities enable cloud-native deployment without legacy system debt. |
| Strategic Partnership | Blockchain-AI convergence automates payment release upon verified delivery completion for 3PL providers. |
| Product Launch | Digital twin technology simulates fulfillment path changes before capital deployment for high-SKU retailers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged supply chain software procurement officers, cloud platform engineers, pharmaceutical regulatory affairs leads, food safety compliance directors, and automotive Tier-1 supplier IT managers. Secondary validation drew from FDA guidance documents, EMA Falsified Medicines Directive enforcement notices, EU Green Deal implementation texts, and SEC filings of publicly traded software vendors. Bottom-up deployment estimates and top-down market sizing triangulated to cross-check segment allocations.
Segment-weighting approaches distributed value across solution type, deployment model, end-user vertical, and technology layer throughout the forecast period. Deployment model splits—cloud-based, hybrid, on-premise, managed services—drove infrastructure revenue assumptions. End-user verticals shaped compliance module pricing power. CAGRs derived from replacement cycle analysis of legacy ERP systems and regulatory deadline impacts on procurement urgency. AI-native architecture displacement rates and IoT sensor fleet penetration curves supplied industry-specific forecast inputs.
Semiconductor supply disruptions, data sovereignty enforcement shifts, and API talent scarcity are the dominant revision risks to modeled deployment timelines. Forecasts embed assumptions about regulatory deadline adherence and cloud migration velocity without hardening into point predictions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Supply Chain Risk Management Software Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
North America Agricultural Enzymes Market
Others
Education and Learning Analytics Market
Others
Europe Digital Experience Platform Market
Others
Global Magnetic Flow Meters Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Latin America Automotive HVAC Market
Others
Aircraft Lighting Market
Others
Industrial PC Market
Others
South Korea Smart Home Market
Others
North America Thermoformed Plastics Market
Others
Agitator Bead Mill Market
Others
Rope Market
Others
Nonlinear Editing System Market
Others
Small Office Home Office (SOHO) Servers Market