
 China Cloud Seeding Market | 2026-2036
China Cloud Seeding Market Size, Share, and Industry Trends Forecast 2026-2036
China Cloud Seeding Market Insights
Government procurement channels for weather modification equipment is fragmenting as provincial meteorological bureaus gain direct contracting authority alongside central ministries. China Meteorological Administration sustains institutional dominance through nationwide operational standards and training protocols. Jiangxi Gangsi competes aggressively in ground-based generator manufacturing for county-level deployments. Aerospace Information Research Institute leverages satellite-data integration to differentiate its seeding mission planning services from conventional equipment vendors.
Cloud seeding encompasses the deliberate introduction of ice-nucleating or hygroscopic agents—typically silver iodide, dry ice, or potassium iodide—into suitable cloud formations to enhance precipitation yield, with operational altitudes generally spanning 3,000 to 8,000 meters depending on cloud base height and seeding modality. The technology serves primarily to augment freshwater availability for agricultural irrigation, reservoir replenishment, and urban water security in precipitation-deficient regions. Aircraft systems command the dominant share of value given capital intensity and flight-hour requirements, while ground-based generators represent the fastest-expanding product category as autonomous remote units reduce labor costs in mountainous terrain. Rain generation applications anchor current revenue, though drought mitigation is displacing traditional agricultural scheduling as climate volatility intensifies.
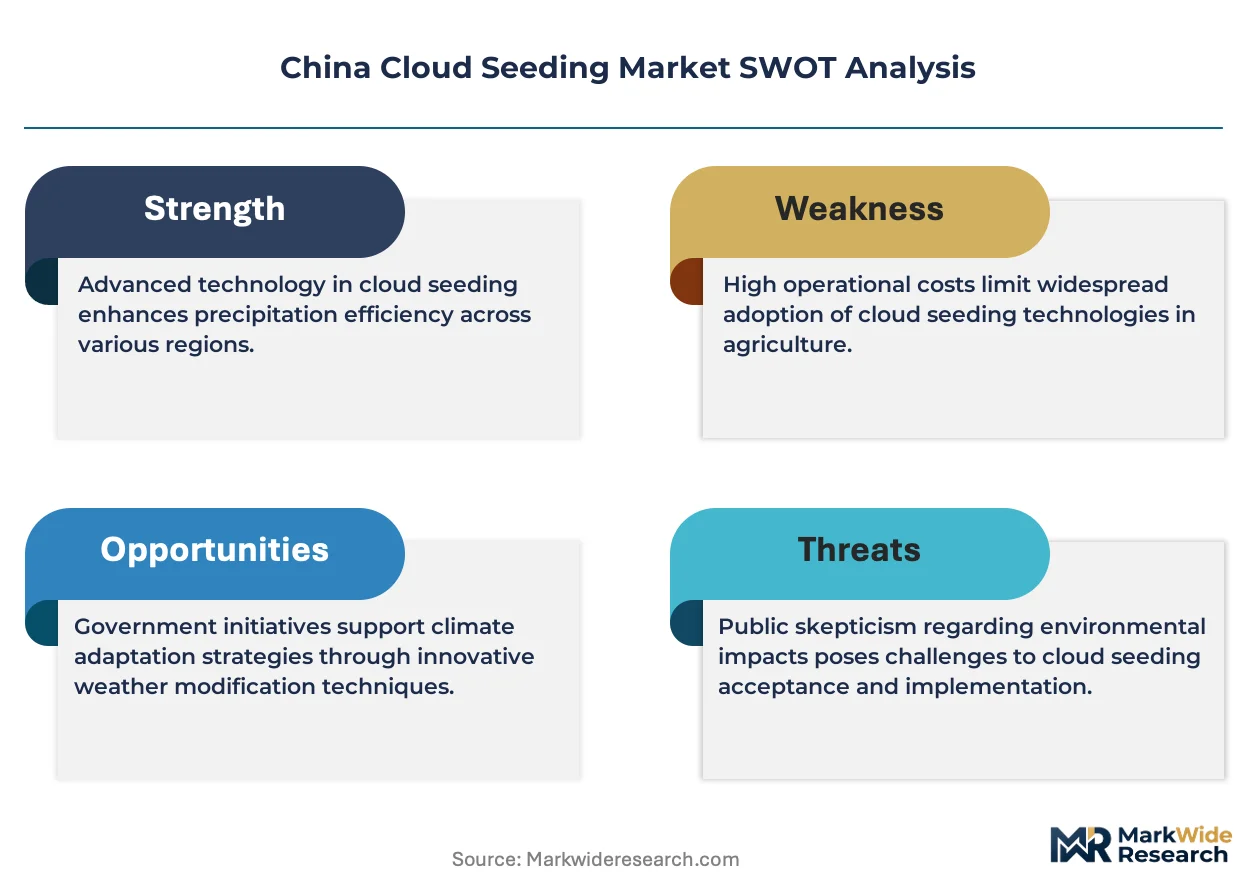
China's Ministry of Ecology and Environment and China Meteorological Administration jointly enforce operational permits for weather modification activities, with GB standards governing silver iodide residue thresholds and flight safety protocols. SAMR oversight of meteorological equipment certification creates compliance barriers for imported seeding technologies. Stakeholders must monitor evolving provincial water-rights frameworks and dual carbon compliance requirements that could restrict high-emission aircraft operations in favor of electric or hydrogen-powered seeding platforms.
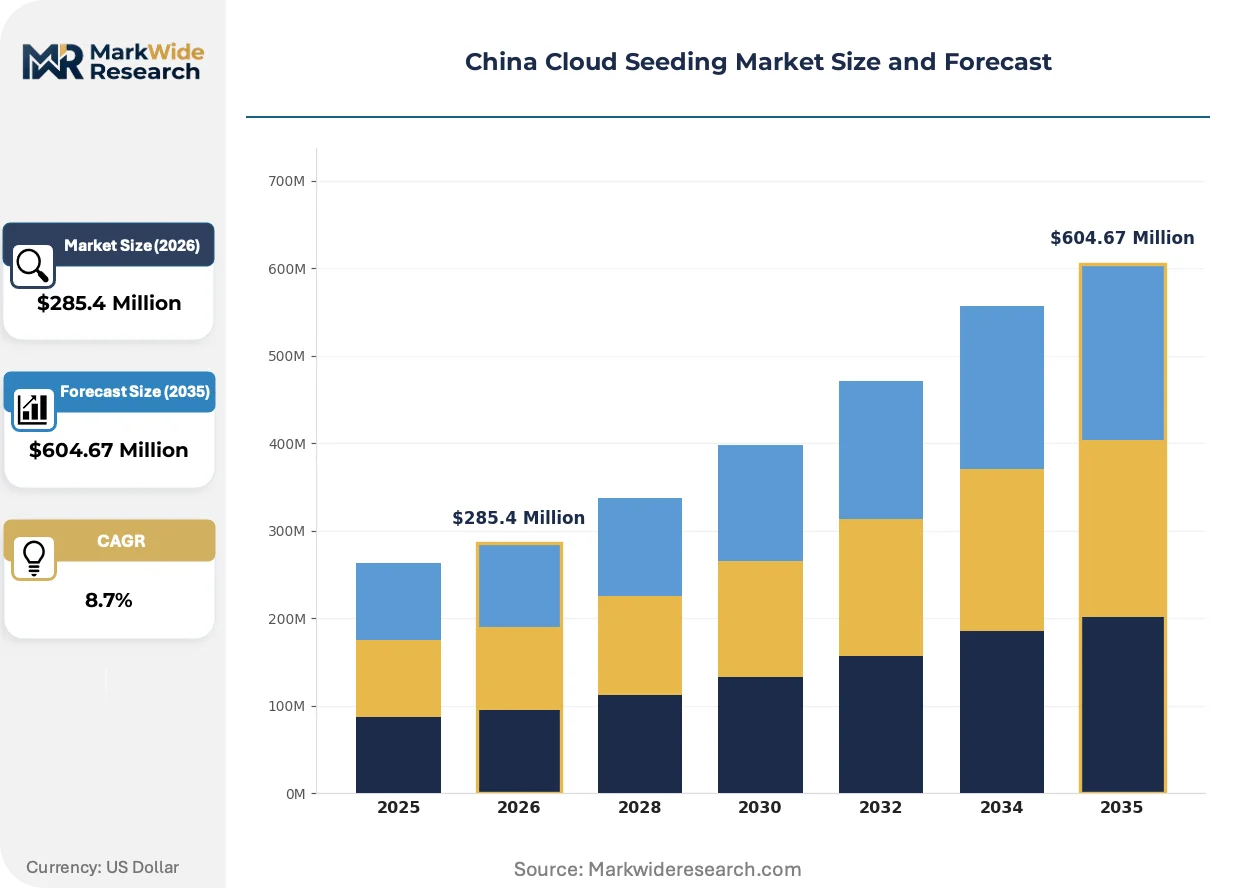
Market Dynamics
Provincial meteorological bureaus in drought-prone regions are consolidating procurement authority while the China Meteorological Administration tightens operational standards, creating a bifurcated governance structure that reshapes vendor access and compliance costs.
Growth Catalysts
- Dual carbon policy framework:MEE directives on water security are mandating expanded weather modification coverage in agricultural corridors, forcing provincial budgets toward cloud seeding infrastructure.
- North China Plain irrigation stress:Depleted groundwater reserves in Hebei, Henan, and Shandong are compelling reservoir-dependent municipalities to fund aircraft-based seeding operations.
- Silver iodide dispersion automation:Ground-based generator networks with remote ignition systems are reducing labor requirements in mountainous terrain, accelerating county-level deployment timelines.
Market Restraints
- Aircraft fuel cost volatility:Jet fuel price swings directly compress flight-hour budgets for seeding missions, squeezing operational margins for bureau contractors.
- SAMR certification barriers:Imported seeding technologies face extended meteorological equipment approval timelines, protecting domestic manufacturers from foreign competition.
- Silver residue threshold enforcement:GB standards on environmental silver iodide limits are restricting seeding intensity in ecologically sensitive watersheds.
Strategic Opportunities
- Autonomous ground generator networks:Unmanned mountain installations with satellite-triggered ignition offer white space in county-level deployments underserved by aircraft.
- Hydrogen-powered seeding aircraft:Zero-emission flight platforms align with dual carbon compliance requirements, creating first-mover advantage for airframe conversions.
- Reservoir replenishment contracts:Urban water utilities are emerging as direct purchasers of seeding services, bypassing traditional agricultural scheduling channels.
Industry Challenges
- Atmospheric physicist shortage:Mission planning expertise for cloud microphysics modeling is concentrating in CMA-affiliated institutes, limiting contractor hiring pools.
- Legacy aircraft integration:Aging Y-12 turboprop fleets require avionics retrofits to meet current flight safety protocols, stretching capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cloud Seeding Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Injection, Snowmaking, Rain Generation, Weather Modification Application: Agriculture, Drought Mitigation, Water Supply, Environmental Management Product Type: Flare Guns, Ground-Based Generators, Aircraft Systems, Rocket Launchers End User: Government Agencies, Research Institutions, Agricultural Enterprises, Private Companies |
| Companies Covered | China Meteorological Administration (CMA), Aerospace Information Research Institute (AIR), Jiangxi Gangsi, China National Aero-Meteorological Center, Weather Modification Inc., RHS Consulting Inc., North America Weather Consultants Inc., Snowy Hydro Limited, Cloud Technologies GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cloud Seeding Market Trends and Innovations
Operational digitization is compressing decision cycles from weather detection to seeding execution, while regulatory pressure on emissions and residue thresholds forces hardware replacement across provincial fleets.
Satellite-data fusion platforms are digitizing mission planning workflows by integrating real-time cloud microphysics from polar-orbiting sensors with ground radar networks. Provincial meteorological bureaus in Shandong and Henan are adopting these systems fastest, replacing manual meteorologist assessments with algorithmic seeding window predictions. The technology is digitizing vendor differentiation, compressing equipment procurement cycles toward integrated solution providers and away from standalone generator manufacturers.
MEE enforcement of GB silver iodide residue thresholds is tightening operational permits for high-frequency seeding zones. Bureaucratic consequence includes mandatory environmental impact assessments for each reservoir catchment, extending project approval timelines by 4-8 months. Agricultural corridor deployments face the strictest scrutiny, with Hebei operators pivoting toward hygroscopic salt alternatives to maintain flight-hour quotas under revised compliance frameworks.
Direct contracting between county governments and equipment vendors is fragmenting traditional CMA-centralized procurement channels. County-level water bureaus in mountainous prefectures are bypassing provincial intermediaries to source autonomous ground generators, attracted by faster deployment timelines and localized maintenance contracts. This pattern is most visible in Jiangxi and Fujian, where terrain constraints favor unmanned installations over aircraft-dependent operations.
China Cloud Seeding Market Segmentation
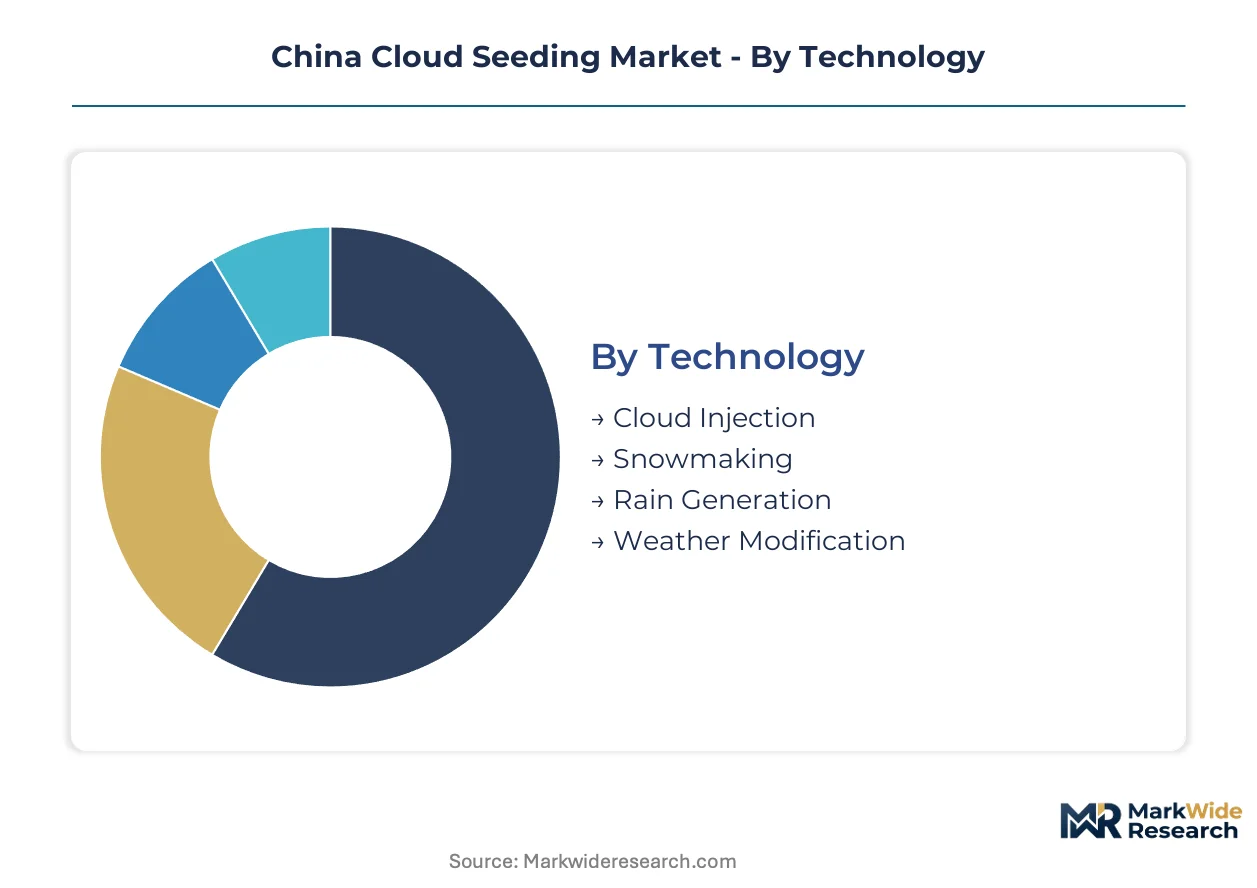
Equipment procurement cycles and operational lifecycles vary dramatically across China's cloud seeding market. Understanding these temporal patterns helps vendors align inventory planning with provincial budget calendars and CMA certification timelines.
Technology:
Replacement cycles stretch from annual consumables to decade-long infrastructure, with software-driven modalities turning over fastest.
- Rain Generation:Hygroscopic salt and silver iodide dispersion systems dominate current flight-hour allocation across Hebei and Henan provinces. Municipal water utilities in the North China Plain are expanding contracting authority for reservoir replenishment missions, bypassing traditional agricultural scheduling channels.
- Weather Modification:Integrated mission planning platforms combining satellite data fusion with ground radar networks command premium pricing from provincial meteorological bureaus. Shandong operators are adopting these systems fastest, replacing manual meteorologist assessments with algorithmic seeding window predictions.
- Cloud Injection:Direct aerosol insertion techniques serve specialized orographic enhancement projects in mountainous Fujian and Jiangxi prefectures.
- Snowmaking:Cold-cloud glaciation systems concentrate in northern ski resort corridors and high-altitude Tibetan water catchments.
Rain Generation dominates installed base. Weather Modification is where expansion concentrates.
Product Type:
Capital intensity and labor substitution potential create three distinct cost tiers across procurement budgets.
- Aircraft Systems:Manned turboprop platforms with wing-mounted flare racks and belly dispensers require CMA flight safety certification and SAMR equipment approval. Aging Y-12 fleets in provincial inventories need avionics retrofits to meet current protocols, stretching replacement timelines.
- Ground-Based Generators:Autonomous mountain installations with satellite-triggered ignition and remote monitoring capabilities are reducing labor requirements in terrain-constrained counties. Jiangxi and Fujian water bureaus are sourcing these directly from manufacturers, bypassing provincial intermediaries.
- Rocket Launchers:Artillery-style delivery systems serve rapid-response hail suppression missions in Xinjiang and Inner Mongolia agricultural corridors.
- Flare Guns:Portable surface-to-air units support tactical spot-seeding operations in emergency drought response scenarios.
Aircraft Systems capture the highest contract values. Ground-Based Generators are climbing the fastest.
Application:
End-use urgency determines funding priority, with existential water security threats commanding accelerated procurement.
- Drought Mitigation:Emergency precipitation augmentation for reservoir-dependent municipalities has displaced traditional agricultural scheduling as climate volatility intensifies. Depleted groundwater reserves in the North China Plain are compelling direct utility contracting for seeding services.
- Agriculture:Seasonal irrigation support for wheat and corn production in Hebei, Henan, and Shandong remains the volume anchor but faces budget competition from urban water security mandates.
- Water Supply:Municipal reservoir replenishment programs are emerging as standalone procurement categories with dedicated operational permits from MEE.
- Environmental Management:Forest fire prevention and air quality improvement applications concentrate in ecologically sensitive watersheds with strict silver residue thresholds.
Agriculture retains the largest historical footprint. Drought Mitigation is gaining share fastest.
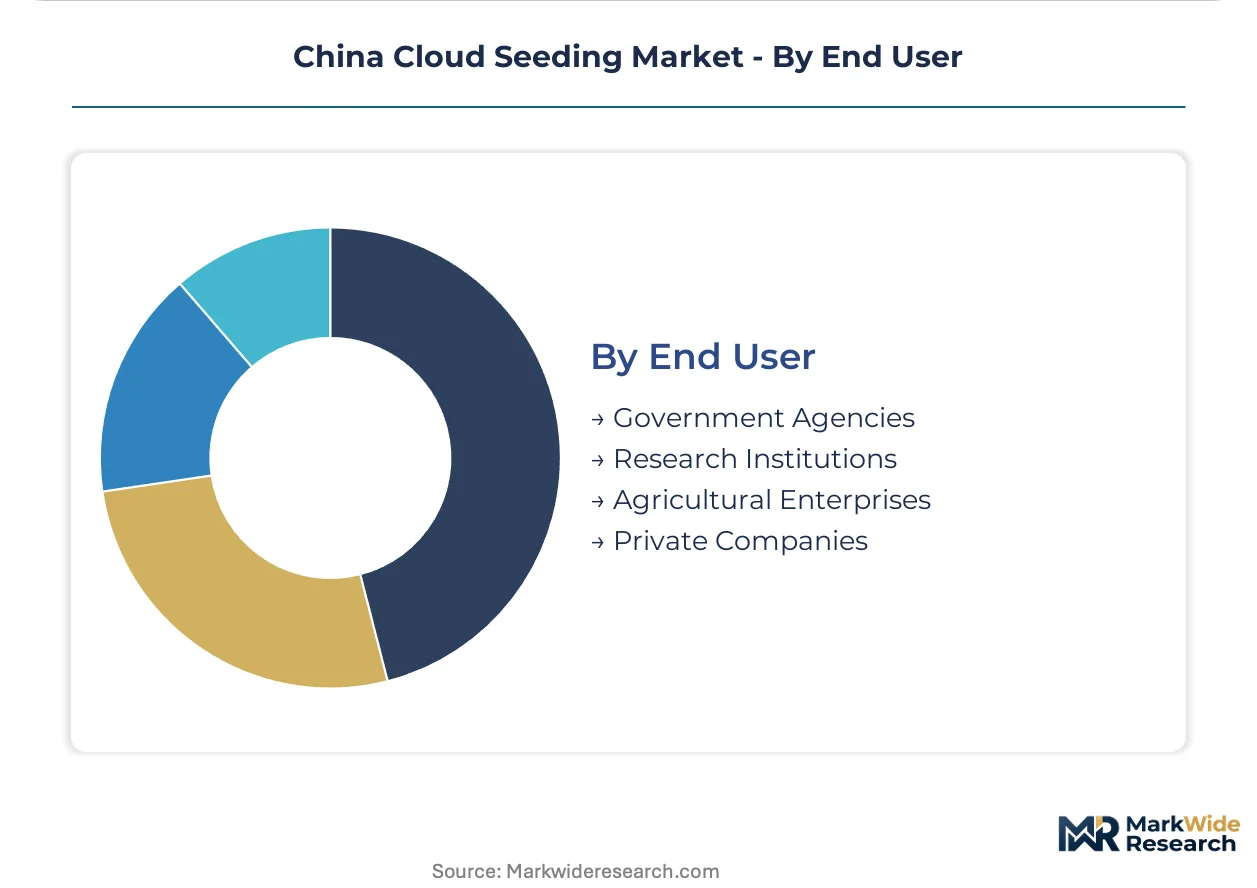
End User:
Contracting authority fragmentation is reshaping vendor access patterns across institutional buyer categories.
- Government Agencies:Provincial meteorological bureaus and county-level water authorities hold diverging procurement powers under evolving CMA decentralization policies. Direct county contracting is accelerating in mountainous terrain where autonomous systems outperform aircraft.
- Agricultural Enterprises:Large-scale farming cooperatives in the North China Plain are pooling resources for localized seeding operations outside traditional bureau channels.
- Research Institutions:CMA-affiliated institutes and university atmospheric physics departments concentrate mission planning expertise and cloud microphysics modeling capabilities.
- Private Companies:Equipment vendors and maintenance contractors serve the fragmented county-level deployment market with localized service agreements.
Government Agencies control institutional procurement. Agricultural Enterprises are where vendor diversification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The South-to-North Water Diversion Project's central route underwrites Hebei's emergence as the dominant procurement zone for aircraft-based seeding systems. Provincial water security infrastructure now channels operational budgets toward atmospheric water resource exploitation.
Hebei
Depleted groundwater reserves in the North China Plain compel reservoir-dependent municipalities to fund expanded flight-hour allocations. MEE water security directives mandate environmental impact assessments for each catchment area. Shijiazhuang operators pivot toward hygroscopic salt alternatives to maintain mission frequency under revised GB silver residue thresholds.
Henan
Wheat and corn irrigation stress drives seasonal demand spikes for precipitation augmentation services. CMA operational standards tighten flight safety protocols for provincial turboprop fleets. Zhengzhou meteorological bureaus adopt satellite-data fusion platforms to compress decision cycles from weather detection to seeding execution.
Shandong
Municipal water utilities emerge as direct purchasers of reservoir replenishment contracts outside traditional agricultural scheduling channels. Dual carbon compliance requirements restrict high-emission aircraft operations in favor of platform conversions. Jinan operators lead provincial adoption of algorithmic seeding window predictions replacing manual meteorologist assessments.
Jiangxi
Mountainous terrain constraints favor unmanned ground generator installations over aircraft-dependent operations. County-level water bureaus bypass provincial intermediaries to source autonomous systems with localized maintenance agreements. Nanchang manufacturers compete aggressively in remote-ignition generator production for county-level deployments.
Fujian
Orographic enhancement projects concentrate in coastal prefectures with specialized direct aerosol insertion requirements. Provincial meteorological bureaus decentralize contracting authority to accelerate deployment timelines in terrain-constrained counties. Fuzhou clusters develop satellite-triggered ignition capabilities for unmanned mountain installations.
China Cloud Seeding Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base organizes around three functional layers: mission planning service providers, equipment fabricators, and consumables suppliers. Two strategic archetypes dominate competitive positioning—CMA-affiliated institutes leveraging institutional authority and autonomous generator manufacturers exploiting county-level procurement fragmentation. Capacity expansion and technology licensing represent the dominant competitive moves as provincial bureaus demand integrated solution packages over standalone hardware.
Among state-affiliated research entities, Aerospace Information Research Institute and China National Aero-Meteorological Center occupy positions as platform integrators with satellite-data fusion capabilities. Jiangxi Gangsi exemplifies the component specialist archetype, anchoring the ground-based generator manufacturing tier with county-level deployment focus. These three entities collectively represent the bifurcation between institutional mission planning authority and decentralized equipment procurement channels reshaping vendor access patterns across provincial meteorological bureaus.
| Leading Market Players |
|---|
| China Meteorological Administration (CMA) |
| Aerospace Information Research Institute (AIR) |
| Jiangxi Gangsi |
| China National Aero-Meteorological Center |
| Weather Modification Inc. |
| RHS Consulting Inc. |
| North America Weather Consultants Inc. |
| Snowy Hydro Limited |
| Cloud Technologies GmbH |
| Others |
Pricing and Supply Chain Analysis
Silver iodide and hygroscopic salt suppliers in China's chemical manufacturing belt anchor upstream margin capture, while provincial meteorological bureaus and county water authorities downstream negotiate equipment procurement based on flight-hour volume commitments and maintenance bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CMA-certified aircraft systems with integrated mission planning from standalone ground generators and basic flare consumables. Price differentiation hinges on SAMR certification grade and after-sales service bundling. Cost compression in economy-tier consumables is intensifying because county-level direct contracting bypasses provincial intermediaries. County water bureaus in mountainous prefectures exhibit highest price sensitivity; municipal utilities in reservoir-dependent North China Plain cities show lowest sensitivity due to water security mandates.
Supply Chain Analysis
Contract manufacturing for seeding aircraft modifications concentrates at Aviation Industry Corporation of China facilities and provincial aerospace maintenance centers. Geographic supply concentration centers on China for silver iodide processing, ground generator fabrication, and avionics retrofitting. Raw material dependencies include silver nitrate feedstock, potassium iodide compounds, and specialized flare casings. Single-source vulnerability runs through CMA-affiliated training and certification channels. Distribution runs through provincial meteorological bureau procurement offices with growing direct-to-county fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's cloud seeding market rewards vendors who attach recurring mission planning and maintenance services to hardware sales, as satellite-data fusion subscriptions and localized maintenance contracts expand faster than aircraft and generator unit shipments.
For Market Incumbents: Pre-empt county-level procurement fragmentation by establishing direct service agreements with water bureaus in Jiangxi and Fujian before autonomous generator networks fully displace aircraft-dependent operations. Secure backward integration into silver iodide compound production to offset raw material cost volatility squeezing consumables margins. For New Entrants and Emerging Players: Unmanned ground generator installations in terrain-constrained western counties represent the most penetrable entry point, given bypass of CMA flight certification requirements and faster deployment timelines than aircraft systems. Hydrogen-powered seeding aircraft conversions for dual carbon compliance offer a second white-space target. Go-to-market leverage should center on satellite-triggered ignition technology partnerships with provincial meteorological bureaus adopting algorithmic mission planning. For Investors and Strategic Acquirers: Capital is best deployed toward mission planning software providers with CMA institutional relationships and proprietary cloud microphysics modeling capabilities, given long-term viability rests on data-driven operational differentiation rather than commoditized hardware fabrication. The signal to watch is MEE enforcement intensity on GB silver residue thresholds, which would accelerate hygroscopic salt substitution and reshape consumables supplier margins.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite-Data Fusion Platform Deployment | Shandong and Henan provincial bureaus replace manual meteorologist assessments with algorithmic seeding windows. |
| Autonomous Ground Generator Network Expansion | Jiangxi and Fujian county water bureaus source unmanned mountain installations with localized maintenance contracts. |
| Hydrogen-Powered Aircraft Conversion Program | Dual carbon compliance requirements in Shandong restrict high-emission turboprop operations. |
| Hygroscopic Salt Substitution Investment | Hebei operators pivot from silver iodide to maintain flight-hour quotas under tightened MEE residue thresholds. |
| Direct County-Level Service Agreement | Equipment vendors bypass provincial CMA intermediaries to capture fragmented procurement authority in mountainous terrain. |
Research Methodology
Desk research of CMA operational bulletins, provincial water security policy documents, and SAMR equipment certification records preceded structured interviews with provincial meteorological bureau directors, county water authority procurement officers, aircraft maintenance contractors, and atmospheric physics researchers at CMA-affiliated institutes. Secondary validation drew from Ministry of Ecology and Environment enforcement notices, China Meteorological Administration training protocols, and provincial budget appropriation disclosures. Bottom-up equipment deployment tallies triangulated against top-down provincial expenditure allocations.
Assumptions held fixed include continued MEE water security directive enforcement, CMA operational standard tightening, and dual carbon policy framework durability; varied assumptions tested SAMR certification timeline acceleration and county-level procurement decentralization pace. Segmentation modeling spanned technology modality, product type capital intensity, application urgency tier, and end-user contracting authority level. CAGRs derived from equipment replacement cycle analysis and flight-hour budget growth trajectories. Industry-specific forecast inputs incorporated reservoir replenishment contract expansion rates and autonomous generator network deployment timelines.
Macroeconomic conditions sit as an overlay; deviation in provincial fiscal transfer flows or jet fuel price volatility would shift the trajectory of aircraft-based seeding operations. Forecasts reflect assumptions on regulatory enforcement continuity and technology substitution elasticities. Quarterly review of CMA certification backlog indicators and MEE environmental impact assessment approval rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Solar Panel Recycling Management Market
Environment & Sustainability
Global Solar Water Desalination Plants Market
Environment & Sustainability
Global Automated Marine Debris Collection Equipment Market
Environment & Sustainability
Home Water Filtration Unit Market
Environment & Sustainability
Qatar Solid Waste Management Market
Environment & Sustainability
Sharp Waste Disposal Market
Environment & Sustainability
Water Quality Analyzer Market
Environment & Sustainability
Outdoor Flooring Market
Environment & Sustainability
Product Stewardship Market
Environment & Sustainability
Green Cement and Concrete Market
Environment & Sustainability
North America Municipal Solid Waste Management Market
Environment & Sustainability
Carbon Capture and Sequestration Market
Environment & Sustainability
Aluminum Cans Recycling Market
Environment & Sustainability
Environmental Technology Market
Environment & Sustainability
Waste Paper Management Market
Environment & Sustainability
North America Industrial Waste Management Market