
 Galectin Inhibitor Therapeutics Market | 2026-2036
Galectin Inhibitor Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Galectin Inhibitor Therapeutics Market Foresight
Oncology is decoupling from fibrosis as the dominant therapy area anchor, though both verticals retain substantial pipeline investment. Galectin Therapeutics Inc leverages its carbohydrate-based platform to sustain leadership in NASH and fibrotic indications. GlycoMimetics Inc anchors its position through specialized small molecule galectin-3 inhibitors with distinct binding kinetics. Pfizer Inc competes by extending its immuno-oncology franchise into galectin-1 checkpoint modulation, where it occupies early clinical territory.
Galectin inhibitor therapeutics are synthetic or biologic compounds that block galectin lectin proteins from binding β-galactoside sugars, thereby disrupting immune suppression, fibroblast activation, or tumor immune evasion pathways; these agents typically achieve nanomolar binding affinity through carbohydrate headgroup optimization or allosteric protein interface blockade. Monoclonal antibodies dominate current development pipelines due to their extended half-life and validated manufacturing scale, while small molecule inhibitors represent the fastest-expanding segment as oral bioavailability drives ambulatory care economics. Carbohydrate mimetics retain specialized positioning in research laboratory settings where precise glycan specificity determines experimental utility.
FDA breakthrough therapy designation and EMA PRIME eligibility for galectin-3 inhibitors in heart failure with preserved ejection fraction are reshaping regulatory expectations and trial design standards. The NIH and EMA jointly influence biomarker qualification requirements that determine market access pathways for fibrosis indications. Stakeholders must monitor how FDA oncology division guidance on immune-related adverse event profiling evolves for galectin-1 combination therapies, as this will determine which delivery modes and care settings receive priority reimbursement.
Market Dynamics
Accelerated FDA breakthrough therapy designations for galectin-3 inhibitors in cardiovascular and fibrotic indications are compressing Phase II-to-approval timelines from the traditional ten-year horizon toward six-to-seven year trajectories, fundamentally restructuring capital deployment patterns across development-stage portfolios.
Growth Catalysts
- NIH Immuno-Oncology Consortia:Federally funded research networks in the United States are de-risking early-phase galectin-1 combination trials through shared biomarker infrastructure and centralized patient registries.
- EMA PRIME Eligibility:Priority medicines designation for heart failure with preserved ejection fraction candidates is compressing regulatory review timelines and attracting European institutional investment.
- Academic Medical Center Expansion:Oncology departments at major university hospitals are building dedicated galectin-targeted trial units with integrated carbohydrate chemistry laboratories.
Market Restraints
- Carbohydrate Synthesis Cost Structure:Complex stereospecific glycosylation steps in galectin-binding headgroup production create 40-60% raw material cost premiums versus standard small molecule APIs.
- Specialized CMO Concentration:Contract manufacturing for carbohydrate-based biologics clusters in Switzerland and Germany, creating single-source vulnerability for Phase III supply security.
- Biomarker Qualification Delays:FDA and EMA discordance on galectin-3 serum assay standardization is extending pivotal trial enrollment periods by 12-18 months.
Strategic Opportunities
- Japan's Geriatric Fibrosis Burden:METI-targeted aging-related disease initiatives are creating fast-track reimbursement pathways for galectin-3 inhibitors in idiopathic pulmonary fibrosis.
- Oral Small Molecule Convergence:Ambulatory administration of galectin-3 inhibitors is displacing infusion-dependent monoclonal antibodies in community oncology settings.
- Companion Diagnostic Integration:Galectin expression profiling in solid tumor biopsies is enabling precision patient selection for combination checkpoint trials.
Industry Challenges
- Glycobiology Talent Scarcity:Carbohydrate medicinal chemistry expertise concentrates at fewer than twelve academic programs globally, constraining R&D team scaling.
- Multi-Region Trial Complexity:Divergent FDA and EMA requirements for immune-related adverse event monitoring in galectin-1 combinations is forcing parallel protocol designs.
- Legacy Assay Standardization:Preclinical galectin binding assays lack cross-laboratory validation, creating translational reliability gaps between discovery and clinical pharmacology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galectin Inhibitor Therapeutics Market |
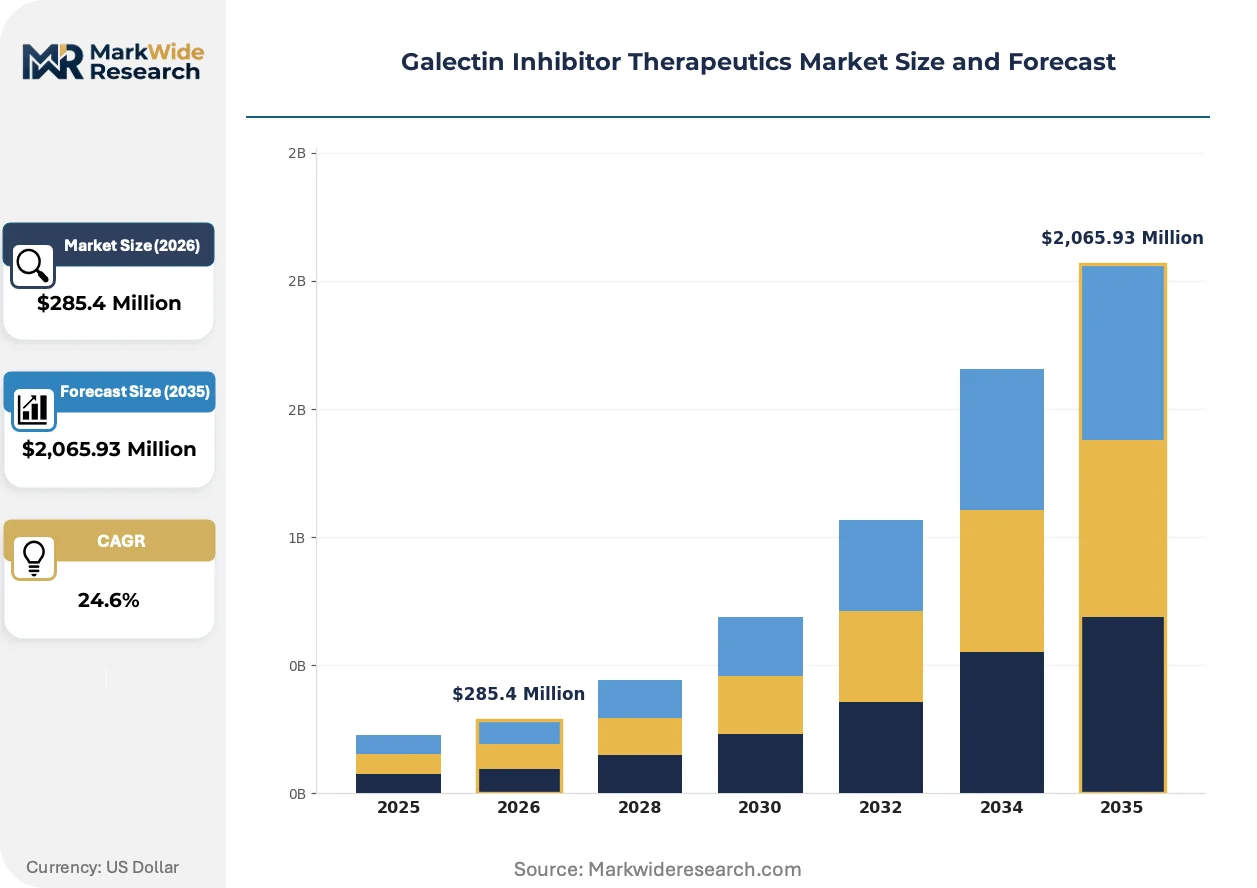
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,065.93 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecule Inhibitors, Monoclonal Antibodies, Carbohydrate Mimetics, Peptide-Based Inhibitors, Aptamers Therapy Area: Oncology, Fibrosis, Immunological Disorders, Infectious Diseases, Metabolic Disorders Care Setting: Hospitals, Specialty Clinics, Research Laboratories, Ambulatory Care Centers, Academic Institutions Delivery Mode: Oral, Intravenous, Subcutaneous, Inhalation, Transdermal |
| Companies Covered | Galectin Therapeutics Inc, GlycoMimetics Inc, Galecto Biotech, MandalMed Inc, G3 Pharmaceuticals, Angion, iTeos Therapeutics, Novartis AG, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galectin Inhibitor Therapeutics Market Shifts & Advancements
Galectin inhibitor development is pivoting from carbohydrate mimetics toward allosteric small molecules and bispecific antibody architectures, driven by pharmacokinetic limitations of glycan-based scaffolds and the therapeutic imperative for tissue penetration in solid tumors.
Bispecific antibody platforms are modularizing galectin-1 checkpoint modulation by combining lectin blockade with PD-1 or LAG-3 targeting in single constructs. Bristol Myers Squibb and Genentech are advancing these formats into Phase I trials with accelerated dose-escalation designs. This architecture is compressing development timelines by enabling simultaneous validation of two mechanistic hypotheses in one clinical program.
REACH registration requirements for novel carbohydrate-containing biologics are mandating expanded environmental fate studies for manufacturing effluents. ECHA guidance on glycan persistence in aquatic systems is forcing CMOs to install specialized wastewater treatment for oligosaccharide synthesis steps. European manufacturing sites are responding by consolidating production in Belgium and the Netherlands where integrated chemical-pharma industrial parks offer shared environmental compliance infrastructure.
Academic medical centers are consolidating procurement of galectin-targeted investigational compounds through centralized NIH-funded compound libraries rather than bilateral sponsor negotiations. This channel shift is displacing traditional business development outreach for early-phase assets. The concentration is most visible in the United States, where the National Cancer Institute's Developmental Therapeutics Program now catalogs over forty galectin modulators available for cooperative research and development agreements.
Galectin Inhibitor Therapeutics Market Segmentation
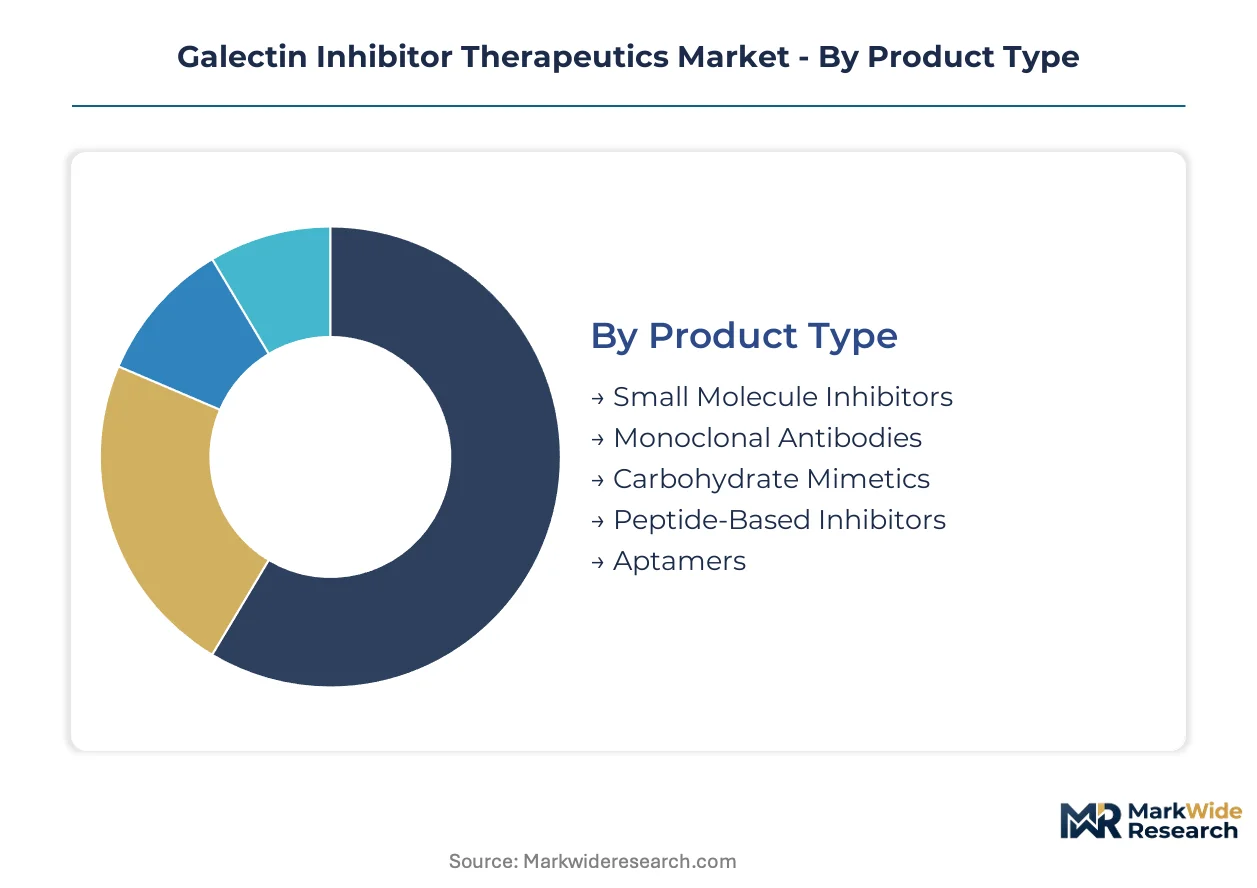
Galectin inhibitor development traverses multiple technological platforms and clinical environments, each imposing distinct manufacturing, regulatory, and reimbursement requirements. Buyers—whether hospital pharmacy directors, specialty clinic administrators, or principal investigators—evaluate segments through divergent lenses of bioavailability, assay compatibility, and care setting economics.
Product Type:
Development-stage biopharma companies select platforms based on half-life requirements, tissue penetration targets, and CMO availability rather than molecular elegance alone.
- Monoclonal Antibodies:Extended circulating half-life and validated GMP manufacturing infrastructure position these agents for chronic fibrotic indications requiring sustained galectin-3 suppression. Demand concentrates at academic medical centers in the United States where NIH-funded consortia underwrite infusion capacity for immuno-oncology combinations.
- Small Molecule Inhibitors:Oral bioavailability and ambulatory administration economics are displacing infusion-dependent formats in community oncology settings. Allosteric binding kinetics at the galectin carbohydrate recognition domain enable tissue penetration in solid tumors where glycan-based scaffolds fail.
- Carbohydrate Mimetics:Specialized glycan specificity determines experimental utility in research laboratory settings.
- Peptide-Based Inhibitors:Intermediate properties between small molecules and biologics attract niche development programs.
- Aptamers:Nucleic acid scaffolds offer rapid optimization cycles for target validation studies.
Volume sits with monoclonal antibodies; growth tilts toward small molecule inhibitors.
Therapy Area:
Regulatory pathway designations and biomarker qualification status determine capital allocation across disease verticals.
- Oncology:Galectin-1 checkpoint modulation addresses tumor immune evasion through disruption of T-cell exhaustion programs. FDA breakthrough therapy designations for combination trials with PD-1 inhibitors are compressing Phase II-to-approval timelines at major cancer centers.
- Fibrosis:NASH, idiopathic pulmonary fibrosis, and heart failure with preserved ejection fraction drive galectin-3 serum assay development. EMA PRIME eligibility for cardiovascular indications is attracting European institutional investment into late-stage programs.
- Immunological Disorders:Autoimmune applications exploit galectin-mediated immune suppression mechanisms.
- Infectious Diseases:Viral entry inhibition through galectin blockade remains preclinical.
- Metabolic Disorders:Diabetic nephropathy and non-alcoholic steatohepatitis overlap with fibrosis pipelines.
Revenue concentrates in oncology; expansion accelerates fastest in fibrosis indications.
Care Setting:
Procurement authority and reimbursement mechanics fragment demand across institutional categories with incompatible purchasing workflows.
- Hospitals:Integrated pharmacy and therapeutics committees govern formulary placement for intravenous galectin inhibitors. 340B pricing exposure and bundled payment models shape contract negotiations for immuno-oncology combinations.
- Specialty Clinics:Focused infusion centers in hepatology and cardiology manage fibrotic disease populations on oral small molecule regimens.
- Research Laboratories:NIH-funded carbohydrate chemistry facilities at academic medical centers procure carbohydrate mimetics for mechanistic studies.
- Ambulatory Care Centers:Community oncology networks favor oral administration for patient convenience.
- Academic Institutions:Principal investigators access centralized compound libraries through cooperative research agreements.
Procurement volume clusters at hospitals; patient volume growth shifts toward specialty clinics.
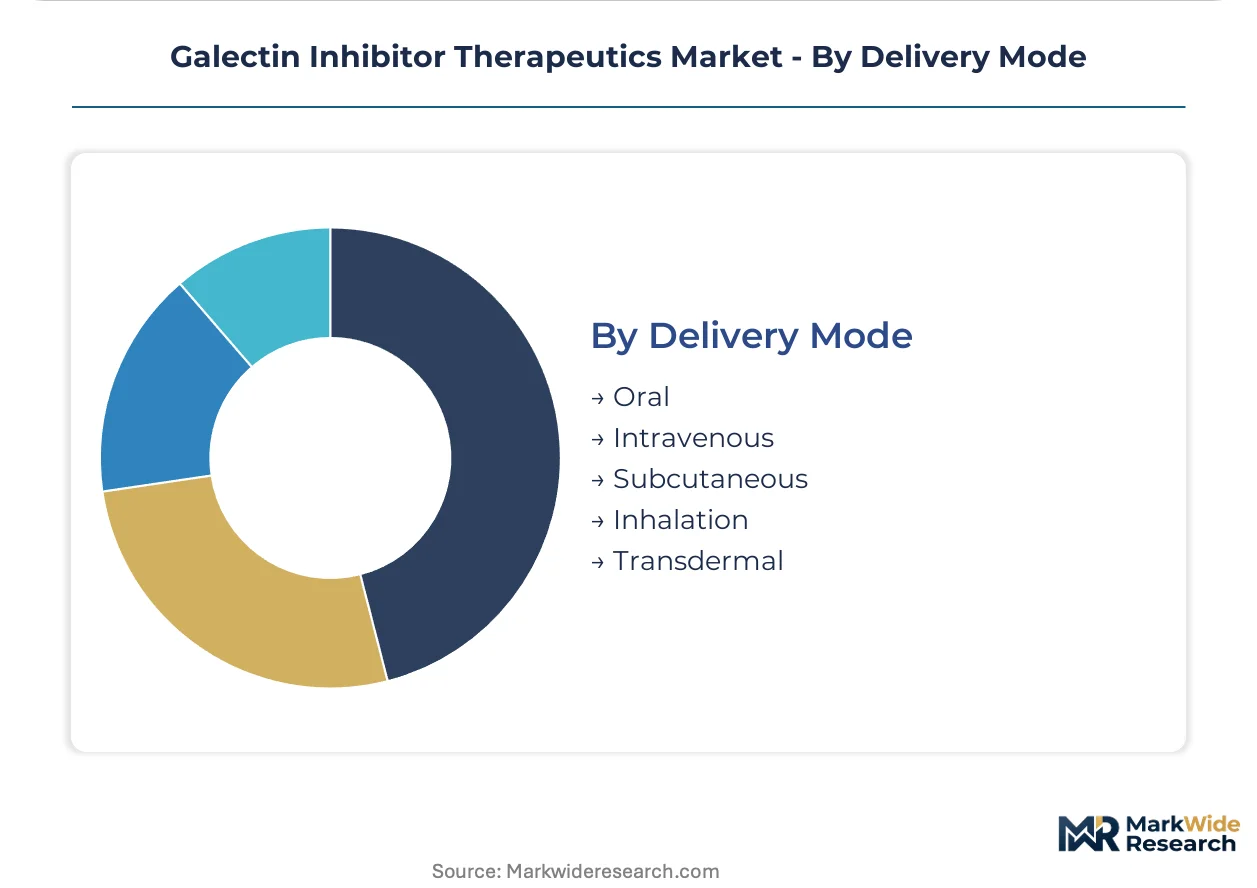
Delivery Mode:
Route selection determines CMO specialization requirements, cold chain infrastructure, and adverse event monitoring protocols.
- Intravenous:Hospital-based administration enables close immune-related adverse event monitoring for galectin-1 combination therapies. FDA oncology division guidance on infusion reaction profiling shapes protocol designs at major cancer centers.
- Oral:Ambulatory administration economics support community oncology expansion and patient adherence in chronic fibrotic diseases.
- Subcutaneous:Self-administration potential attracts development for maintenance therapy in immunological disorders.
- Inhalation:Pulmonary delivery targets idiopathic pulmonary fibrosis with localized galectin-3 suppression.
- Transdermal:Novel formulations for peptide-based inhibitors remain experimental.
Installed base favors intravenous delivery; pipeline investment flows toward oral formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina and comparable biopharma clusters concentrate galectin inhibitor development through NIH-funded infrastructure and specialized CMO networks.
United States
NIH immuno-oncology consortia de-risk early-phase galectin-1 combination trials through shared biomarker infrastructure. FDA breakthrough therapy designations for cardiovascular indications compress regulatory timelines. Boston and San Francisco academic medical centers host dedicated galectin-targeted trial units with integrated carbohydrate chemistry laboratories.
Germany
EMA PRIME eligibility for heart failure candidates attracts institutional investment into late-stage programs. ECHA REACH requirements for carbohydrate-containing biologics mandate expanded environmental fate studies. Heidelberg and Munich clusters consolidate production in integrated chemical-pharma industrial parks with shared compliance infrastructure.
Switzerland
Contract manufacturing for carbohydrate-based biologics clusters around Basel and Zurich, creating specialized supply nodes for Phase III security. Swissmedic alignment with EMA accelerated pathways streamlines multi-region trial submissions. The Basel industrial park hosts concentrated glycobiology talent pools for R&D team scaling.
Japan
METI-targeted aging-related disease initiatives create fast-track reimbursement pathways for galectin-3 inhibitors in idiopathic pulmonary fibrosis. PMDA consultation programs compress pre-submission review periods. Tokyo and Osaka academic centers expand procurement through centralized compound libraries rather than bilateral negotiations.
United Kingdom
MHRA post-Brexit regulatory autonomy enables adaptive licensing pilots for galectin-targeted therapies. London and Cambridge biotech corridors attract venture capital through proximity to European trial infrastructure. The Francis Crick Institute catalogs galectin modulators for cooperative research agreements with sponsors.
Galectin Inhibitor Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform technology holders commanding premium positions in fibrosis while immuno-oncology franchises compete through checkpoint combination rights. The structure concentrates around three archetypes: carbohydrate-based platform developers, small molecule specialists with allosteric binding kinetics, and diversified biopharma extending immuno-oncology pipelines. Dominant competitive moves include strategic partnerships for biomarker co-development and capacity reservations at specialized CMOs for carbohydrate synthesis.
Within the platform technology tier, Galectin Therapeutics Inc and GlycoMimetics Inc exemplify divergent approaches to galectin blockade, with the former representing carbohydrate-based scaffold development and the latter occupying specialized small molecule positioning. Pfizer Inc anchors the diversified biopharma archetype, extending established immuno-oncology infrastructure into galectin-1 checkpoint modulation. These three entities collectively illustrate how molecular platform selection determines competitive territory in this market.
| Leading Market Players |
|---|
| Galectin Therapeutics Inc |
| GlycoMimetics Inc |
| Galecto Biotech |
| MandalMed Inc |
| G3 Pharmaceuticals |
| Angion |
| iTeos Therapeutics |
| Novartis AG |
| Pfizer Inc |
| Others |
Supply & Pricing Matrix
Carbohydrate synthesis complexity bifurcates galectin inhibitor supply into premium biologic tiers and commoditized small molecule alternatives, with stereospecific glycosylation steps commanding 40-60% raw material cost premiums that concentrate pricing power at Swiss and German CMOs while oral formulation development erodes infusion-dependent margins.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent Phase III supply reservations at Basel-based carbohydrate specialists from spot procurement of research-grade carbohydrate mimetics through NIH compound libraries. Three-tier pricing structure across premium GMP-certified biologics, standard small molecules, and economy research reagents reflects FDA breakthrough therapy designation urgency versus academic laboratory budget constraints. Cost compression in monoclonal antibody manufacturing intensifies as oral small molecule galectin-3 inhibitors displace infusion formats in community oncology. Hospital pharmacy directors exhibit highest price sensitivity for chronic fibrotic indications requiring sustained administration, while immuno-oncology trial sponsors absorb premium pricing for accelerated enrollment timelines.
Supply Chain Analysis
Stereochemically pure galactose derivatives rest on Swiss and German specialty chemical producers with validated GMP carbohydrate synthesis infrastructure. Raw material dependencies span protected sugar precursors, specialized glycosyltransferase enzymes, and single-use bioreactor systems. Single-source vulnerability clusters around Basel and Zurich CMO nodes, where REACH-mandated environmental fate studies for glycan manufacturing effluents constrain capacity expansion. Distribution runs through academic medical center procurement committees for clinical trial materials and centralized NIH compound libraries for research-grade access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA PRIME eligibility and FDA breakthrough therapy designation create a cost-of-compliance moat that rewards players with established regulatory affairs infrastructure and biomarker co-development capabilities.
For Market Incumbents: Anticipate carbohydrate synthesis cost inflation by securing capacity reservations at Swiss CMOs before REACH environmental compliance investments price out mid-tier competitors. Backward integration into protected sugar precursor supply insulates margin compression from single-source raw material dependencies. Prioritize biomarker assay standardization partnerships with FDA and EMA to preempt 12-18 month enrollment delays from discordant regulatory requirements. For New Entrants and Emerging Players: Launch via oral small molecule platforms targeting Japan's METI fast-track reimbursement pathways for idiopathic pulmonary fibrosis, where geriatric disease burden outpaces domestic development capacity. Community oncology ambulatory settings represent the most penetrable care environment, displacing infusion-dependent monoclonal antibodies through patient convenience economics. Pursue cooperative research agreements with NIH Developmental Therapeutics Program compound libraries to bypass bilateral sponsor negotiation barriers. For Investors and Strategic Acquirers: Re-rating potential sits with allosteric small molecule specialists given oral bioavailability convergence in fibrosis indications and checkpoint modulation expansion. Long-term viability hinges on 5-10 year regulatory pathway durability across cardiovascular, oncologic, and immunologic verticals. Acquisition target archetype: development-stage platforms with validated galectin-3 serum assay partnerships and EMA PRIME-eligible cardiovascular candidates. Watch FDA oncology division guidance evolution on immune-related adverse event profiling for galectin-1 combination therapies as inflection indicator for reimbursement priority settings.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Co-Development Partnership | FDA and EMA assay standardization alignment compresses pivotal trial enrollment timelines by resolving regulatory discordance. |
| CMO Capacity Reservation | Swiss and German carbohydrate synthesis slot commitments secure Phase III supply against REACH compliance-driven capacity constraints. |
| Oral Formulation Pipeline Pivot | Ambulatory administration economics displace infusion-dependent formats in community oncology and chronic fibrotic disease management. |
| Companion Diagnostic Integration | Galectin expression profiling in solid tumor biopsies enables precision patient selection for combination checkpoint trials. |
| Academic Medical Center Procurement Consolidation | NIH compound library cooperative agreements displace bilateral sponsor negotiations for early-phase asset access. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving drug development executives at galectin-targeted biopharma sponsors, regulatory affairs leads navigating FDA breakthrough therapy and EMA PRIME pathways, hospital formulary directors managing immuno-oncology procurement, and payer access specialists evaluating fibrotic disease reimbursement. FDA submission databases, EMA assessment reports, ClinicalTrials.gov protocol registries, and NIH RePORTER funding disclosures supplied quantitative pipeline tracking. Bottom-up project-level enumeration and top-down therapeutic category sizing underwent iterative reconciliation.
Data-stream reconciliation across product type, therapy area, care setting, and delivery mode segmentation dimensions generated volume and value outputs across the projection horizon. CAGRs derived from fitted growth curves applied to developmental-stage asset probability-adjusted revenue forecasts, incorporating clinical trial advancement rates, regulatory pathway designation frequencies, and biomarker qualification timelines specific to galectin inhibitor mechanisms.
Regulatory guidance revision, biomarker assay standardization failure, and carbohydrate synthesis cost inflation are the dominant revision risks to modeled outputs. Forecasts embed assumptions regarding EMA-FDA convergence on immune-related adverse event monitoring protocols. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Balantidiasis Market
Medical Biotechnology
Leprosy Vaccines Market
Medical Biotechnology
Antisense Therapy Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Global Stem Cells Market
Medical Biotechnology
Smart Drug Discovery Market
Medical Biotechnology
Insulinoma Market
Medical Biotechnology
Immortalized Cell Line Market
Medical Biotechnology
AI for Drug Discovery Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Targeted Cancer Drugs Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Insulin Management System Market
Medical Biotechnology
Clarithromycin Market