
 Adapalene Products Market | 2026-2036
Adapalene Products Market Size, Share, and Industry Trends Forecast 2026-2036
Adapalene Products Market Insights
China is fragmenting adapalene manufacturing capacity as domestic API producers scale retinoid synthesis operations. Galderma leverages its integrated dermatology platform to sustain brand loyalty across prescription and cosmetic channels. Teva Pharmaceutical Industries anchors the generic adapalene segment through cost-optimized production and broad pharmacy distribution. Sun Pharmaceutical Industries competes in emerging markets with localized manufacturing and regulatory filing expertise.
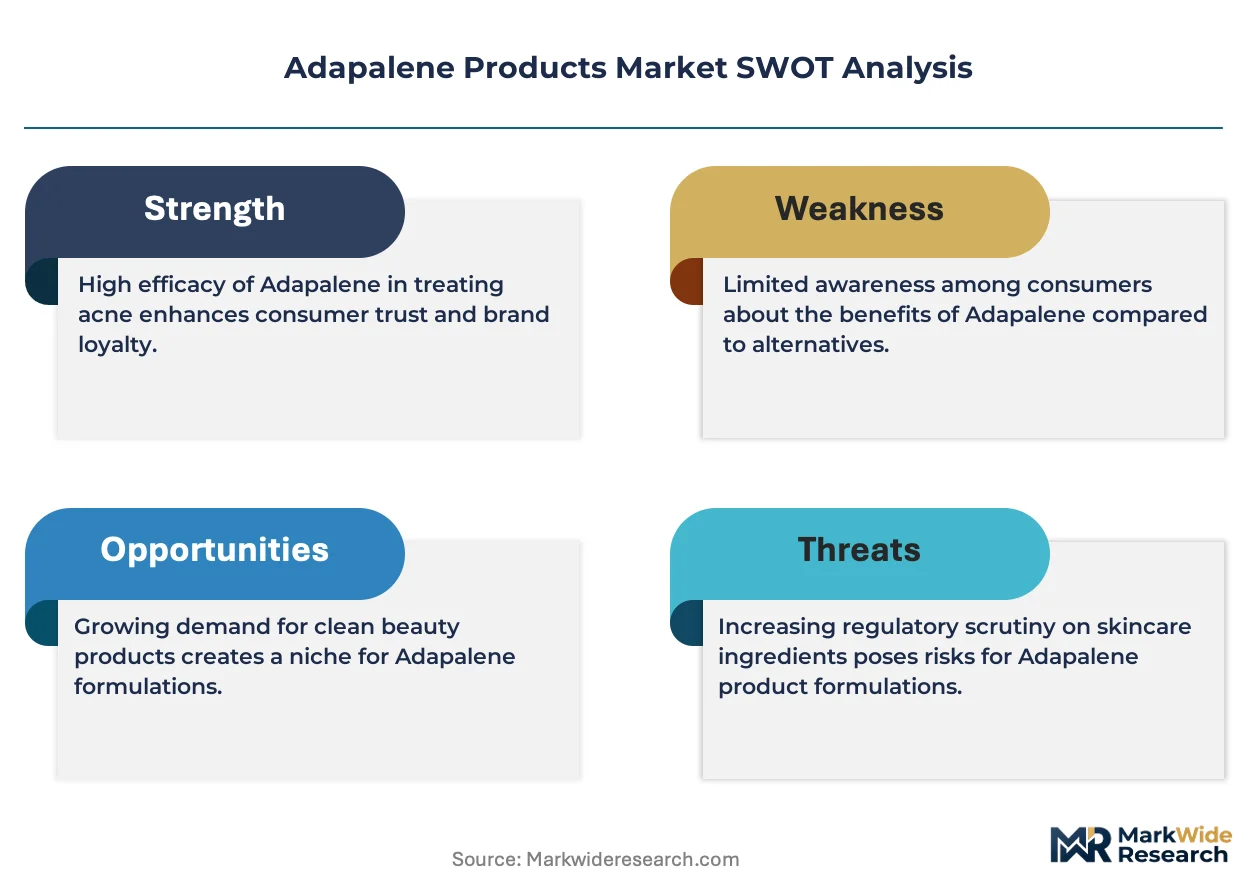
Adapalene is a third-generation synthetic retinoid, chemically classified as a naphthoic acid derivative with selective retinoic acid receptor beta and gamma agonism, manufactured through multi-step organic synthesis involving naphthalene ring modification and carboxylic acid functionalization. It primarily functions as a comedolytic and anti-inflammatory agent for acne vulgaris and photoaging management. Gels dominate prescription volumes due to superior patient tolerability and faster epidermal penetration, while creams capture expanding over-the-counter demand through milder moisturizing bases. Home care channels represent the fastest-growing end-user segment as telehealth prescribing and direct-to-consumer platforms bypass traditional clinic gatekeeping.
The US FDA governs adapalene concentration limits and pregnancy labeling requirements, while the EMA's REACH framework and the EU Green Deal chemical sustainability mandates constrain European manufacturing inputs and packaging specifications. India's CDSCO aligns bioequivalence standards with WHO prequalification criteria, enabling export-oriented production from Hyderabad and Ahmedabad clusters. Stakeholders must monitor evolving retinoid classification debates between cosmetic and pharmaceutical regulators that could reshape channel access and formulation investment priorities.
Market Dynamics
The adapalene market pivots on the FDA's retinoid safety labeling review, which is compressing formulation timelines and forcing manufacturers to recalibrate clinical trial endpoints across both prescription and cosmetic channels.
Growth Catalysts
- Telehealth prescribing expansion:Direct-to-consumer platforms bypass traditional dermatology gatekeeping, accelerating patient access to adapalene therapies in the United States.
- REACH chemical sustainability mandates:The EU Green Deal framework pushes manufacturers toward greener synthesis pathways, creating first-mover advantages for retinoid producers with certified green chemistry credentials.
- Photoaging protocol adoption:Dermatology clinics in South Korea and Japan integrate adapalene into combination anti-aging regimens, expanding the addressable patient population beyond acne vulgaris.
Market Restraints
- API supply concentration:Domestic Chinese producers control naphthoic acid derivative synthesis capacity, exposing formulation houses to input volatility from the Yangtze River Delta manufacturing clusters.
- Pregnancy category X classification:The FDA's teratogenicity labeling restricts prescribing to women of childbearing potential, compressing the eligible patient pool for dermatology practices.
- Benzoyl peroxide combination substitution:Fixed-dose adapalene-benzoyl peroxide gels displace monotherapy prescriptions in managed care formularies, eroding standalone product volumes.
Strategic Opportunities
- Brazilian dermocosmetic channel:ANVISA's streamlined OTC classification for low-concentration retinoids enables pharmacy-direct distribution without prescription barriers in Latin America's largest dermatology market.
- Microencapsulation technology convergence:Liposomal delivery systems paired with adapalene reduce irritation profiles, opening pediatric and sensitive-skin segments previously excluded from retinoid therapy.
- India PLI scheme alignment:The country's production-linked incentive framework for active pharmaceutical ingredients subsidizes domestic retinoid synthesis, positioning Hyderabad and Ahmedabad clusters for export-oriented scale.
Industry Challenges
- Bioequivalence study complexity:CDSCO and WHO prequalification criteria demand extended clinical endpoint trials for generic adapalene approvals, stretching R&D timelines for emerging market entrants.
- Retinoid classification ambiguity:Cosmetic-pharmaceutical boundary disputes between national regulators create channel access uncertainty, forcing dual-track formulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adapalene Products Market |
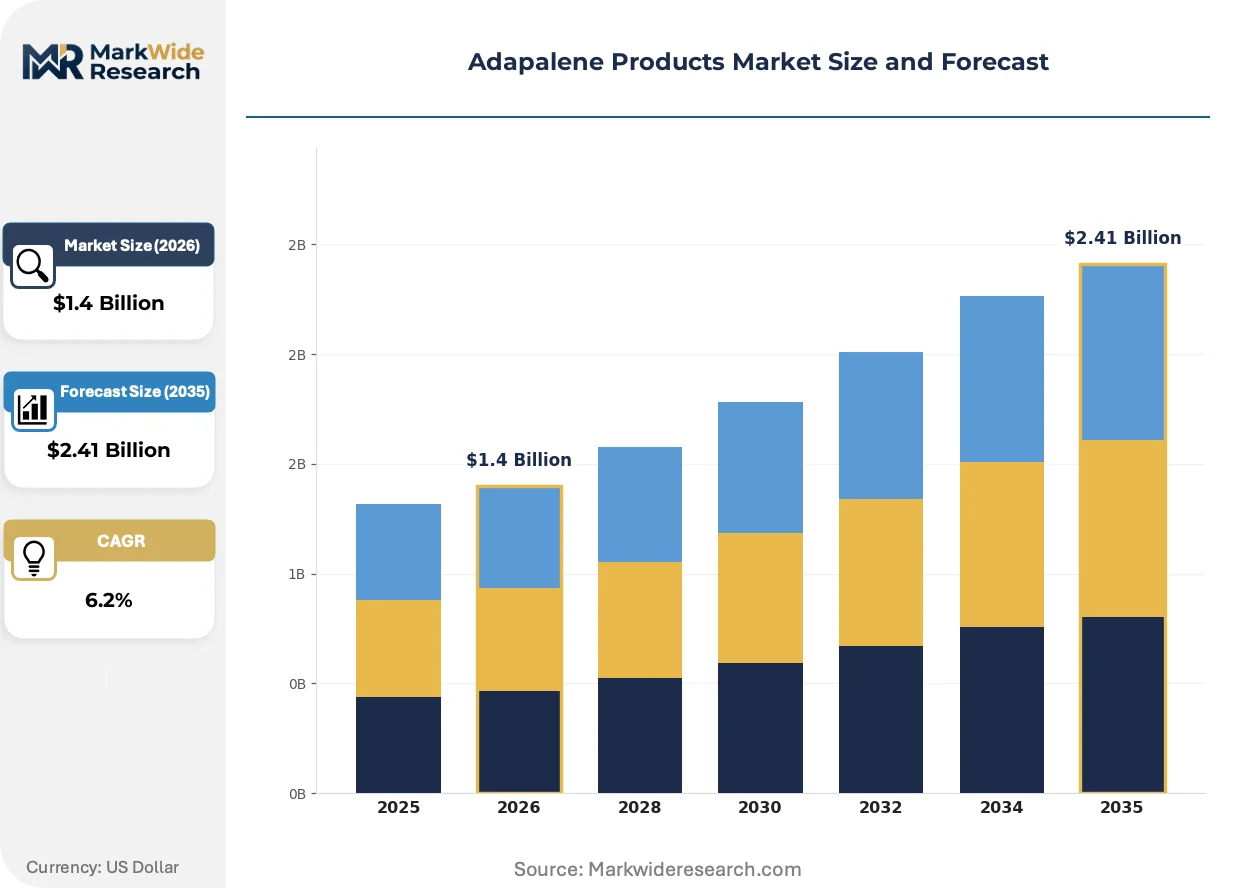
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gels, Creams, Solutions, Lotions Application: Acne Treatment, Skin Tone Improvement, Wrinkle Reduction, Psoriasis End User: Dermatology Clinics, Hospitals, Pharmacies, Home Care Packaging Type: Tube, Jar, Bottle, Packet |
| Companies Covered | Galderma, Teva Pharmaceutical Industries, Bausch Health, Johnson & Johnson, Sandoz, Sun Pharmaceutical Industries, Mylan, Zydus Cadila, Almirall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adapalene Products Market Trends and Innovations
Formulation science and regulatory arbitrage are converging to reshape how adapalene reaches patients, with delivery mechanisms and channel strategies evolving faster than clinical indication expansion.
Microencapsulated adapalene systems is hybridizing topical retinoid therapy by embedding active molecules in lipid bilayers that release upon epidermal contact. Compounding pharmacies and boutique skincare manufacturers in Germany and Switzerland adopt these systems for customized patient formulations. This convergence is compressing the tolerability gap between prescription-strength and cosmetic-grade retinoids, enabling concentration flexibility previously locked behind regulatory barriers.
EMA's MDR and CSRD disclosure requirements now mandate supply chain transparency for cosmetic-grade retinoid ingredients sold into European Union markets. Manufacturers must document naphthalene derivative sourcing and environmental impact across tier-two and tier-three suppliers. Mid-sized formulation houses in Italy and Spain face the steepest compliance costs, accelerating consolidation toward integrated producers with captive API capabilities.
Subscription-based skincare platforms disintermediate traditional pharmacy and clinic channels for adapalene distribution in the United States. Patients receive algorithm-matched concentration titrations through direct mail, with teledermatology oversight replacing in-person consultations. This model concentrates most rapidly among urban millennials seeking acne management without insurance formularies, forcing legacy dermatology practices to unbundle consultation fees from product dispensing.
Adapalene Products Market Segmentation
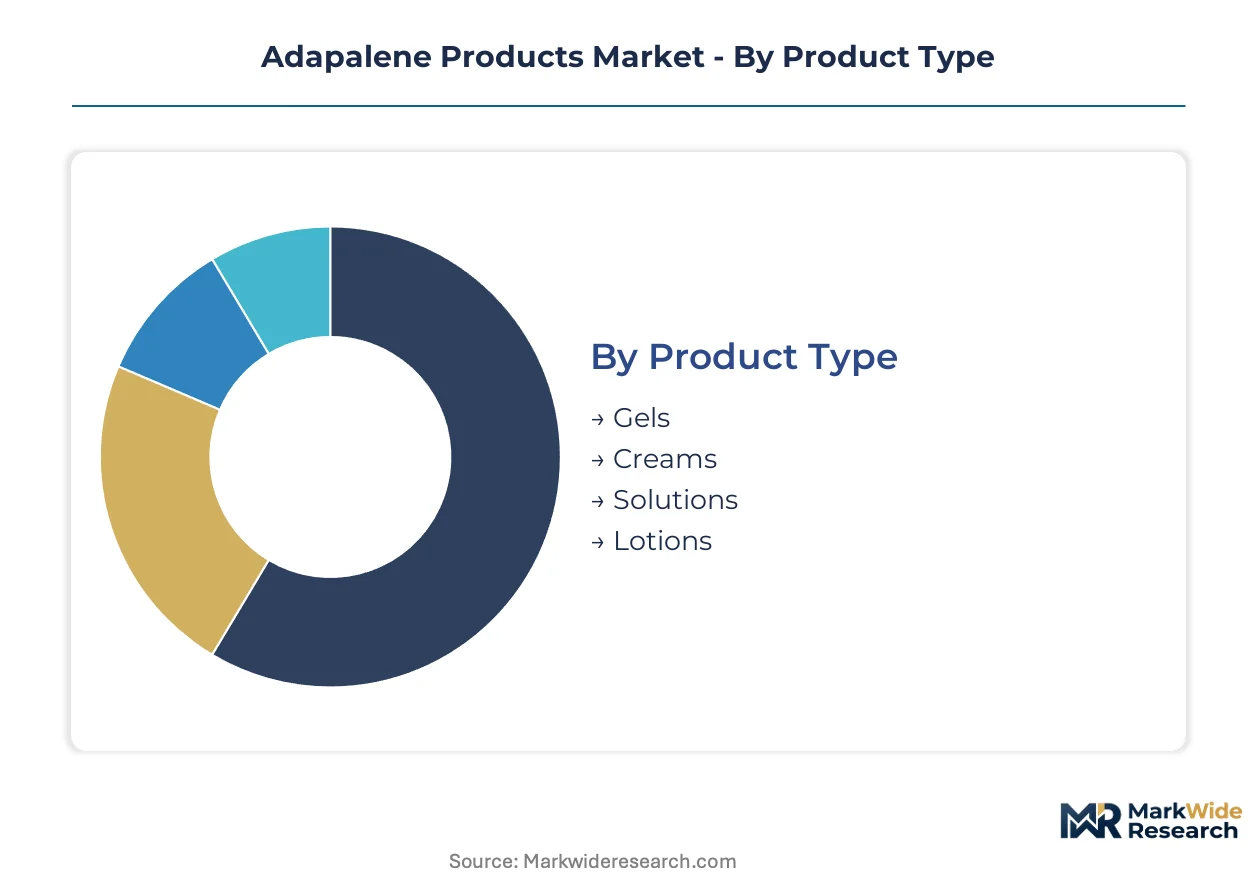
Adapalene product differentiation hinges on formulation chemistry, clinical indication, and channel access. Each segmentation dimension carries distinct regulatory pathways and margin structures that shape competitive positioning across prescription and cosmetic markets.
Product Type:
Formulation vehicle determines epidermal penetration kinetics, patient tolerability thresholds, and regulatory classification boundaries.
- Gels:Water-based matrices with alcoholic co-solvents achieve rapid stratum corneum penetration for acne vulgaris protocols. Prescription volumes concentrate in United States dermatology clinics where managed care formularies prioritize proven bioequivalence.
- Creams:Emulsion systems incorporating humectants and occlusive agents reduce transepidermal water loss, enabling daily tolerability for photoaging regimens. Over-the-counter demand in South Korean and Japanese direct-to-consumer channels drives expansion beyond clinical settings.
- Solutions:Hydroalcoholic vehicles suit scalp and hairline applications where residue-free application matters.
- Lotions:Lower viscosity emulsions target larger surface area coverage for trunk and back acne presentations.
Gels command the established base. The steepest expansion runs through creams as cosmetic-grade concentrations gain pharmacy-direct access.
Application:
Clinical indication breadth determines prescriber specialty, reimbursement coding, and combination therapy compatibility.
- Acne Treatment:Comedolytic and anti-inflammatory mechanisms target follicular hyperkeratinization in mild-to-moderate vulgaris cases. United States telehealth platforms now originate prescriptions without in-person dermatology consultations, compressing traditional clinic gatekeeping.
- Skin Tone Improvement:Melanin dispersion effects from retinoid-induced epidermal turnover address post-inflammatory hyperpigmentation. Brazilian dermocosmetic channels under ANVISA's streamlined OTC framework bypass prescription requirements for low-concentration formulations.
- Wrinkle Reduction:Collagen synthesis stimulation from RAR-gamma agonism supports anti-aging protocols in Japanese and South Korean aesthetic clinics.
- Psoriasis:Keratinocyte differentiation normalization offers adjunctive therapy for plaque management in hospital-based dermatology units.
Acne treatment anchors volume. Skin tone improvement gains share fastest as pigmentation concerns drive pharmacy-direct purchasing in tropical markets.
End User:
Channel configuration determines patient access economics, clinical oversight intensity, and formulation concentration availability.
- Home Care:Algorithm-matched subscription platforms in the United States deliver concentration-titrated regimens through direct mail with asynchronous teledermatology oversight. Urban millennial demographics bypass insurance formularies entirely.
- Dermatology Clinics:In-person consultation enables combination protocol design with benzoyl peroxide and topical antibiotics. South Korean clinic networks integrate adapalene into multi-step aesthetic regimens.
- Hospitals:Inpatient dermatology services manage severe acne fulminans and medication-resistant presentations.
- Pharmacies:Brazilian and Indian retail channels dispense OTC-classified concentrations without prescription barriers.
Dermatology clinics retain the high-value prescription base. Home care channels climb the fastest as platform economics disintermediate traditional distribution.
Packaging Type:
Primary container format shapes dosing precision, oxidation protection, and patient compliance monitoring.
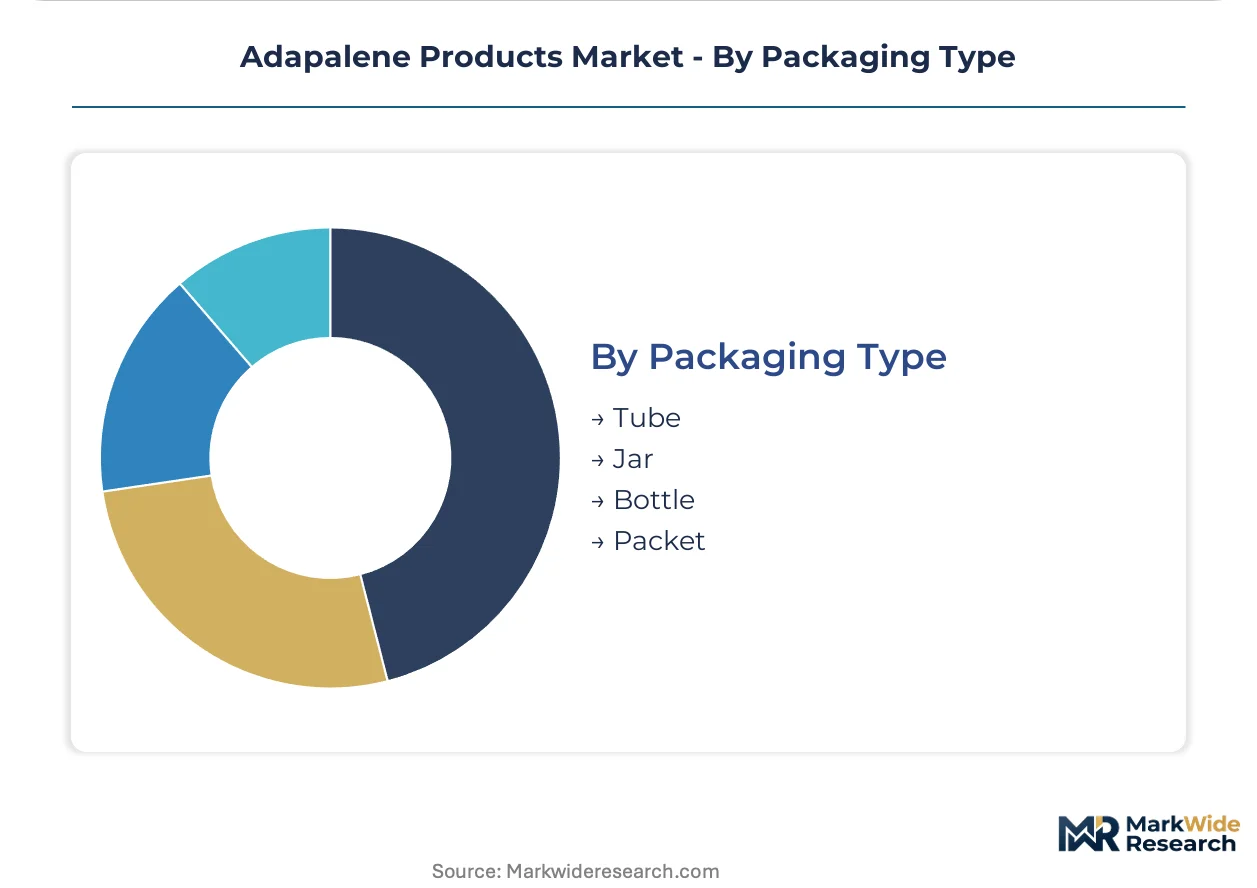
- Tube:Collapsible aluminum-laminate structures with narrow orifice dispensers protect photosensitive retinoid from air exposure. European EMA packaging specifications mandate recyclability disclosures under CSRD supply chain transparency rules.
- Jar:Wide-mouth containers suit cream-based cosmetic-grade products where finger-application dominates Japanese and South Korean skincare routines.
- Bottle:Pump-dispense systems for solution formulations enable measured dosing in hospital and clinic settings.
- Packet:Single-use sachets support trial sampling and travel-size compliance in Indian pharmacy channels.
Tube formats dominate prescription volumes. Packet configurations expand most quickly as emerging market sampling strategies accelerate patient initiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adapalene consumption patterns diverge sharply across geographies. The United States favors prescription-strength gels through managed care channels, while Asian markets embrace cosmetic-grade creams via direct-to-consumer platforms. European demand concentrates in sustainability-certified formulations under REACH mandates.
United States
Telehealth prescribing platforms and subscription-based skincare services drive patient access outside traditional dermatology gatekeeping. FDA pregnancy category X labeling restricts prescribing to women of childbearing potential, compressing eligible populations. Formulation R&D clusters concentrate in New Jersey and North Carolina, where contract manufacturers serve both pharmaceutical and cosmetic channels.
Germany
Compounding pharmacies and boutique skincare manufacturers adopt microencapsulated delivery systems for customized patient formulations. EMA's MDR and CSRD disclosure requirements mandate supply chain transparency for cosmetic-grade retinoid ingredients. Industrial activity clusters in Baden-Württemberg, where mid-sized formulation houses face steep compliance costs accelerating consolidation toward integrated producers.
China
Domestic API producers scale naphthoic acid derivative synthesis capacity, exposing formulation houses to input volatility from Yangtze River Delta manufacturing clusters. NMPA bioequivalence standards align with international frameworks, enabling export-oriented production. Synthesis operations concentrate in Shanghai and Jiangsu province, where retinoid manufacturing scales under government industrial policy support.
Brazil
ANVISA's streamlined OTC classification for low-concentration retinoids enables pharmacy-direct distribution without prescription barriers. Post-inflammatory hyperpigmentation concerns drive pharmacy-direct purchasing for skin tone improvement formulations. Dermocosmetic channel expansion centers on São Paulo, where retail pharmacy networks bypass traditional clinic gatekeeping for cosmetic-grade products.
India
The PLI scheme for active pharmaceutical ingredients subsidizes domestic retinoid synthesis, positioning clusters for export-oriented scale. CDSCO bioequivalence standards aligned with WHO prequalification criteria enable generic adapalene approvals for emerging market entry. Manufacturing concentrates in Hyderabad and Ahmedabad, where API producers leverage cost-optimized production for broad pharmacy distribution.
Adapalene Products Market Competitive Landscape
Capability concentration sits with integrated dermatology platforms possessing captive API supply and regulatory expertise; scale advantage sits with generic pharmaceutical houses optimizing cost structures across broad distribution networks. The market structures around three tiers: multinational dermatology specialists with prescription-cosmetic hybrid portfolios, generic manufacturers competing on pharmacy formulary placement, and emerging market producers leveraging localized regulatory filing speed. Dominant competitive moves include backward integration into naphthoic acid derivative synthesis and strategic partnerships with telehealth platforms for direct-to-consumer channel access.
Among Switzerland-based dermatology specialists, Galderma occupies a position exemplifying integrated platform strategy across prescription and cosmetic channels. Israeli-American generic heavyweight Teva Pharmaceutical Industries represents the scale-driven archetype through cost-optimized production and broad pharmacy distribution networks. Indian pharmaceutical conglomerate Sun Pharmaceutical Industries anchors the emerging market specialist tier, leveraging localized manufacturing and regulatory filing expertise for price-sensitive geographies.
| Leading Market Players |
|---|
| Galderma |
| Teva Pharmaceutical Industries |
| Bausch Health |
| Johnson & Johnson |
| Sandoz |
| Sun Pharmaceutical Industries |
| Mylan |
| Zydus Cadila |
| Almirall |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Yangtze River Delta naphthoic acid derivative producers determines both pricing tier spreads and supply chain shape across adapalene markets. API concentration in Shanghai and Jiangsu province manufacturing clusters exposes formulation houses to input volatility that compresses margins in generic segments while sustaining premium pricing for integrated dermatology platforms with captive synthesis capabilities.
Pricing Analysis
Prescription gels in the United States command substantial premiums over Brazilian pharmacy-direct OTC creams. Three-tier pricing structure across premium, standard, and economy levels separates Galderma-branded dermatology formulations from Teva generic gels and Indian export-oriented economy creams. Pricing pressure stems from benzoyl peroxide combination substitution in managed care formularies. Generic manufacturers exhibit highest price sensitivity; integrated platforms with cosmetic-prescription hybrid portfolios demonstrate lowest.
Supply Chain Analysis
Naphthalene feedstock and carboxylic acid functionalization reagents anchor upstream dependencies for adapalene synthesis. Manufacturing concentrates in China, India, and Switzerland for API production; formulation finishing clusters in the United States, Germany, and Brazil. Supply chain risk centers on regulatory chokepoint vulnerability from FDA pregnancy labeling reviews affecting batch release timelines. Distribution runs through dermatology clinic networks, direct-to-consumer subscription platforms, and retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth prescribing expansion and microencapsulation technology convergence constitute high-growth disruption vectors. FDA retinoid safety labeling review accelerates formulation timeline compression and channel access recalibration.
For Market Incumbents: Insulate prescription volumes through backward integration into naphthoic acid derivative synthesis and exclusive telehealth platform partnerships. Galderma-type integrated dermatology platforms should deepen cosmetic-prescription hybrid channel control to defend against benzoyl peroxide combination substitution. Certification investment in EMA green chemistry credentials creates REACH compliance moats. For New Entrants and Emerging Players: Pursue Brazilian dermocosmetic channel penetration under ANVISA's streamlined OTC classification for low-concentration retinoids. Indian PLI scheme alignment enables cost-optimized API production for export-oriented scale. Direct-to-consumer subscription platforms offer the most penetrable go-to-market angle for bypassing traditional dermatology gatekeeping. For Investors and Strategic Acquirers: FDA retinoid safety labeling review reshapes the acquisition landscape toward integrated producers with captive API capabilities and regulatory expertise. Long-term viability favors dermatology specialists with prescription-cosmetic hybrid portfolios over pure generic manufacturers facing formulary compression. Monitor CDSCO bioequivalence standard alignment with WHO prequalification criteria as inflection indicator for emerging market generic entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive naphthoic acid derivative production insulates against Yangtze River Delta supply volatility. |
| Telehealth Platform Partnership | Direct-to-consumer channel access bypasses traditional dermatology clinic gatekeeping economics. |
| Green Chemistry Certification | EMA REACH compliance credentials create first-mover advantage in European Union markets. |
| Microencapsulation R&D Investment | Liposomal delivery systems open pediatric and sensitive-skin segments previously excluded. |
| Brazilian Dermocosmetic Registration | ANVISA streamlined OTC classification enables pharmacy-direct distribution without prescription barriers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dermatology clinic directors, formulary managers at managed care organizations, regulatory affairs leads at API manufacturers, and telehealth platform executives; and secondary validation through FDA retinoid labeling dockets, EMA REACH substance registrations, CDSCO bioequivalence guidelines, ANVISA OTC classification rulings, and customs trade data for naphthoic acid derivative flows. Bottom-up patient access modeling and top-down pharmaceutical market sizing triangulated volume estimates.
Forecast inputs encompassed formulation type segmentation across gels, creams, solutions, and lotions; clinical indication splits between acne vulgaris, photoaging, and skin tone improvement; and channel configuration across home care subscription platforms, dermatology clinics, hospitals, and retail pharmacies. CAGRs derived from patient population epidemiology, telehealth penetration trajectories, and regulatory approval timeline assumptions across the analysis window. Specific inputs included FDA pregnancy labeling review status and EMA CSRD supply chain disclosure implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical reimbursement policy, dermatology visit economics, or consumer discretionary skincare spending would shift the trajectory. Forecasts reflect documented assumptions regarding telehealth regulatory permanence and retinoid cosmetic-pharmaceutical classification stability. Quarterly review of FDA labeling review progress, EMA green chemistry mandate enforcement, and CDSCO-WHO alignment milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Bacteriostatic Water for Injection Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Unit Dose Manufacturing Market
Pharmaceuticals
Depression and Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market