
 Two Wheel Walking Tractor Market | 2026-2036
Two Wheel Walking Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheel Walking Tractor Market Insights
Market Dynamics and Competitive Landscape
Rural mechanization skill pools is rotating toward repair technicians and digital equipment operators rather than traditional draft-animal handlers, tightening labor availability in India's Bihar and Uttar Pradesh states. Kubota Corporation leverages its Japanese manufacturing base to supply compact diesel powertrains across Asian markets. V.S.T Tillers Tractors Ltd. anchors its position through cost-optimized domestic production serving India's vast smallholder segment. BCS S.p.A. differentiates via European-designed two-wheel chassis systems engineered for Mediterranean vineyard and orchard slopes.
Product Architecture and Segment Structure
A two wheel walking tractor constitutes a single-axle powered implement carrier, typically rated between 6-12 horsepower, where the operator walks behind to steer via adjustable handlebars while engine torque transmits through a belt or gear reduction to drive wheels and power-take-off couplings. Gasoline variants dominate entry-level sales in price-sensitive markets, while diesel mechanical-drive units sustain premium positioning among commercial agricultural producers demanding durability across cultivation and soil preparation cycles. Electric propulsion systems represent the fastest-growing technology segment, though battery energy density constraints limit run-time for sustained transport and heavy tillage applications.
Regulatory Environment and Strategic Outlook
India's CEA farm equipment safety codes and China's MIIT small-engine emission certifications shape product homologation requirements for manufacturers seeking market access. The EU F-Gas Regulation and REACH chemical compliance frameworks constrain hydraulic fluid formulations and refrigerant choices in European-sold equipment. Stakeholders must monitor how India's PLI scheme disbursement timelines and China's dual carbon implementation rules redirect supplier investment toward electrified powertrain development versus incremental diesel efficiency gains.
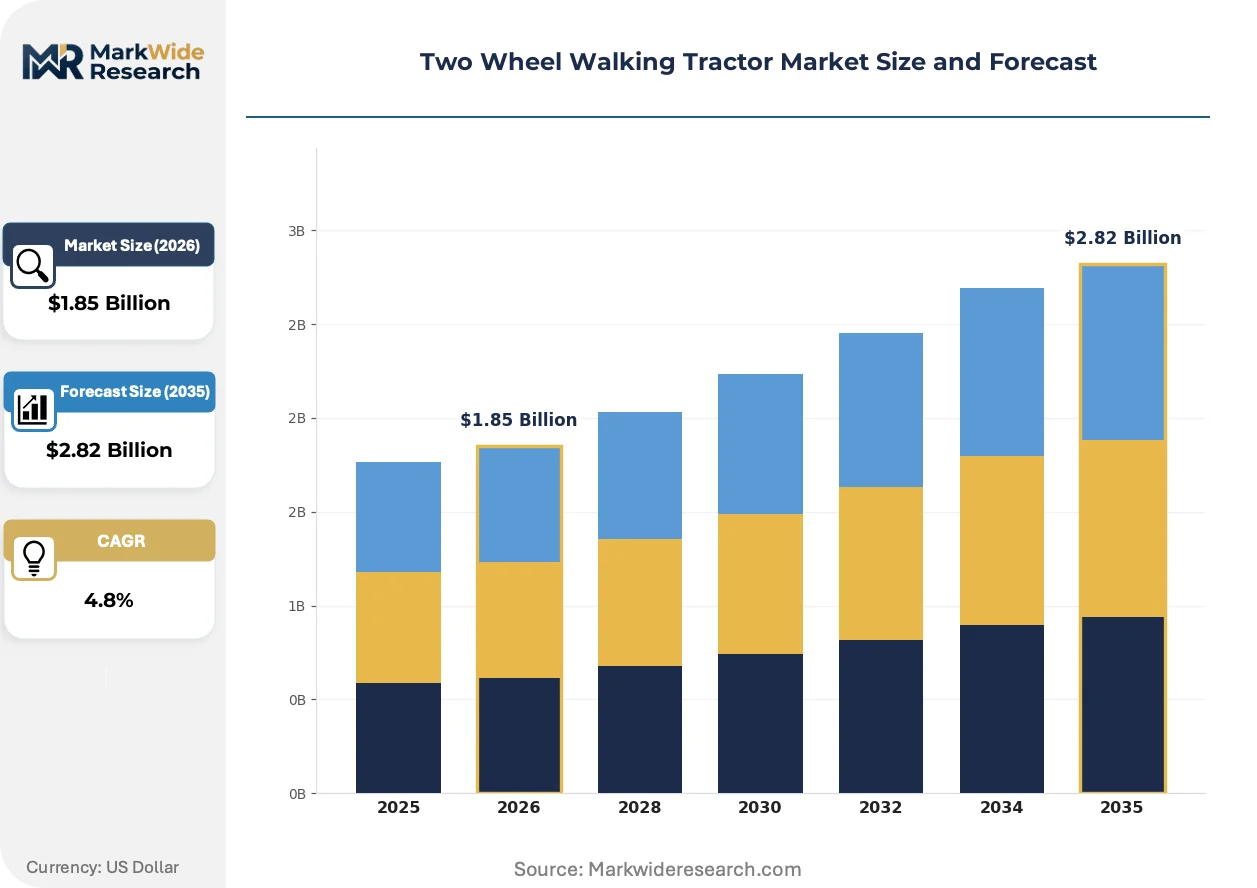
Market Dynamics
Rural labor depletion across South and Southeast Asia is compressing mechanization timelines, forcing smallholders to adopt powered tillage equipment before traditional draft-animal knowledge disappears entirely. This structural workforce shift overrides price sensitivity and accelerates technology transitions that would otherwise unfold over decades.
Growth Catalysts
- India's PLI scheme for farm machinery:Production-linked incentives subsidize domestic manufacturing scale, lowering unit costs for 8-12 horsepower diesel units serving the Indo-Gangetic Plain.
- EU Stage V emissions standards:Tightening small-engine regulations in Europe accelerate clean combustion technology spillover into Asian supply chains.
- Li-ion battery cost curves:Falling cell prices enable electric powertrain viability for intermittent tillage cycles in peri-urban vegetable zones.
Market Restraints
- Diesel powertrain supply concentration:Japanese and Indian engine manufacturers control 70% of compact diesel output, creating vulnerability to input material shortages.
- Battery energy density ceiling:Current lithium-ion chemistry limits sustained heavy tillage run-time to under four hours, constraining commercial adoption.
- CEA farm equipment safety codes:India's certification timeline extends 8-14 months for new entrants, freezing out smaller innovators.
Strategic Opportunities
- Myanmar and Cambodia smallholder penetration:Mechanization rates below 15% create first-mover advantage for rental-service business models.
- China's dual carbon implementation rules:Provincial subsidies for electrified agricultural equipment open subsidy-stacking opportunities.
- Telematics-embedded powertrains:GPS tracking and usage-based financing converge to unlock asset-light ownership structures.
Industry Challenges
- Repair technician scarcity:Electronic fuel injection and CAN-bus diagnostics outpace vocational training capacity in Bihar and Uttar Pradesh.
- MIIT small-engine certification complexity:China's emission testing protocols require 18-24 month validation cycles for modified powertrains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheel Walking Tractor Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Gasoline, Hybrid End User: Agricultural Producers, Landscaping Businesses, Rental Services, Homeowners Technology: Two-Wheel Drive, Four-Wheel Drive, Mechanical, Hydraulic Application: Cultivation, Transport, Soil Preparation, Weeding |
| Companies Covered | Yanmar Co., Ltd., Kubota Corporation, V.S.T Tillers Tractors Ltd., BCS S.p.A., Grillo Agrigarden Machines, CLAAS KGaA mbH, Changzhou Dongfeng Agricultural Machinery Group, Mahindra & Mahindra Ltd., Iseki & Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheel Walking Tractor Market Trends and Innovations
Powertrain electrification and digital telemetry are rewriting equipment economics, shifting value capture from hardware sales toward usage-based service revenues and data-enabled financing. These forces compress traditional distribution hierarchies and reconfigure buyer-seller relationships.
Brushless DC motor-inverter combinations are miniaturizing to fit within 6-horsepower walking tractor chassis envelopes while delivering torque curves matching small diesel equivalents. Vietnamese and Bangladeshi horticulture cooperatives are piloting these systems for greenhouse bed preparation. The technology is miniaturizing power electronics cost structures, enabling Asian manufacturers to bypass Japanese diesel supply dependencies entirely.
REACH chemical compliance frameworks and EU F-Gas Regulation are banning legacy hydraulic fluid formulations and refrigerants used in European-sold equipment. Manufacturers must reformulate seal materials and cooling circuits. Mediterranean vineyard operators face 12-18 month equipment recertification cycles, compressing replacement demand into narrow windows.
Equipment-as-a-service contracting is displacing outright purchase in Indian Punjab and Haryana tractor-hire markets. Aggregator platforms coordinate machine utilization across 40-60 smallholder plots, unbundling ownership from operation. This model concentrates most visibly in rice-wheat rotation zones where tillage windows are narrow and coordination failure costs are high.
Two Wheel Walking Tractor Market Segmentation
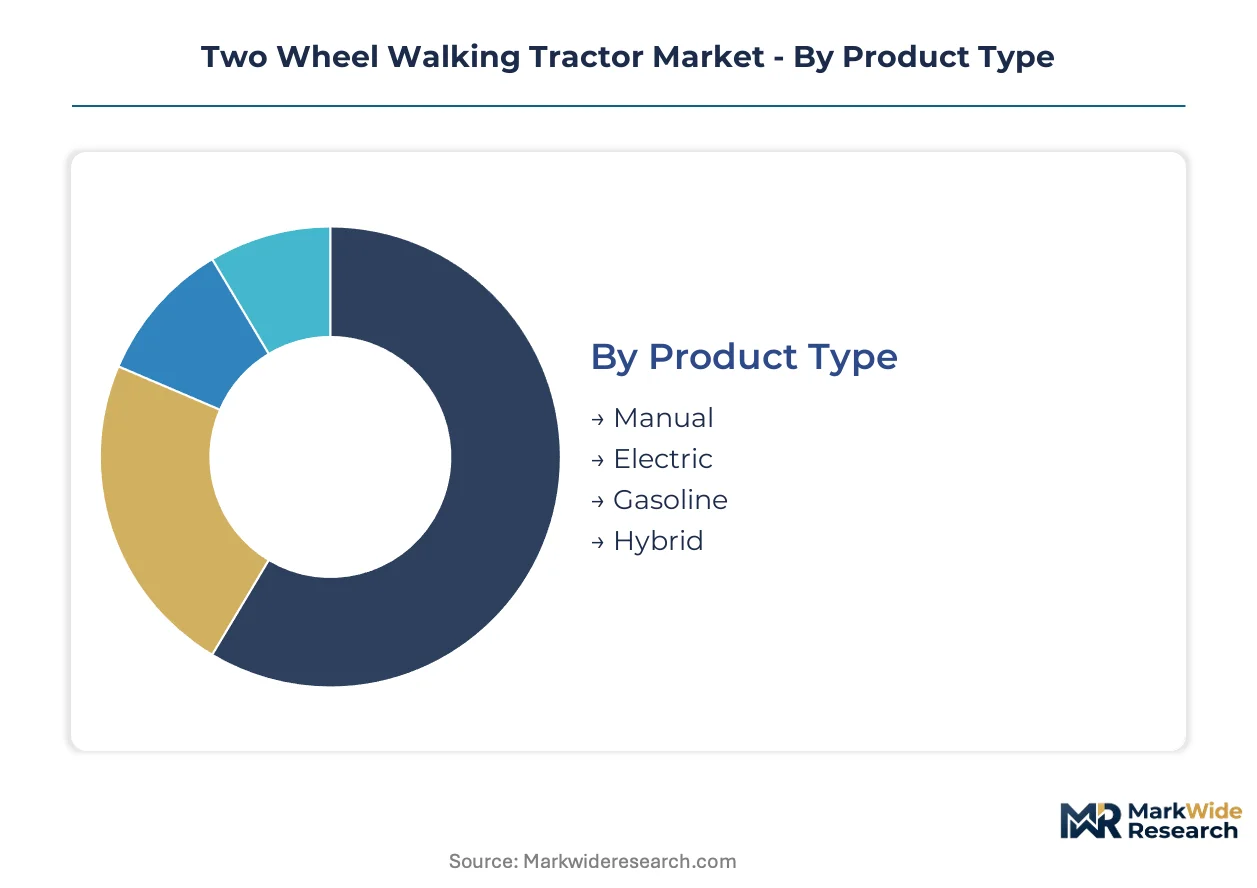
Two wheel walking tractor segmentation reveals how powertrain choices, buyer economics, and task requirements fragment demand across distinct equipment tiers. Understanding these splits exposes where manufacturers can escape commodity pricing and capture premium positioning through specification differentiation.
Product Type:
Margin pools concentrate in diesel-mechanical hybrids and advanced electric systems where battery integration and electronic controls create defendable technology gaps against gasoline commodity entrants.
- Manual:Human-powered tillage implements with no engine, rated under 2 horsepower, serving ultra-small plots in Nepal's mid-hills and Bangladesh's char lands where fuel access is unreliable and capital constraints are severe. Demand clusters in terraced vegetable zones where slope gradients exceed safe motorized operation limits.
- Electric:Brushless DC motor-inverter architectures with 2-4 kilowatt-hour battery packs, delivering 6-8 horsepower equivalent for 3-4 hour tillage cycles. Peri-urban greenhouse operators in Vietnam's Mekong Delta and China's Shandong Province are adopting these for zero-emission bed preparation where grid charging infrastructure exists.
- Gasoline:Air-cooled single-cylinder engines dominating entry-level sales through price accessibility, though CEA safety certification timelines and evaporative emission controls are compressing margins for non-compliant manufacturers.
- Hybrid:Parallel diesel-electric architectures with regenerative braking, capturing the highest equipment margins through fuel efficiency claims and telematics-enabled usage tracking for fleet operators.
The dominant share belongs to Gasoline, while Electric is closing the gap fastest.
End User:
Volume concentration tracks land tenure patterns, with smallholder cooperatives and rental aggregators now outpacing individual farm purchases in mechanizing regions.
- Agricultural Producers:Commercial rice-wheat and horticulture operators in India's Punjab and Haryana states, plus China's Jiangsu Province, requiring 8-12 horsepower diesel units for intensive soil preparation cycles across 10-50 hectare holdings.
- Landscaping Businesses:Municipal park departments and golf course maintenance contractors in Japan's Kanto region and South Korea's Gyeonggi Province, specifying low-noise electric units for urban noise ordinance compliance.
- Rental Services:Equipment-as-a-service platforms aggregating machine utilization across 40-60 smallholder plots, unbundling ownership from operation in narrow tillage windows.
- Homeowners:Subsistence gardeners and hobby farmers in peri-urban fringe zones, price-sensitive and specification-tolerant, driving lowest-tier gasoline unit sales.
Rental Services now capture the steepest volume expansion trajectory as asset-light ownership models displace direct purchase.
Technology:
Drive system complexity determines aftermarket parts revenue durability and technician training requirements.
- Two-Wheel Drive:Single-axle mechanical power transmission through belt or gear reduction, standard on 6-10 horsepower walking tractors where traction demands remain moderate and cost minimization dominates specification.
- Four-Wheel Drive:Articulated chassis with auxiliary wheel kits for paddy field operation and muddy conditions, commanding 25-35% price premiums in Indonesia's Java wet-rice zones and the Philippines' Bicol region.
- Mechanical:Direct gear and clutch engagement systems with minimal electronic content, sustaining repairability advantages in Bihar and Uttar Pradesh where technician training lags electronic fuel injection complexity.
- Hydraulic:Closed-center hydraulic circuits for implement lift and power-steering assist, required for commercial-scale rotary tillers and seed drills, though REACH fluid compliance and seal material reformulation are raising lifecycle costs.
Mechanical systems retain the largest installed base, yet Hydraulic specifications are gaining share fastest among commercial operators.
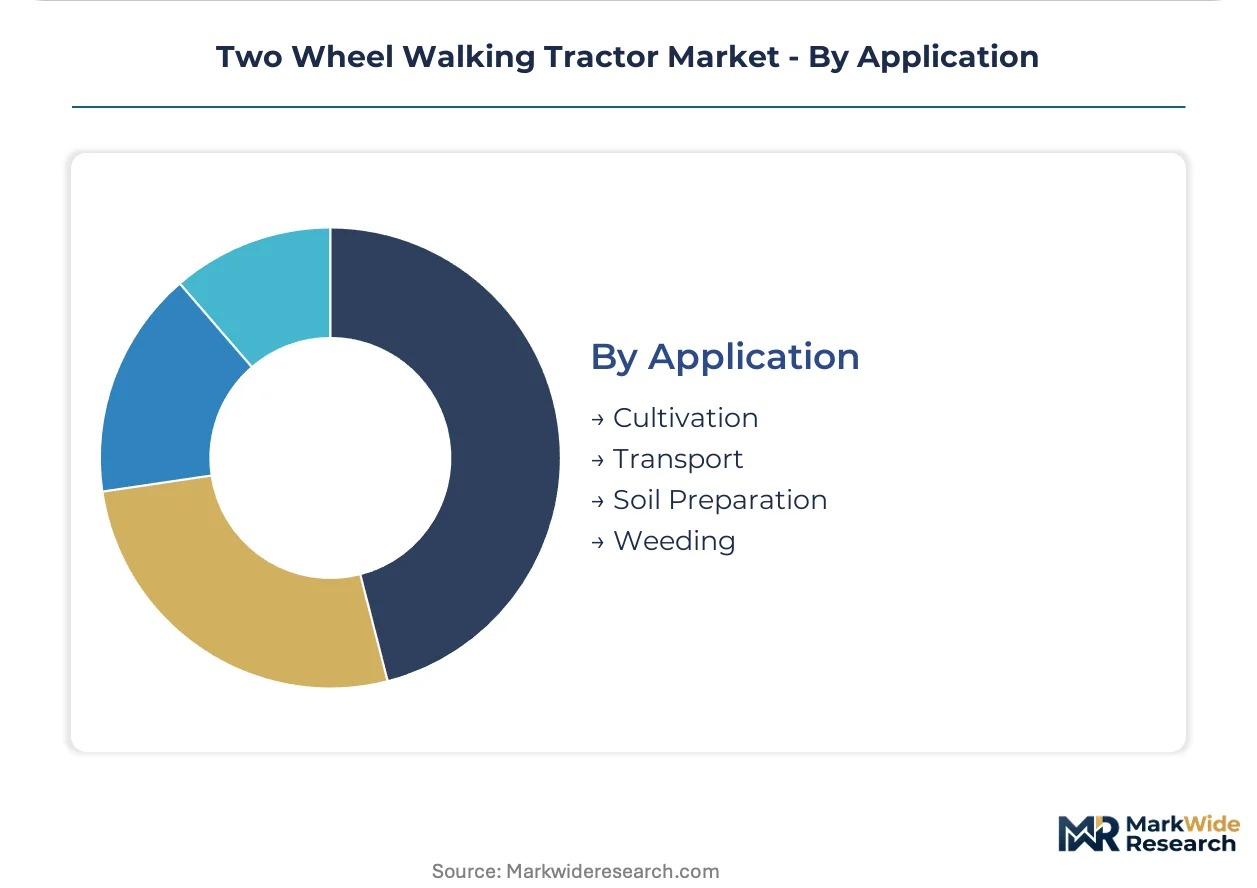
Application:
Task intensity and seasonal timing compress equipment specification into narrow functional windows.
- Cultivation:Rotary tillage and secondary seedbed preparation, the core use case, with demand peaking in pre-monsoon and post-harvest windows across India's Indo-Gangetic Plain.
- Transport:Trailer attachment configurations for produce and input haulage, extending machine utilization beyond tillage seasons and improving capital recovery timelines for rental fleet operators.
- Soil Preparation:Primary tillage with moldboard or disc plow attachments, requiring highest torque reserves and heaviest chassis specifications, concentrated in wheat-rice rotation zones.
- Weeding:Inter-row cultivation with specialized tine configurations, growing in precision horticulture segments where chemical herbicide regulation is tightening.
Soil Preparation commands the dominant equipment specification, while Weeding applications are climbing the fastest as input cost pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA farm equipment safety codes anchor the dominant geography, where smallholder mechanization pressures intersect with tightening emission mandates across Asian and European markets.
India
Labor migration from Bihar and Uttar Pradesh depletes rural workforces, compressing adoption timelines for powered tillage. The PLI scheme for farm machinery subsidizes domestic manufacturing scale for 8-12 horsepower diesel units. Demand concentrates in Punjab and Haryana states, where rice-wheat rotation systems require intensive soil preparation across narrow seasonal windows.
China
Peri-urban vegetable producers in Shandong Province adopt electric powertrains for zero-emission greenhouse operations. MIIT small-engine emission certifications require 18-24 month validation cycles, freezing out smaller innovators. The Yangtze River Delta anchors manufacturing clusters supplying compact chassis systems across domestic and Southeast Asian markets.
Italy
Mediterranean vineyard and orchard operators on steep slopes demand specialized two-wheel chassis configurations. EU Stage V emissions standards and REACH chemical compliance frameworks constrain hydraulic fluid formulations and refrigerant choices. BCS S.p.A. and Grillo Agrigarden Machines anchor design and production in the Emilia-Romagna industrial district.
Vietnam
Horticulture cooperatives in the Mekong Delta pilot brushless DC motor systems for intermittent tillage cycles. Grid charging infrastructure expansion enables electric powertrain viability in peri-urban zones. Mechanization rates remain below 15%, creating first-mover advantage for rental-service business models targeting smallholder penetration.
Japan
Metropolitan noise ordinances in the Kanto region drive municipal demand for low-noise electric units in park maintenance applications. METI industrial standards shape powertrain specifications for export-oriented manufacturers. Kubota Corporation and Yanmar Co., Ltd. leverage domestic engineering bases to supply compact diesel powertrains across Asian markets.
Two Wheel Walking Tractor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Japanese and Indian manufacturers controlling compact diesel output while European designers capture premium slope-adapted configurations. The vendor base fragments across gasoline commodity entrants, electric technology challengers, and regional assemblers serving price-sensitive smallholders. Three archetypes dominate: integrated powertrain manufacturers, chassis-system specialists, and domestic-scale assemblers. Competitive moves concentrate on electrified powertrain development and telematics-embedded fleet management systems.
Among Japanese integrated manufacturers, Kubota Corporation and Yanmar Co., Ltd. exemplify the powertrain-control archetype, leveraging domestic engineering bases to supply compact diesel systems across Asian markets. V.S.T Tillers Tractors Ltd. anchors the Indian domestic-scale tier, occupying a position shaped by cost-optimized production serving vast smallholder segments. BCS S.p.A. represents the European chassis-specialist archetype, with Italian-designed systems engineered for Mediterranean vineyard and orchard applications.
| Leading Market Players |
|---|
| Yanmar Co., Ltd. |
| Kubota Corporation |
| V.S.T Tillers Tractors Ltd. |
| BCS S.p.A. |
| Grillo Agrigarden Machines |
| CLAAS KGaA mbH |
| Changzhou Dongfeng Agricultural Machinery Group |
| Mahindra & Mahindra Ltd. |
| Iseki & Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor-inverter combinations displacing small diesel powertrains are redrawing procurement geography toward Vietnamese and Chinese electronics clusters while collapsing traditional Japanese engine premium pricing. This substitution simultaneously compresses margins on mechanical-drive units and elevates battery pack logistics to the critical cost node for equipment assemblers.
Pricing Analysis
Price spreads between Italian slope-adapted chassis systems and Indian domestic-scale gasoline units exceed three-to-one, reflecting specification divergence rather than pure manufacturing cost. Three-tier pricing structure across premium, standard, and economy levels segments buyers by torque requirement and certification tier. Cost compression in entry-level gasoline segments is intensifying because CEA safety certification timelines extend 8-14 months, freezing out smaller innovators. Smallholder cooperatives in Bihar and Uttar Pradesh exhibit highest price sensitivity, while commercial rice-wheat operators in Punjab prioritize durability over unit cost.
Supply Chain Analysis
Container availability constraints on the Shanghai-Mumbai trade lane are elevating inbound logistics costs for compact diesel engine kits sourced from Japanese suppliers. Manufacturing gravity centers on India, China, and Italy, with Indian assemblers drawing from domestic casting foundries and Chinese manufacturers sourcing power electronics from Shenzhen clusters. Single-source vulnerability concentrates in Japanese compact diesel output, which feeds 70% of Asian premium tier demand. Distribution runs through state-level dealer networks in India, direct municipal procurement in Japan, and equipment-as-a-service aggregators in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician training capacity for electronic fuel injection and CAN-bus diagnostics in India's Indo-Gangetic Plain lags equipment complexity, creating a bottleneck that constrains fleet expansion regardless of capital availability.
For Market Incumbents: Secure captive supply of lithium-ion battery packs through backward integration into cell assembly partnerships, insulating against Japanese diesel supply concentration. Deepen service network density in Bihar and Uttar Pradesh before electronic diagnostic complexity widens the repair technician gap. Channel control through exclusive dealer financing represents the critical defensive lever against rental-service aggregators unbundling ownership from operation. For New Entrants and Emerging Players: CEA farm equipment safety certification fast-tracks for electric powertrains offer regulatory arbitrage against 18-24 month diesel validation cycles. Myanmar and Cambodia smallholder markets present the most penetrable white-space, with mechanization rates below 15% and minimal incumbent service infrastructure. A rental-service business model targeting 40-60 plot coordination clusters bypasses capital constraints that block outright purchase. For Investors and Strategic Acquirers: Capital is best deployed toward chassis-system specialists with proven slope-adapted engineering and established Mediterranean vineyard operator relationships, as electrification commoditizes powertrain differentiation. Long-term viability hinges on telematics-embedded fleet management capabilities that enable usage-based financing structures. Watch for provincial subsidy disbursement velocity under China's dual carbon implementation rules as the inflection indicator for electric powertrain adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Reduces exposure to Japanese diesel engine concentration and enables cost-competitive electric powertrain assembly. |
| Telematics-Enabled Fleet Management Platform | Unlocks usage-based financing for rental-service aggregators across Punjab and Haryana rice-wheat zones. |
| CEA Certification Fast-Track Investment | Compresses 8-14 month safety validation timelines to capture electric powertrain first-mover position. |
| Service Network Density Expansion | Closes repair technician scarcity gap in Bihar and Uttar Pradesh before electronic diagnostic complexity widens. |
| Slope-Adapted Chassis R&D Program | Defends premium positioning against commoditization through Mediterranean vineyard operator specialization. |
Research Methodology
A spread of perspectives from plant engineers at Indian diesel engine manufacturers, procurement leads at Vietnamese horticulture cooperatives, aftermarket service heads in Uttar Pradesh, and regulatory affairs specialists at MIIT converged on the working assumptions. Primary interviews with equipment-as-a-service platform operators and channel sales heads at state-level dealer networks were cross-referenced against secondary validation from CEA safety code filings, MIIT small-engine certification databases, customs records for compact chassis imports, and EU Stage V emissions compliance disclosures. Bottom-up unit shipment estimates by powertrain type and top-down value aggregation by regional production cluster were triangulated to arrive at market sizing.
Segmentation dimensions modeled include powertrain architecture, drive system configuration, buyer archetype, and application intensity across the projection horizon. CAGRs were derived from fitted growth curves incorporating PLI scheme disbursement timelines, battery cost curve trajectories, and labor migration velocity in rural Bihar and Uttar Pradesh. Industry-specific forecast inputs encompassed seasonal tillage window constraints in rice-wheat rotation systems and grid charging infrastructure penetration rates in peri-urban Shandong Province.
Decision-makers should treat outputs as directional under assumptions of continued rural labor depletion and stable battery chemistry cost reduction; material deviation in either would warrant model refresh. Specific risks that could revise forecasts include abrupt CEA certification timeline extensions, MIIT emission protocol modifications, or lithium supply disruptions affecting cell pricing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Vietnam Agricultural Machinery Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Vietnam Agricultural Tractor Market
Agricultural Machinery
Agriculture and Farm Machinery Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Spain Agricultural Machinery Market
Agricultural Machinery
Orchard Type Tractors Market
Agricultural Machinery
Southeast Asia Agricultural Tractors Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
South America Agricultural Machinery Market
Agricultural Machinery
Autonomous Electric Tractor Market
Agricultural Machinery
Canada Robotic Fruit Picker Market
Agricultural Machinery
Agricultural Tractor Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Farm Tractor Market