
 E-Commerce Payments Market | 2026-2036
E-Commerce Payments Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Payments Market Analysis
Market Context
Southeast Asian payment processor networks are pivoting toward unified QR-code infrastructure across Indonesia, Singapore, and Vietnam. Stripe leverages API-first architecture to sustain developer loyalty among mid-market platforms. Adyen dominates omnichannel routing for enterprise merchants seeking single-vendor consolidation across online and in-store environments.
Technical Definition and Structural Segments
E-commerce payments encompass digital fund transfers between buyers and sellers through encrypted transaction rails, typically processing authorization, settlement, and reconciliation within sub-second latencies via tokenized credential exchange. The primary commercial purpose is reducing friction in remote commerce while mitigating fraud exposure through multi-factor authentication protocols. Digital wallet penetration is outpacing card-based flows in emerging corridors, while subscription transaction types are capturing recurring revenue streams that improve merchant lifetime value metrics. Installment mechanisms are expanding fastest among retail customers, though API integration remains the margin-dense layer where platform control concentrates.
Regulatory Frame and Outlook
India's RBI mandates tokenization of card data, while the EU's PSD2 strong-customer-authentication requirements reshape checkout flows across European corridors. Singapore's MAS licensing framework governs cross-border remittance aggregators operating within ASEAN payment corridors. Stakeholders must monitor how open-banking mandates in multiple jurisdictions alter data portability and interchange economics.
Market Dynamics
Real-time payment rails and tokenized credential architectures are compressing settlement windows from days to seconds, forcing processors to rebuild infrastructure around sub-second latency requirements rather than batch-based legacy systems.
Growth Catalysts
- India's PLI Scheme for Fintech Infrastructure:Production-linked incentives for domestic payment hardware manufacturing are accelerating local server deployment and reducing foreign dependency for core switching infrastructure.
- Unified QR-Code Standards:Cross-border interoperability protocols across Indonesia, Singapore, and Vietnam are eliminating friction for tourists and regional merchants operating across ASEAN corridors.
- Subscription Billing Automation:Recurring revenue platforms are embedding payment orchestration directly into SaaS workflows, capturing merchant lifetime value through integrated financial services rather than standalone processing.
Market Restraints
- Interchange Rate Compression:Regulatory caps on merchant discount rates in Brazil and India are squeezing processor margins while transaction volumes shift toward low-yield debit rails.
- Cloud Infrastructure Concentration:Three hyperscalers dominate payment-grade server deployment in Southeast Asia, creating single-point-of-failure risk for regional clearing systems.
- Tokenization Compliance Burden:India's RBI mandate for card-on-file tokenization forced merchants to rebuild checkout flows, delaying conversion optimization projects by 12-18 months.
Strategic Opportunities
- Philippines Unbanked Corridors:Mobile wallet penetration remains below 40% in Visayas and Mindanao, creating whitespace for agent-network-based onboarding models.
- Embedded Finance Convergence:Payment APIs are merging with lending and insurance orchestration, enabling platforms to offer working capital at checkout without redirecting to external banking interfaces.
- Open Banking Mandates:PSD2-style frameworks spreading across ASEAN are forcing data portability, allowing new entrants to build on incumbent transaction histories without legacy infrastructure.
Industry Challenges
- Legacy Core Modernization:Regional banks in Indonesia and Vietnam maintain COBOL-based switching systems that resist API integration, forcing processors to maintain expensive middleware layers.
- Cross-Border FX Volatility:Real-time settlement across ASEAN currencies exposes merchants to intraday exchange rate swings that erode margin on thin-ticket transactions.
Report Scope
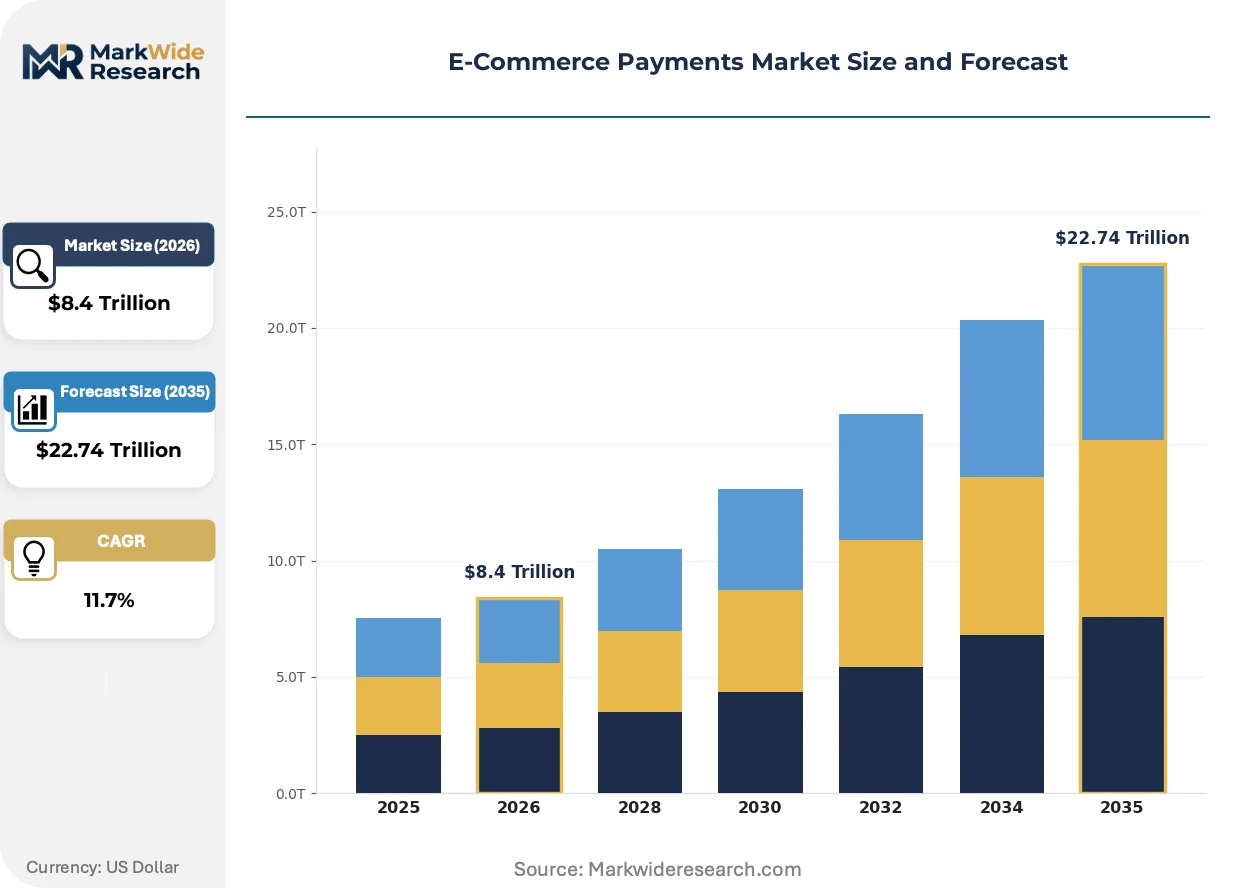
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Payments Market |
| Market Size in 2026 | $8.4 Trillion |
| Market Size in 2035 | $22.74 Trillion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer Transaction Type: One-Time Purchase, Subscription, Installment, Pre-Ordered End User: Retail Customers, Businesses, Organizations, Marketplaces Integration Type: API Integration, E-commerce Platform, Payment Gateway, Custom Solutions |
| Companies Covered | Square, Worldpay, Stripe, Airwallex, Razorpay, PayPal, Checkout.com, Rapyd, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Payments Market Emerging Trajectories
Distributed ledger architectures and programmable money standards are rewiring how value moves across e-commerce networks, collapsing the distinction between payment messaging and settlement finality.
Blockchain-based payment channels are decentralizing correspondent banking relationships that historically dominated cross-border remittance corridors. Southeast Asian fintech platforms are deploying these rails for intra-ASEAN salary disbursements and supplier payments, bypassing SWIFT messaging delays and reducing correspondent fees by eliminating intermediary bank hops. The structural consequence is compressing the competitive moat of established clearing networks.
The EU's Digital Operational Resilience Act is mandating stress-testing of critical payment infrastructure against cyberattack scenarios. Payment service providers must now demonstrate 48-hour recovery capabilities for core transaction processing, forcing architectural investment in geographically distributed redundancy. European merchants are responding by consolidating vendor relationships around providers with pre-certified operational resilience frameworks.
Buy-now-pay-later options are fragmenting checkout preferences across demographic cohorts, with younger consumers in Vietnam and Thailand expecting installment embedding at the point of sale. Traditional card acquirers are losing direct merchant relationships as BNPL platforms capture the primary customer interface, relegating banks to back-end funding roles. This pattern is most visible in fashion and electronics verticals where average ticket sizes align with four-installment structures.
E-Commerce Payments Market Segmentation
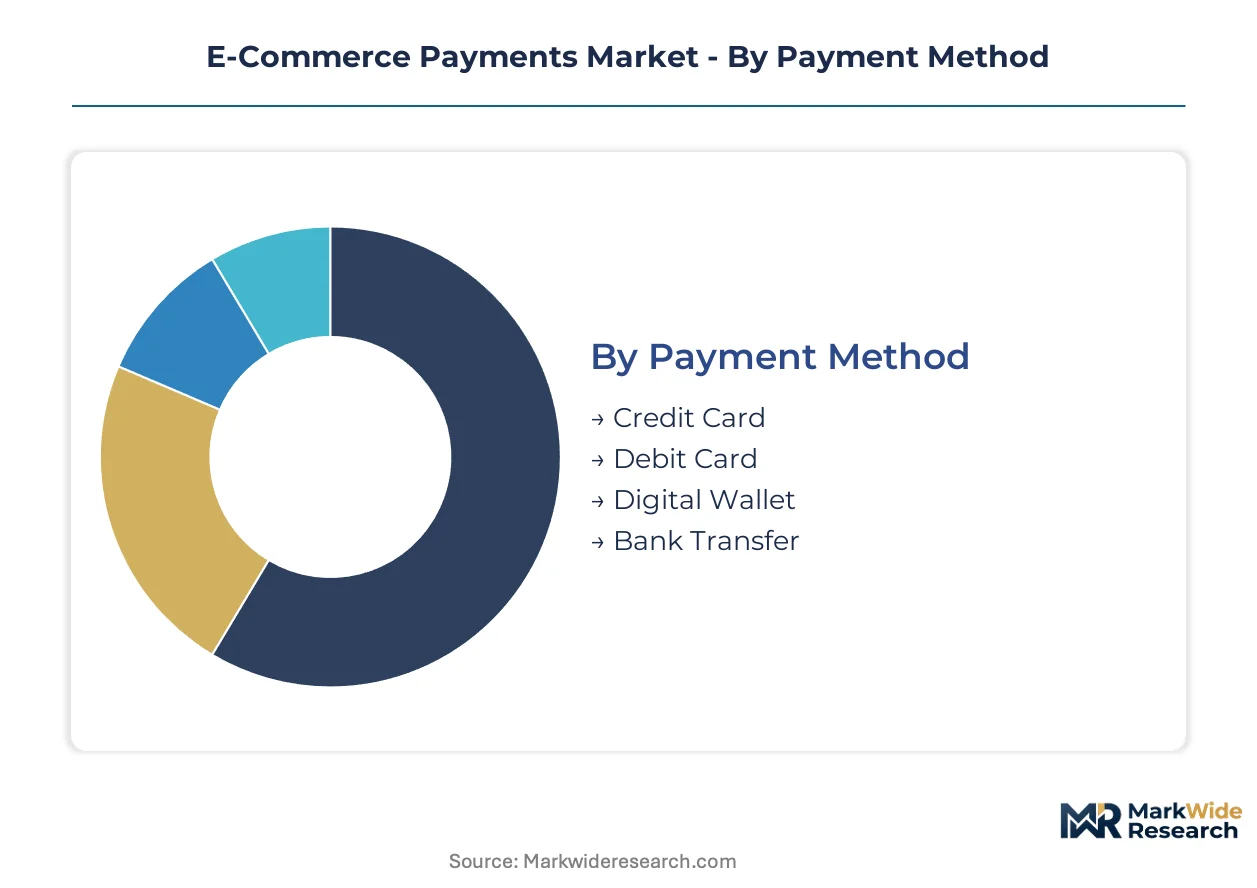
E-commerce payment infrastructure fragments across four structural dimensions that determine merchant acquisition costs, technical integration complexity, and regulatory exposure. Each segmentation axis reveals distinct margin profiles and competitive moats that shape vendor positioning strategies across transaction corridors.
Payment Method:
Upgrade cycles in payment acceptance infrastructure are compressing from five-year hardware refresh timelines to eighteen-month software update velocities as tokenization mandates proliferate.
- Credit Card:Networks process authorization through tokenized credential exchange with interchange economics regulated by central banks in Brazil and India. Demand concentrates among enterprise merchants in Singapore seeking cross-border acceptance reach, though margin compression from rate caps in Delhi and São Paulo corridors forces revenue diversification into value-added services.
- Digital Wallet:Mobile-first architectures dominate Southeast Asian urban corridors where UPI in India and similar real-time rails displace card-present habits. Wallet penetration accelerates fastest in Indonesian and Vietnamese retail environments where smartphone ownership outpaces banking infrastructure depth.
- Debit Card:PIN-authenticated networks carry lower fraud liability but thinner interchange yields, concentrating volume in European PSD2-compliant corridors with strong-customer-authentication mandates.
- Bank Transfer:Account-to-account rails bypass card network fees entirely, gaining traction among B2B marketplaces and subscription platforms seeking to eliminate chargeback exposure.
Volume placements concentrate in credit card acceptance; the faster expansion belongs to digital wallet infrastructure.
Transaction Type:
Cost tier differentiation separates high-touch manual reconciliation workflows from fully automated recurring revenue engines that improve merchant lifetime value metrics.
- Subscription:Automated billing cycles embed payment orchestration directly into SaaS platforms, reducing churn through seamless credential updates and dunning management. Demand clusters among software vendors and media streaming services in North American and European corridors where recurring revenue models dominate venture-funded growth strategies.
- Installment:Buy-now-pay-later mechanisms fragment checkout preferences among younger demographics in Vietnam and Thailand, capturing primary customer interface and relegating traditional acquirers to back-end funding roles.
- One-Time Purchase:Single-transaction flows remain the default for marketplace environments and impulse-driven retail categories where checkout friction directly correlates with cart abandonment rates.
- Pre-Ordered:Deferred fulfillment payments require escrow-like credential holding that increases compliance burden but unlocks crowdfunding and limited-release commerce models.
Merchant preference clusters around subscription automation; installment mechanisms are climbing the fastest among retail verticals.
End User:
Customer type determines fraud exposure profiles and support infrastructure requirements, with B2B corridors demanding multi-entity approval workflows absent in consumer contexts.
- Retail Customers:Individual buyers drive volume concentration in mobile-first emerging markets where checkout optimization focuses on one-click repetition and biometric authentication.
- Businesses:Corporate procurement cards and virtual account structures require enhanced reporting and reconciliation tools that command premium processing fees.
- Organizations:Nonprofit and educational entities operate under distinct tax-exempt interchange programs with specialized compliance documentation.
- Marketplaces:Multi-party split payment architectures demand sophisticated escrow and seller disbursement capabilities that only API-first processors reliably support.
Transaction density peaks among retail customers; marketplace infrastructure is gaining share fastest as platform economics reshape merchant acquisition.
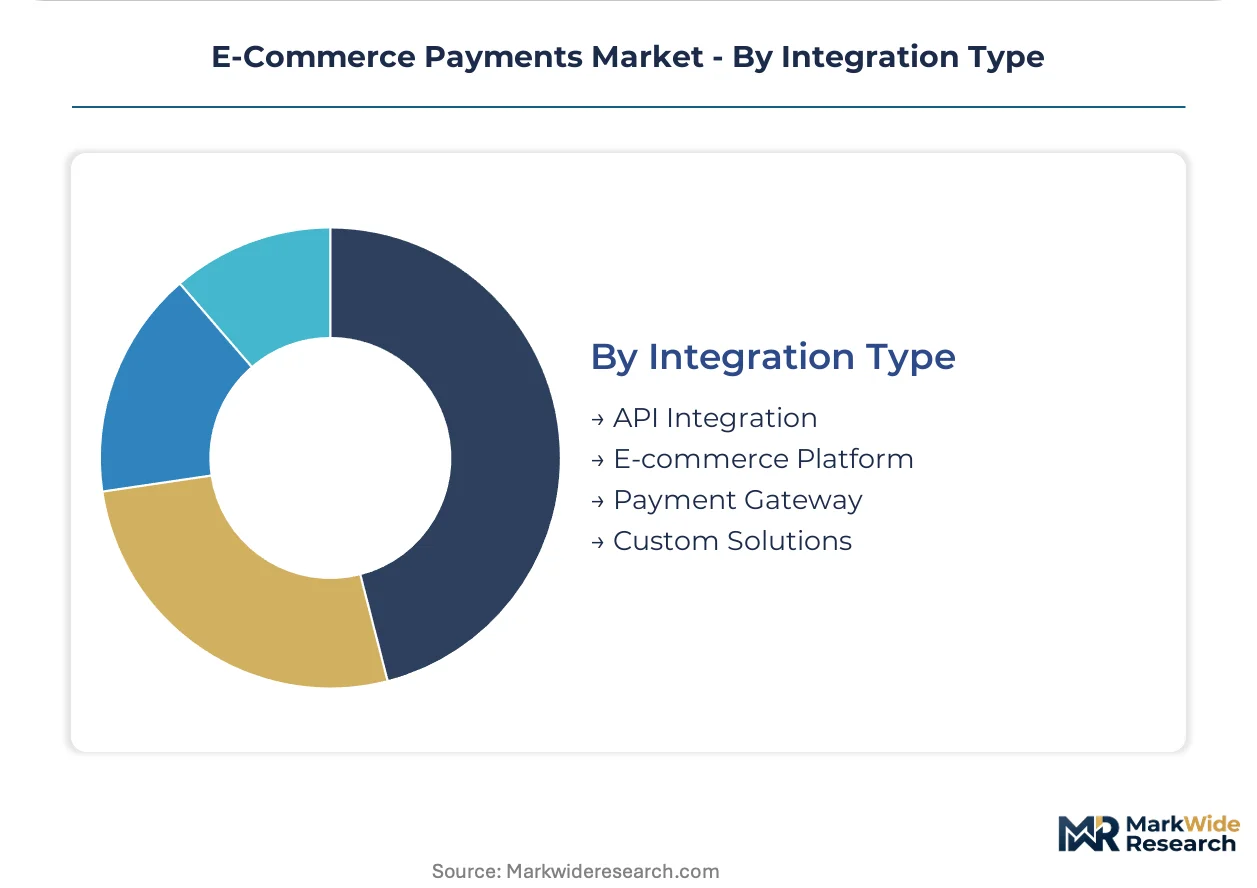
Integration Type:
Margin concentration follows technical abstraction depth, with raw API layers capturing value that commoditized platform plugins cannot access.
- API Integration:Direct developer relationships enable custom checkout flows and embedded finance convergence, sustaining loyalty among mid-market platforms seeking differentiation from template-based competitors.
- Payment Gateway:Aggregated merchant onboarding reduces technical barrier to entry but standardizes user experience and limits optimization flexibility.
- E-commerce Platform:Native payment modules in Shopify and WooCommerce environments capture small-merchant volume through convenience despite higher effective rates.
- Custom Solutions:Enterprise bespoke deployments address legacy core modernization challenges in Indonesian and Vietnamese banking infrastructure resistant to standard API patterns.
Deployment scale favors gateway convenience; API integration shows the steepest expansion trajectory as developer-centric platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Server-grade silicon from Taiwan's Hsinchu Science Park underpins payment processing infrastructure across major transaction corridors. Data center construction in Singapore and Mumbai anchors regional clearing capacity. Regulatory divergence between RBI mandates and EU PSD2 protocols shapes where processors deploy capital.
India
UPI transaction volumes exceeding 12 billion monthly payments drive domestic processor expansion. RBI's card-on-file tokenization mandate forces merchant checkout rebuilds, delaying optimization projects by 12-18 months. Bangalore's fintech cluster concentrates engineering talent for API-first payment orchestration platforms serving Southeast Asian markets.
Singapore
Cross-border ASEAN remittance flows position the city-state as a regional clearing hub. MAS licensing frameworks govern payment aggregators operating multi-currency corridors. The Marina Bay financial district hosts headquarters for processors targeting Indonesia and Vietnam's unbanked merchant segments.
United States
Subscription billing automation and embedded finance convergence attract venture deployment. The FedNow instant payment rail competes with card networks for B2B transaction share. Silicon Valley and New York fintech clusters drive developer-centric API platform innovation.
Germany
PSD2 strong-customer-authentication compliance reshapes checkout flows for pan-European merchants. Berlin's startup ecosystem produces account-to-account payment challengers targeting retail and B2B segments. Frankfurt's banking infrastructure supports euro-denominated settlement for cross-border e-commerce.
Brazil
PIX instant payment adoption displaces card-present habits among urban consumers. Central Bank caps on merchant discount rates compress processor margins while volumes shift to low-yield debit rails. São Paulo's fintech corridor hosts payment orchestrators integrating PIX with installment lending products.
E-Commerce Payments Market Vendor Landscape
Global majors compete with regional champions across developer loyalty and local regulatory compliance capabilities. Market structure shows tiered consolidation: omnichannel enterprise processors, API-first mid-market platforms, and specialized emerging-market aggregators. Three archetypes dominate: full-stack acquirers with banking licenses, pure-technology orchestration layers, and wallet-centric super-apps with captive user bases. Competitive moves concentrate on M&A for regulatory licenses and strategic partnerships for local payment method access.
Within the API-first orchestration tier, Stripe and Checkout.com exemplify developer-centric positioning that sustains platform loyalty through documentation quality and integration speed. Among emerging-market specialists, Razorpay occupies a position representing India-focused infrastructure depth, while Airwallex anchors the cross-border multi-currency segment for Asia-Pacific merchant expansion. Adyen exemplifies the full-stack acquirer archetype with direct banking relationships across multiple jurisdictions.
| Leading Market Players |
|---|
| Square |
| Worldpay |
| Stripe |
| Airwallex |
| Razorpay |
| PayPal |
| Checkout.com |
| Rapyd |
| Adyen |
| Others |
Supply Flow & Price Mechanics
Enterprise merchants with omnichannel footprints anchor pricing power in the E-Commerce Payments Market, commanding subscription-based SaaS tiers that bundle tokenization compliance and multi-currency settlement against per-transaction models serving smaller merchants. This buyer concentration rewards scale economies while squeezing mid-market processors between enterprise consolidation and API-first platform competition.
Pricing Analysis
Service bundling separates premium orchestration tiers from stripped-down gateway offerings. Three-tier pricing structure across premium, standard, and economy levels reflects transaction volume thresholds and API customization depth. Pricing pressure stems from India's RBI-mandated tokenization compliance costs and Brazil's interchange rate caps. Small merchants show highest price sensitivity, while enterprise buyers prioritize resilience certifications over rate minimization.
Supply Chain Analysis
India's PLI scheme for fintech infrastructure and similar domestic-content mandates in Indonesia are reshaping server deployment patterns away from hyperscaler concentration. Taiwan's Hsinchu Science Park, Singapore's data center clusters, and India's Bangalore-Mumbai corridor anchor payment-grade silicon and clearing capacity. Supply chains draw from specialized semiconductor foundries, undersea cable infrastructure, and localized switching hardware. Single-point-of-failure risk concentrates in three hyperscalers dominating Southeast Asian cloud deployment. Distribution runs through direct API relationships for enterprise accounts and platform-integrated channels for small merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The E-Commerce Payments Market sits in a technology-transition phase where real-time payment rails displace batch-based legacy systems. Tokenized credential architectures and sub-second latency requirements are rendering COBOL-based switching infrastructure obsolete.
For Market Incumbents: Extend API-first orchestration capabilities into embedded finance convergence before pure-technology challengers capture merchant relationships. Acquire regulatory licenses in ASEAN corridors where MAS frameworks govern cross-border aggregators. Vertical integration into local server deployment mitigates hyperscaler concentration risk.
For New Entrants and Emerging Players: API-first orchestration layers targeting Philippines unbanked corridors offer the most penetrable white space. Mobile wallet penetration below 40% in Visayas and Mindanao creates whitespace for agent-network onboarding. Partner with regional banks for PIX-UPI interoperability to bypass legacy core modernization barriers.
For Investors and Strategic Acquirers: The window for entry favors orchestration platforms with pre-certified operational resilience frameworks. Long-term viability hinges on regulatory license breadth across multiple jurisdictions. Monitor PSD2-style open banking mandate spread across ASEAN as inflection signal for data portability-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory License Acquisition | MAS and RBI frameworks require local certification for cross-border payment aggregation. |
| API-First Platform Integration | Stripe and Checkout.com demonstrate developer loyalty sustains mid-market platform retention. |
| Embedded Finance Convergence | Payment APIs merging with lending orchestration capture working capital at checkout. |
| Local Server Deployment | India's PLI scheme accelerates domestic hardware manufacturing reducing foreign dependency. |
| Operational Resilience Certification | EU Digital Operational Resilience Act mandates 48-hour recovery for core transaction processing. |
Methodological Framework
SEC filings, central bank payment system reports, and hyperscaler infrastructure disclosures formed the secondary backbone for this analysis. Primary interviews with payment processors, merchant platform engineers, regulatory compliance officers, and API integration specialists validated transaction volume assumptions. Bottom-up merchant acquisition cost modeling combined with top-down regional payment flow estimates enabled triangulation across the analysis window.
Bottom-up segmentation by payment method, transaction type, end user, and integration type anchored the analytical lens. Top-down macroeconomic indicators including smartphone penetration curves and real-time rail adoption rates informed corridor-level scaling. CAGRs derived from volume trajectory analysis against regulatory mandate timelines. Tokenization compliance burden and open banking mandate spread served as industry-specific forecast inputs throughout the projection horizon.
Several conditions sit outside the modeled scope, including cryptocurrency payment flows, central bank digital currency deployments, and sanctions-corridor payment restrictions. Forecasts reflect documented assumptions about regulatory implementation timelines and merchant technology refresh cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Utility Billing Software Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
APAC Mobile Payments Market
Payments
B2B Payments Platform Market
Payments
Mobile Payment Security Software Market
Payments
Sweden Mobile Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Israel Credit Cards Market
Payments
Singapore Remittance Market
Payments
Singapore Payments Market
Payments
Dual Interface Payment Card Market
Payments
Brazil POS Terminal Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Argentina Mobile Wallet Market
Payments
Mobile Money Market